
 Commercial Vehicle Seats Market | 2026-2036
Commercial Vehicle Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Seats Market Insights
The EU Green Deal is realigning material sourcing priorities across the commercial vehicle seating supply chain. Faurecia leverages its integrated foam-to-finished-seat manufacturing to meet recycled-content thresholds. GRAMMER anchors European production capacity with dedicated plants in Germany and Czechia. Adient competes through modular platform architectures that reduce SKU complexity for truck OEMs.
Commercial vehicle seats are engineered assemblies combining steel frames, polyurethane foam cushions, suspension mechanisms, and trim materials designed to withstand sustained vibration, weight loads exceeding 150 kg, and duty cycles of 16+ hours daily in trucks, buses, and vocational vehicles. Driver seats command premium positioning due to integrated air suspension and heating modules that fleet managers specify for retention-focused procurement. Fabric trim dominates volume production for price-sensitive segments, while leather and vinyl concentrate in executive and premium bus configurations where operators differentiate passenger experience.
EMA and REACH frameworks govern chemical emissions and material safety in seats sold across Europe, while NHTSA and FMVSS 302 flammability standards shape US market access requirements for foam and textile suppliers. The EU AI Act introduces emerging compliance dimensions for seats with embedded biometric monitoring and occupant detection sensors. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's evolving recyclability mandates reshape material specifications and supplier qualification timelines.
Market Dynamics
Fleet operator consolidation across long-haul trucking is compressing procurement cycles and forcing seat suppliers to absorb warranty risk through extended service agreements tied to driver retention metrics.
Growth Catalysts
- EU Green Deal recyclability mandates:Automotive suppliers are retooling foam production lines to incorporate post-consumer polyurethane content, creating qualified supplier status for OEM tender participation.
- Biometric sensor integration:Driver fatigue monitoring systems embedded in seat assemblies are commanding specification priority from logistics operators insuring against accident liability.
- German manufacturing clusters:Concentrated commercial vehicle assembly around Munich and Stuttgart anchors just-in-time seat delivery networks, reducing inventory carrying costs for tier-one suppliers.
Market Restraints
- Steel frame cost volatility:Cold-rolled steel price swings transmit directly to seat BOM costs, compressing margin buffers for suppliers locked into annual OEM pricing agreements.
- Polyurethane feedstock concentration:Isocyanate and polyol supply chains cluster around Rotterdam and Antwerp port infrastructure, creating single-point vulnerability for European seat foam production.
- REACH chemical registration timelines:Novel flame-retardant formulations face 18-24 month ECHA evaluation windows, delaying compliant product launches for export-bound seat configurations.
Strategic Opportunities
- Aftermarket refurbishment channels:Independent truck service networks in Poland and Hungary are developing seat reconditioning capabilities, opening margin-recapture paths beyond OEM captive supply.
- EU AI Act compliance services:Biometric seat suppliers can bundle algorithmic transparency documentation as a paid advisory layer, monetizing regulatory complexity for fleet compliance officers.
- Bus electrification retrofit demand:Municipal operators replacing diesel coaches with battery-electric units require lightweight seat assemblies to preserve range, favoring composite frame technologies.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for low-emission, high-durability foam systems concentrates among retiring specialists, constraining R&D throughput for sustainable material transitions.
- Homologation test facility bottlenecks:ECE R14 seat anchorage strength certification queues at KBA-approved laboratories extend lead times by 8-12 weeks for new product introductions.
- Legacy CAN bus integration:Heated and ventilated seat modules must interface with proprietary truck OEM electrical architectures, requiring redundant engineering for each platform qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Seats Market |
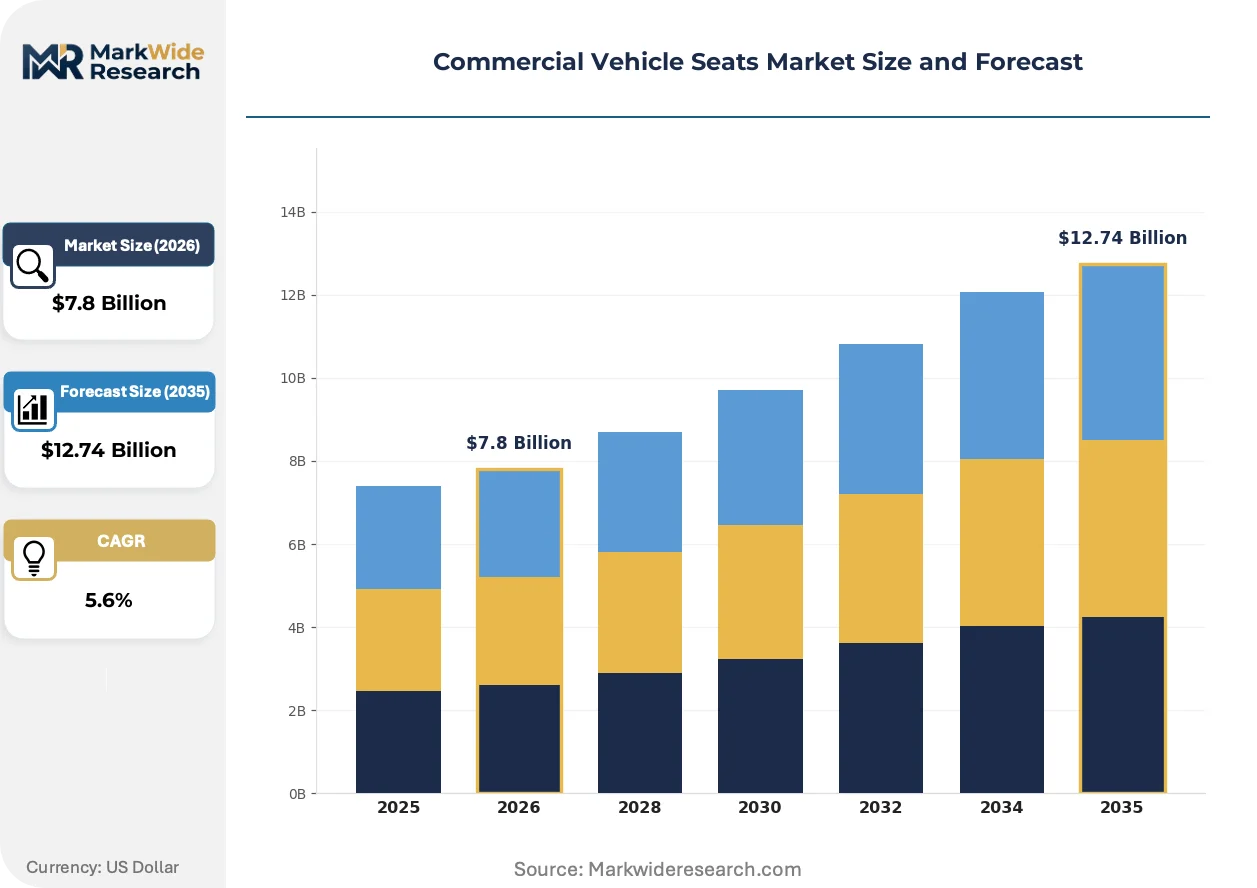
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Driver Seat, Passenger Seat, Bench Seat, Executive Seat Material: Fabric, Vinyl, Leather, Foam End User: Truck Manufacturers, Bus Operators, Fleet Managers, OEMs Installation: Built-in, Aftermarket, DIY, Custom |
| Companies Covered | Faurecia, TS Tech, GRAMMER, Toyota Boshoku Corporation, Johnson Controls International, Lear Corporation, RECARO Automotive Seating, Magna International, Adient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Seats Market Trends and Innovations
Active suspension systems and sensor-embedded seating architectures are compressing the traditional mechanical-electrical boundary in commercial vehicle interiors, forcing suppliers to acquire software competencies.
Air suspension seat mechanisms are modularizing across driver, passenger, and bunk configurations, enabling Grammer and competitors to reduce platform variants by 40% while maintaining load-specific damping calibration. Fleet procurement teams are specifying these systems for retention-focused driver packages. The technology is modularizing supplier-OEM relationships around configurable subassembly sourcing rather than finished seat tenders.
REACH Annex XVII restrictions on organophosphate flame retardants are accelerating migration to phosphorus-nitrogen synergist systems in polyurethane foam formulations. ECHA substance evaluation deadlines in 2025-2026 are compressing reformulation timelines for seat suppliers serving pan-European OEMs. Bus interior applications face the strictest scrutiny given passenger density and evacuation time requirements.
Driver wellness metrics are penetrating fleet procurement specifications, with logistics operators in Germany and the Netherlands tying seat purchase decisions to accelerometer-derived whole-body vibration data. Insurance underwriters are beginning to reference ISO 2631-1 compliance in premium calculations for long-haul operators. This behavioral shift favors suppliers offering integrated vibration monitoring rather than passive mechanical suspension.
Commercial Vehicle Seats Market Segmentation
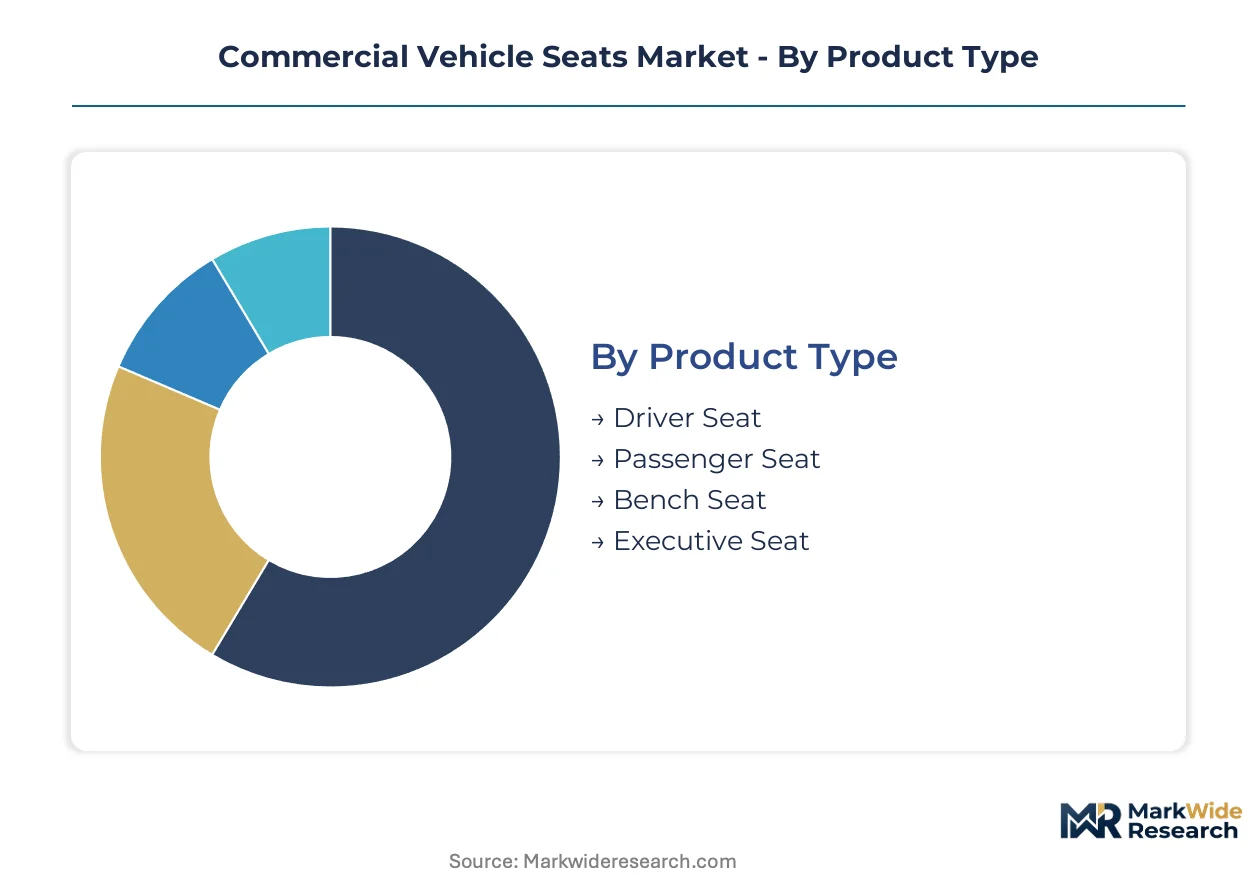
Commercial vehicle seat procurement splits along distinct technical and commercial fault lines that determine supplier qualification requirements and margin structures. Fleet operators specify different performance thresholds for driver versus passenger positions, while material choices trade off durability against weight targets in electrified platforms.
Product Type:
Replacement cycles vary dramatically across seating positions, with driver seats commanding premium refurbishment schedules due to concentrated wear patterns.
- Driver Seat:Integrated air suspension modules and heating elements define this specification tier. German long-haul fleet operators mandate 16-hour duty cycle certification, with vibration dampening calibrated to ISO 2631-1 thresholds for driver retention programs.
- Passenger Seat:Fixed-back configurations dominate this segment, though fold-flat designs are penetrating sleeper cab applications. Czech and Polish truck assembly plants source these units through just-in-time contracts tied to platform production schedules.
- Bench Seat:Crew cab configurations in vocational trucks utilize three-person bench assemblies with simplified suspension. Municipal utility vehicle procurement in France specifies these for maintenance and construction fleets.
- Executive Seat:Premium bus operators in the Netherlands and Belgium deploy these for tour and intercity routes, with leather trim and extended recline mechanisms differentiating passenger experience.
Driver Seat sits at the top of the volume ranking, with Executive Seat climbing the fastest as premium bus electrification accelerates.
Material:
Cost tiers separate material specifications, with REACH compliance timelines forcing accelerated reformulation decisions across supplier portfolios.
- Fabric:Polyester and wool blends dominate price-sensitive fleet procurement, with recycled-content thresholds now written into German OEM tenders. ECHA substance evaluations are compressing acceptable flame-retardant chemistries.
- Leather:Full-grain hides concentrate in executive bus and premium truck sleeper configurations. Italian tanneries supply this segment through qualified supplier networks with traceability documentation.
- Vinyl:Polyvinyl chloride formulations offer chemical resistance for vocational applications. Cleaning protocol compatibility drives specification in food-service and medical transport vehicles.
- Foam:Polyurethane systems with post-consumer recycled content are qualifying for EU Green Deal procurement preferences. Isocyanate supply concentration around Rotterdam creates formulation bottlenecks.
Foam commands the highest procurement attention due to recyclability mandates, with recycled-content formulations expanding most quickly.
End User:
Customer type determines contract structure, with captive supply agreements diverging sharply from spot aftermarket purchasing.
- Truck Manufacturers:Daimler Truck and Volvo Group anchor European demand through multi-year platform supply contracts. These OEMs specify modular architectures that reduce SKU complexity across cab variants.
- Bus Operators:Municipal and private coach fleets prioritize total cost of ownership calculations. Dutch public transport tenders now incorporate seat weight specifications to preserve electric range.
- Fleet Managers:Independent trucking companies in Hungary and Romania procure through distributor networks with extended warranty terms tied to driver retention metrics.
- OEMs:Captive seat production remains concentrated at major commercial vehicle assembly sites, though outsourcing pressure is mounting for non-driver positions.
Truck Manufacturers anchor procurement volume, with Fleet Managers gaining share fastest as independent operator consolidation proceeds.
Installation:
Channel structure determines margin capture, with direct OEM supply commanding premium pricing against independent service network alternatives.
- Built-in:Factory installation at commercial vehicle assembly plants in Germany and Sweden integrates seats into electrical and anchorage systems before chassis completion.
- Aftermarket:Independent service networks in Poland and Hungary are developing reconditioning capabilities for seat mechanism refurbishment and foam replacement.
- DIY:Owner-operator replacement of worn cushions and trim represents a price-sensitive channel with limited supplier brand loyalty.
- Custom:Specialized vehicle converters for emergency services and luxury coaches commission bespoke seating configurations with extended lead times.
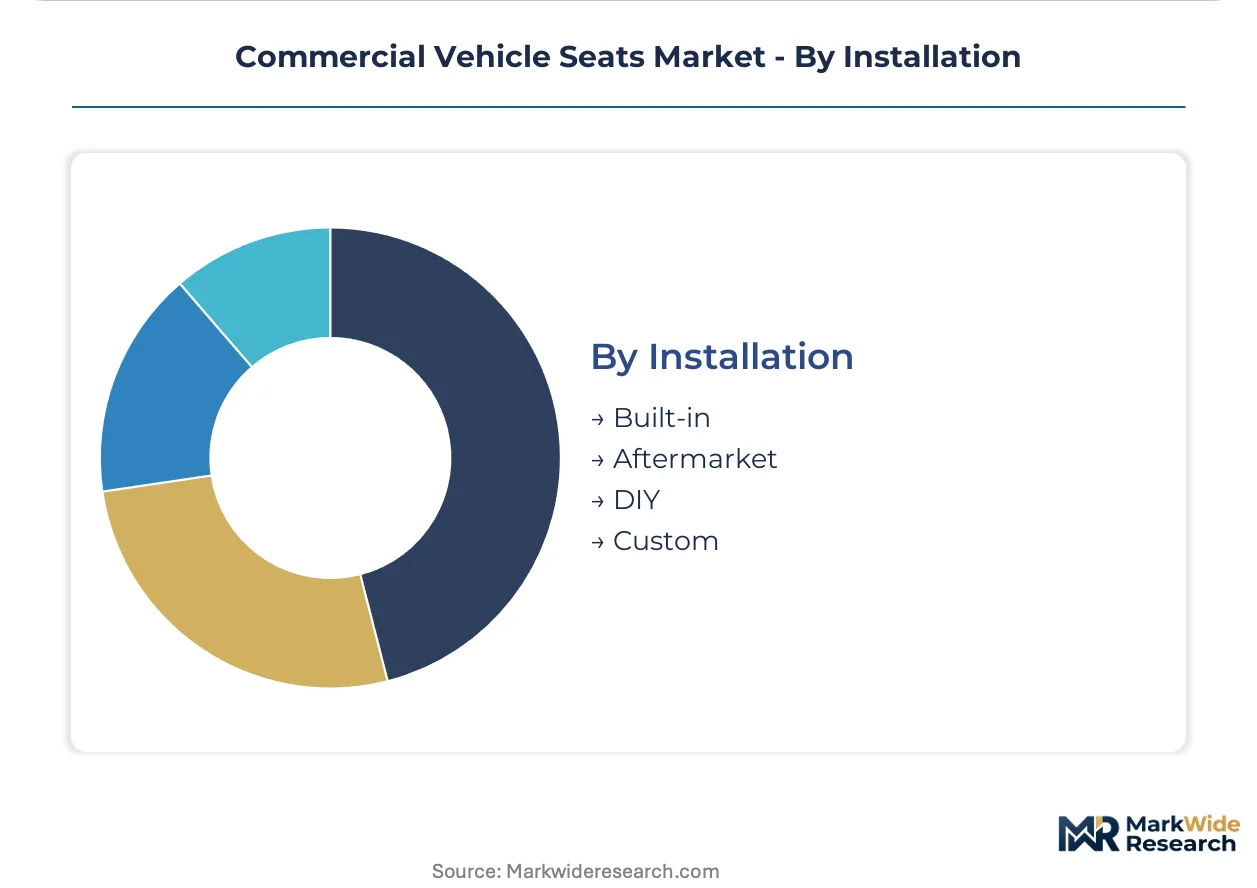
Built-in installation dominates value capture, with Aftermarket channels climbing fastest as refurbishment economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vehicle seat manufacturing traces its industrial lineage to post-war Germany, where specialized metalworking and upholstery trades consolidated around emerging truck and bus production corridors. This foundation established quality benchmarks and supplier qualification protocols that persist across European procurement standards today.
Germany
Long-haul fleet operators in Bavaria and Baden-Württemberg specify air-suspension driver seats with ISO 2631-1 vibration certification for driver retention programs. KBA homologation requirements for ECE R14 seat anchorage strength govern all products sold across the EU. Manufacturing clusters around Munich and Stuttgart anchor just-in-time delivery networks for Daimler Truck and MAN production lines.
United States
Heavy-duty truck OEMs in Michigan and Ohio source seats through multi-year platform contracts tied to NHTSA FMVSS 302 flammability compliance. Fleet consolidation across the Midwest and Southeast is compressing procurement cycles toward annual pricing agreements. The Detroit-Warren corridor concentrates final assembly integration for Class 8 truck configurations.
China
Domestic truck manufacturers in Shandong and Hubei provinces are qualifying local seat suppliers under dual carbon goals that prioritize lightweight composite frames. MIIT standards for commercial vehicle component durability are tightening test protocols for suspension mechanisms. The Yangtze River Delta hosts foam formulation facilities serving both domestic OEMs and export-bound configurations.
Japan
Bus electrification programs in Kanto and Kansai regions are driving specifications for reduced-weight seat assemblies to preserve battery range. METI safety guidelines for occupant protection in commercial vehicles influence regional tender requirements. Toyota Boshoku and affiliated suppliers concentrate R&D capacity around Nagoya engineering corridors.
India
State transport corporations in Maharashtra and Karnataka are modernizing bus fleets with improved passenger seating under BIS automotive component standards. PLI scheme incentives for auto component manufacturing are attracting seat assembly investments to Gujarat and Tamil Nadu. The Delhi-Mumbai Industrial Corridor is emerging as a logistics hub for aftermarket seat refurbishment channels.
Commercial Vehicle Seats Market Competitive Landscape
Premium-margin players sit above commodity-margin players across suspension technology integration and OEM qualification depth. The market structures around three tiers: integrated system suppliers with captive foam production, modular platform specialists serving multiple OEMs, and regional fabricators focused on aftermarket refurbishment. Consolidation pressure is mounting as fleet operators reduce approved vendor lists and extend warranty liability upstream. Dominant competitive moves include backward integration into polyurethane formulation and strategic partnerships for sensor-embedded seat architectures.
Within the integrated manufacturing tier, Faurecia and GRAMMER exemplify archetypes combining foam production with finished seat assembly. Adient occupies a position emphasizing modular platform architectures that reduce SKU complexity for truck OEMs. Among specialized seating suppliers, RECARO Automotive Seating represents the performance-oriented segment targeting premium bus and vocational vehicle configurations. These anchors demonstrate how qualification depth with major commercial vehicle manufacturers determines tier positioning and margin capture potential.
| Leading Market Players |
|---|
| Faurecia |
| TS Tech |
| GRAMMER |
| Toyota Boshoku Corporation |
| Johnson Controls International |
| Lear Corporation |
| RECARO Automotive Seating |
| Magna International |
| Adient |
| Others |
Pricing and Supply Chain Analysis
Fleet operator consolidation across German long-haul trucking anchors contract-based pricing structures that compress annual renegotiation windows and extend warranty liability upstream to seat suppliers. This buyer concentration forces tier-one manufacturers to absorb steel frame cost volatility within fixed-price multi-year agreements with Daimler Truck and MAN.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates air-suspension driver seats with ISO 2631-1 certification from fixed-back passenger units and simplified bench configurations. Price differentiation hinges on suspension technology grade and REACH-compliant material certification tiers. Cost compression in standard-tier foam formulations is intensifying because polyurethane feedstock concentration around Rotterdam port infrastructure limits supplier bargaining power. Fleet managers operating sleeper cab configurations demonstrate lowest price sensitivity due to driver retention program budgets, while municipal bus operators in Eastern Europe exhibit highest sensitivity to per-unit procurement costs.
Supply Chain Analysis
ECE R14 seat anchorage strength certification and REACH chemical registration timelines function as primary gating mechanisms that filter qualified suppliers from commodity fabricators. Manufacturing concentration clusters in Germany, Czechia, and China, with foam formulation drawing from isocyanate and polyol supply chains anchored to Rotterdam and Antwerp port infrastructure. Raw material dependencies center on cold-rolled steel for frame structures, polyurethane systems for cushioning, and textile inputs for trim materials. Single-source vulnerability characterizes European isocyanate supply, creating formulation bottlenecks for sustainable material transitions. Distribution runs through just-in-time delivery networks serving Munich and Stuttgart assembly corridors, with aftermarket refurbishment channels developing in Poland and Hungary.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial vehicle seating functions as a stable compounder anchored by fleet operator investment in driver retention infrastructure and regulatory mandates for sustainable materials. The EU Green Deal's evolving recyclability thresholds ensure steady replacement demand across OEM and aftermarket channels.
For Market Incumbents: Acquire polyurethane formulation expertise to secure captive supply of post-consumer recycled content foam and reduce dependency on Rotterdam-port isocyanate concentration. Backward integration into foam production insulates margin buffers against feedstock price volatility while qualifying suppliers for EU Green Deal procurement preferences. Defensive positioning requires sensor-embedded seat architecture development to counter biometric monitoring specialists entering from adjacent automotive electronics segments.
For New Entrants and Emerging Players: Begin with aftermarket refurbishment capabilities in Poland and Hungary, where independent truck service networks lack standardized seat reconditioning protocols and fleet managers seek extended warranty alternatives to OEM captive supply. Municipal bus electrification programs in the Netherlands and Belgium represent the most penetrable segment, with lightweight composite frame specifications creating entry paths outside established steel-frame supplier relationships. Go-to-market execution should target fleet compliance officers with EU AI Act documentation services bundled with biometric seat installations.
For Investors and Strategic Acquirers: Tier 1 automotive suppliers with modular platform competencies are the most active acquirer in this space, seeking seat assembly capabilities to complete interior system integration portfolios. Long-term viability over a five-to-ten year window rests on qualification depth with Daimler Truck and Volvo Group platform engineering teams. Acquisition target archetypes include specialized foam formulators with REACH-compliant sustainable chemistries and sensor-embedded seat developers with algorithmic transparency documentation capabilities. Watch for KBA homologation queue extensions as an inflection signal indicating capacity constraints favoring qualified incumbent expansion over new entrant qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Formulation | Captive polyurethane production secures EU Green Deal compliance and insulates margin buffers from Rotterdam feedstock volatility. |
| Sensor-Embedded Seat Architecture Development | Biometric monitoring capabilities address fleet operator liability concerns under emerging EU AI Act frameworks. |
| Aftermarket Refurbishment Network Expansion | Polish and Hungarian service channels capture margin beyond OEM captive supply with extended warranty positioning. |
| Lightweight Composite Frame Qualification | Bus electrification programs in the Netherlands specify reduced-weight assemblies to preserve battery range performance. |
| REACH-Compliant Flame Retardant Reformulation | Phosphorus-nitrogen synergist systems replace restricted organophosphates ahead of ECHA evaluation deadlines. |
Research Methodology
Direct dialogue with OEM platform engineers, fleet procurement managers, polyurethane formulation specialists, and aftermarket service network operators grounded qualitative assessment of specification trends and contract structures. Secondary validation drew from KBA type-approval databases, ECHA substance registration filings, vehicle production statistics, and customs trade records for steel and chemical inputs. Bottom-up segment sizing triangulated against top-down OEM procurement value chain estimates.
Market value and volume outputs across the projection horizon reflect structured segmentation by seating position, material composition, end-user category, and installation channel. CAGRs were derived from trend extrapolation of fleet replacement cycles, regulatory compliance timelines, and electrification content shifts. Industry-specific forecast inputs incorporated ECE R14 homologation queue data and REACH Annex XVII restriction implementation schedules.
Several conditions sit outside the modeled scope, including unannounced OEM platform cancellations, abrupt ECHA substance evaluation acceleration, and geopolitical disruption of Rotterdam-Antwerp chemical logistics corridors. Forecasts reflect documented assumptions regarding fleet operator consolidation trajectories and EU Green Deal enforcement consistency. A model refresh is warranted upon material change in KBA homologation processing capacity or REACH chemical registration timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Auto Ventilated Seats Market