
 Seat Comfort and Lumbar Actuator Systems Market | 2026-2036
Seat Comfort and Lumbar Actuator Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Seat Comfort and Lumbar Actuator Systems Market Insights
Buyer concentration among premium passenger vehicle OEMs is realigning procurement priorities across the supply base. Brose leverages its mechatronics heritage to anchor European seating actuator supply chains. Lear Corporation competes through vertical integration into foam, frame, and motion control assembly. Magna International sustains manufacturing scale across multiple vehicle platforms simultaneously.
Seat comfort and lumbar actuator systems comprise electromechanical drive units, typically integrating brushed or brushless DC motors with lead-screw or ball-screw linear translation mechanisms, generating adjustable lumbar support forces between 200 and 500 Newtons depending on occupant mass distribution and seat-back geometry. These systems enable real-time ergonomic profiling to reduce driver fatigue and musculoskeletal strain during extended operation. Electric technology leads volume shipments while magnetostrictive variants capture emerging interest in ultra-precise aviation seating where minimal electromagnetic interference and nanometer-scale positional accuracy justify premium positioning. Passenger vehicles dominate application demand though commercial transport fleets are expanding actuator retrofit programs to improve operator retention.
Federal Motor Vehicle Safety Standards administered by NHTSA govern seat strength and occupant protection requirements that indirectly shape actuator load-rating specifications in the United States. ECE R14 and R17 regulations under UN Economic Commission for Europe protocols mandate seat anchorage integrity and head restraint positioning that constrain actuator mounting geometry and travel envelopes across EU-member and aligned markets. Tier-1 integrators and OEM engineering teams must monitor pending amendments to FMVSS 302 flammability standards and evolving EU end-of-life vehicle directives that could alter housing material selection and recyclability obligations.
Market Dynamics
Electric actuator architectures are displacing pneumatic lumbar systems across premium vehicle platforms as OEMs pursue revised efficiency mandates and weight reduction targets. This technology transition concentrates procurement leverage among mechatronics-capable Tier-1 suppliers with in-house motor and motion control competencies.
Growth Catalysts
- FMVSS 302 Flammability Revisions:Pending NHTSA amendments are accelerating housing material qualification cycles, opening specification windows for advanced polymer compounds with improved thermal resistance.
- Commercial Fleet Retrofit Programs:North American trucking operators are expanding actuator installations to reduce driver turnover and workers compensation claims linked to musculoskeletal disorders.
- Magnetostrictive Positioning:Aviation seating manufacturers in Germany and Japan are piloting solid-state actuation for nanometer-scale accuracy in first-class cabin configurations.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export controls compress margin stability for brushless DC motor production.
- Ball-Screw Supply Concentration:Precision ground screw manufacturing clusters in Switzerland and Japan create single-source vulnerability for high-load lumbar mechanisms.
- Pneumatic System Lock-In:Legacy seat platforms in mass-market segments retain compressed air infrastructure, slowing electromechanical conversion timelines.
Strategic Opportunities
- India PLI Scheme Alignment:Component localization incentives under the Production Linked Incentive program invite captive manufacturing investment for export-oriented seating modules.
- EU End-of-Life Vehicle Directives:Recyclability mandates are creating specification pull for aluminum-housing actuators with disassembly-friendly fastener architectures.
- Sensor-Actuator Convergence:Integration of pressure-mapping arrays with real-time lumbar force adjustment is opening software-defined seating feature tiers.
Industry Challenges
- Embedded Firmware Talent Scarcity:Motion control algorithm development for brushless motor commutation faces recruitment gaps across Midwest US and Bavarian engineering clusters.
- ISO 26262 Certification Burden:Functional safety documentation for seat-mounted actuators in autonomous-ready vehicles extends validation timelines by 8-14 months.
- Legacy LIN Bus Integration:New electric actuators must maintain backward compatibility with 2008-2018 vehicle electrical architectures without protocol gateway cost penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seat Comfort and Lumbar Actuator Systems Market |
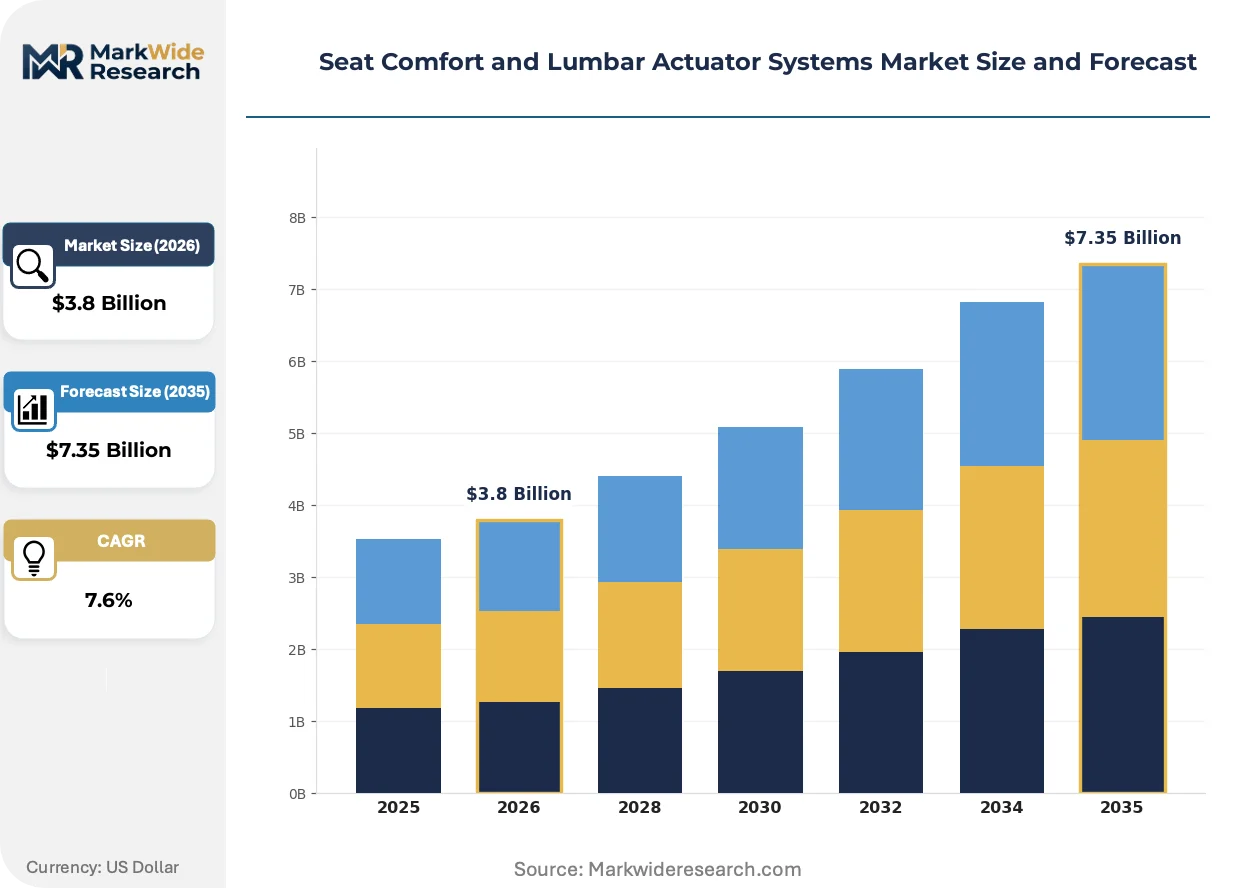
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Linear Actuators, Rotary Actuators, Motors, Sensors, Controls Technology: Electric, Pneumatic, Hydraulic, Magnetostrictive, Piezoelectric Application: Passenger Vehicles, Heavy Machinery, Commercial Transport, Marine Seating, Aviation Seating End User: OEMs, Aftermarket Suppliers, Tier-1 Integrators, Vehicle Assemblers |
| Companies Covered | Brose, Adient, Lear Corporation, Forvia, Robert Bosch, TS Tech, NHK Spring, Magna International, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seat Comfort and Lumbar Actuator Systems Market Trends and Innovations
Seating module architectures are converging around domain-centralized computing, compressing actuator intelligence requirements while elevating precision demands. This shift favors suppliers with mechatronics integration depth over component specialists.
Brushless DC motors with integrated position sensors are expanding into premium SUV and electric vehicle platforms where silent operation and 50,000-cycle durability ratings command specification priority. BMW and Mercedes-Benz have standardized these architectures across 2024 model year seat programs. The technology is expanding into mid-size vehicle segments previously served by brushed motor alternatives, compressing the addressable market for legacy electromechanical suppliers.
REACH Substance of Very High Concern listings are forcing reformulation of potting compounds and cable jacketing used in actuator housings. ECHA's 2023-2024 candidate list expansions target phthalate plasticizers and certain flame retardants common in automotive wire insulation. European Tier-1 integrators are accelerating qualification of bio-based polyamide alternatives, with seat harness suppliers facing 2026 compliance deadlines for new platform awards.
Fleet procurement departments are consolidating specification authority previously dispersed across regional maintenance managers, centralizing actuator vendor selection at headquarters level. This concentration favors suppliers with national service networks and multi-year total cost of ownership data over price-focused distributors. The pattern is most visible in US Class 8 trucking where Werner, Schneider, and J.B. Hunt have standardized lumbar actuator specifications across 15,000-plus unit annual orders.
Seat Comfort and Lumbar Actuator Systems Market Segmentation
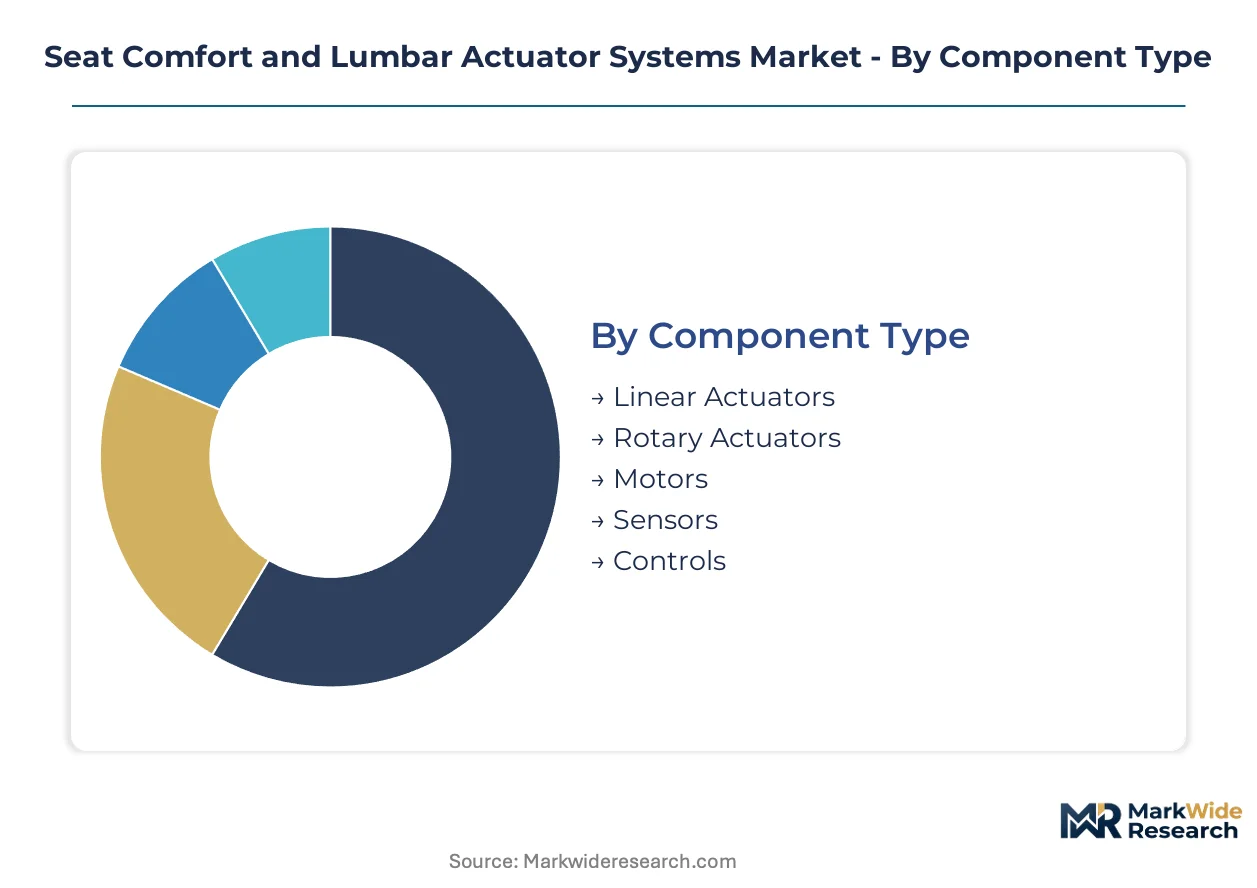
Seat comfort and lumbar actuator systems fragment across multiple technical and commercial dimensions. Component complexity and integration depth vary sharply by application, reshaping supplier capability requirements. Procurement patterns diverge between automotive OEMs and specialized transport operators.
Component Type:
Capital intensity concentrates in precision motion hardware where machining tolerances and motor winding automation demand dedicated production assets.
- Linear Actuators:Lead-screw and ball-screw mechanisms generate 200-500 Newton lumbar support forces through electromechanical translation. Passenger vehicle OEMs in Germany and Japan specify these for multi-way adjustable seat architectures under revised efficiency mandates.
- Motors:Brushed and brushless DC motor assemblies constitute the electromechanical core, with brushless variants capturing premium SUV and electric vehicle platforms where silent operation and 50,000-cycle durability command specification priority.
- Rotary Actuators:Torque-dense designs enable recliner and headrest articulation through worm-gear reduction stages.
- Sensors:Hall-effect and potentiometric position feedback devices enable closed-loop force control.
- Controls:Embedded motor drivers and LIN bus interface modules manage motion profiles.
Linear actuators absorb the bulk of installed capacity; motors are expanding most quickly as brushless architectures displace legacy electromechanical alternatives.
Technology:
Technology selection tracks application precision requirements and electromagnetic compatibility constraints across transport modes.
- Electric:DC motor-driven electromechanical systems dominate volume shipments across automotive seating, displacing pneumatic alternatives under weight reduction and efficiency mandates. BMW and Mercedes-Benz have standardized brushless architectures across recent model year seat programs.
- Magnetostrictive:Solid-state actuation using Terfenol-D or Galfenol alloys delivers nanometer-scale positional accuracy with minimal electromagnetic interference. Aviation seating manufacturers in Germany and Japan pilot these for first-class cabin configurations where precision justifies premium positioning.
- Pneumatic:Compressed air bladder systems retain presence in legacy mass-market seat platforms where infrastructure lock-in slows conversion timelines.
- Hydraulic:Fluid-power actuation serves heavy machinery operator seats requiring extreme load ratings.
- Piezoelectric:Ceramic-stack positioning enables ultra-fine adjustment in specialized ergonomic applications.
Electric technology commands the dominant share of unit volume; magnetostrictive systems are gaining share fastest in aviation and precision seating segments.
Application:
Application segmentation reflects divergent duty cycles, regulatory exposure, and operator retention economics across transport modes.
- Passenger Vehicles:Light-duty automotive seating generates the foundational demand base, with premium OEMs expanding adjustable architectures across model lines. Electric actuator penetration concentrates here as efficiency mandates reshape specification priorities.
- Commercial Transport:Class 8 trucking and long-haul fleet operators are expanding actuator retrofit programs to reduce driver turnover and workers compensation claims linked to musculoskeletal disorders. Werner, Schneider, and J.B. Hunt have standardized lumbar specifications across large annual orders.
- Heavy Machinery:Construction and mining equipment seating demands ruggedized actuators with extended environmental sealing.
- Aviation Seating:First-class and business-class cabin configurations drive precision actuation requirements with minimal electromagnetic interference tolerance.
- Marine Seating:Vessel operator stations require corrosion-resistant architectures for saltwater environments.
Passenger vehicles retain the steepest installed base; commercial transport is climbing the fastest as fleet procurement centralizes ergonomic specification authority.
End User:
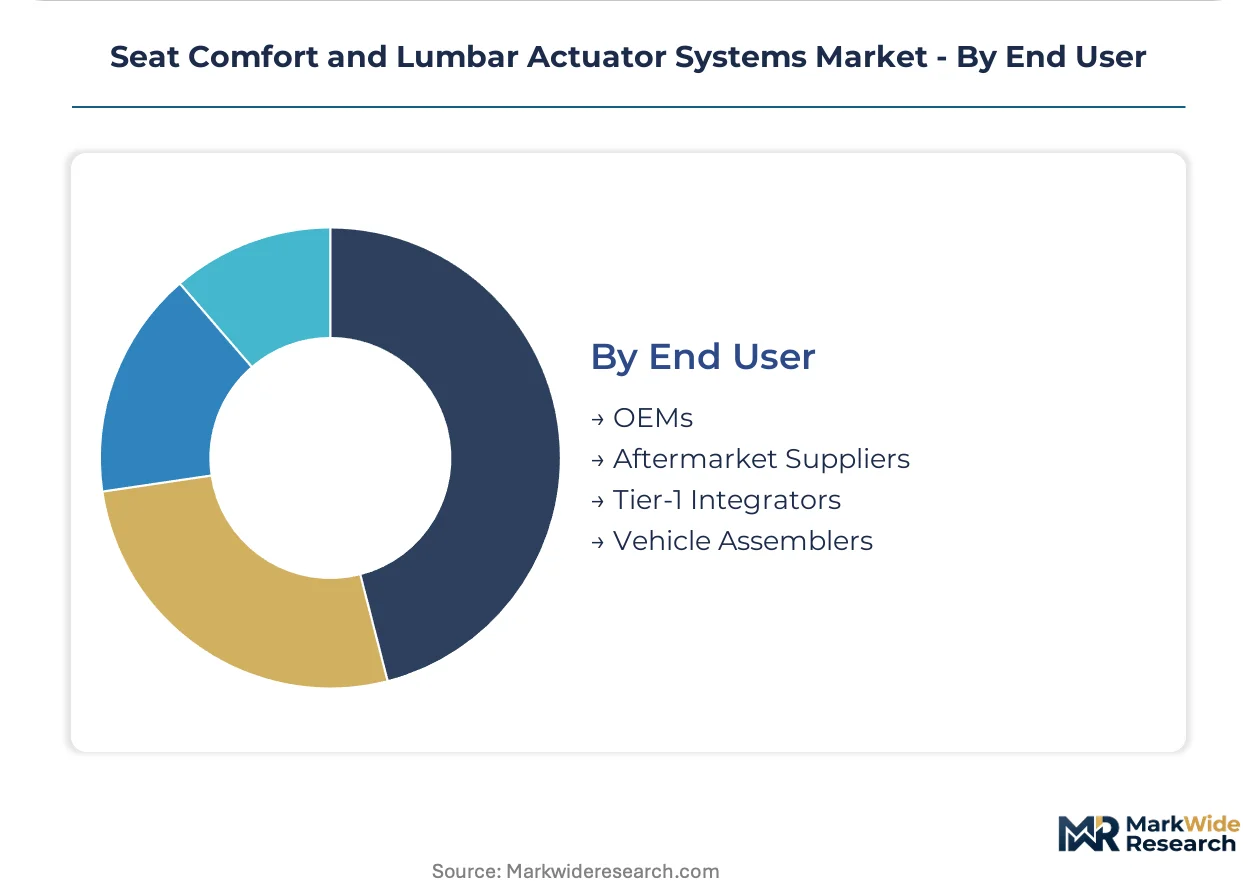
End user structure tracks supply chain tiering and backward integration depth across seating module production.
- OEMs:Premium passenger vehicle manufacturers maintain direct specification authority for seat programs, consolidating procurement leverage among mechatronics-capable suppliers with in-house motor and motion control competencies.
- Tier-1 Integrators:Seating module specialists such as Lear Corporation and Magna International assemble complete seat systems, controlling actuator sourcing decisions through captive supply relationships or external procurement.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations receive seating modules as complete subassemblies.
- Aftermarket Suppliers:Independent distributors and retrofit specialists serve commercial fleet upgrade programs and replacement demand.
OEMs and Tier-1 integrators together absorb the bulk of production volume; aftermarket channels are expanding most quickly in North American commercial fleet retrofit activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for seat comfort and lumbar actuator systems concentrates in automotive manufacturing clusters where premium vehicle production and seating module integration depth intersect. Germany, Japan, and the United States absorb the majority of procurement volume through direct OEM relationships and Tier-1 integrator networks.
Germany
Premium passenger vehicle OEMs headquartered in Stuttgart and Munich drive specification authority for multi-way adjustable seat architectures. ECE R14 and R17 regulations under UN Economic Commission for Europe protocols mandate seat anchorage integrity and head restraint positioning that constrain actuator mounting geometry. The Baden-Württemberg cluster around Stuttgart hosts concentrated seating module engineering activity.
Japan
Aviation seating manufacturers in Nagoya and Tokyo pilot magnetostrictive solid-state actuation for first-class cabin configurations requiring nanometer-scale accuracy. METI efficiency mandates accelerate electric actuator displacement of pneumatic systems across domestic vehicle platforms. The Aichi Prefecture automotive corridor sustains deep supplier integration for brushless motor production.
United States
Commercial fleet operators including Werner, Schneider, and J.B. Hunt centralize lumbar actuator specifications at headquarters level across annual orders exceeding 15,000 units. Federal Motor Vehicle Safety Standards administered by NHTSA govern seat strength requirements that indirectly shape actuator load-rating specifications. Michigan and Ohio host the primary seating module assembly corridors serving Detroit-based OEMs.
China
Domestic electric vehicle manufacturers expand adjustable seating architectures across model lines under revised vehicle efficiency mandates. MIIT regulations on new energy vehicle weight reduction accelerate electromechanical conversion timelines previously constrained by pneumatic system lock-in. The Yangtze River Delta cluster around Shanghai concentrates Tier-1 seating module manufacturing for both domestic and export programs.
India
Component localization incentives under the PLI scheme invite captive manufacturing investment for export-oriented seating modules. BIS standards for automotive seating safety create compliance pathways for actuator load-rating specifications aligned with European and North American requirements. Tamil Nadu and Gujarat host expanding seating module assembly operations serving multinational OEMs.
Seat Comfort and Lumbar Actuator Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-actuator convergence and software-defined seating feature tiers. The supplier base organizes around three archetypes: mechatronics-heritage specialists with in-house motor competencies, vertically integrated seating module assemblers controlling captive supply relationships, and diversified automotive component conglomerates sustaining manufacturing scale across multiple vehicle platforms. Competitive dynamics center on backward integration into precision motion hardware and strategic partnerships for domain-centralized computing architectures.
Among European mechatronics specialists, Brose anchors the premium-tier supply chain through its heritage in precision drive systems. Lear Corporation and Magna International exemplify the vertically integrated archetype, with Lear representing upstream control over foam, frame, and motion control assembly while Magna occupies a position sustaining simultaneous manufacturing scale across multiple OEM platforms. These three entities collectively illustrate the competitive tension between component specialization and full-system integration that defines procurement leverage in seating actuator markets.
| Leading Market Players |
|---|
| Brose |
| Adient |
| Lear Corporation |
| Forvia |
| Robert Bosch |
| TS Tech |
| NHK Spring |
| Magna International |
| Denso Corporation |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement centralization at Werner, Schneider, and J.B. Hunt headquarters is compressing supplier margins while demanding national service networks and multi-year total cost of ownership documentation. This buyer consolidation forces Tier-1 integrators to absorb precision motion hardware costs or sacrifice specification slots to mechatronics-capable competitors.
Pricing Analysis
Volume shipments of brushed DC motor actuators command thin margins in mass-market segments while brushless architectures in premium SUVs and electric vehicles sustain healthier returns. Price differentiation rests on ISO 26262 functional safety certification tiers and volume scale commitments from OEM platform engineers. Cost compression in standard-tier electric actuators is intensifying because rare earth magnet volatility from Chinese export controls squeezes brushless motor production economics. Commercial fleet retrofit buyers exhibit highest price sensitivity; aviation seating manufacturers demonstrate lowest sensitivity due to nanometer-scale precision requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from BMW and Mercedes-Benz platform engineering teams while Tier-1 integrators like Lear Corporation and Magna International manage multi-source procurement for complete seat system assembly. Manufacturing gravity centers on Germany, Japan, and the United States where seating module integration depth is greatest. Precision ground ball-screw supply draws from Switzerland and Japan, creating single-source vulnerability for high-load lumbar mechanisms. Tariff exposure on rare earth magnet imports from China presents structural supply chain risk. Distribution runs through captive supplier relationships and external procurement networks controlled by vertically integrated seating module assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ball-screw manufacturing concentration in Swiss and Japanese precision machining clusters constrains capacity expansion, propping pricing power for suppliers with secured allocation agreements. This bottleneck benefits incumbents with long-standing supplier relationships.
For Market Incumbents: Cement specification authority by locking multi-year ball-screw supply agreements with Swiss and Japanese precision manufacturers before capacity constraints tighten. Deepen backward integration into brushless DC motor winding automation to offset rare earth magnet cost volatility from Chinese export control exposure. Prioritize ISO 26262 certification investment for autonomous-ready vehicle programs where validation timelines already extend procurement lead times. For New Entrants and Emerging Players: Begin with commercial fleet retrofit channels where headquarters-level procurement consolidation at major trucking operators has standardized specifications across 15,000-plus unit annual orders. Target sensor-actuator convergence opportunities in software-defined seating feature tiers where embedded firmware talent scarcity creates entry gaps. Pursue partnership routes with Indian PLI scheme beneficiaries seeking export-oriented seating module component suppliers. For Investors and Strategic Acquirers: The window for entry favors mechatronics-heritage specialists with in-house motor competencies and secured precision motion hardware supply relationships over pure component assemblers. Long-term viability hinges on domain-centralized computing architecture alignment where actuator intelligence requirements compress but precision demands escalate. Watch for magnetostrictive solid-state actuation pilot program expansion at German and Japanese aviation seating manufacturers as inflection signal for premium-tier technology displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Motion Hardware | Secures ball-screw allocation from Swiss and Japanese manufacturers against single-source vulnerability. |
| ISO 26262 Functional Safety Certification Investment | Extends validation timelines by 8-14 months but locks autonomous-ready vehicle specification slots. |
| Sensor-Actuator Convergence Development | Opens software-defined seating feature tiers through pressure-mapping array integration with real-time lumbar adjustment. |
| India PLI Scheme Manufacturing Alignment | Captures component localization incentives for export-oriented seating module captive supply relationships. |
| Magnetostrictive Actuation Pilot Partnership | Positions for aviation first-class cabin precision requirements with minimal electromagnetic interference tolerance. |
Research Methodology
SEC 10-K filings, NHTSA regulatory dockets, and ECHA REACH substance listings formed the secondary backbone for supply chain mapping and compliance pathway analysis. Primary interviews with Tier-1 seating module procurement directors, OEM platform engineers, and commercial fleet maintenance managers validated specification trends and pricing dynamics. Brushless motor commutation algorithm developers and precision motion hardware plant managers contributed technical depth on capacity constraints. Bottom-up triangulation across component-level production data and top-down reconciliation against vehicle production databases ensured segmentation integrity.
Bottom-up volume modeling tracked actuator shipments by vehicle class, propulsion architecture, and content per vehicle across the projection horizon. Top-down value reconciliation applied regional pricing differentials observed in Germany, Japan, and United States procurement patterns. CAGRs were derived from segment-specific growth trajectories weighted by premium SUV and electric vehicle platform expansion timelines. Rare earth magnet price volatility assumptions and ball-screw manufacturing capacity constraints informed sensitivity boundaries.
Underlying measurement precision varies by segment; passenger vehicle OEM specification data carries tighter precision than aftermarket retrofit channel estimates. Forecasts reflect assumptions on electric actuator displacement timelines and aviation magnetostrictive adoption curves that regulatory amendments or commodity shocks could revise. Periodic stress-testing of base assumptions against NHTSA FMVSS amendment schedules and ECHA SVHC list expansions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
Automotive Baggage Handling System Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market