
 Automotive OEM Interior Coatings Market | 2026-2036
Automotive OEM Interior Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive OEM Interior Coatings Market Analysis
The gap between premium and commodity interior coating tiers is broadening as OEMs specify differentiated haptic and visual finishes for luxury vehicle lines versus cost-optimized mass-market platforms. PPG Industries leverages its color-matching expertise to sustain premium positioning with major European and North American OEMs. BASF SE anchors its competitive stance through integrated resin and coating formulation capabilities that reduce supply chain complexity for tier-1 suppliers. Kansai Nerolac Paints Limited dominates the Asian market through deep relationships with Japanese and Korean vehicle manufacturers.
Automotive OEM interior coatings are formulated polymer systems—primarily urethane, acrylic, and epoxy chemistries—applied to dashboard substrates, door panels, and instrument clusters to deliver scratch resistance, UV stability, and tactile surface quality. These coatings cure through spray, powder, or liquid processes at thicknesses typically ranging from 25 to 100 microns to meet OEM durability specifications exceeding 10 years of interior service life. Urethane coatings lead the product type landscape due to their superior flexibility and abrasion resistance in high-touch cabin areas. Spray coating technology occupies the largest share of application methods, though powder coating is gaining share where VOC regulations tighten most aggressively. Among end users, tier-1 suppliers control the dominant procurement channel as they integrate coating operations into interior module assembly before delivering complete dashboard and door panel modules to vehicle manufacturers.
The EPA enforces VOC emission limits that constrain solvent-borne coating formulations in the United States, while REACH and the EU Green Deal in Europe mandate progressive reduction of hazardous substances and carbon intensity across coating lifecycles. China's MEE implements parallel emission standards that push domestic and multinational suppliers toward waterborne technology transitions. Stakeholders must monitor how regulatory divergence across these jurisdictions reshapes formulation R&D priorities and capital allocation for coating plant upgrades.
Market Dynamics
Waterborne coating chemistry transitions are compressing solvent-borne capacity while tier-1 suppliers consolidate procurement power around integrated formulation-resin partnerships.
Growth Catalysts
- REACH substance restrictions:Europe's progressive hazardous substance phase-outs force coating suppliers to accelerate bio-based binder development, expanding addressable premium segments for compliant formulations.
- Electric vehicle cabin architectures:Battery-electric platforms demand lighter, lower-VOC interior finishes with enhanced thermal stability for battery-proximate modules.
- German assembly cluster concentration:Dense OEM and tier-1 supplier networks in Stuttgart, Wolfsburg, and Munich create localized demand pull for just-in-time coating delivery systems.
Market Restraints
- Petrochemical resin volatility:Urethane and acrylic precursor costs fluctuate with crude oil derivatives, compressing formulation margins for mid-tier suppliers without captive resin supply.
- Application equipment lock-in:Existing spray booths and curing ovens represent sunk capital that slows waterborne technology transitions at smaller tier-2 facilities.
- Performance gap in high-wear zones:Current bio-based coatings exhibit inferior mar resistance versus solvent-borne alternatives in steering wheel and gear shift applications.
Strategic Opportunities
- China's dual carbon targets:Provincial MEE enforcement in Jiangsu and Guangdong creates first-mover advantage for waterborne specialists establishing local technical service centers.
- In-mold coating integration:Converging injection molding and surface finishing processes eliminates post-mold coating steps for door panel substrates.
- Digital color-matching platforms:Cloud-based spectrophotometry tools enable tier-1 suppliers to reduce OEM approval cycles from weeks to days.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in waterborne polymer stabilization and rheology control remains concentrated among retiring specialists at legacy coating houses.
- OEM qualification timelines:Interior coating approvals require 18-24 month durability testing under SAE and OEM-specific protocols, freezing supplier switches mid-program.
- Legacy ERP integration:Real-time inventory tracking for just-in-sequence coating delivery demands middleware upgrades at mature tier-1 plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive OEM Interior Coatings Market |
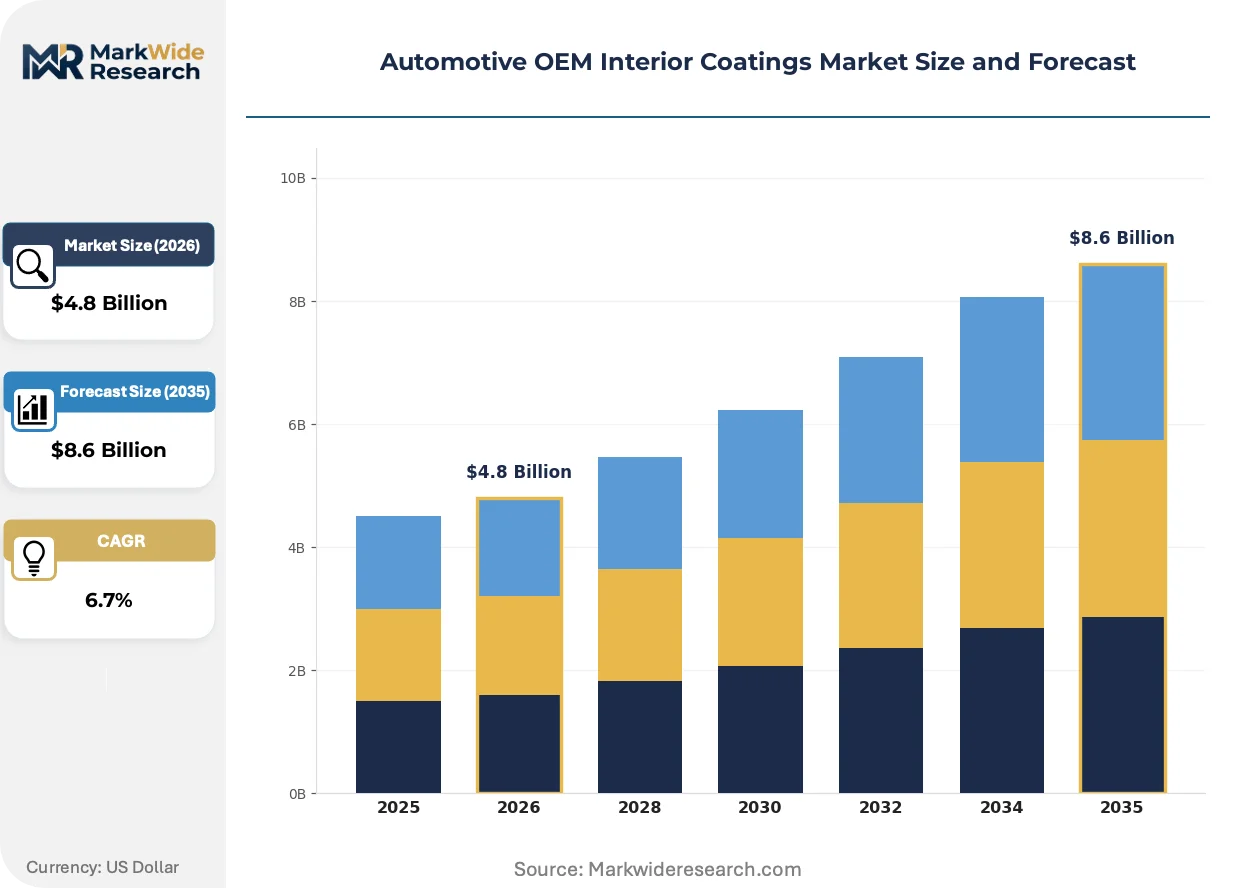
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urethane, Acrylic, Epoxy, Polyester Application: Dashboard, Door Panels, Instrument Clusters, Headliners End User: Tier-1 Suppliers, Vehicle Manufacturers, Aftermarket Providers, Custom Installers Technology: Spray Coating, Powder Coating, Liquid Coating, Film Coating |
| Companies Covered | PPG Industries Inc, Akzo Nobel N.V., BASF SE, Axalta Coating Systems, Kansai Nerolac Paints Limited, Nippon Paint Holdings Co., Ltd., RPM International Inc, KCC Corporation, Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive OEM Interior Coatings Market Emerging Trajectories
Coating application hardware and formulation chemistry are converging to eliminate process steps, while regulatory pressure and buyer concentration reshape how value is captured across the supply chain.
Self-healing polyurethane clearcoats are penetrating luxury vehicle lines through microcapsule-based scratch recovery mechanisms. Mercedes-Benz and BMW specification teams are qualifying these finishes for dashboard and center console modules. This technology is modularizing repair and warranty cost structures while compressing traditional touch-up coating revenue streams.
EPA VOC emission limits under 40 CFR Part 59 are constraining solvent-borne spray operations at US assembly plants. Tier-1 suppliers in Michigan and Ohio are retrofitting booths for waterborne conversion or relocating coating operations to Mexico to exploit regulatory arbitrage. Interior module categories with the highest surface area—door panels and instrument clusters—face the steepest compliance cost escalation.
Consolidated procurement desks at Magna, Faurecia, and Forvia are unbundling coating supply from substrate manufacturing. These tier-1 giants now specify formulation performance standards while sourcing directly from resin producers, bypassing traditional coating compounders. The shift is most advanced in Germany and Japan, where supplier development programs embed chemists at OEM technical centers.
Automotive OEM Interior Coatings Market Segmentation
Interior coating procurement flows through distinct technical and commercial channels that reshape how suppliers allocate R&D and capital. Each segmentation dimension reveals where formulation expertise, application hardware, and regulatory compliance intersect to determine competitive position.
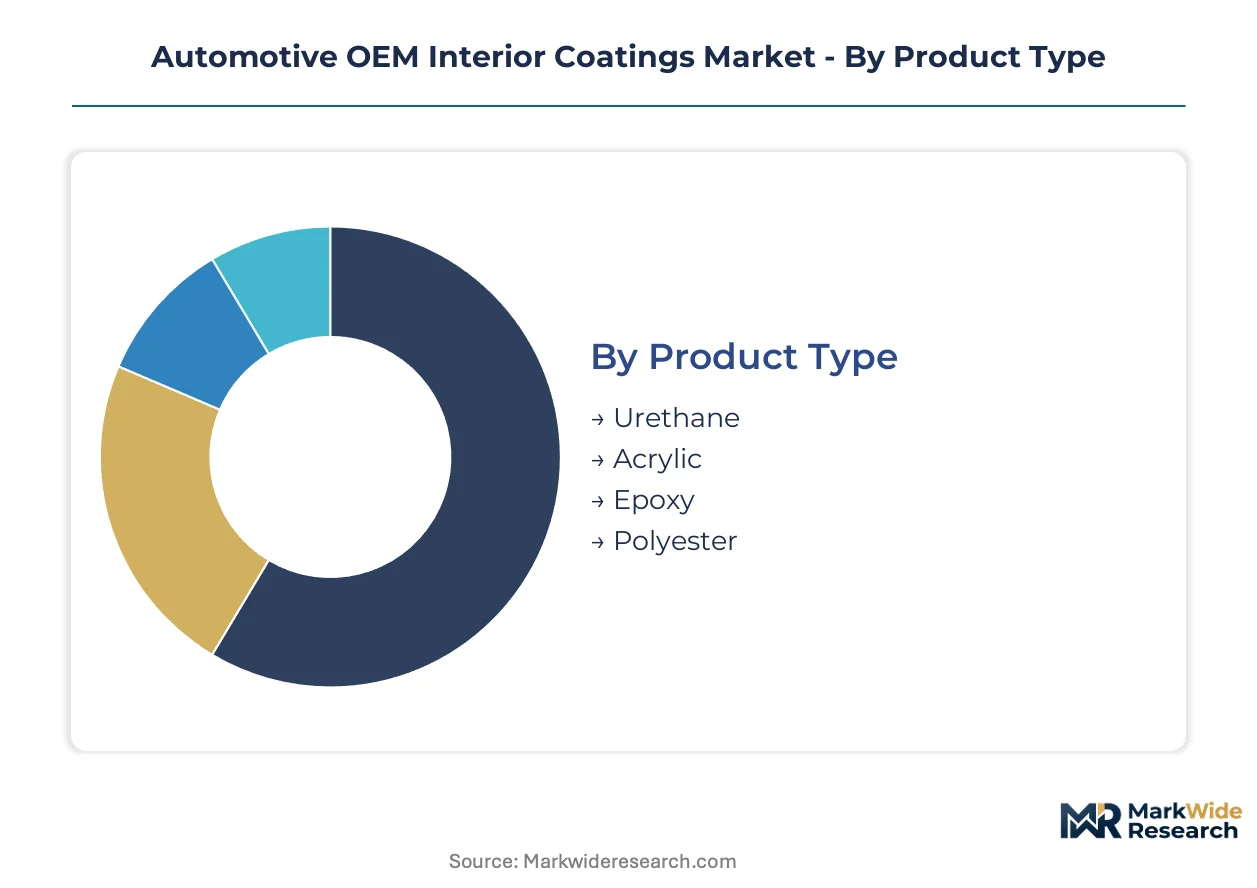
Product Type:
Capital intensity varies sharply across polymer platforms, with urethane requiring the most sophisticated resin synthesis and curing infrastructure.
- Urethane:Polymer systems built on isocyanate-cured aliphatic backbones deliver unmatched flexibility and abrasion resistance for high-touch surfaces. German and Japanese OEMs specify urethane for steering wheels and gear selectors where 10-year mar resistance is mandatory. REACH substance restrictions on isocyanate monomers are forcing reformulation toward blocked-cure alternatives.
- Acrylic:Thermoplastic and thermoset acrylics dominate cost-optimized mass-market platforms through simpler spray application and faster line speeds. Chinese MEE enforcement in Jiangsu province accelerates waterborne acrylic transitions for domestic OEM supply chains. Thermal stability limitations exclude acrylics from battery-proximate EV modules.
- Epoxy:Rigid, chemically resistant systems anchor instrument cluster bezels and rigid substrate applications.
- Polyester:Saturated polyester resins serve powder coating lines where zero-VOC compliance is non-negotiable.
Most installed capacity flows through Urethane. Expansion is steepest in Acrylic as waterborne platforms mature.
Application:
Surface area and touch frequency determine formulation performance tiers and OEM qualification rigor.
- Dashboard:Largest interior surface area demands coatings balancing UV stability, haptic quality, and thermal cycling resistance. Stuttgart and Wolfsburg assembly clusters source dashboard modules with integrated coating from Faurecia and Forvia plants. Self-healing clearcoats are penetrating luxury specifications here first.
- Door Panels:Complex geometries with multiple substrate types—plastic, leather, fabric—require coating systems compatible with varied adhesion promoters. In-mold coating integration is eliminating post-mold finishing steps for door substrates at Magna facilities in Michigan and Ontario.
- Instrument Clusters:Smaller surface area but highest optical clarity requirements favor high-gloss urethane and epoxy systems.
- Headliners:Fabric and foam-backed substrates use specialized spray or film coating with low-temperature cure to prevent substrate distortion.
Dashboard absorbs the majority of formulation R&D spend. Door Panels are gaining share fastest through module consolidation trends.
End User:
Procurement authority concentrates in tier-1 suppliers who control coating application timing and specification.
- Tier-1 Suppliers:Magna, Faurecia, Forvia, and Yanfeng operate captive coating lines or specify formulations for outsourced application. These consolidated procurement desks unbundle coating from substrate manufacturing, sourcing resins directly from BASF and PPG while setting performance standards. Their 18-24 month OEM qualification timelines freeze supplier relationships mid-program.
- Vehicle Manufacturers:Premium OEMs like BMW and Mercedes-Benz retain direct coating specification for luxury lines, embedding chemists at technical centers to develop differentiated haptic finishes. Volume manufacturers delegate entirely to tier-1 partners.
- Aftermarket Providers:Refinish and repair coatings serve collision repair and vehicle refurbishment channels with less stringent durability testing.
- Custom Installers:Niche segment serving specialty vehicle modifications and executive fleet upfitting with small-batch, color-matched finishes.
Tier-1 Suppliers channel the dominant procurement volume. Vehicle Manufacturers command the steepest premium pricing through direct specification.
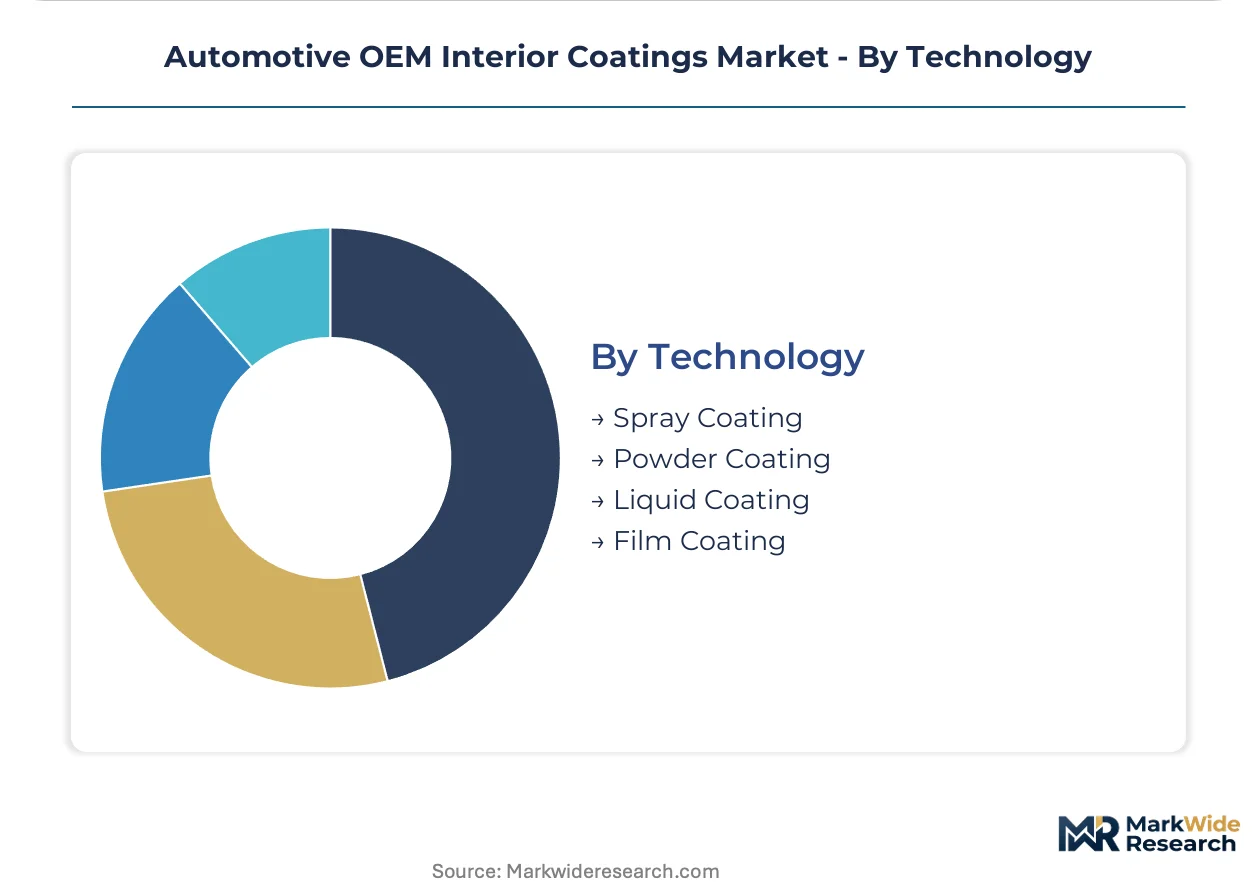
Technology:
Application method determines VOC exposure, capital requirements, and line integration complexity.
- Spray Coating:Conventional air-assisted and electrostatic spray dominates existing capacity with 25-100 micron film builds. EPA 40 CFR Part 59 constraints are forcing booth retrofits or geographic relocation to Mexico at US tier-1 plants. Waterborne spray conversion requires humidity-controlled curing environments that compress effective line speeds.
- Powder Coating:Zero-VOC thermal cure systems gain share where regulatory pressure is most severe, particularly under EU Green Deal carbon intensity mandates. High-temperature cure requirements limit substrate compatibility to metal and high-heat plastics.
- Liquid Coating:Dip and flow-coat methods serve complex interior trim with uniform coverage requirements.
- Film Coating:Pre-formed decorative films with adhesive backing enable design flexibility without liquid application infrastructure.
Spray Coating retains the largest installed base. Powder Coating is climbing the fastest as European and Chinese regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and polymer engineers cluster in Germany, China, and the United States, anchoring the industry's technical talent base and driving regional R&D intensity.
United States
Domestic OEM assembly plants in Michigan, Ohio, and Tennessee generate concentrated demand for dashboard and door panel coatings. EPA enforcement of 40 CFR Part 59 VOC limits forces tier-1 suppliers to retrofit spray booths or relocate finishing operations to Mexico. The Detroit-Windsor corridor hosts Magna and Forvia facilities where waterborne conversion timelines compress procurement cycles.
Germany
Mercedes-Benz and BMW specification teams in Stuttgart and Munich demand differentiated haptic finishes for luxury vehicle lines. REACH substance restrictions on isocyanate monomers accelerate blocked-cure urethane development at BASF and PPG technical centers. The Wolfsburg-Hanover axis anchors Volkswagen Group's interior module sourcing, with Faurecia operating captive coating lines for just-in-sequence delivery.
China
Jiangsu and Guangdong provincial MEE offices enforce dual carbon targets that push domestic OEM supply chains toward waterborne acrylic platforms. BYD and NIO battery-electric architectures require lighter, lower-VOC interior finishes with enhanced thermal stability. The Yangtze River Delta concentration of Yanfeng and tier-1 supplier plants creates localized demand pull for technical service centers.
Japan
Toyota and Honda qualification protocols demand 10-year mar resistance for steering wheel and gear selector applications. METI guidance on carbon-neutral manufacturing aligns with Kansai Nerolac's waterborne formulation roadmaps. The Nagoya-Osaka industrial corridor hosts concentrated coating application facilities serving Japanese OEM export programs.
South Korea
Hyundai and Kia EV platform launches in Asan and Hwaseong drive specification of UV-stable interior finishes for battery-proximate modules. MFDS-aligned chemical safety assessments intersect with MEE-equivalent emission standards at domestic coating plants. The Busan-Ulsan petrochemical complex supplies captive resin feedstocks to KCC Corporation formulation operations.
Automotive OEM Interior Coatings Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as integrated resin-coating compounders face unbundling pressure from consolidated tier-1 procurement desks. The supplier base segments into three strategic archetypes: integrated chemical conglomerates with captive resin supply, specialized coating formulators with color-matching expertise, and regional players with OEM relationship depth. Dominant competitive moves include backward integration into resin production and geographic relocation to exploit regulatory arbitrage between US EPA constraints and Mexican enforcement gaps.
Among North American-integrated compounders, PPG Industries and Sherwin-Williams occupy positions anchored in color-matching capabilities and automotive refinish heritage. BASF SE represents the European integrated chemical archetype, with SE corporate structure signaling conglomerate-scale resin and formulation verticality. Kansai Nerolac Paints Limited exemplifies the Asia-Pacific relationship-driven model, with Limited suffix indicating concentrated ownership and Japanese-Korean OEM technical embedding.
| Leading Market Players |
|---|
| PPG Industries Inc |
| Akzo Nobel N.V. |
| BASF SE |
| Axalta Coating Systems |
| Kansai Nerolac Paints Limited |
| Nippon Paint Holdings Co., Ltd. |
| RPM International Inc |
| KCC Corporation |
| Sherwin-Williams Company |
| Others |
Supply Flow & Price Mechanics
Petrochemical resin costs feed through three distinct pricing tiers as urethane precursors from the Busan-Ulsan complex and acrylic monomers from German chemical parks determine formulation economics for tier-1 suppliers in Stuttgart, Wolfsburg, and Detroit-Windsor.
Pricing Analysis
Bundled coating-substrate packages command premiums against unbundled resin-procurement models where Magna and Faurecia specify performance standards independently. Three-tier pricing structure across premium, standard, and economy levels separates luxury OEM direct specifications from mass-market tier-1 procurement and aftermarket refinish channels. Price differentiation hinges on REACH compliance certification and volume scale, with mid-tier suppliers facing margin compression from petrochemical volatility. Tier-2 facilities in Jiangsu province exhibit highest price sensitivity due to waterborne conversion capital burdens.
Supply Chain Analysis
Single-source vulnerability sits with isocyanate monomer supply concentrated in Germany, China, and South Korea where BASF, Covestro, and KCC Corporation anchor global production. Formulation chemistry draws from aliphatic diisocyanates, polyester polyols, and acrylic resins as core inputs. Tariff exposure on Chinese-sourced resin feedstocks threatens margin stability at North American compounding facilities. Distribution runs through just-in-sequence delivery systems from tier-1 module plants to OEM assembly clusters in Munich, Stuttgart, and Wolfsburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH substance restrictions and EPA 40 CFR Part 59 enforcement create durable demand pull for compliant formulation development.
For Market Incumbents: To counter unbundling pressure from consolidated tier-1 procurement desks, PPG Industries and BASF SE should deepen captive resin supply through backward integration into aliphatic isocyanate production. BASF's Ludwigshafen complex offers template for integrated binder-coating verticality that reduces supply chain complexity for Faurecia and Forvia qualification programs. For New Entrants and Emerging Players: Waterborne acrylic stabilization expertise for battery-electric vehicle modules represents the most penetrable white-space target as BYD and NIO platforms expand in Jiangsu and Guangdong. Provincial MEE enforcement creates first-mover advantage for specialists establishing technical service centers in the Yangtze River Delta. Direct embedding with Yanfeng procurement teams accelerates OEM qualification timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional waterborne specialists with established MEE relationships because fragmented tier-2 coating applicators face equipment lock-in barriers to independent conversion. Long-term viability rests on formulation chemist retention and blocked-cure urethane patent positions. Watch for tier-1 supplier consolidation announcements as signal of procurement desk bargaining power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | BASF's captive isocyanate supply reduces tier-1 supplier qualification risk in REACH-regulated European markets. |
| Waterborne Technology Conversion | Provincial MEE enforcement in Jiangsu creates compliance-driven replacement demand for solvent-borne capacity. |
| In-Mold Coating Integration | Magna's Michigan facilities eliminate post-mold finishing steps through converged injection and surface processes. |
| Digital Color-Matching Platform Deployment | Cloud-based spectrophotometry compresses OEM approval cycles from weeks to days at PPG technical centers. |
| Geographic Relocation to Mexico | Tier-1 suppliers exploit regulatory arbitrage between EPA VOC constraints and Mexican enforcement gaps. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tier-1 supplier procurement directors, OEM platform engineers, coating formulation chemists, and aftermarket distribution managers with secondary validation against SEC 10-K filings, ACC and Cefic chemical industry reports, customs and trade data, and vehicle production databases from IHS Markit. Bottom-up resin demand modeling and top-down OEM coating specification analysis were triangulated for consistency.
Comparable-period anchoring linked historical formulation transitions to forward projection assumptions across the analysis window, with segmentation dimensions spanning polymer chemistry, application method, interior module category, and regional regulatory cluster. CAGRs were derived from installed capacity conversion timelines and tier-1 supplier capital expenditure patterns, incorporating EV platform launch schedules and MEE enforcement intensity as automotive-specific demand drivers.
The model holds under stable petrochemical feedstock availability and gradual regulatory harmonization; deviation in crude oil derivative volatility or abrupt REACH substance list expansion would shift formulation economics and capacity relocation decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Global Cabin Air Heater Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Pneumatic Seat System Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Overhead Console Market