
 Automotive Air Conditioning Market | 2026-2036
Automotive Air Conditioning Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Conditioning Market Intelligence
Software-defined climate control features are shifting the value proposition from hardware components to user experience and recurring revenue. This transition favors established Tier-1 suppliers with deep electronics integration capabilities. Denso Corporation leverages its extensive R&D in thermal systems and electronics to lead in integrated solutions. Valeo SA differentiates through its focus on cabin air quality and thermal comfort systems for electric vehicles.
Automotive air conditioning refers to the system that cools and dehumidifies a vehicle's cabin using a vapor-compression refrigeration cycle. These systems circulate a refrigerant, such as R-1234yf, to absorb and release heat, maintaining occupant comfort. Within the technology segment, electrically driven compressors are displacing belt-driven variants, a change essential for electric vehicle efficiency. Passenger vehicles continue to constitute the largest application, but the heavy-duty truck segment shows significant growth potential for advanced climate systems.
Regulatory frameworks are a primary market force, with the EU's F-Gas Regulation and the US EPA's SNAP program mandating transitions to low-GWP refrigerants. China's environmental standards also influence component design and material selection for its vast domestic market. Navigating the complex landscape of divergent global refrigerant standards while optimizing system architecture for electric vehicles remains a central challenge for all stakeholders.
Market Dynamics
The transition to electric vehicles, coupled with stringent global environmental regulations on refrigerants, represents the central structural force shaping the automotive air conditioning market. This dual pressure compels innovation in both system architecture and component technology, favoring integrated solutions.
Growth Catalysts
- EV Proliferation:The rapid expansion of the electric vehicle market necessitates advanced thermal management systems to cool both the cabin and the battery pack, creating new demand for efficient electric compressors and heat pumps.
- Regulatory Mandates:The EU's F-Gas Regulation and similar policies in other regions are compelling automakers to adopt low-GWP refrigerants, driving investment in new system components and designs.
- Passenger Comfort:Rising consumer expectations for cabin comfort and air quality, particularly in premium and mid-range vehicle segments, support the adoption of more sophisticated, multi-zone climate control systems.
Market Restraints
- Component Cost:The higher cost of low-GWP refrigerants like R-1234yf and the associated specialized components, such as internal heat exchangers, increases overall system and vehicle manufacturing expenses.
- System Complexity:Integrating HVAC systems with battery thermal management in electric vehicles introduces significant engineering complexity, impacting development timelines and requiring extensive validation.
- Service Infrastructure:The aftermarket service and repair network requires significant investment in new equipment and technician training to handle next-generation refrigerants and high-voltage electric compressors safely.
Strategic Opportunities
- Integrated Thermal Modules:There is a significant opportunity for suppliers to offer complete, pre-validated thermal management modules that combine battery cooling, cabin climate control, and power electronics cooling into a single unit.
- Heavy-Duty Electrification:The emerging electric and hydrogen fuel cell truck segments require robust, high-capacity thermal systems, opening a new high-value application area for specialized climate control solutions.
- Air Quality Systems:Advanced filtration, purification, and sensor technologies that monitor and improve in-cabin air quality represent a key area for product differentiation and value creation.
Industry Challenges
- Divergent Standards:Manufacturers face the challenge of designing and validating systems that comply with a patchwork of different refrigerant regulations and safety standards across North America, Europe, and Asia.
- Software Integration:Ensuring seamless integration of climate control software with the vehicle's core operating system and over-the-air update architecture presents a significant software engineering hurdle.
- Supply Chain Volatility:The supply of critical semiconductor components for electronic controllers and sensors remains a persistent operational challenge for system manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Conditioning Market |
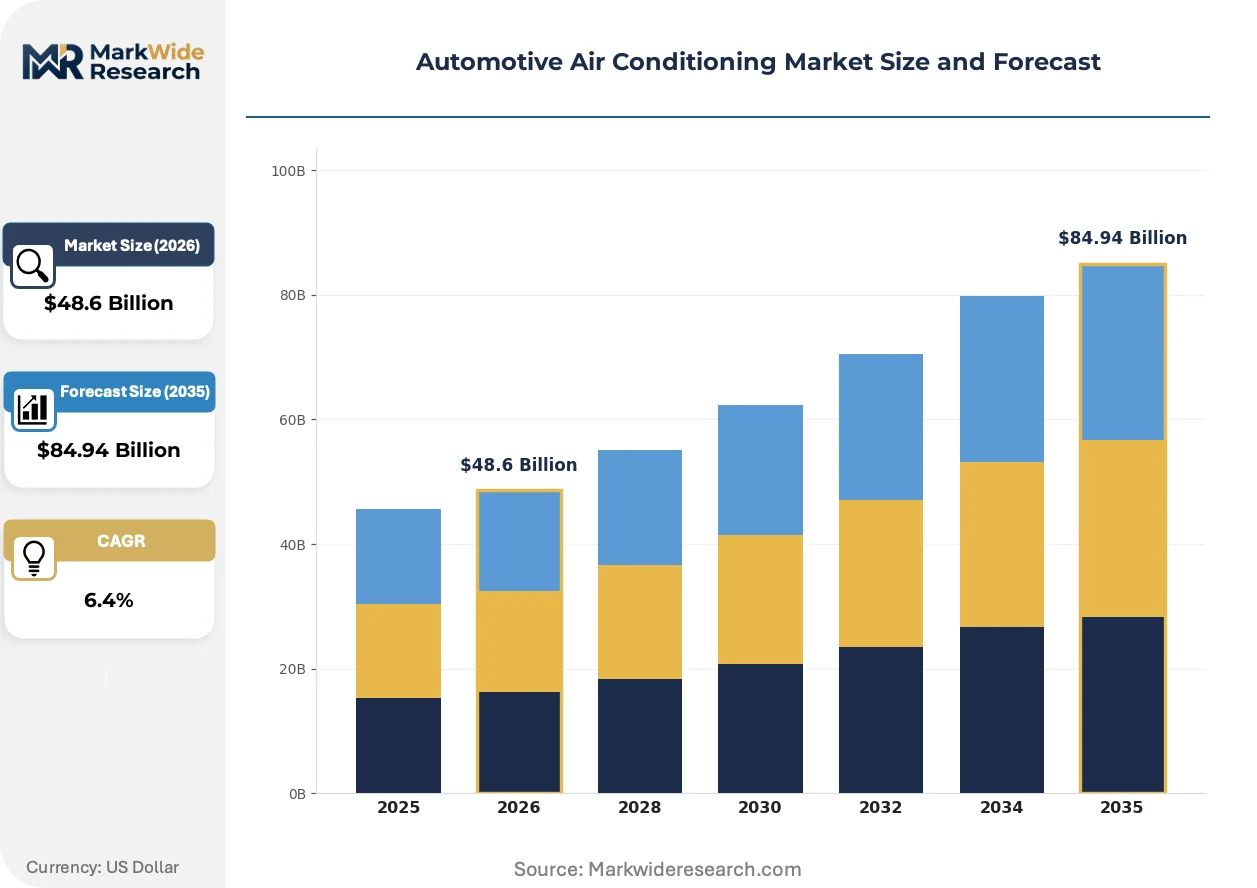
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressor, Condenser, Evaporator, Expansion Valve, Receiver Drier Technology: Electrically Driven, Belt Driven, Variable Displacement, Scroll, Rotary Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Heavy Duty Trucks, Specialty Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Fleet Operators, Maintenance Workshops |
| Companies Covered | Denso Corporation, Valeo SA, MAHLE GmbH, Hanon Systems, Sanden Holdings Corporation, Calsonic Kansei Corporation, Keihin Corporation, Mitsubishi Heavy Industries Ltd., Brose Fahrzeugteile GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Conditioning Market Strategic Shifts & Innovations
A fundamental shift from discrete mechanical components to intelligent, software-defined thermal ecosystems is underway. This evolution prioritizes energy efficiency for electric vehicles and enhances user experience through integrated cabin environment control.
Electrically driven compressors are replacing traditional belt-driven types, allowing them to operate independently of the internal combustion engine. The electric vehicle segment is universally adopting this technology to minimize parasitic losses on the battery. This change is absorbing the function and value previously held by engine-dependent mechanical components into the vehicle's high-voltage electrical architecture.
Regulatory mandates, led by the EU's F-Gas Regulation and the US EPA's SNAP program, are forcing the phase-out of high-GWP refrigerants. This directly impacts component design, as systems must be re-engineered for the different operating pressures and material compatibility of alternatives like R-1234yf. The passenger car segment faces the most immediate compliance pressure.
Automakers are increasingly specifying pre-integrated thermal management modules instead of sourcing individual components like compressors and heat exchangers separately. This procurement model favors large Tier-1 suppliers capable of delivering a full system, disrupting the business of smaller, component-focused manufacturers. The trend is most visible within China's fast-paced EV development cycles.
Automotive Air Conditioning Market Segmentation
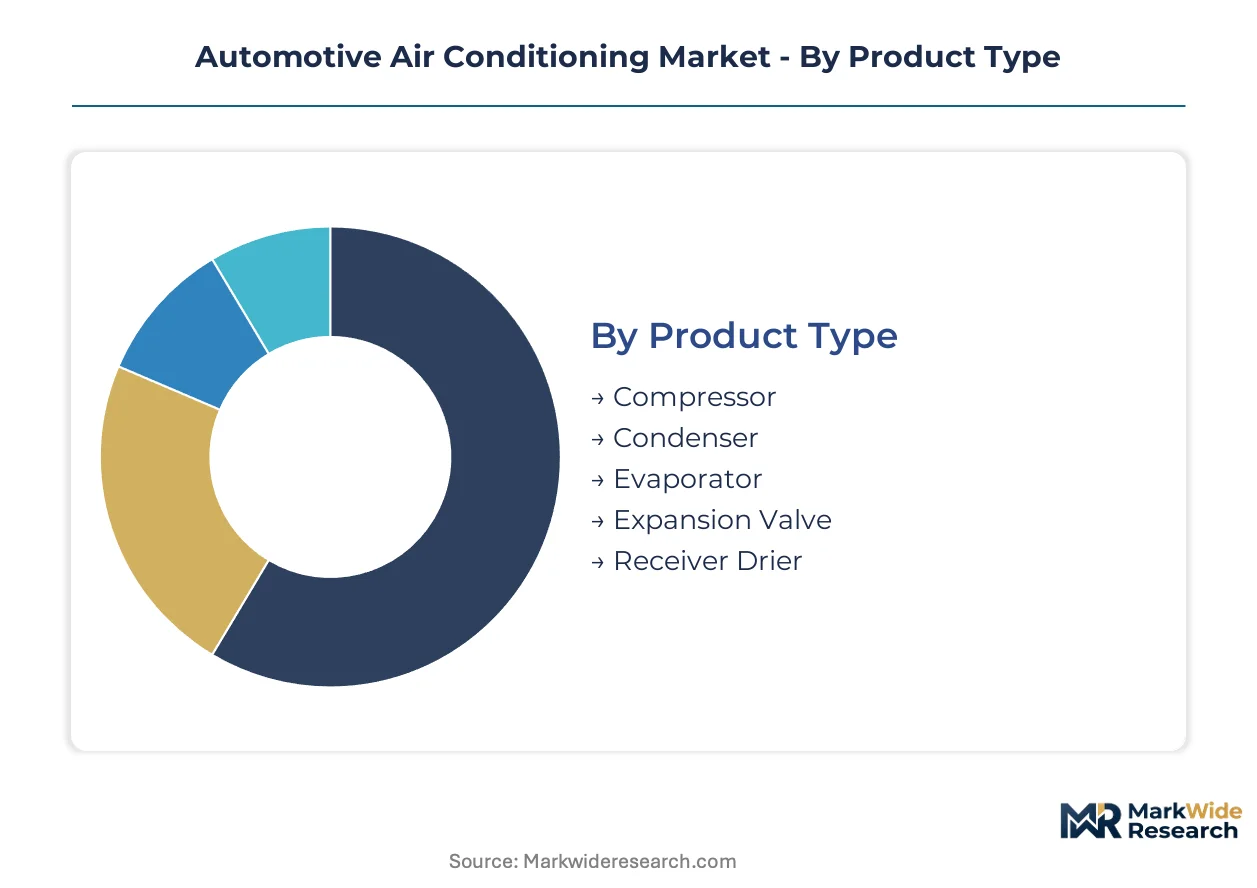
The automotive air conditioning market segmentation clarifies distinct demand patterns and technological trajectories across various product types, technologies, applications, and end-user groups. Understanding these divisions is essential for stakeholders to align product development and market strategies with evolving industry requirements and regulatory pressures.
Product Type:
Compliance with diverse global standards imposes specific certification burdens on different air conditioning components.
- Compressor:These critical components generate the necessary pressure difference for refrigerant circulation, driving the vapor-compression cycle. Electrically driven compressors require rigorous ISO 26262 functional safety certifications for integration into high-voltage electric vehicle architectures.
- Condenser:The condenser dissipates heat from the refrigerant to the ambient air, a crucial step in the cooling process. Condensers must meet material compatibility and pressure resistance standards for new low-GWP refrigerants, often necessitating specific EU F-Gas Regulation compliance.
- Evaporator:The evaporator absorbs heat from the cabin air, facilitating cooling and dehumidification. This component needs to ensure efficient heat transfer and robust material integrity.
- Expansion Valve:This device controls the flow of refrigerant into the evaporator, regulating the system's cooling capacity. Precision engineering is vital for optimal performance.
- Receiver Drier:The receiver drier stores excess liquid refrigerant and removes moisture and contaminants from the system. It is crucial for maintaining refrigerant purity and system longevity.
The compressor sits at the top of the volume ranking, with the expansion valve climbing the fastest.
Technology:
The operational mechanism dictates system integration and vehicle energy consumption profiles across different powertrain types.
- Electrically Driven:These compressors operate independently of the engine, powered by the vehicle's electrical system. Demand is concentrating within the electric vehicle segment due to efficiency requirements and battery thermal management needs.
- Belt Driven:Traditional belt-driven compressors derive power directly from the internal combustion engine via a serpentine belt. This technology remains prevalent in conventional gasoline and diesel vehicles, offering a cost-effective solution for established powertrains.
- Variable Displacement:This technology allows the compressor to adjust its cooling capacity based on demand, enhancing fuel efficiency and occupant comfort. It is widely adopted in modern passenger vehicles.
- Scroll:Scroll compressors utilize two interleaved spiral-shaped scrolls to compress refrigerant, known for their smooth operation and high efficiency. This design is gaining traction in various automotive applications.
- Rotary:Rotary compressors use a rotating shaft and vanes to compress refrigerant, offering a compact design suitable for space-constrained vehicle layouts. They provide reliable performance in diverse climate conditions.
Electrically driven technology is gaining significant traction, while belt-driven solutions remain foundational for legacy systems.
Application:
Specific vehicle types drive distinct requirements for thermal management system capacity, integration, and performance.
- Passenger Vehicles:This segment encompasses cars, SUVs, and vans, representing the largest application area for automotive air conditioning systems. Consumer demand for comfort and advanced climate control features influences product innovation.
- Commercial Vehicles:This category includes light and medium-duty trucks, buses, and delivery vans, where robust and reliable air conditioning systems are essential for driver comfort and operational efficiency. Demand is accelerating in urban logistics fleets.
- Electric Vehicles:EVs require integrated thermal management for both the cabin and the battery pack, necessitating highly efficient electric compressors and heat pump systems. This application area requires sophisticated control software.
- Heavy Duty Trucks:These vehicles operate over long distances and often in extreme conditions, demanding high-capacity and durable climate control solutions. Driver comfort is a key factor for retention and productivity.
- Specialty Vehicles:This segment includes off-road vehicles, agricultural machinery, construction equipment, and emergency vehicles. These applications require customized and rugged air conditioning systems designed for harsh environments.
The passenger vehicle segment generates the largest revenue, with electric vehicles showing significant expansion.
End User:
The customer type influences procurement channels, service needs, and the demand for original equipment versus aftermarket components.
- OEMs:Original Equipment Manufacturers integrate air conditioning systems directly into new vehicle production lines, demanding high-volume supply and precise specification adherence. Procurement patterns concentrate among large Tier-1 suppliers with global manufacturing footprints.
- Aftermarket Suppliers:These entities provide replacement parts and components for vehicle repair and maintenance, requiring broad product catalogues and efficient distribution networks. Demand is driven by vehicle longevity and the need for system upkeep.
- Vehicle Assemblers:These companies assemble vehicles from components sourced from various suppliers, requiring reliable and timely delivery of air conditioning systems. Their operations often involve just-in-time inventory management.
- Fleet Operators:Businesses managing large fleets of vehicles prioritize durability, ease of maintenance, and energy efficiency in their air conditioning systems. Cost of ownership is a primary consideration.
- Maintenance Workshops:These service providers perform diagnostics, repairs, and refrigerant recharging for existing vehicle air conditioning systems. They require access to specialized tools, refrigerants, and replacement components.
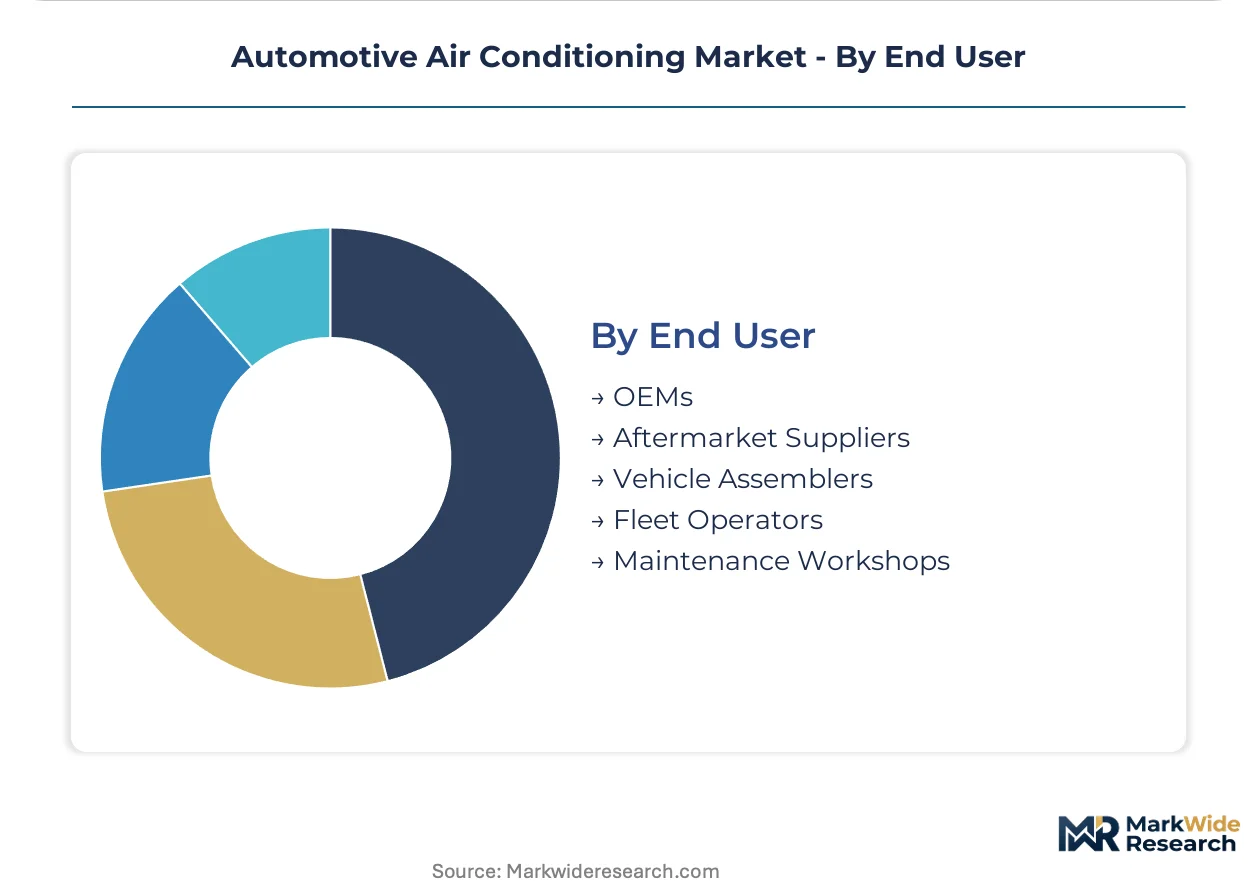
OEMs drive the initial system demand, while aftermarket channels ensure long-term serviceability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China's automotive air conditioning market experiences rapid expansion driven by electric vehicle integration, the German market emphasizes advanced thermal management for premium vehicle segments. This difference highlights distinct regional priorities in technology adoption and regulatory compliance.
China
China's electric vehicle proliferation drives significant demand for advanced thermal management systems, including electric compressors and heat pumps. The country's dual carbon goals and environmental standards influence component design and material selection. The Yangtze River Delta region, particularly around Shanghai, sees intense innovation and manufacturing in EV thermal solutions.
Germany
Germany's automotive sector focuses on high-performance and premium vehicles, necessitating sophisticated multi-zone climate control systems. The EU's F-Gas Regulation mandates the transition to low-GWP refrigerants like R-1234yf, impacting system architecture. The Stuttgart region, home to major automakers, serves as a hub for thermal system research and development.
United States
The United States passenger vehicle market remains substantial, while the heavy-duty truck segment shows increasing demand for advanced climate systems, especially with electrification. The US EPA's SNAP program guides the adoption of alternative refrigerants and energy-efficient technologies. Detroit, Michigan, continues as a central point for automotive technology integration and supply chain coordination.
Japan
Japan's automotive industry, known for its hybrid vehicle leadership, requires efficient thermal management solutions that balance fuel economy and occupant comfort. Initiatives from METI promote energy efficiency and sustainable manufacturing practices within the automotive supply chain. The Nagoya area, a major automotive manufacturing cluster, concentrates on advanced component development.
India
India's growing passenger vehicle sales and rising consumer expectations for cabin comfort fuel demand for reliable and cost-effective air conditioning systems. The Bureau of Indian Standards (BIS) establishes quality and safety benchmarks for automotive components. Chennai, a prominent automotive manufacturing hub, observes expansion in local component production.
Automotive Air Conditioning Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with Tier-1 suppliers dominating the OEM channel. The market structure exhibits a tiered consolidation, favoring companies with extensive R&D capabilities and global manufacturing footprints. Strategic archetypes include integrated thermal system providers, specialized component manufacturers, and emerging software-defined climate control innovators. Dominant competitive moves involve strategic partnerships for technology co-development and capacity expansion to meet EV demand.
Leading Tier-1 suppliers like Denso Corporation and Valeo SA exemplify integrated thermal management solutions, leveraging their deep electronics integration capabilities. Germany-based MAHLE GmbH also occupies a significant position, particularly through its focus on advanced thermal systems for electric vehicles. These companies anchor the market through comprehensive product portfolios and established relationships with global automakers.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| MAHLE GmbH |
| Hanon Systems |
| Sanden Holdings Corporation |
| Calsonic Kansei Corporation |
| Keihin Corporation |
| Mitsubishi Heavy Industries Ltd. |
| Brose Fahrzeugteile GmbH & Co. KG |
Cost & Logistics Intelligence
The EU's F-Gas Regulation, a named environmental mandate, gates qualified supply for low-GWP refrigerants and premium-tier pricing access for compliant systems. This regulatory pressure directly influences both component costs and market entry barriers for suppliers. Supply concentration also shapes pricing power for integrated thermal management solutions.
Pricing Analysis
Capacity additions in China are reshaping price floors for core automotive air conditioning components, especially for electric compressors. The dominant pricing model is contract-based long-term offtake for OEMs, with tiered premium-mid-economy pricing differentiation in the aftermarket. Price differentiation stems from certification level for low-GWP refrigerants and the integration complexity of thermal modules. Pricing pressure stems from the high cost of new refrigerants and the demand for energy-efficient EV systems. The aftermarket segment exhibits higher price sensitivity compared to OEM procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, while aftermarket distributors manage replacement parts. Geographic supply concentration for automotive air conditioning components centers on China, Germany, and Japan. The supply chain draws from critical raw materials like R-1234yf refrigerant and advanced semiconductors for electronic controls. Semiconductor supply chain volatility represents a structural risk. Distribution runs through established Tier-1 suppliers directly to vehicle assembly plants and independent aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
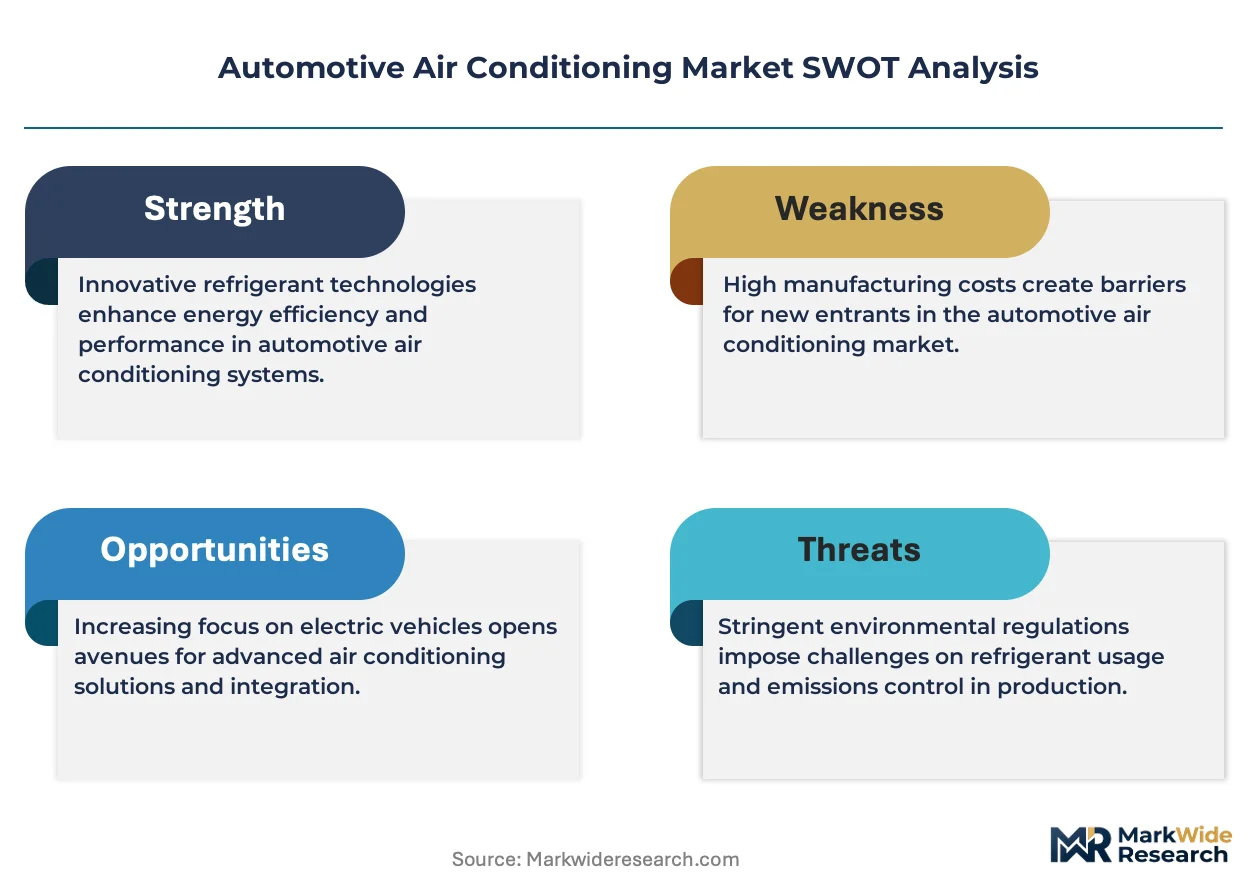
The automotive air conditioning market presents a geographic-arbitrage play, leveraging China's manufacturing scale against Europe's stringent regulatory compliance costs. This cost differential creates distinct strategic pathways for market participants.
For Market Incumbents:Extend R&D investments into advanced thermal management systems for electric vehicles, focusing on integrated modules. Deepen electronics integration capabilities to support software-defined climate control features, mitigating the threat from emerging software innovators. Form strategic partnerships for technology co-development, particularly for next-generation refrigerants and high-voltage components. Expand manufacturing capacity in key EV production hubs like China to capture volume growth.
For New Entrants and Emerging Players:Fleet operators in the heavy-duty electric truck segment represent an underserved buyer archetype with significant growth potential. Target specialized vehicle air quality systems and robust climate control solutions for off-road machinery. The most penetrable segment is advanced thermal management for niche electric commercial vehicles. A strong go-to-market angle centers on offering superior energy efficiency and enhanced cabin comfort for these demanding applications.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized component manufacturers with proven expertise in low-GWP refrigerant systems or power electronics for thermal management. The long-term viability for this market spans a 5-10 year window, driven by electric vehicle proliferation and evolving regulatory mandates. Acquire firms with strong intellectual property in heat pump technology or integrated thermal module design. Accelerated adoption of integrated thermal modules by new EV platforms is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization for EV Thermal Systems | Standardization reduces development costs and accelerates market entry for new electric vehicle models. |
| Low-GWP Refrigerant Technology Licensing | Licensing accelerates global compliance and provides access to critical refrigerant alternatives. |
| Integrated Thermal Module Development | Developing integrated modules offers OEMs a streamlined, energy-efficient solution for complex EV thermal needs. |
| Software-Defined Climate Control Investment | Investment in software enhances user experience and enables over-the-air updates for climate control functionalities. |
| Aftermarket Service Network Expansion | Expanding service networks ensures long-term support for new refrigerant systems and high-voltage components. |
Research Approach
Coverage spans China, Germany, United States, Japan, and India, with primary inputs from each key automotive manufacturing region. Primary research included in-depth interviews with Tier-1 supplier executives, OEM procurement leads, automotive engineers, and aftermarket distributors. This primary data was rigorously validated against secondary sources such as vehicle production databases, environmental agency reports, industry association publications, and financial disclosures. The analysis employed both bottom-up market sizing and top-down validation approaches.
Granular modeling incorporated data points across product type, technology, application, end-user, and regional levels throughout the forecast period. Key segmentation dimensions included compressor type, refrigerant generation, vehicle powertrain, and the OEM versus aftermarket channels. Compound annual growth rates were derived from historical data, expert interviews, and relevant macroeconomic indicators. Industry-specific forecast inputs included electric vehicle adoption rates and regulatory compliance timelines.
Underlying measurement precision varies by segment; passenger vehicle and OEM segments carry tighter precision than others, reflecting data availability. Forecasts reflect assumptions concerning EV market growth trajectories and refrigerant cost fluctuations. Supply chain disruptions or unforeseen regulatory changes represent specific risk factors that could revise forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market