
 Global Automotive Anti Vibration Mounting Market | 2026-2036
Global Automotive Anti Vibration Mounting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Anti Vibration Mounting Market Intelligence
Expertise in computational fluid dynamics and multi-physics simulation for NVH analysis is reorganizing competitive dynamics among component suppliers. Vibracoustic GmbH leverages its deep specialization in elastomeric solutions to address complex vibration challenges in both internal combustion and electric powertrains. Continental AG sustains its market position through extensive R&D investments and a broad portfolio spanning multiple mounting technologies, including advanced hydro-pneumatic systems.
Automotive anti-vibration mountings are engineered components designed to isolate and dampen vibrations originating from the engine, drivetrain, and road surface. These devices, often using a combination of rubber and metal, absorb kinetic energy to improve vehicle comfort, reduce noise, and enhance the durability of other components. Hydraulic mounts and advanced elastomeric technologies command higher margins, particularly for applications in the engine compartment and suspension systems. While the aftermarket suppliers segment provides volume, sales directly to vehicle assemblers for new platforms represent the primary value pool.
Vehicle noise regulations set by bodies like the US EPA and standards under the EU's vehicle type-approval system directly influence mounting performance requirements. Concurrently, China's GB standards for vehicle manufacturing and material composition rules like the EU's REACH directive govern the materials used in these components. Component manufacturers must now balance the conflicting demands of lightweighting for efficiency with the increased complexity of NVH management in electric and hybrid vehicles.
Market Dynamics
The fundamental shift from internal combustion engines to electric vehicle architectures is the central force reshaping the automotive anti-vibration mounting market. This transition alters the entire noise, vibration, and harshness profile, demanding new material science and component designs for effective isolation.
Growth Catalysts
- Stringent NVH Regulations:Vehicle noise standards, such as those under the EU's vehicle type-approval system, compel manufacturers to adopt more advanced mounting solutions to meet comfort and environmental targets, especially for quieter electric vehicles.
- Advanced Elastomer Development:Innovations in composite and elastomeric compounds enable the creation of lighter, more durable mounts that can handle the unique high-frequency vibration challenges of electric vehicle powertrains and battery systems.
- Electric Vehicle Platform Proliferation:The rising number of dedicated electric vehicle platforms from global assemblers in China, Germany, and the United States creates a direct demand stream for specialized mounts designed for battery packs and electric drive units.
Market Restraints
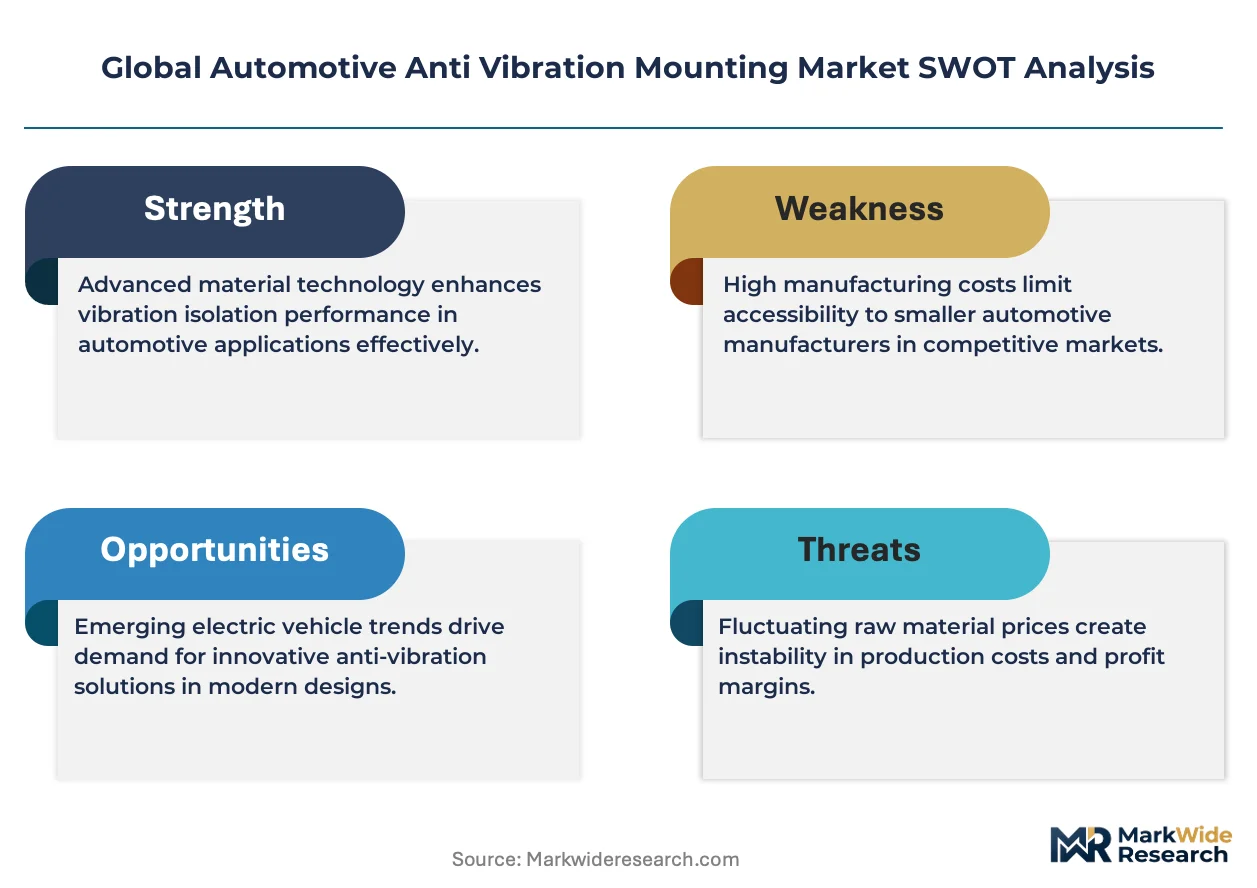
- Raw Material Price Volatility:Fluctuations in the cost of advanced elastomeric compounds and specialized metals create significant margin pressure for component suppliers, complicating pricing for long-term contracts with vehicle assemblers.
- Conflicting Design Requirements:The need to balance lightweighting for vehicle efficiency against the increased mass and complexity required for effective NVH management in EVs presents a persistent engineering and cost challenge.
- Integration into Sub-Assemblies:A long-term substitution threat involves the integration of vibration damping functions directly into chassis or powertrain structures, potentially reducing the need for discrete mounting components in future vehicle designs.
Strategic Opportunities
- Battery Pack and E-Motor Isolation:A significant opportunity exists in developing specialized mounts for isolating high-frequency vibrations from electric motors and securing large, heavy battery packs within the chassis of electric vehicles.
- Advanced Hydro-Pneumatic Systems:Expanding the application of active and semi-active hydro-pneumatic mounts from premium vehicles to mainstream segments offers a path to capture higher value and provide significant performance differentiation.
- Aftermarket Growth in China:Servicing the large and aging vehicle parc in China with higher-performance aftermarket mounts represents a substantial volume opportunity outside of direct sales to original equipment manufacturers.
Industry Challenges
- Simulation Expertise Scarcity:A shortage of engineers skilled in multi-physics simulation and computational fluid dynamics for NVH analysis hinders the product development speed of smaller component suppliers trying to compete for new platform contracts.
- Complex Material Compliance:Navigating intricate and evolving material composition rules, such as the EU's REACH directive, requires significant investment in testing, supply chain verification, and documentation, adding administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Anti Vibration Mounting Market |
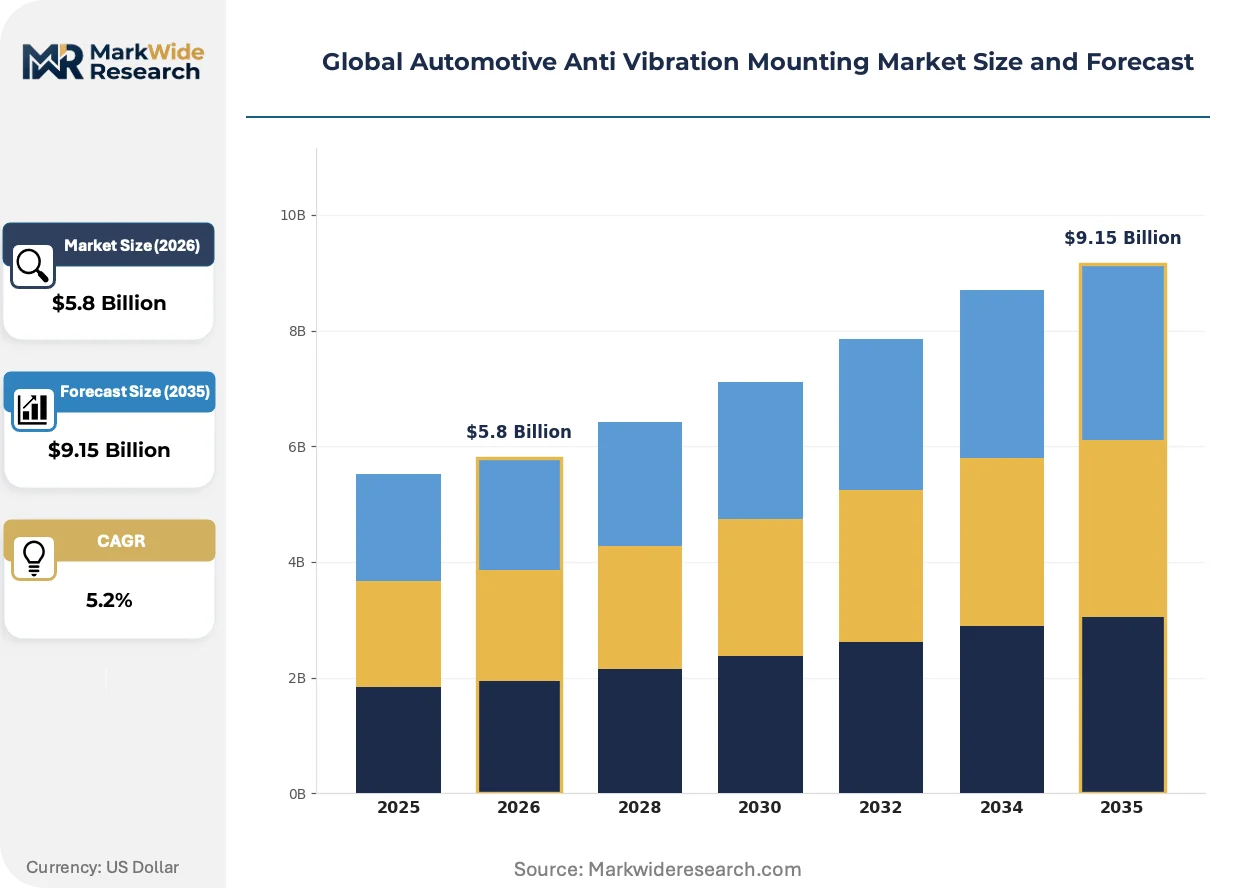
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.15 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Mounts, Metal Bushings, Hydraulic Mounts, Spring Mounts Technology: Elastomeric, Hydro-Pneumatic, Electromagnetic, Composite Application: Engine Compartment, Exhaust Systems, Transmission Assemblies, Suspension Systems End User: Vehicle Assemblers, Aftermarket Suppliers, Tier-1 Component Makers, Dealerships |
| Companies Covered | Continental AG, Schaeffler AG, Trelleborg AB, Hutchinson SA, Vibracoustic GmbH, Sumitomo Riko Company Limited, ContiTech, LORD Corporation, Boge Rubber & Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Anti Vibration Mounting Market Strategic Shifts & Innovations
Component intelligence and material science are converging to redefine vibration management. The industry's focus is shifting from passive dampening to active isolation, a change driven by the distinct NVH characteristics of electric and hybrid vehicles that require more sophisticated solutions.
Active and semi-active mounting systems integrate sensors and actuators to counteract vibrations in real-time. Luxury vehicle manufacturers and premium EV brands are the primary adopters, seeking superior cabin refinement and ride comfort. This integration of electronics and hydraulics into a single component is miniaturizing the control systems, making them increasingly viable for broader platform applications beyond the premium segment.
China's GB standards for vehicle manufacturing are becoming increasingly stringent regarding interior noise and vibration levels. This directly influences design choices for both domestic Chinese automakers and global brands manufacturing within the country. Component suppliers must now validate mount performance against these specific national standards, impacting material selection and testing protocols for the world's largest automotive market.
Vehicle assemblers are moving toward sourcing complete NVH sub-systems rather than purchasing individual mounting components. This shift favors larger, more technologically advanced suppliers who can offer integrated design, simulation, and validation services as a package. The trend is most pronounced in North America and Europe, where EV startups and legacy OEMs alike seek to outsource NVH complexity and shorten development cycles.
Global Automotive Anti Vibration Mounting Market Segmentation
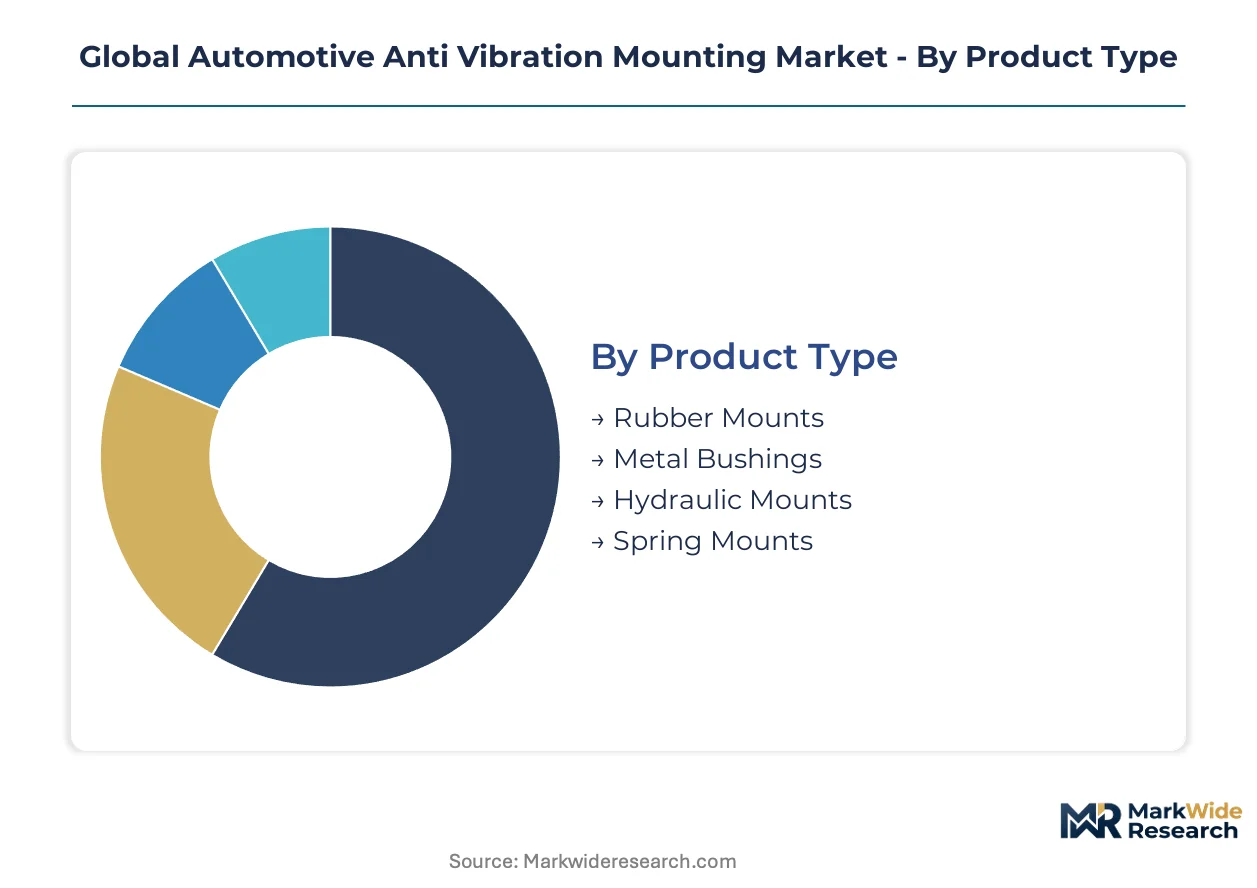
This market's segmentation highlights the distinct engineering requirements across vehicle platforms and end-use environments. Understanding these categories reveals where specialized material science and advanced damping technologies are most critical for performance and comfort. It also clarifies the varying supply chain dynamics that govern component procurement.
Product Type:
The product type segmentation reveals how different mounting solutions are deployed across diverse global manufacturing footprints, with some types favoring domestic production for cost efficiency while others are geared for export-led advanced vehicle platforms.
- Hydraulic Mounts:These components integrate fluid-filled chambers to provide superior damping characteristics, particularly effective against low-frequency vibrations. Demand concentrates in premium vehicle platforms manufactured in Germany and the US, where stringent NVH standards drive the adoption of sophisticated comfort solutions.
- Rubber Mounts:Comprising elastomeric compounds, these mounts offer cost-effective vibration isolation through material deformation and energy absorption. Their widespread use across China's and India's automotive manufacturing hubs reflects their versatility and suitability for a broad range of vehicle types.
- Metal Bushings:These rigid components primarily manage structural alignment and some high-frequency noise, finding application in less critical areas of the chassis.
- Spring Mounts:Utilizing coiled or leaf springs, these mounts provide basic vibration isolation, often in heavy-duty or specialized industrial vehicle applications.
Rubber Mounts command the established base. The steepest expansion runs through Hydraulic Mounts.
Technology:
Technological differentiation within anti-vibration mountings directly correlates with the specific performance requirements of various vehicle systems, from basic isolation to active vibration cancellation.
- Hydro-Pneumatic:These systems combine fluid and gas elements to deliver variable stiffness and damping, adapting to changing road conditions and engine loads. Premium vehicle manufacturers in Europe and North America increasingly adopt these for enhanced ride comfort and dynamic performance.
- Elastomeric:Utilizing advanced rubber and polymer blends, these technologies provide passive vibration absorption and noise reduction across a wide frequency range. Their cost-effectiveness and durability make them fundamental for engine and suspension mounts in mass-market vehicles globally.
- Electromagnetic:Active systems employing magnetic fields to generate counter-forces, primarily found in luxury vehicles for superior real-time vibration cancellation.
- Composite:Lightweight designs integrating multiple materials like plastics and fibers to optimize strength-to-weight ratios for electric vehicle battery pack isolation.
Elastomeric and Composite technologies are foundational for current and future vehicle platforms. Hydro-Pneumatic and Electromagnetic systems offer specialized solutions for high-performance applications.
Application:
Application-specific mountings demonstrate varied margin profiles, reflecting the complexity of engineering and the criticality of performance in different vehicle zones.
- Engine Compartment:Mounts here manage significant low-frequency vibrations and high temperatures from the engine, requiring robust designs and specialized elastomeric compounds. Demand remains strong in internal combustion engine vehicle production across Asian and European markets, prioritizing durability.
- Suspension Systems:These components isolate road noise and impacts, directly influencing ride comfort and vehicle handling dynamics. Their performance is crucial for luxury and electric vehicles in Germany and the US, where consumer expectations for cabin refinement are exceptionally high.
- Exhaust Systems:Designed to dampen vibrations and thermal expansion from the exhaust line, these mounts prevent rattling and structural fatigue.
- Transmission Assemblies:These mounts absorb torque reactions and gear whine, crucial for smooth power delivery and reducing cabin noise in both ICE and EV powertrains.
Engine Compartment and Suspension Systems applications represent the highest value segments. Exhaust Systems and Transmission Assemblies provide essential support functions.
End User:
End-user categories delineate distinct purchasing behaviors and supply chain relationships, from direct OEM partnerships to broader retail channels.
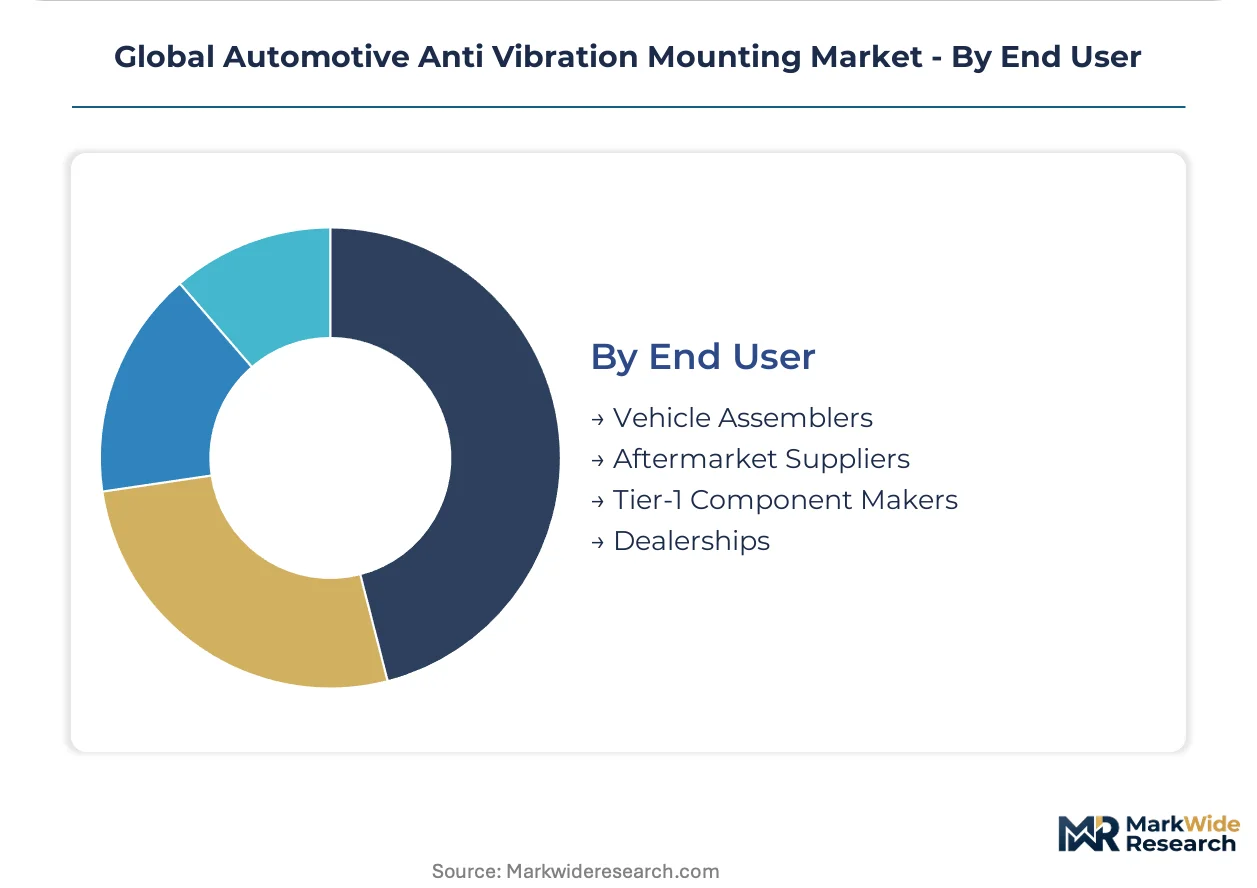
- Vehicle Assemblers:These entities represent the primary value pool for new platform development, demanding custom-engineered solutions and long-term supply contracts. Major automotive OEMs in China, Germany, and the United States drive significant procurement volumes for their production lines.
- Aftermarket Suppliers:This segment provides replacement parts for existing vehicles, focusing on broad compatibility and competitive pricing for maintenance and repair operations. The large and aging vehicle parc in China offers a substantial volume opportunity for these suppliers.
- Tier-1 Component Makers:These suppliers often integrate anti-vibration mounts into larger sub-assemblies before delivering to vehicle assemblers, requiring close collaboration.
- Dealerships:As retail points for vehicle sales and service, dealerships source mounts for warranty repairs and direct customer service, often through OEM-approved channels.
Vehicle Assemblers are central to initial product integration. Aftermarket Suppliers are crucial for long-term vehicle maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EPA, along with other environmental regulators, influences automotive anti-vibration mounting performance requirements across key manufacturing regions. Regional demand for advanced mounts reflects local production volumes and specific regulatory frameworks. China, Germany, and the United States remain central to global automotive production and technological advancement in NVH solutions.
United States
Demand for advanced anti-vibration mountings in the United States stems from the rapid expansion of electric vehicle manufacturing and luxury automotive production. NHTSA safety standards and state-level emissions regulations drive innovation in lightweight and durable components. Major automotive clusters in Michigan, California, and the Southern states are significant procurement hubs for specialized NVH solutions.
Germany
German automotive production, particularly in premium and luxury segments, requires sophisticated anti-vibration mounts for superior ride comfort and noise reduction. The EU's vehicle type-approval system mandates stringent NVH performance, pushing suppliers towards hydro-pneumatic and active systems. Bavaria and Baden-Württemberg, home to leading OEMs, concentrate significant R&D and manufacturing activities for these components.
China
China's automotive market, the world's largest, generates substantial demand for anti-vibration mountings driven by both domestic and international brands. GB standards for vehicle manufacturing increasingly focus on interior noise and vibration levels, influencing material selection and design. Major automotive production bases in the Yangtze River Delta and Pearl River Delta regions are critical for volume and technology adoption.
Japan
Japanese automotive manufacturers prioritize precision engineering and long-term durability in their anti-vibration mounting solutions for both domestic and export markets. METI industrial policies encourage technological advancements in lightweight materials and efficient manufacturing processes. Automotive manufacturing hubs in Aichi Prefecture and the Kanto region are key centers for component development and supply.
India
India's automotive sector, characterized by high-volume production of mass-market vehicles, drives demand for cost-effective and robust anti-vibration mounts. BIS standards for component quality and vehicle safety shape design and material choices for local production. Major automotive clusters around Chennai, Pune, and Gurugram serve as primary manufacturing and procurement centers for these essential components.
Global Automotive Anti Vibration Mounting Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive dynamics in the automotive anti-vibration mounting market. The industry structure reflects a tiered landscape, with large, diversified suppliers competing alongside specialized niche players. Strategic archetypes include full-service NVH solution providers and material science innovators. Dominant competitive moves involve extensive R&D investments and strategic partnerships with vehicle assemblers.
On the premium-tier vector, Continental AG and Vibracoustic GmbH exemplify suppliers offering comprehensive portfolios and deep engineering expertise. Continental AG sustains its market position through broad R&D and multiple mounting technologies, including hydro-pneumatic systems. Vibracoustic GmbH leverages its deep specialization in elastomeric solutions for complex vibration challenges in various powertrains. Sumitomo Riko Company Limited, a Japan-based industrial firm, anchors a position as a key supplier of rubber and resin products, including anti-vibration components for global automotive platforms.
| Leading Market Players |
|---|
| Continental AG |
| Schaeffler AG |
| Trelleborg AB |
| Hutchinson SA |
| Vibracoustic GmbH |
| Sumitomo Riko Company Limited |
| ContiTech |
| LORD Corporation |
| Boge Rubber & Plastics |
| Others |
Cost & Logistics Intelligence
The EU's REACH directive gates supply qualification for elastomeric compounds and specialized metals, simultaneously influencing price differentiation for compliant anti-vibration mountings. This regulatory framework necessitates rigorous testing and documentation, adding costs that premium suppliers can absorb more readily.
Pricing Analysis
Pricing for automotive anti-vibration mountings exhibits a significant geographic spread, with higher costs in regions demanding advanced NVH solutions like Germany and the United States. The dominant pricing model involves long-term, contract-based agreements directly with vehicle assemblers for new platforms. Price differentiation stems from the quality grade of NVH performance and the customization level required for specific vehicle architectures. Raw material price volatility, particularly for advanced elastomers, creates persistent margin pressure for component suppliers. Aftermarket suppliers typically demonstrate the highest price sensitivity, while premium EV manufacturers prioritize performance over cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate the supply chain for automotive anti-vibration mountings, particularly for OEM production lines, minimizing holding costs. Geographic supply concentration centers in China, Germany, and Japan, reflecting major automotive manufacturing hubs. The supply chain relies heavily on advanced elastomeric compounds and specialized metals as critical raw material inputs. Raw material price volatility represents a significant structural risk, impacting profitability and long-term contract stability. Distribution runs primarily direct to vehicle assemblers for new platforms, while aftermarket parts flow through broader wholesale and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive anti-vibration mounting market is undergoing a platform-economics inflection, driven by the emergence of dedicated electric vehicle architectures and integrated NVH sub-systems.
For Market Incumbents: Shield core market share by deepening vertical integration into advanced material science for next-generation elastomers. Invest heavily in multi-physics simulation expertise to address the complex NVH profiles of electric powertrains, mitigating the threat from niche specialists. Secure long-term supply contracts with leading EV platform developers in China and Europe. Expand active and semi-active mounting system portfolios to maintain competitive differentiation in premium segments.
For New Entrants and Emerging Players: Differentiate on specialized solutions for battery pack and e-motor isolation, targeting the high-frequency vibration challenges unique to EVs. The aftermarket segment in China, with its substantial aging vehicle parc, offers a penetrable volume opportunity for cost-effective, performance-upgraded mounts. Focus go-to-market strategies on agile design cycles and rapid prototyping for EV startups seeking quick development timelines. Develop expertise in composite materials for lightweighting without compromising damping capabilities.
For Investors and Strategic Acquirers: Tightening global NVH regulations like the EU's vehicle type-approval system reshapes the acquisition landscape, favoring companies with proven compliance capabilities. Long-term viability rests on identifying targets with deep specialization in active NVH technologies or proprietary advanced elastomeric compounds. Acquisition targets should possess strong R&D pipelines for next-generation EV platforms. A key signal to watch is the increasing outsourcing of complete NVH sub-systems by vehicle assemblers, indicating a shift towards integrated solution providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Multi-Physics Simulation | Enhances design accuracy for complex EV NVH challenges and shortens development cycles for OEMs. |
| Develop Advanced Elastomeric Compounds | Enables lighter, more durable mounts tailored for electric vehicle specific vibration frequencies. |
| Expand Active Mounting Systems | Offers superior real-time vibration cancellation, improving cabin comfort in premium and EV segments. |
| Secure Long-term OEM Contracts | Provides stable revenue streams and guarantees market access for next-generation vehicle platforms. |
| Target Chinese Aftermarket Growth | Captures substantial volume from a large and aging vehicle parc, diversifying revenue beyond new vehicle sales. |
Research Approach
The analysis maps key sub-sectors, including hydraulic mounts, elastomeric technologies, and engine compartment applications, each validated through primary interviews with OEM platform engineers and Tier-1 procurement leads. This involved extensive secondary research across vehicle production databases, regulatory filings from the US EPA and EU type-approval system, and material science journals. A robust bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Output validation against external benchmarks confirmed the integrity of the forecast framework across the analysis window. The quantitative model segmented the market by product type, technology, application, end-user, and regional production volume. Compound Annual Growth Rates were derived from historical trends and projected adoption rates for electric vehicle platforms. Key inputs included global EV production forecasts and raw material cost projections for advanced elastomeric compounds.
The analysis sits within stated boundaries; outcomes outside macroeconomic stability or consistent regulatory evolution would require recalibration. Forecasts reflect assumptions regarding technological advancements in NVH solutions and sustained demand from the automotive sector. Revision becomes warranted when geopolitical shifts impacting trade or unforeseen raw material supply disruptions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market