
 Automotive Clear Coat Paint Market | 2026-2036
Automotive Clear Coat Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Clear Coat Paint Market Outlook
ISO 14001 environmental management certification is reorganizing supplier qualification protocols across the automotive clear coat paint value chain. PPG Industries sustains broad geographic coverage through integrated resin-to-coating manufacturing networks spanning North America, Europe, and Asia. Axalta Coating Systems specializes in mobility-focused color and performance technologies, leveraging direct OEM technical partnerships. Kansai Paint Co. anchors its competitive position in Asian automotive assembly corridors, particularly in Japan and Thailand.
Automotive clear coat paint constitutes a transparent, chemically cross-linked topcoat layer applied over base color coats, typically formulated with acrylic or polyurethane resins at film builds of 35–50 micrometers to provide gloss retention, ultraviolet protection, and chemical resistance against road debris and environmental exposure. Water-based polyurethane clear coats are gaining formulation share as OEMs pursue volatile organic compound reduction targets without sacrificing durability metrics. The solvent-based segment still occupies the largest installed base in commercial vehicle and motorcycle applications where drying speed and equipment compatibility outweigh environmental compliance pressures. UV-cured technology leads in niche premium segments requiring instant process throughput and exceptional scratch resistance.
EPA regulations in the United States and REACH compliance requirements in Europe are constraining allowable solvent content, directly elevating demand for compliant water-based and electrodeposition clear coat systems. China's MEE enforces progressively stricter VOC limits in automotive manufacturing zones, compelling local and multinational suppliers to reformulate product portfolios. Japan's METI promotes next-generation coating technologies through industrial standards that emphasize reduced energy consumption during cure cycles. Stakeholders must monitor regulatory divergence across these jurisdictions to determine where capital allocation for compliant capacity expansion will yield durable competitive positioning.
Market Dynamics
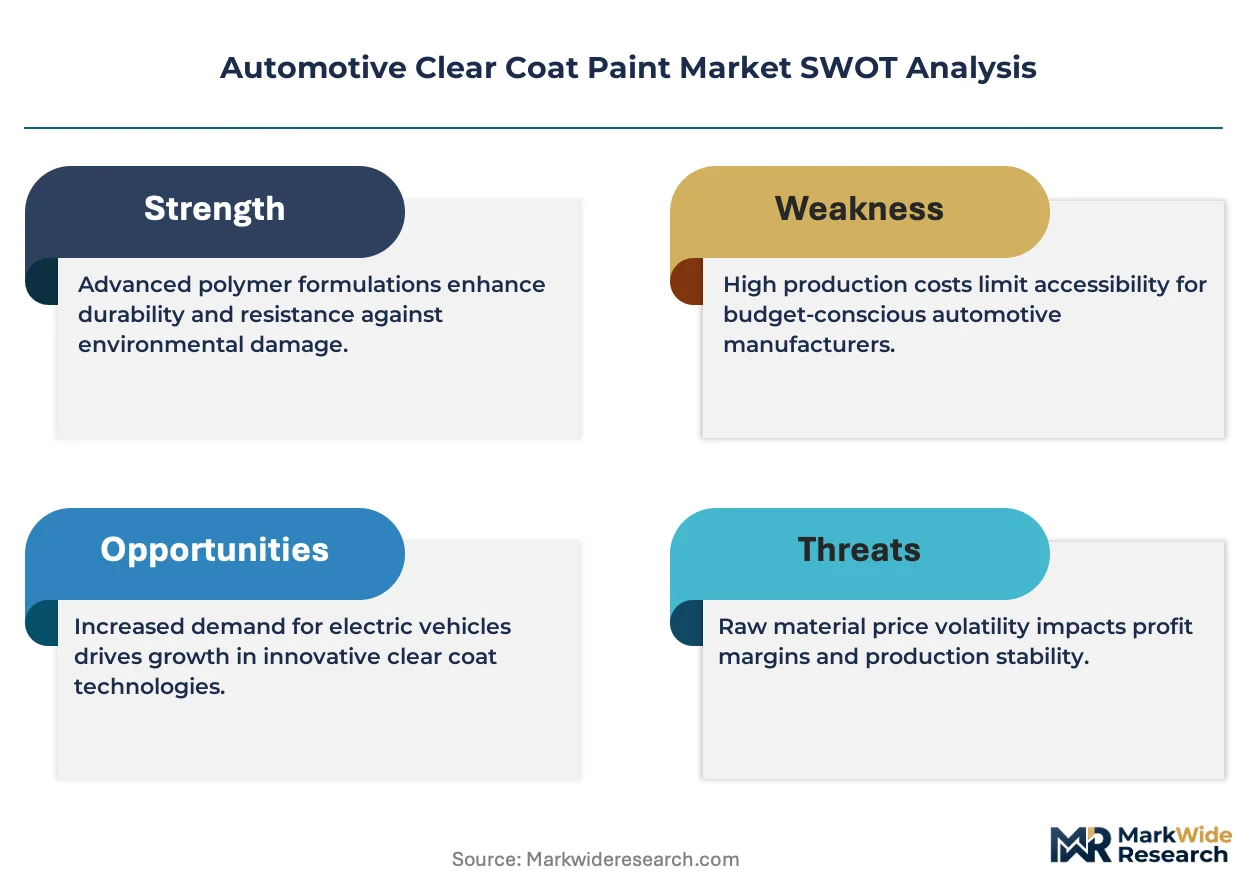
Environmental compliance deadlines are compressing formulation cycles as coating suppliers race to replace solvent-borne systems before VOC thresholds tighten across major automotive manufacturing corridors.
Growth Catalysts
- China's MEE enforcement:Progressive VOC limits in Yangtze River Delta manufacturing zones are compelling clear coat suppliers to accelerate water-based and UV-cured technology deployment.
- Passenger vehicle OEM procurement:Automakers are extending warranty periods for exterior finishes, driving specification upgrades to high-performance polyurethane clear coats with enhanced UV stability.
- Electrodeposition integration:Advanced e-coat compatibility requirements are pulling clear coat formulation investments toward integrated coating system architectures.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane resin costs fluctuate with crude oil derivatives, compressing margin predictability for formulation specialists.
- Equipment retrofit requirements:Water-based clear coat adoption demands substantial capital outlay for spray booth humidity control and flash-off zone modifications at OEM paint shops.
- Cure cycle energy intensity:Extended bake requirements for compliant formulations conflict with automaker throughput targets, creating adoption friction in high-volume assembly plants.
Strategic Opportunities
- Commercial vehicle electrification:Battery-electric truck and bus platforms require specialized clear coat chemistries for thermal management and lightweight substrate compatibility.
- Japan's METI standards:Reduced energy consumption mandates for coating cure cycles are creating competitive openings for suppliers with low-temperature cross-linking technologies.
- Refinish channel consolidation:Independent body shop networks are centralizing procurement through distributor alliances, favoring suppliers with technical service density.
Industry Challenges
- Formulation chemist scarcity:Expertise in water-based polyurethane stabilization and UV-curable oligomer design is concentrated among senior specialists approaching retirement.
- ISO 14001 certification timelines:Supplier qualification protocols now require 18-24 month environmental management system verification before OEM contract award.
- Legacy solvent-based inventory:Paint shops maintain substantial stocked volumes of non-compliant clear coats, complicating rapid formulation transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Clear Coat Paint Market |
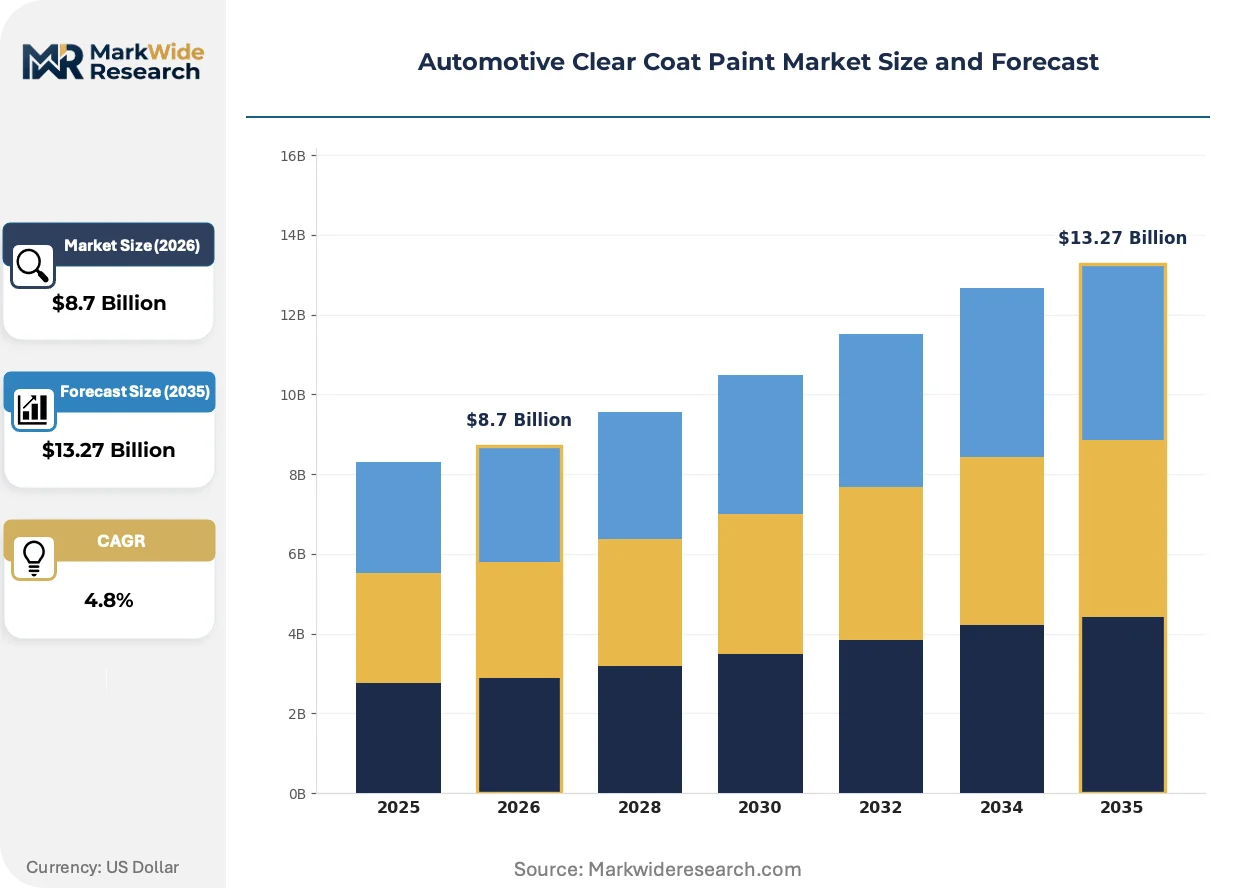
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Alkyd, Nitrocellulose Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Aftermarket Technology: Solvent-Based, Water-Based, UV-Cured, Electrodeposition End User: OEMs, Repair Shops, Distributors, Vehicle Assemblers |
| Companies Covered | PPG Industries, Inc., Axalta Coating Systems, BASF SE, Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., The Sherwin-Williams Company, 3M Company, KCC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Clear Coat Paint Market Strategic Shifts
Formulation science is diverging along performance-versus-compliance axes as suppliers develop parallel product architectures for different regulatory environments and end-use durability requirements.
Self-healing clear coat technology is bifurcating the premium automotive segment. Microcapsule-based and intrinsic polymer network approaches restore gloss after minor scratching through thermal or UV activation. Luxury and performance vehicle manufacturers are specifying these systems for hood and bumper applications where stone chip exposure concentrates. The technology is compressing traditional warranty claim structures while enabling extended service interval marketing.
REACH authorization procedures are constraining isocyanate-based hardener chemistries across European automotive coating operations. ECHA's restriction roadmap is forcing reformulation toward blocked isocyanate and non-isocyanate cross-linking alternatives. Premium passenger vehicle clear coats are most affected, with suppliers accelerating aliphatic polyurethane alternatives through validation pipelines.
Automotive OEMs are unbundling coating system procurement from integrated supplier agreements. Tier-1 paint shop operators are gaining direct specification authority for clear coat selection, displacing historical captive supply arrangements. This pattern is most visible in German and Japanese automotive assembly corridors where modular paint shop contracts are proliferating.
Automotive Clear Coat Paint Market Segmentation
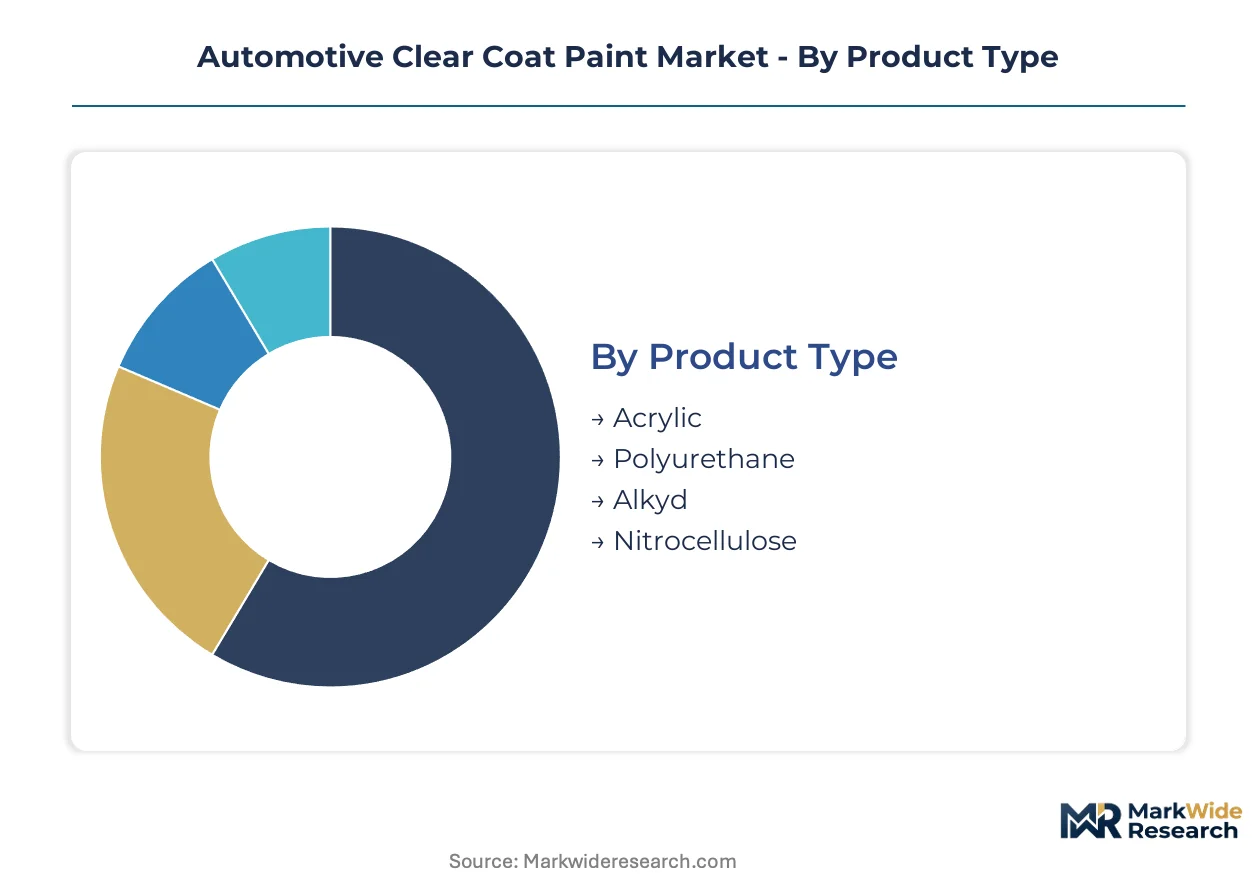
Automotive clear coat paint segmentation reveals how formulation chemistry, application environment, and regulatory pressure intersect to determine supplier resource allocation. Understanding these divides exposes where substitution threats from alternative finishing technologies concentrate most intensely.
Product Type:
Acrylic and polyurethane resin systems face divergent substitution pressures from ceramic coating alternatives and film-based paint protection systems in premium vehicle segments.
- Polyurethane:Aliphatic polyurethane clear coats deliver superior UV stability and gloss retention through cross-linked polymer networks. OEM specification for extended warranty coverage in Germany and Japan concentrates procurement toward high-solids polyurethane systems with 40-50 micrometer film builds.
- Acrylic:Thermoplastic acrylic formulations dominate refinish channels where rapid air-dry characteristics and sandability outweigh durability metrics. China's independent body shop networks in Guangdong and Jiangsu provinces sustain acrylic volume despite water-based transition pressures.
- Alkyd:Modified alkyd resins retain commercial vehicle and motorcycle applications where cost positioning supersedes compliance timelines in Southeast Asian assembly corridors.
- Nitrocellulose:Legacy nitrocellulose lacquers persist in vintage vehicle restoration and specialty motorcycle finishing where historical authenticity commands premium pricing.
Polyurethane retains volume leadership; acrylic holds the steepest expansion curve in water-based reformulation.
Application:
Cost tier stratification separates passenger vehicle OEM procurement—where specification authority centralizes at headquarters—from fragmented aftermarket channels where distributor relationships govern access.
- Passenger Vehicles:Light vehicle OEMs specify integrated coating system architectures with electrodeposition primer compatibility. Yangtze River Delta assembly plants in China demand water-based clear coat validation before supplier qualification.
- Commercial Vehicles:Heavy truck and bus manufacturers prioritize throughput velocity over environmental compliance in North American and Indian production facilities.
- Motorcycles:Two-wheeler assembly in Thailand and Indonesia sustains solvent-based clear coat demand where compact paint shop footprints limit humidity control infrastructure.
- Aftermarket:Collision repair networks consolidate procurement through distributor alliances, concentrating technical service requirements in metropolitan body shop clusters.
Passenger vehicles command the dominant value share; aftermarket channels are expanding most quickly through distributor consolidation.
Technology:
Maturity gradients separate established solvent-based infrastructure from emerging UV-cured niches requiring capital-intensive equipment conversion at OEM paint shops.
- Solvent-Based:Conventional solvent-borne clear coats retain installed base dominance where existing spray booth configurations and flash-off zones resist modification. Commercial vehicle manufacturers in the United States defer retrofit investments amid EPA compliance timeline uncertainty.
- Water-Based:Waterborne polyurethane systems achieve VOC reduction targets without sacrificing durability through advanced coalescing agent formulations. China's MEE enforcement in Shanghai and Suzhou manufacturing zones accelerates supplier portfolio conversion.
- UV-Cured:Ultraviolet-curable oligomer systems enable instant process throughput for premium electric vehicle components requiring exceptional scratch resistance.
- Electrodeposition:E-coat integrated clear coat architectures streamline coating system layers for lightweight substrate compatibility in battery-electric vehicle platforms.
Solvent-based technology retains volume leadership; UV-cured systems follow the steepest expansion trajectory in premium segment penetration.
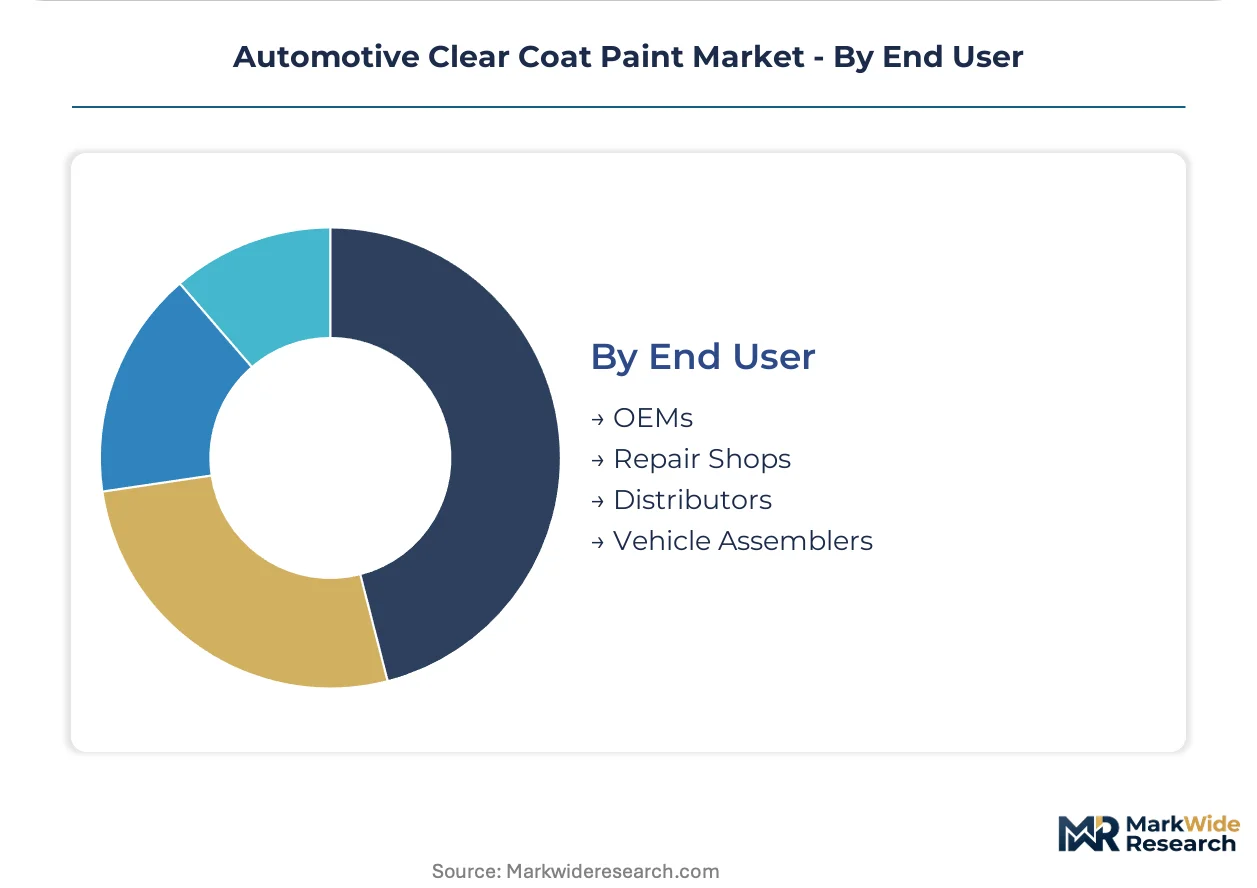
End User:
Customer type determines whether procurement emphasizes technical partnership depth or logistics efficiency in supply chain configuration.
- OEMs:Original equipment manufacturers exercise direct specification authority through integrated coating system agreements with PPG, Axalta, and Kansai in Germany, Japan, and Thailand assembly corridors.
- Vehicle Assemblers:Contract assembly operations in China's Yangtze River Delta delegate clear coat selection to tier-1 paint shop operators under modular service contracts.
- Repair Shops:Independent collision repair networks centralize procurement through distributor technical service partnerships in North American and European metropolitan markets.
- Distributors:Refinish channel distributors consolidate body shop procurement volumes, favoring suppliers with inventory positioning and color-matching support infrastructure.
OEMs retain volume leadership; vehicle assemblers are gaining specification authority fastest through modular paint shop contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific coating logistics, handling resin feedstocks and formulated clear coats for Yangtze River Delta assembly plants. European distribution relies on Rhine River barge networks connecting BASF Ludwigshafen to OEM paint shops in Germany and France. North American supply chains leverage Houston petrochemical corridors for acrylic and polyurethane resin inputs.
China
Passenger vehicle OEM procurement and NMPA-aligned environmental standards drive formulation investments. MEE enforcement in Shanghai and Suzhou manufacturing zones compels water-based and UV-cured technology deployment. The Yangtze River Delta automotive cluster concentrates domestic and multinational supplier production facilities with integrated technical service operations.
Germany
Luxury automaker specification authority and extended warranty requirements elevate high-performance polyurethane demand. REACH authorization procedures constrain isocyanate-based hardener chemistries, forcing reformulation toward blocked isocyanate alternatives. Bavarian and Baden-Württemberg assembly corridors host modular paint shop contracts with direct tier-1 operator specification authority.
United States
Commercial vehicle manufacturers prioritize throughput velocity over environmental compliance in Michigan and Ohio production facilities. EPA regulations constrain allowable solvent content, elevating demand for compliant water-based systems. The Houston petrochemical corridor supplies acrylic and polyurethane resin feedstocks to domestic formulation plants.
Japan
METI promotes next-generation coating technologies through industrial standards emphasizing reduced energy consumption during cure cycles. Kansai and Kanto automotive assembly corridors sustain direct OEM technical partnerships with coating suppliers. Low-temperature cross-linking technologies create competitive openings for compliant formulation specialists.
Thailand
Two-wheeler and passenger vehicle assembly sustains solvent-based clear coat demand where compact paint shop footprints limit humidity control infrastructure. Multinational suppliers operate integrated production facilities serving ASEAN automotive export corridors. Bangkok and Eastern Economic Zone manufacturing clusters concentrate coating procurement through distributor technical service networks.
Automotive Clear Coat Paint Market Competitive Environment
Listed leaders compete with private specialists across integrated coating system architectures and regional technical service density. The market structure consolidates around resin-to-coating manufacturing networks, diversified chemical conglomerates, and mobility-focused coating specialists. Three archetypes dominate: integrated resin manufacturers with captive coating formulation, automotive-dedicated coating system suppliers, and diversified chemical majors with industrial coatings portfolios. Competitive moves center on ISO 14001 certification timelines for supplier qualification and water-based technology portfolio conversion ahead of VOC compliance deadlines.
Within the integrated coating system tier, PPG Industries and Axalta Coating Systems exemplify geographic coverage and OEM technical partnership models. Kansai Paint Co. anchors Asian automotive assembly corridor positioning. These three represent distinct strategic postures: North American-listed global networks, mobility-focused performance specialists, and Japan-based regional concentration with Thailand expansion.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Axalta Coating Systems |
| BASF SE |
| Akzo Nobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| The Sherwin-Williams Company |
| 3M Company |
| KCC Corporation |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of acrylic and polyurethane resin inventory at Yangtze River Delta coating plants concentrates pricing power among integrated resin manufacturers while compressing margin buffers for independent formulators facing MEE compliance deadlines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with ISO 14001 certification tier and volume scale serving as primary differentiation drivers. Premium polyurethane clear coats for German and Japanese OEMs command substantial brand premiums tied to extended warranty coverage. Cost compression in economy-tier solvent-based formulations is intensifying because Thai and Indonesian motorcycle assemblers prioritize throughput velocity over environmental compliance. Commercial vehicle manufacturers in North America exhibit highest price sensitivity, while luxury passenger vehicle OEMs in Germany demonstrate lowest sensitivity due to durability specification mandates.
Supply Chain Analysis
China, Germany, and the United States anchor acrylic and polyurethane resin production, with the Houston petrochemical corridor and BASF Ludwigshafen supplying feedstocks to regional formulation networks. Clear coat manufacturing draws from isocyanate hardeners, aliphatic polyols, and UV-curable oligomers as critical inputs. Single-source vulnerability concentrates in isocyanate supply chains constrained by REACH authorization procedures. Distribution runs through integrated supplier technical service facilities positioned adjacent to Yangtze River Delta and Bavarian automotive assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where ISO 14001 certification timelines and VOC compliance deadlines create eighteen-to-twenty-four month barriers to supplier qualification that protect incumbent positions.
For Market Incumbents: Consolidate backward integration into acrylic and polyurethane resin production to defend against petrochemical feedstock volatility and margin compression. Expand water-based formulation capacity in Shanghai and Suzhou manufacturing zones ahead of MEE enforcement tightening. Prioritize captive supply of aliphatic polyols to secure hardener chemistry access amid REACH authorization constraints.
For New Entrants and Emerging Players: Anchor in Thailand's Eastern Economic Zone two-wheeler assembly corridor, where compact paint shop footprints and limited humidity control infrastructure sustain solvent-based demand that multinational incumbents are deprioritizing. Target independent collision repair networks in North American metropolitan markets through distributor technical service partnerships as the most penetrable aftermarket channel. Pursue UV-cured technology licensing agreements with premium electric vehicle component suppliers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because VOC threshold divergence across jurisdictions creates persistent reformulation demand that rewards agile formulation specialists. Acquisition targets should emphasize mid-tier suppliers with validated water-based portfolios and established MEE compliance track records in China. The signal to watch is accelerated tier-1 paint shop operator specification authority displacing historical OEM captive supply arrangements in German and Japanese assembly corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of acrylic and polyurethane feedstocks insulates margin stability against crude oil derivative volatility. |
| Water-Based Portfolio Conversion | MEE enforcement in Shanghai and Suzhou manufacturing zones accelerates compliant formulation validation requirements. |
| UV-Cured Technology Licensing | Premium electric vehicle component suppliers demand instant process throughput and exceptional scratch resistance specifications. |
| ISO 14001 Certification Investment | Eighteen-to-twenty-four month environmental management system verification timelines gate OEM contract awards. |
| Distributor Technical Service Expansion | Independent collision repair network consolidation in North American metropolitan markets favors technical service density. |
Study Parameters
Desk research of customs and trade data, SEC 10-K filings, and ACC industry reports preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and coating formulation R&D directors. Primary fieldwork across Yangtze River Delta, Bavarian, and Thai Eastern Economic Zone automotive clusters combined with secondary validation from vehicle production databases and IHS Markit registration data. Bottom-up segment sizing and top-down market triangulation reconciled variance across supplier shipment records and OEM consumption estimates.
Variance decomposition across product type, application technology, and regional regulatory cluster dimensions informed the analytical framework over the projection horizon. Modeled segmentation captured vehicle class, propulsion architecture, content per vehicle, and OEM tier distinctions throughout the forecast period. CAGRs derived from regression analysis against automotive production forecasts and coating content per vehicle trajectories. Industry-specific inputs incorporated MEE enforcement timelines, REACH authorization roadmaps, and METI low-temperature cure standards.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and progressive VOC regulatory enforcement; material deviation in crude oil derivative costs or accelerated compliance timeline shifts would warrant model refresh. Recalibration cycles align with material shifts in MEE enforcement intensity, REACH restriction expansions, and tier-1 paint shop operator specification authority transfers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Seat Covers Market