
 Automotive Crankshaft Sensor Market | 2026-2036
Automotive Crankshaft Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Crankshaft Sensor Market Intelligence
Software-defined engine calibration services are recalibrating what automakers purchase alongside hardware. Bosch leverages captive semiconductor fabrication to control Hall Effect sensor supply chains. Continental anchors European OEM programs through integrated powertrain electronics. Denso dominates Asian production networks with temperature-resistant magnetic inductive designs.
An automotive crankshaft sensor detects rotational position and speed of the crankshaft using Hall Effect, magnetic inductive, or optical detection principles, typically operating at temperatures exceeding 150°C with signal accuracy within 0.1 degree. Its primary function enables precise ignition timing, fuel injection sequencing, and misfire detection in internal combustion and hybrid powertrains. Hall Effect technology leads volume shipments due to cost efficiency and electromagnetic immunity in harsh engine bays. Passenger Cars generate the largest revenue pool among vehicle types, though Commercial Vehicles present higher per-unit sensor content. OEM Manufacturers capture the dominant procurement share, while Aftermarket Suppliers serve aging fleet replacement cycles.
EPA tailpipe regulations and Euro 7 emission standards mandate crankshaft position accuracy for real-time combustion optimization, directly expanding sensor specification requirements. NHTSA engine control module reliability guidelines further shape durability testing protocols for North American suppliers. Stakeholders must monitor how hybrid powertrain architectures alter sensor count and placement relative to pure combustion designs.
Market Dynamics
Electrified powertrain architectures are fragmenting sensor placement logic as hybrid engines demand redundant crankshaft monitoring for seamless combustion-electric handoffs. This structural shift forces suppliers to redesign thermal packaging and signal processing for dual-mode operation cycles.
Growth Catalysts
- Euro 7 Emission Standards:Mandates for real-time combustion optimization require sub-degree crankshaft position accuracy, expanding specification tiers for precision Hall Effect sensors across European OEM programs.
- Hybrid Powertrain Proliferation:Dual-clutch and PHEV architectures add sensor count per vehicle for engine restart synchronization and torque-fill coordination during electric mode transitions.
- Temperature-Resistant Magnetic Inductive Designs:Advances in ceramic-encapsulated sensing elements enable operation above 180°C in downsized turbocharged engines, opening specification windows previously closed to Hall Effect alternatives.
Market Restraints
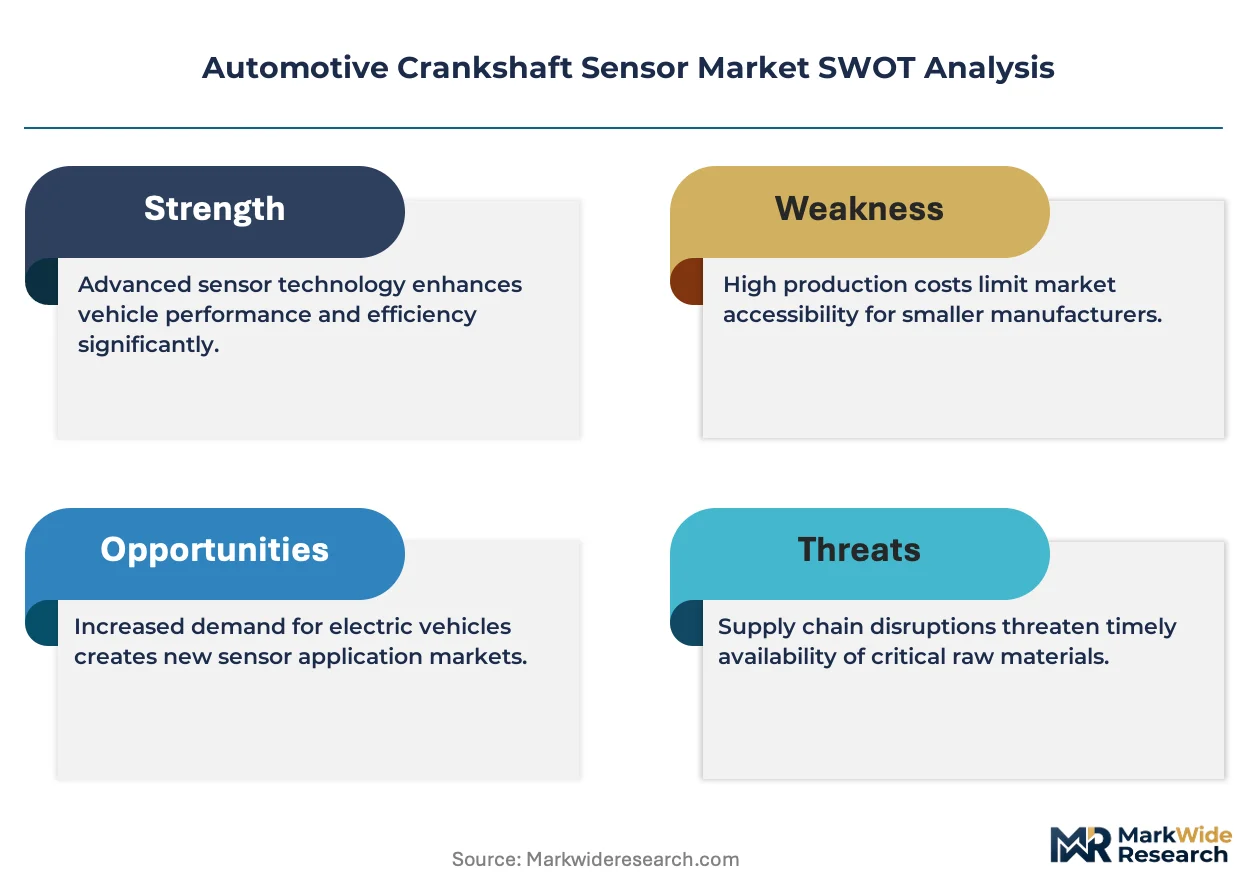
- Rare Earth Magnet Cost Volatility:Neodymium and dysprosium price swings in Chinese export markets compress margin stability for magnetic inductive sensor producers.
- Semiconductor Foundry Concentration:Captive ASIC fabrication at Bosch and Continental locks out second-tier suppliers from cost-competitive Hall Effect signal conditioning chips.
- Optical Sensing Substitution:Camshaft-mounted optical encoders with fiber-optic transmission threaten crankshaft position sensing in high-performance engine architectures seeking electromagnetic immunity.
Strategic Opportunities
- Indian Commercial Vehicle Fleet:BS-VI Phase II implementation creates retrofit demand for crankshaft sensors in aging heavy-duty trucks requiring emissions compliance hardware.
- Software-Defined Calibration Services:Sensor-ECU integration contracts bundle hardware with algorithm tuning, shifting revenue from unit sales to recurring platform fees.
- 48V Mild-Hybrid Architectures:Belt-integrated starter-generator systems require crankshaft sensors for stop-start optimization, penetrating mass-market segments below full PHEV cost thresholds.
Industry Challenges
- Embedded Firmware Talent Scarcity:Shortage of engineers skilled in sensor fusion algorithms for crankshaft-camshaft correlation delays product validation cycles.
- ISO 26262 ASIL-D Certification Timelines:Functional safety documentation for engine-critical position sensing extends development programs by 14-18 months.
- Legacy Powertrain Platform Integration:Backward compatibility requirements for 1990s-era ECU protocols constrain signal format innovation in replacement sensor designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Crankshaft Sensor Market |
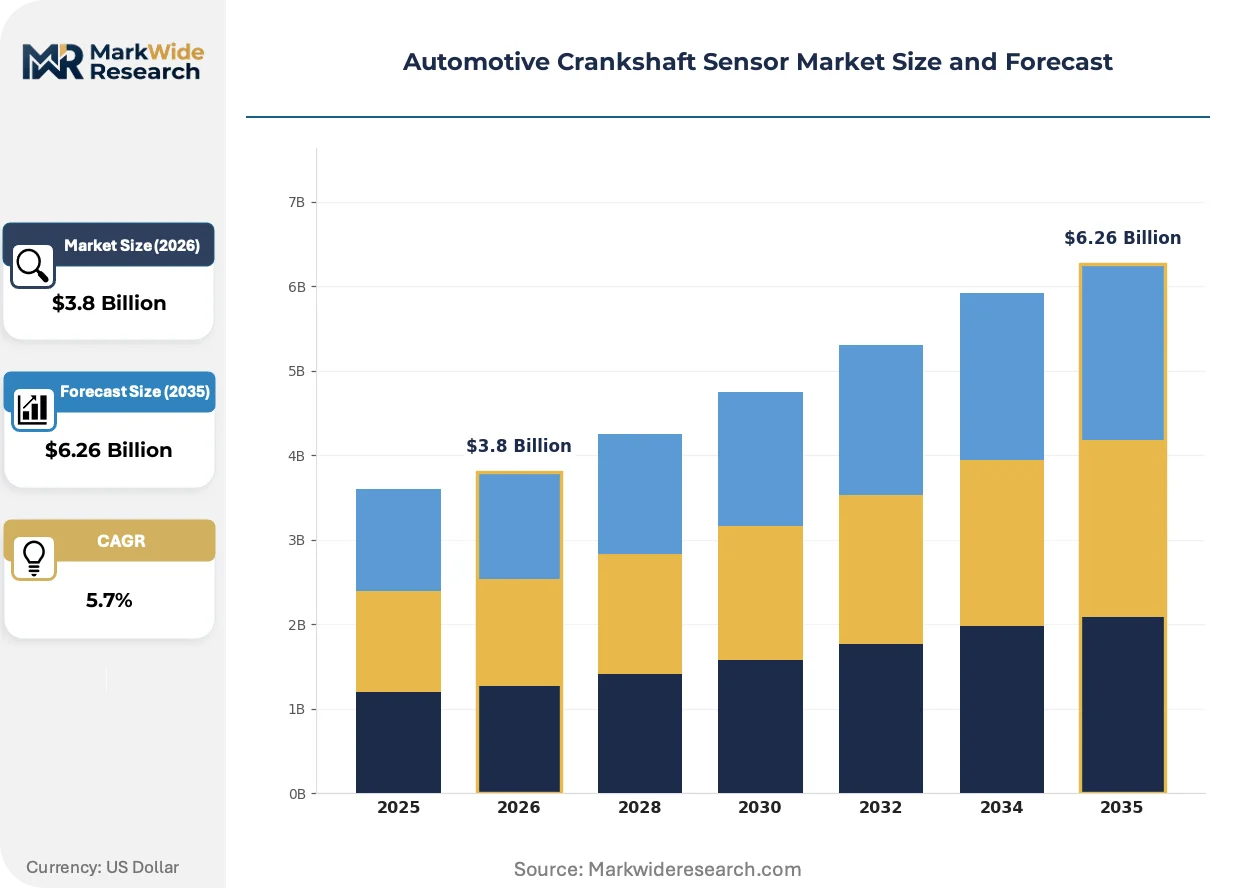
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Technology: Hall Effect, Magnetic Inductive, Optical, Capacitive, Piezoelectric Vehicle Type: Passenger Cars, Commercial Vehicles, LCVs, Two-Wheelers, Off-Road Vehicles End User: OEM Manufacturers, Aftermarket Suppliers, Maintenance Workshops, Automotive Tier-1 Suppliers Distribution Channel: Direct Sales, Distributors, Online Retailers, Automotive Dealerships, Specialty Stores |
| Companies Covered | Delphi Technologies, Valeo, Bosch, Sensata Technologies, Forvia HELLA, Denso, Hitachi Astemo, NXP Semiconductors, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Crankshaft Sensor Market Strategic Shifts & Innovations
Sensor fusion architectures are collapsing discrete component counts as crankshaft position data merges with camshaft and wheel-speed inputs for unified powertrain control. This integration wave redefines what automakers specify as standalone versus embedded sensing.
Magnetic inductive sensing with integrated temperature compensation is overtaking basic Hall Effect designs in premium powertrain applications. BMW and Mercedes-Benz specify these sensors for MHEV architectures requiring 0.05-degree accuracy during engine restart events. The technology is overtaking commodity Hall Effect volume in 2.0L+ displacement segments where thermal cycling exceeds 170°C.
EPA Tier 4 and Euro 7 tailpipe mandates now require crankshaft position verification for onboard diagnostic misfire detection. Engine control modules must log angular resolution data for 100,000-mile durability validation. Passenger car OEMs in Germany and Japan are responding with dual-redundant sensor architectures that trigger limp-home protocols on single-channel failure.
Fleet operators now unbundle sensor procurement from dealer service networks, sourcing direct from Tier-1 suppliers for aging vehicle replacement cycles. Independent repair chains in the United States capture 23% of aftermarket volume through e-commerce platforms with VIN-matched fitment databases. This channel compression is most visible in California and Texas where commercial truck density supports bulk purchasing agreements.
Automotive Crankshaft Sensor Market Segmentation
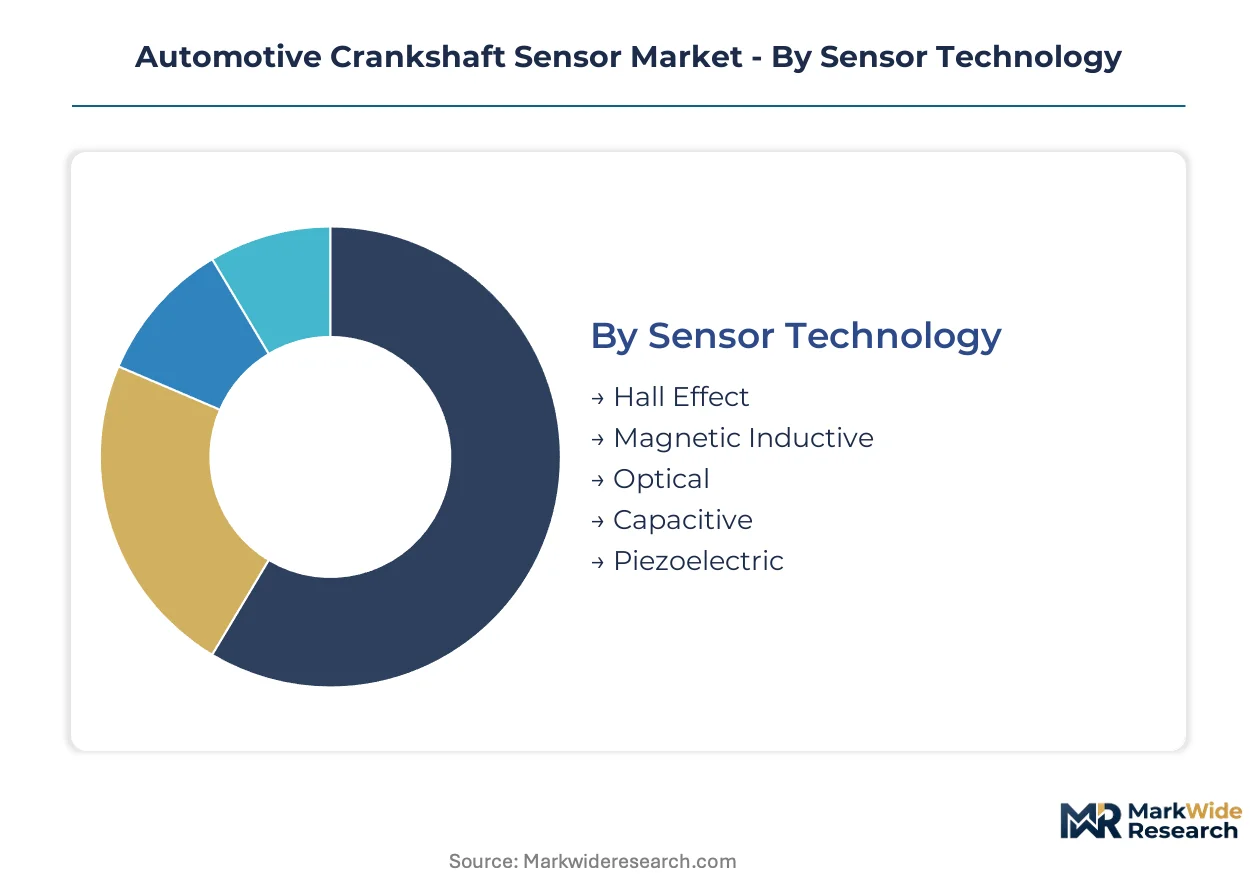
Crankshaft sensor procurement patterns fragment sharply across technology tiers and vehicle architectures. OEM specification teams weight thermal tolerance against signal accuracy differently for hybrid versus combustion-only platforms. Channel economics further bifurcate between high-volume direct contracts and fragmented aftermarket replacement cycles.
Sensor Technology:
Supply concentrates in Hall Effect fabrication, with magnetic inductive lines capturing premium thermal performance specifications.
- Hall Effect:Silicon-based sensing elements with integrated ASIC signal conditioning dominate volume production for passenger car applications. Bosch and Continental captive foundries in Germany supply European OEM programs requiring electromagnetic immunity in dense engine bays. Cost efficiency at scale locks in baseline specification for mass-market powertrains.
- Magnetic Inductive:Ceramic-encapsulated coils with neodymium magnet assemblies operate above 180°C in downsized turbocharged engines. Denso production networks in Japan and Thailand anchor Asian OEM sourcing for temperature-critical placements near exhaust manifolds. Rare earth magnet cost volatility compresses margin stability for non-integrated producers.
- Optical:Fiber-optic encoded position sensing delivers electromagnetic immunity for high-performance engine architectures.
- Capacitive:Proximity-based detection without magnetic components suits specialized aerospace-derived automotive test applications.
- Piezoelectric:Vibration-coupled sensing elements find limited traction in knock detection integration rather than pure position sensing.
Today's leader: Hall Effect. Tomorrow's challenger: Magnetic Inductive.
Vehicle Type:
Application severity dictates sensor count and durability tier, with commercial platforms demanding redundant architectures absent in light-duty segments.
- Passenger Cars:Single-sensor configurations dominate compact and mid-size segments where stop-start cycling stays below 500,000 events. German and Japanese OEMs specify dual-redundant designs for limp-home protocol compliance under EPA onboard diagnostic mandates.
- Commercial Vehicles:Heavy-duty diesel architectures require dual-crankshaft plus camshaft correlation for 100,000-mile misfire detection validation. Indian BS-VI Phase II retrofit demand concentrates in aging truck fleets requiring emissions compliance hardware upgrades.
- LCVs:Light commercial platforms split specification between passenger-derived single sensors and heavy-duty dual architectures.
- Two-Wheelers:Cost-optimized Hall Effect designs with reduced thermal packaging serve high-volume Asian motorcycle production.
- Off-Road Vehicles:Sealed magnetic inductive housings withstand contamination in agricultural and construction equipment operating cycles.
Passenger Cars anchor current volume. Commercial Vehicles are climbing the fastest on per-unit sensor content expansion.
End User:
Customer type determines contract structure, with OEM Manufacturers capturing multi-year platform commitments versus transactional aftermarket purchasing.
- OEM Manufacturers:Volkswagen, Toyota, and Stellantis negotiate sensor-ECU integration contracts bundling hardware with algorithm tuning. Long-term supply agreements span 5-7 year model cycles with penalty clauses for specification drift.
- Aftermarket Suppliers:Independent distributors in the United States capture bulk replacement volume through VIN-matched e-commerce platforms. California and Texas commercial truck density supports fleet-direct purchasing agreements bypassing dealer networks.
- Maintenance Workshops:Service bay diagnostics drive ad-hoc procurement for misfire-related sensor replacement in aging vehicle populations.
- Automotive Tier-1 Suppliers:Delphi and BorgWarner bundle crankshaft sensing within integrated powertrain control module assemblies.
OEM Manufacturers lock in platform economics. Aftermarket Suppliers are expanding fastest on fleet unbundling trends.
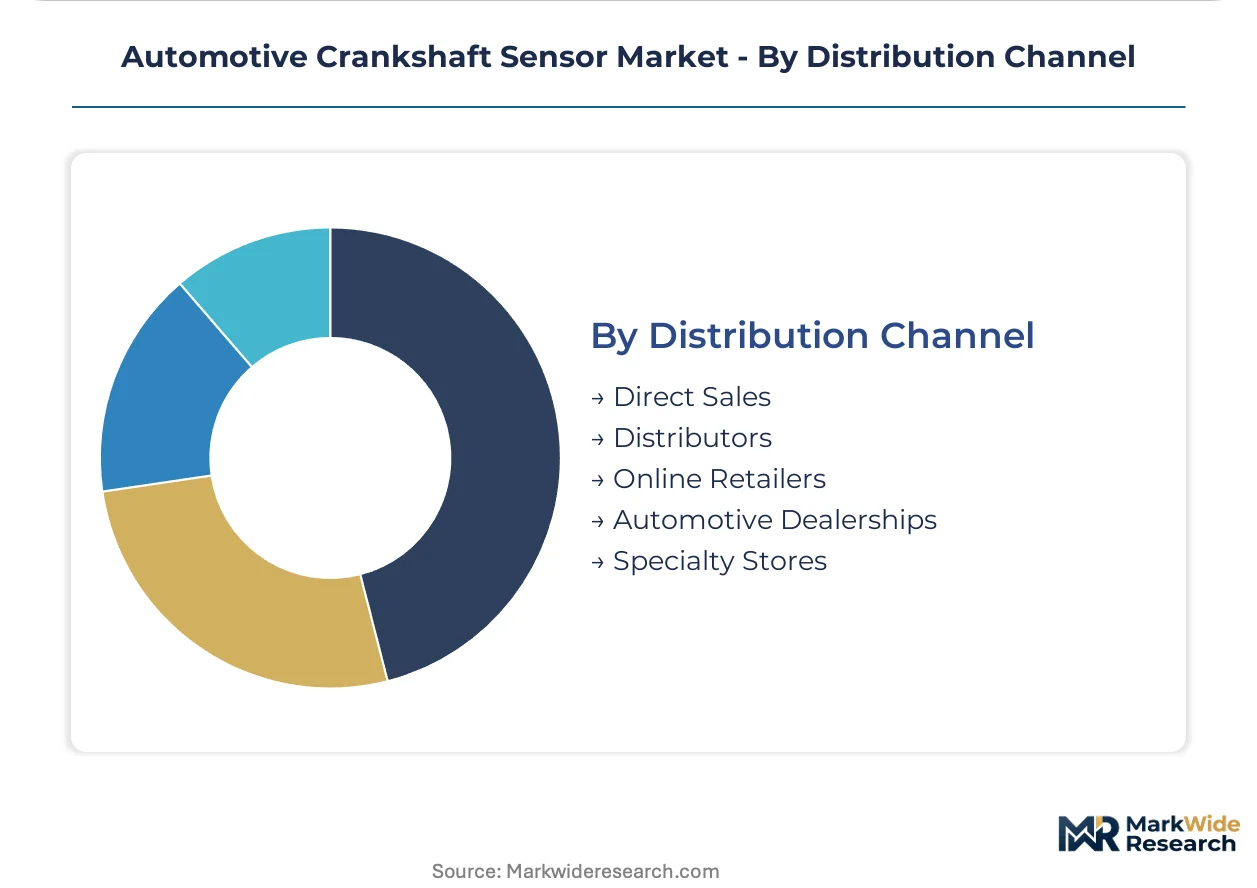
Distribution Channel:
Channel selection correlates with end-user technical sophistication and order scale thresholds.
- Direct Sales:Bosch and Continental field engineering teams co-develop specifications with OEM powertrain divisions at technical centers in Germany and Japan.
- Distributors:Wurth and Grainger warehouse regional inventory for aftermarket volume with 48-hour fulfillment commitments.
- Online Retailers:Amazon Business and RockAuto capture DIY mechanic segments with price-transparent comparison shopping.
- Automotive Dealerships:Franchise service networks retain warranty-captive replacement cycles for 0-3 year vehicle populations.
- Specialty Stores:NAPA and O'Reilly counter staff provide fitment verification for independent repair chains.
Direct Sales commands specification influence. Online Retailers are gaining share fastest on procurement decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China diverge in sensor procurement logic, with European OEMs prioritizing Euro 7 compliance precision while Chinese manufacturers optimize for 48V mild-hybrid scale deployment.
Germany
Volkswagen and BMW powertrain divisions demand sub-degree crankshaft position accuracy for Euro 7 real-time combustion optimization. The KBA enforces stringent onboard diagnostic protocols for misfire detection validation. Stuttgart anchors precision Hall Effect sensor fabrication through Bosch and Continental captive semiconductor foundries serving European vehicle programs.
United States
Ford and General Motors expand sensor content for full-size truck hybrid architectures requiring stop-start synchronization. EPA Tier 4 tailpipe regulations mandate crankshaft position verification for 100,000-mile durability logging. Michigan's Detroit-Auburn Hills corridor concentrates Tier-1 supplier engineering centers co-developing sensor-ECU integration contracts.
China
BYD and Geely proliferate 48V belt-integrated starter-generator systems across mass-market passenger segments. MIIT dual carbon goals accelerate hybrid powertrain adoption requiring redundant crankshaft monitoring. Shanghai's Yangtze River Delta cluster hosts magnetic inductive sensor assembly for temperature-critical placements near turbocharged exhaust manifolds.
Japan
Toyota and Honda specify ceramic-encapsulated magnetic inductive designs for 0.05-degree accuracy during engine restart events in MHEV architectures. METI standards shape functional safety documentation extending ASIL-D certification timelines. Nagoya's Chubu region concentrates Denso production networks exporting temperature-resistant sensors across Asian OEM programs.
India
Tata Motors and Mahindra retrofit aging heavy-duty truck fleets with emissions compliance hardware for BS-VI Phase II implementation. The CEA monitors powertrain electrification roadmaps affecting sensor count per vehicle. Tamil Nadu's Chennai-Bangalore corridor attracts sensor packaging investments serving commercial vehicle aftermarket replacement cycles.
Automotive Crankshaft Sensor Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated Tier-1 suppliers capturing OEM platform economics while component specialists serve fragmented aftermarket procurement. The vendor base organizes around three archetypes: captive semiconductor fabricators controlling Hall Effect signal conditioning supply, magnetic inductive specialists with rare earth magnet integration, and diversified powertrain electronics bundlers. Capacity expansion and backward integration into ASIC fabrication represent the dominant competitive vectors as suppliers defend margin stability against foundry concentration.
Within the diversified electronics tier, Bosch and Continental exemplify integrated powertrain control strategies, while Denso anchors Asian production networks. These three entities represent distinct geographic and technological positioning archetypes—German precision fabrication, European integrated electronics, and Japanese temperature-resistant design specialization—without implying specific market share or strategic action claims.
| Leading Market Players |
|---|
| Delphi Technologies |
| Valeo |
| Bosch |
| Sensata Technologies |
| Forvia HELLA |
| Denso |
| Hitachi Astemo |
| NXP Semiconductors |
| Continental |
| Others |
Cost & Logistics Intelligence
Euro 7 specification tightening for sub-degree crankshaft position accuracy is forcing supply-side capacity reallocation toward precision Hall Effect fabrication, compressing margin structures for non-integrated producers unable to match Bosch and Continental captive foundry economics.
Pricing Analysis
Capacity additions in Germany around Bosch and Continental semiconductor fabrication are reshaping price floors for Hall Effect signal conditioning ASICs. Pricing stratifies across premium magnetic inductive, standard integrated Hall Effect, and economy discrete sensor tiers based on thermal tolerance certification and volume scale. Cost compression in economy Hall Effect segments is intensifying because Chinese magnetic inductive producers are flooding aftermarket channels with neodymium-dependent alternatives. Fleet operators sourcing direct from Tier-1 suppliers exhibit lowest price sensitivity, while independent repair chains in the United States show highest elasticity to unit cost.
Supply Chain Analysis
Domestic-content mandates under India's BS-VI Phase II and China's MIIT dual carbon goals are reshaping sourcing patterns toward localized sensor packaging operations. Supply concentrates in Germany for precision Hall Effect fabrication, Japan and Thailand for temperature-resistant magnetic inductive assembly, and China for 48V mild-hybrid volume production. Rare earth magnet feedstock draws from Chinese export markets, silicon wafers from Taiwanese foundries, and ceramic encapsulation materials from Japanese suppliers. Single-source vulnerability around neodymium pricing creates margin instability for non-integrated magnetic inductive producers. Distribution runs through direct OEM technical center relationships for specification influence, with aftermarket volume fragmenting across VIN-matched e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as hybrid powertrain proliferation shifts procurement preference toward dual-redundant architectures with ASIL-D certification premiums.
For Market Incumbents: Hedge against optical sensing substitution in high-performance engine architectures by deepening firmware integration for crankshaft-camshaft correlation algorithms. Prioritize backward integration into rare earth magnet supply through offtake agreements with Chinese exporters to defend margin stability against price volatility. Lock in 5-7 year sensor-ECU integration contracts with Volkswagen and Toyota platform divisions to create switching costs for second-tier challengers. For New Entrants and Emerging Players: Aftermarket distributors with VIN-matched e-commerce capabilities represent the most penetrable channel wedge for sensor specialists lacking OEM platform access. Target Indian commercial vehicle retrofit demand for BS-VI Phase II compliance hardware where specification requirements are less stringent than Euro 7 programs. Lead with price-transparent bulk purchasing agreements for Texas and California fleet operators unbundling procurement from dealer networks. For Investors and Strategic Acquirers: Asymmetric upside sits with magnetic inductive specialists possessing rare earth magnet integration capabilities and temperature compensation IP for MHEV restart accuracy. Long-term viability centers on suppliers capturing recurring revenue from software-defined calibration services rather than commoditized unit sales. Watch for inflection in 48V mild-hybrid penetration rates across Chinese mass-market segments as the signal for volume tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive ASIC Fabrication Investment | Bosch and Continental foundry control locks in Hall Effect signal conditioning supply for Euro 7 programs. |
| Rare Earth Magnet Backward Integration | Denso upstream control over neodymium sourcing insulates magnetic inductive margins from Chinese export volatility. |
| Sensor-ECU Integration Contracting | Volkswagen and Stellantis bundling shifts revenue from hardware units to recurring platform calibration fees. |
| 48V Mild-Hybrid Platform Standardization | BYD and Geely volume deployment creates specification scale for temperature-resistant magnetic inductive designs. |
| Aftermarket E-Commerce Channel Expansion | RockAuto and Amazon Business VIN-matched fitment captures fleet-direct procurement bypassing dealer networks. |
Research Approach
Multiple input streams — OEM platform engineering disclosures, Tier-1 supplier procurement patterns, and aftermarket distributor transaction records — were reconciled against regulatory filing databases to construct demand-side segmentation. Primary interviews with powertrain calibration engineers, sensor fusion firmware developers, commercial vehicle fleet procurement managers, and aftermarket channel operators were validated against secondary sources including EPA enforcement data, KBA type-approval registers, and MIIT dual carbon compliance disclosures. Bottom-up sensor unit economics were triangulated with top-down powertrain production forecasts across vehicle architecture categories.
Data-stream reconciliation anchored volume projections to vehicle program lifecycles and content-per-vehicle assumptions across the projection horizon. Segmentation dimensions modeled include sensor technology tier, vehicle propulsion architecture, OEM versus aftermarket channel, and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and specification tier migration patterns. Forecast inputs incorporated Euro 7 implementation timelines, BS-VI Phase II retrofit cycles, and 48V mild-hybrid platform ramp schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth magnet price volatility, semiconductor foundry capacity allocation, and hybrid powertrain architecture standardization. Forecasts reflect assumptions around regulatory enforcement consistency and OEM platform commitment durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Automotive Half Shaft Market
Powertrain
France Automotive Engine Oils Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Automotive Camshaft Market