
 Electric Vehicle Power Control Unit Market | 2026-2036
Electric Vehicle Power Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Power Control Unit Market Foresight
Project finance tied to EV-dedicated production lines is rewriting competitive entry conditions for power control unit suppliers. Robert Bosch leverages captive semiconductor fabrication to control inverter cost curves across European OEM programs. Infineon Technologies anchors its position through R&D intensity in silicon carbide die packaging for traction inverters. Denso Corporation dominates thermal-integrated power module assembly for Japanese and North American electric vehicle platforms.
An electric vehicle power control unit manages energy flow between battery packs, electric motors, and auxiliary systems through high-frequency switching circuits typically rated between 400V and 800V DC bus architectures. The device governs torque response, regenerative braking capture, and thermal stability under dynamic load conditions. Inverter segments command the deepest margin pools as silicon carbide technology displaces conventional insulated-gate bipolar transistor designs in premium passenger car programs. Battery management systems sustain volume leadership across commercial vehicle and electric bus end users where cell balancing complexity multiplies with pack scale. Gallium nitride technology competes for cost-sensitive DC/DC converter applications below 6.6kW charging power levels.
FDA medical-device electromagnetic compatibility standards indirectly shape isolation requirements for power control units deployed in electrified ambulance and mobile health vehicle conversions. EPA tailpipe rules and NHTSA fuel economy mandates in the United States force OEMs to source higher-efficiency inverters or face fleet-average penalties. China's MIIT new-energy vehicle catalog and GB/T charging interface standards dictate connector pinouts and communication protocol stacks for any supplier accessing domestic production quotas. Stakeholders must monitor how regional semiconductor subsidy programs alter foundry capacity allocation between automotive and consumer electronics customers.
Market Dynamics
Silicon carbide semiconductor transitions are compressing inverter development cycles while EPA tailpipe rules force OEMs to absorb higher-efficiency power electronics or face fleet-average penalties. This dual pressure is restructuring supplier qualification timelines and foundry capacity allocation.
Growth Catalysts
- EPA Fleet Emissions Mandates:United States OEMs must source higher-efficiency inverters to avoid regulatory penalties, accelerating procurement of silicon carbide-based designs across passenger car programs.
- China's MIIT New-Energy Vehicle Catalog:Domestic production quotas require GB/T charging interface compliance, forcing power control unit suppliers to localize connector pinouts and communication protocol stacks.
- 800V DC Bus Architectures:Premium battery electric passenger cars are driving demand for high-frequency switching circuits capable of faster charging and improved thermal performance under dynamic load conditions.
Market Restraints
- Silicon Carbide Substrate Costs:Wafer supply concentration among limited foundry operators creates input cost volatility that compresses inverter margin pools during scale-up phases.
- Thermal Management Complexity:Power density gains from wide-bandgap semiconductors exceed conventional cooling system capabilities, requiring parallel investment in liquid-cooled module designs.
- Automotive Semiconductor Allocation:Foundry capacity competition with consumer electronics customers creates supply concentration risk during demand surge periods.
Strategic Opportunities
- Commercial Vehicle Electrification:Battery management systems for electric bus platforms present white space where cell balancing complexity multiplies with pack scale and procurement volumes remain underpenetrated.
- Gallium Nitride DC/DC Converters:Cost-sensitive applications below 6.6kW charging power levels enable technology convergence between consumer and automotive power electronics supply chains.
- Electrified Ambulance Conversions:FDA medical-device electromagnetic compatibility standards create regulatory tailwinds for isolation-rated power control units in mobile health vehicle segments.
Industry Challenges
- Silicon Carbide Packaging Expertise:Shortage of engineers skilled in die-attach and thermal interface materials for traction inverters extends product qualification timelines.
- Multi-Standard Certification:Simultaneous compliance with EPA, NHTSA, and China's MIIT requirements creates fragmented testing protocols that delay platform launches.
- Legacy IGBT Inventory Transitions:OEMs face integration complexity when retrofitting silicon carbide inverters onto platforms originally designed for insulated-gate bipolar transistor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Power Control Unit Market |
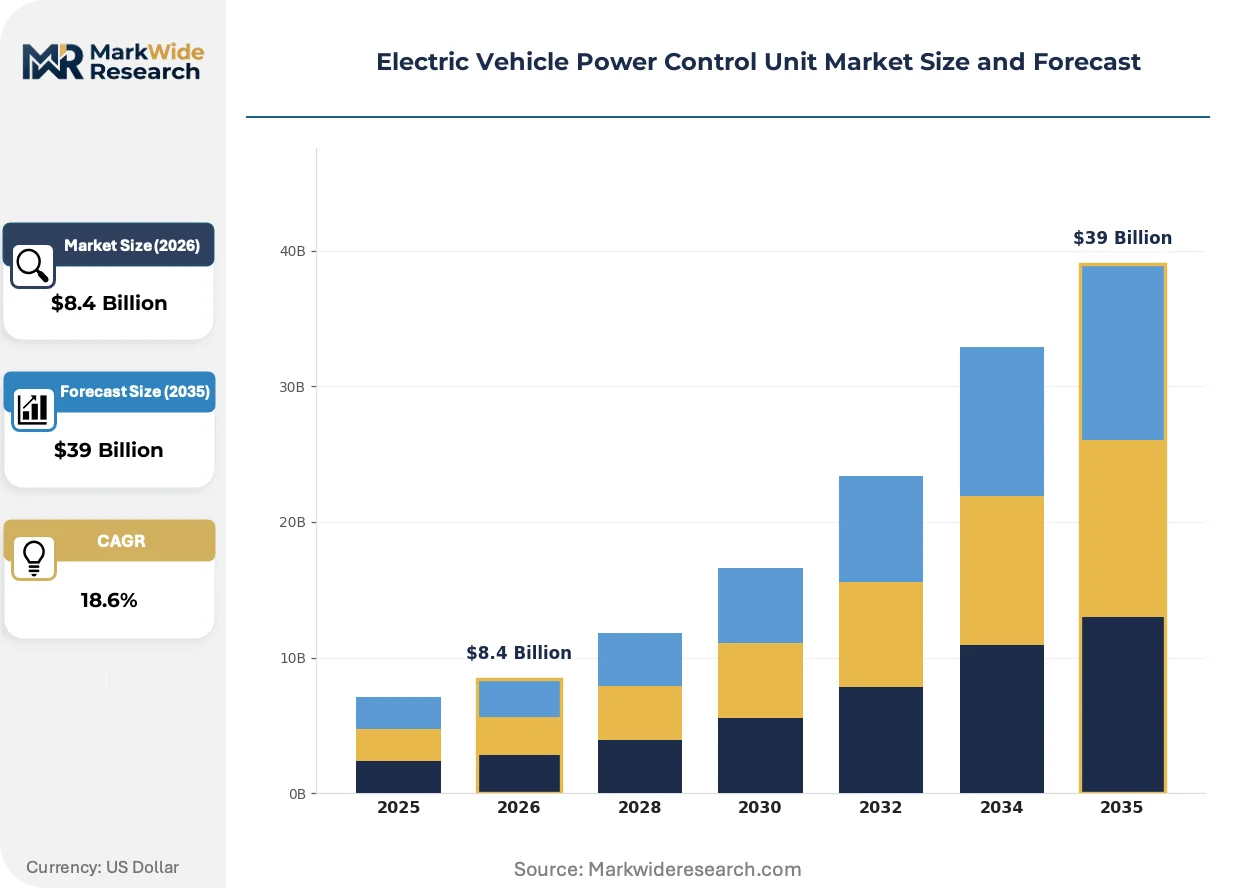
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC/DC Converters, AC/DC Chargers, Inverters, Battery Management Systems End User: Passenger Cars, Commercial Vehicles, E-Bikes, Electric Buses Technology: Silicon Carbide, Gallium Nitride, Aluminum, Copper Application: Energy Management, Thermal Management, Safety Systems, Communication Interfaces |
| Companies Covered | Robert Bosch, Continental, Infineon Technologies, Vitesco, BorgWarner, STMicroelectronics, Denso Corporation, NXP Semiconductors, Wolfspeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Power Control Unit Market Shifts & Advancements
Power semiconductor packaging is converging with thermal system design as wide-bandgap materials enable higher switching frequencies. This convergence is redrawing supplier boundaries and compressing the traditional separation between inverter and cooling module sourcing.
Silicon carbide metal-oxide-semiconductor field-effect transistors govern energy conversion efficiency in next-generation traction inverters. Battery electric passenger car OEMs are adopting these devices fastest in 800V architectures. The technology is hybridizing inverter and onboard charger functions into consolidated power electronics enclosures.
EPA tailpipe emissions rules and NHTSA fuel economy mandates in the United States force OEMs to source higher-efficiency inverters or absorb fleet-average penalties. This regulatory pressure is accelerating the phase-out of silicon-only designs in premium vehicle programs. Power control unit suppliers serving North American OEMs are restructuring R&D budgets to prioritize wide-bandgap semiconductor qualification.
Chinese OEM procurement patterns are shifting from discrete component sourcing to integrated power module assemblies. BYD and CATL-tier suppliers now specify complete thermal-integrated units rather than individual inverter boards. This behavioral change concentrates sourcing decisions in China's eastern manufacturing corridor and marginalizes second-tier component vendors lacking module-level assembly capabilities.
Electric Vehicle Power Control Unit Market Segmentation
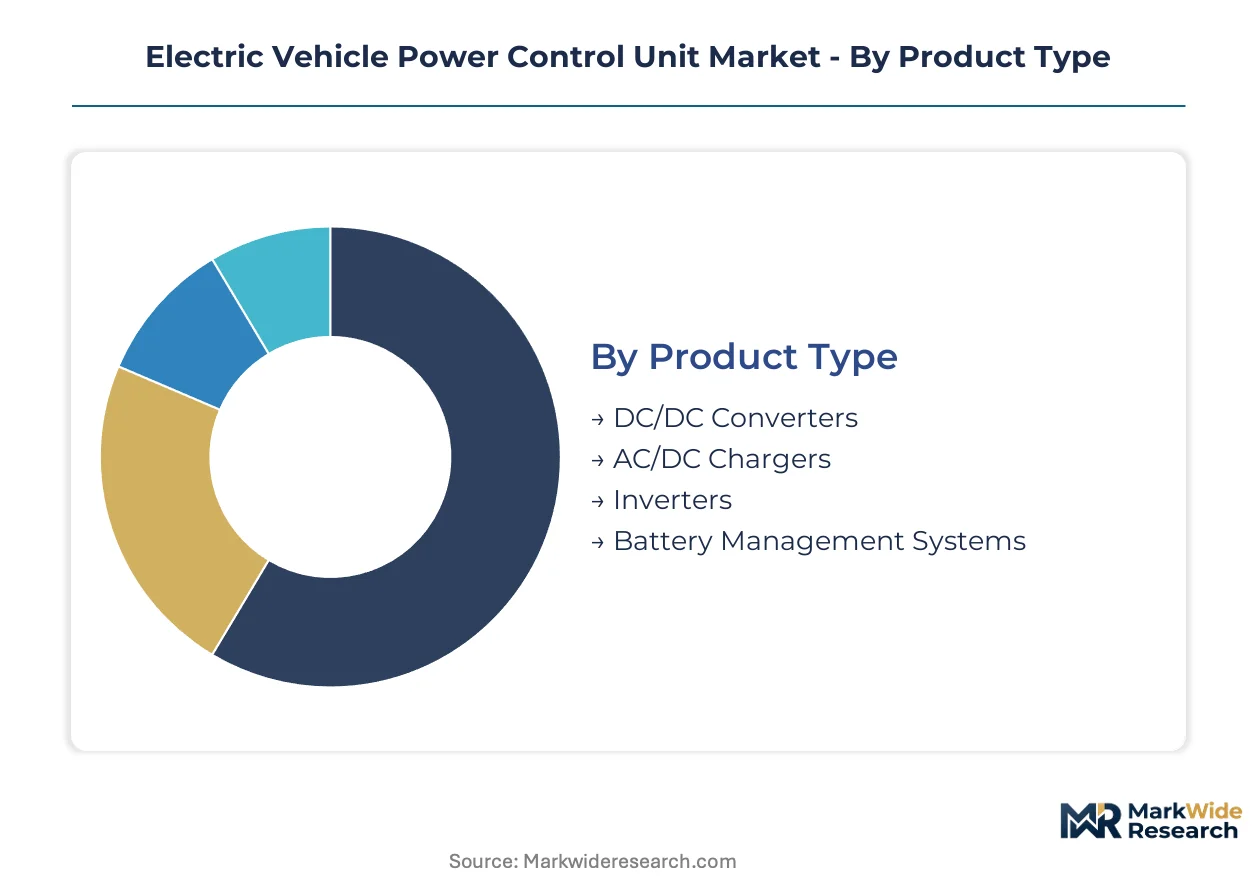
Power control unit segmentation reveals how technology transitions and regulatory pressures fragment procurement strategies across vehicle platforms. Suppliers must align product architectures with divergent efficiency mandates and thermal performance requirements.
Product Type:
Cost tier differentiation separates commodity converters from premium inverter modules where wide-bandgap semiconductors command pricing power.
- Inverters:High-frequency switching circuits govern torque response and regenerative braking capture in 400V-800V DC bus architectures. Silicon carbide MOSFET designs dominate premium battery electric passenger car programs across Germany, Japan, and South Korea as EPA fleet efficiency rules tighten.
- Battery Management Systems:Cell balancing electronics and state-of-charge algorithms manage thermal stability under dynamic load conditions. Electric bus procurement in China's eastern manufacturing corridor drives volume concentration where pack scale multiplies complexity.
- DC/DC Converters:Voltage step-down modules for auxiliary systems below 6.6kW charging power levels.
- AC/DC Chargers:Onboard charging circuits integrating with GB/T connector standards for domestic Chinese production quotas.
Inverters command the established base. The steepest expansion runs through battery management systems.
End User:
Application maturity varies sharply between mass-market passenger electrification and heavy-duty commercial platforms still resolving thermal management at scale.
- Passenger Cars:Battery electric architectures drive procurement volume concentration across OEM assembly lines. 800V platform adoption in European and North American premium segments accelerates silicon carbide inverter demand as NHTSA fuel economy mandates intensify.
- Electric Buses:High-capacity pack configurations require sophisticated cell balancing and thermal runaway protection. Procurement volumes concentrate in China's MIIT new-energy vehicle catalog compliance programs where domestic suppliers anchor component sourcing.
- Commercial Vehicles:Medium-duty delivery and freight electrification programs.
- E-Bikes:Low-voltage power control modules for two-wheel electrification.
Passenger cars command the established base. The steepest expansion runs through electric buses.
Technology:
Material science transitions determine switching efficiency ceilings and thermal performance boundaries across voltage classes.
- Silicon Carbide:Wide-bandgap semiconductors enable higher switching frequencies with reduced thermal losses in traction inverters. EPA tailpipe rules and NHTSA fuel economy mandates in the United States force OEMs to absorb cost premiums or face fleet-average penalties.
- Gallium Nitride:High-electron-mobility transistors compete for cost-sensitive DC/DC converter applications below 6.6kW charging power levels. Technology convergence with consumer electronics supply chains creates foundry capacity competition during demand surge periods.
- Aluminum:Legacy interconnect materials in standard-efficiency inverter designs.
- Copper:High-conductivity busbar and thermal interface applications.
Silicon carbide commands the established base. The steepest expansion runs through gallium nitride.
Application:
Functional integration requirements reshape how power electronics packaging converges with vehicle thermal and safety architectures.
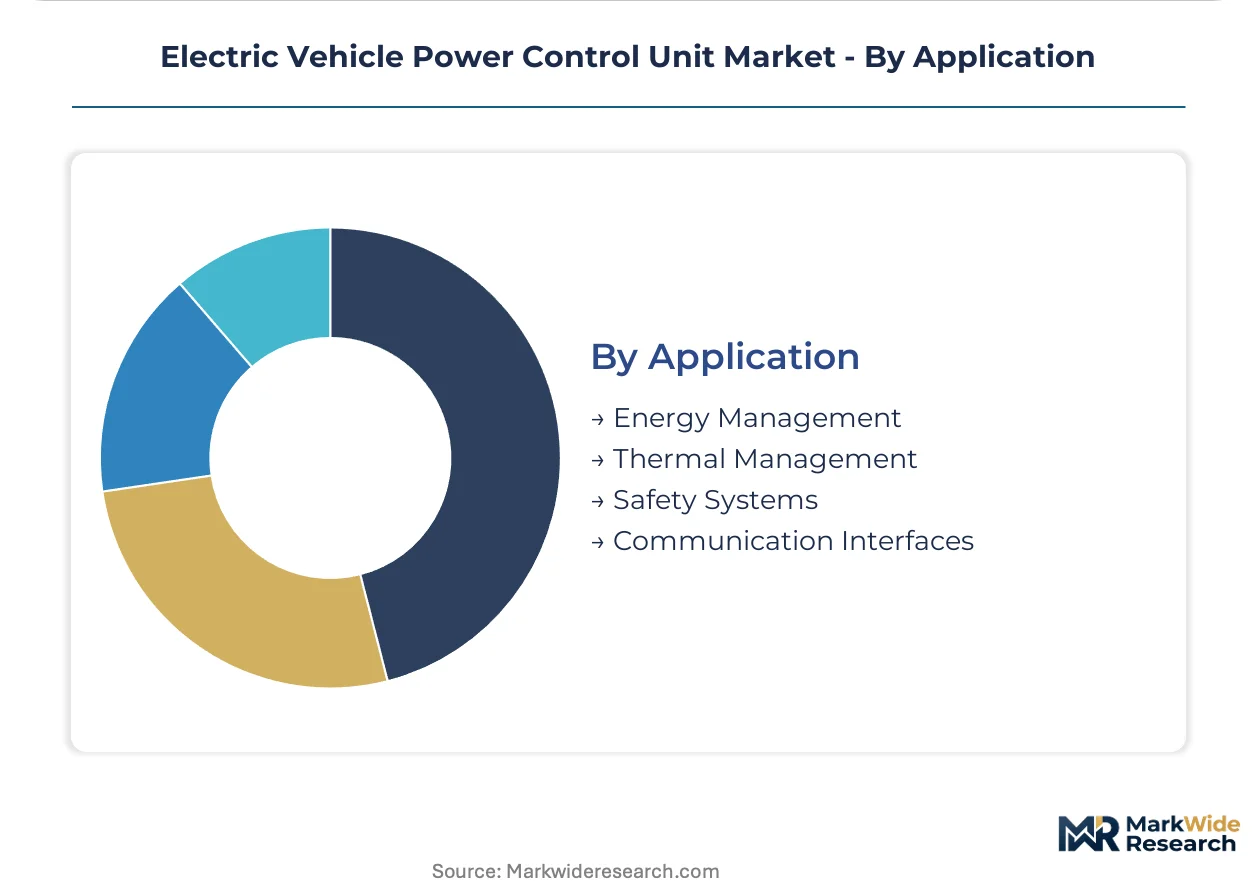
- Energy Management:Bidirectional power flow control between battery packs, electric motors, and regenerative braking systems. FDA electromagnetic compatibility standards for electrified ambulance conversions in the United States create regulatory tailwinds for isolation-rated designs in mobile health vehicle segments.
- Thermal Management:Liquid-cooled module designs and thermal interface materials stabilize power density gains from wide-bandgap semiconductors. Foundry capacity allocation constraints between automotive and consumer electronics customers create supply concentration risk during platform scale-up phases.
- Safety Systems:Fault isolation and arc detection circuits for high-voltage protection.
- Communication Interfaces:GB/T charging protocol stacks and CAN bus integration for vehicle network compatibility.
Energy management commands the established base. The steepest expansion runs through thermal management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for silicon carbide inverters runs higher in Germany than in China, where domestic foundry scale compresses margin premiums for foreign suppliers. This asymmetry shapes how power control unit vendors allocate R&D budgets and foundry partnerships across geographies.
United States
EPA tailpipe emissions rules and NHTSA fuel economy mandates force Detroit OEMs to source higher-efficiency inverters or absorb fleet-average penalties. The Inflation Reduction Act's domestic content requirements steer procurement toward North American assembly. Michigan and Ohio anchor inverter module production for premium battery electric passenger car programs.
Germany
Premium OEM electrification roadmaps drive demand for 800V silicon carbide traction inverters across Bavaria and Baden-Württemberg. The EU Green Deal's automotive CO2 targets accelerate phase-out of silicon-only designs. Stuttgart and Ingolstadt concentrate power electronics R&D where Bosch and Continental-tier suppliers control captive semiconductor fabrication.
China
MIIT new-energy vehicle catalog compliance requires GB/T charging interface standardization for domestic production quotas. BYD and CATL-tier suppliers in the Yangtze River Delta now specify complete thermal-integrated power modules rather than discrete components. Shanghai and Shenzhen anchor the eastern manufacturing corridor where procurement volumes concentrate.
Japan
METI's decarbonization roadmap and JIS standards for high-voltage safety shape inverter qualification timelines for Toyota and Honda electrification platforms. Denso Corporation dominates thermal-integrated power module assembly. Aichi Prefecture and the Kanto region concentrate supplier engineering resources for next-generation wide-bandgap semiconductor packaging.
South Korea
Hyundai and Kia electrification targets drive silicon carbide inverter procurement for 800V E-GMP platforms. MFDS automotive safety standards intersect with electromagnetic compatibility requirements for export-bound vehicles. Gyeonggi Province and the Seoul Capital Area anchor power control unit assembly for domestic and North American OEM programs.
Electric Vehicle Power Control Unit Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in die packaging and substrate fabrication. The market structures around three tiers: captive semiconductor fabricators controlling cost curves, thermal-integrated module assemblers, and fabless design houses licensing IP to foundry partners. Consolidation pressure runs highest where EPA and EU efficiency mandates compress development cycles. Dominant competitive moves include backward integration into wafer supply and geographic co-location with 800V platform engineering centers.
Among German-based diversified suppliers, Robert Bosch and Continental occupy positions spanning inverter system integration and captive semiconductor production. Infineon Technologies exemplifies the component specialist archetype, anchoring silicon carbide die packaging expertise for traction inverter applications. These three entities represent how European vendors leverage vertical control over fabrication to defend margin pools against Asian competitors scaling module assembly capacity.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| Infineon Technologies |
| Vitesco |
| BorgWarner |
| STMicroelectronics |
| Denso Corporation |
| NXP Semiconductors |
| Wolfspeed |
| Others |
Supply & Pricing Matrix
Silicon carbide wafer supply concentration among Japanese and U.S. foundry operators funnels margin pools toward inverter module assemblers with captive die-attach capabilities. OEM procurement contracts now embed raw-material escalation clauses that transfer substrate cost volatility downstream.
Pricing Analysis
Configured-to-order pricing for 800V silicon carbide traction inverters commands spreads of 40-60% above standard 400V IGBT configurations. Pricing stratifies across premium, standard, and economy tiers based on semiconductor material grade and thermal interface certification tier. Cost compression in standard-efficiency modules is intensifying because Chinese foundry scale is eroding legacy silicon inverter margins. Fleet procurement teams at commercial vehicle operators exhibit highest price sensitivity, while premium passenger car OEMs absorb wide-bandgap premiums to meet EPA fleet efficiency mandates.
Supply Chain Analysis
Export-control regimes restricting wide-bandgap semiconductor equipment shipments to Chinese foundries are fragmenting substrate sourcing across Japan, the United States, and Germany. Power control unit production draws from silicon carbide wafers, copper thermal interface materials, and liquid-cooled aluminum housings. Single-source vulnerability concentrates in 6-inch SiC substrate supply where Wolfspeed and Coherent anchor capacity. Distribution runs through Tier 1 module assemblers co-located with OEM platform engineering centers in Michigan, Bavaria, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—EPA fleet rules and China's MIIT catalog—locks incumbent suppliers into multi-year qualification cycles that new entrants cannot shortcut.
For Market Incumbents: Entrench position by backward integration into silicon carbide wafer supply through joint ventures with Japanese or U.S. foundry partners. Accelerate thermal-integrated module assembly capacity in China's eastern manufacturing corridor to match BYD-tier procurement specifications. Gallium nitride DC/DC specialists represent the emerging entrant archetype threatening cost-tier margins.
For New Entrants and Emerging Players: Build out white-space presence in electric bus battery management systems where cell balancing complexity exceeds incumbent R&D bandwidth. Commercial vehicle electrification in North America presents the most penetrable procurement segment. Lead with FDA electromagnetic compatibility certification for electrified ambulance conversions to bypass direct inverter competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless design houses licensing silicon carbide IP to automotive foundries. Long-term viability hinges on 5-10 year OEM platform lock-in where switching costs exceed $50 million per qualification. Watch for MIIT catalog revisions expanding domestic content requirements as the inflection signal forcing portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Wafer Supply Agreement | Captive substrate access insulates margin pools from foundry allocation competition between automotive and consumer electronics customers. |
| Thermal-Integrated Module Assembly Scale-Up | Co-location with BYD-tier suppliers in China's Yangtze River Delta secures procurement volume concentration. |
| 800V Platform Engineering Partnership | Direct OEM collaboration accelerates silicon carbide MOSFET qualification timelines for premium passenger car programs. |
| FDA Electromagnetic Compatibility Certification | Isolation-rated designs unlock electrified ambulance and mobile health vehicle segments with regulatory tailwinds. |
| Gallium Nitride DC/DC Converter Development | Technology convergence with consumer electronics supply chains enables cost-positioning below 6.6kW charging tiers. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement directors, foundry operations managers, and thermal systems R&D leads and refined through secondary validation against SEC filings, EPA regulatory dockets, MIIT new-energy vehicle catalog releases, and IHS Markit vehicle production databases. Bottom-up unit economics modeling triangulated with top-down market sizing across silicon carbide inverter, battery management system, and DC/DC converter segments.
Demand-supply balance dynamics anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product architecture, voltage class, semiconductor material, end-use platform, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to OEM electrification roadmap disclosures and foundry capacity expansion announcements. Silicon carbide substrate yield rates and EPA fleet efficiency compliance penalties served as industry-specific forecast inputs.
Stress conditions across silicon carbide wafer pricing, foundry allocation ratios, and EPA rule stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM platform launch timing and wide-bandgap semiconductor adoption curves. Material shifts in U.S.-China semiconductor equipment export controls or MIIT domestic content thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Scooter Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market