
 Automotive Clutch Rotor Market | 2026-2036
Automotive Clutch Rotor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Clutch Rotor Market Outlook
Chinese foundry capacity for clutch rotor castings is decoupling from European forging traditions as cost structures diverge. BorgWarner leverages its dual-clutch transmission expertise to secure rotor supply contracts with premium German OEMs. Exedy Corporation anchors Asia-Pacific aftermarket distribution through its Thailand and Indonesia facilities. Schaeffler AG differentiates via integrated torque-converter and rotor module designs that reduce assembly complexity for vehicle assemblers.
An automotive clutch rotor is a friction-coupled disc assembly, typically 200-400 mm in diameter and 4-12 mm thick, that transmits engine torque to the transmission input shaft through pressure-plate engagement. It operates within 300-500°C thermal cycles and requires surface flatness tolerances below 0.05 mm to prevent shudder and premature wear. Manual clutch rotors retain dominant volume share in emerging-market passenger cars where cost sensitivity shapes procurement decisions. Dual-clutch variants command premium positioning in European and Chinese performance segments where shift-speed requirements drive material upgrades toward carbon-composite facings. Aftermarket providers represent a concentrated margin pool in Latin America and Southeast Asia where vehicle aging extends replacement cycles beyond OEM warranty periods.
FDA oversight of friction-material dust exposure in US remanufacturing facilities shapes workplace safety standards for aftermarket rotor handling. EPA particulate emissions rules for foundry operations raise production costs for steel and aluminum rotor suppliers operating in the Midwest. ECHA REACH compliance for hexavalent chromium alternatives in surface coatings limits European supplier formulations and extends qualification timelines for new friction facings. Stakeholders must monitor how EU Green Deal carbon-border adjustments reshape sourcing economics for Indian and Chinese rotor exporters serving European OEM assembly plants.
Market Dynamics
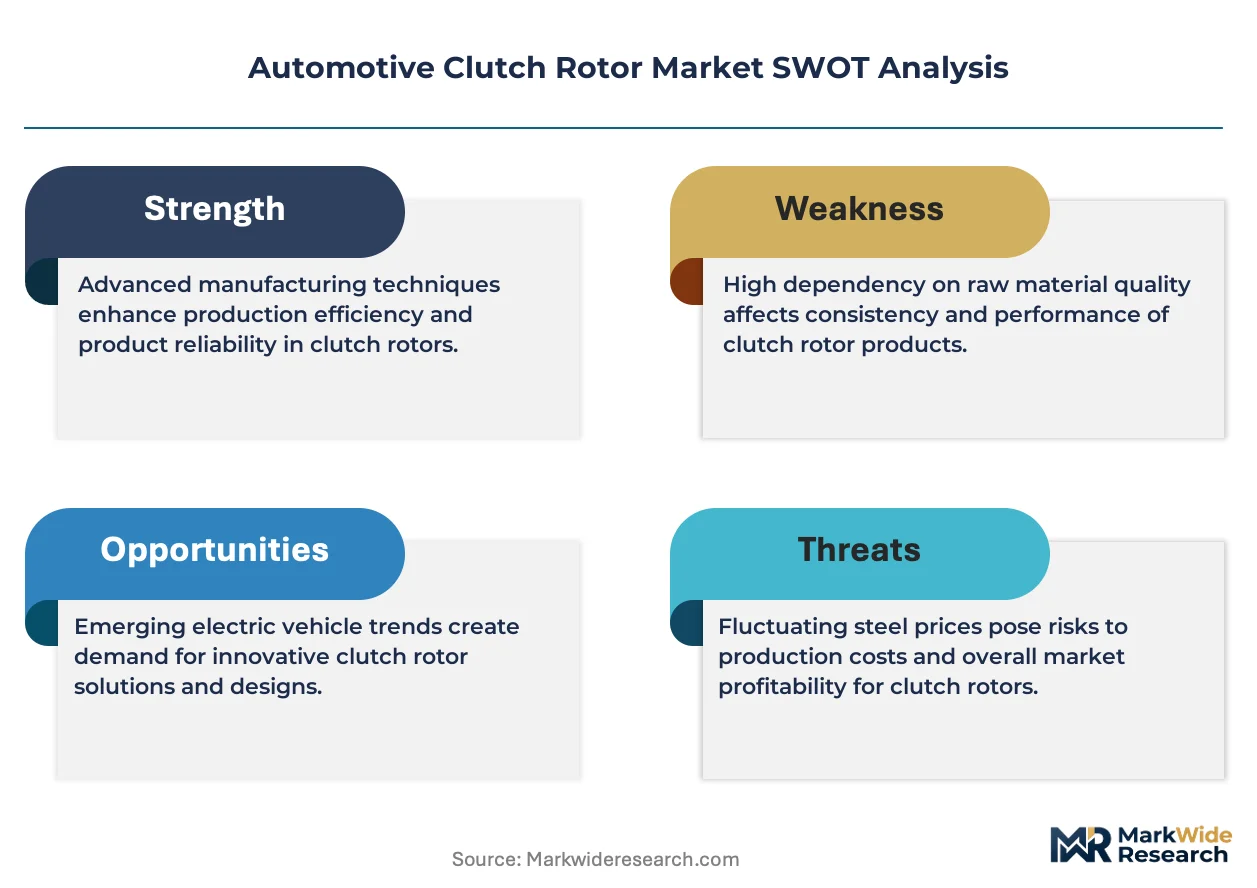
MIIT fuel-efficiency mandates in China are forcing OEMs to abandon traditional steel rotors for aluminum designs, compressing legacy supplier margins while opening procurement windows for lightweight foundry specialists.
Growth Catalysts
- Commercial fleet renewal:Heavy-duty clutch rotor orders from Indian and Brazilian logistics operators are climbing as transmission loads intensify on aging highway infrastructure.
- REACH compliance migration:European suppliers accelerating hexavalent chromium alternatives in surface coatings are qualifying new friction-facing formulations ahead of competitors.
- Dual-clutch transmission proliferation:Carbon-composite facing demand in German and Chinese performance segments is pulling material upgrades through the supply chain.
Market Restraints
- Foundry cost volatility:EPA particulate emissions rules for Midwest steel and aluminum foundries are raising production costs for rotor suppliers serving North American OEMs.
- Chinese supply concentration:Foundry capacity for clutch rotor castings is decoupling from European forging traditions, creating dependency risk on single-source geography.
- Friction-material substitution:Ceramic-matrix composites in high-performance electric vehicle couplings threaten traditional friction-facing volumes in premium segments.
Strategic Opportunities
- EU Green Deal carbon-border adjustments:Indian and Chinese rotor exporters can capture premium positioning by certifying low-carbon production ahead of 2026 implementation.
- Integrated module designs:Torque-converter and rotor module consolidation reduces assembly complexity for vehicle assemblers, creating vendor lock-in potential.
- Thailand aftermarket hub:Exedy Corporation's Indonesian and Thai distribution anchors Asia-Pacific replacement demand as vehicle aging extends cycles beyond OEM warranty periods.
Industry Challenges
- Surface flatness certification:Maintaining tolerances below 0.05 mm across 300-500°C thermal cycles requires metrology investments that strain mid-tier foundry balance sheets.
- Workplace safety compliance:FDA oversight of friction-material dust exposure in US remanufacturing facilities mandates capital-intensive ventilation upgrades for aftermarket handlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Clutch Rotor Market |
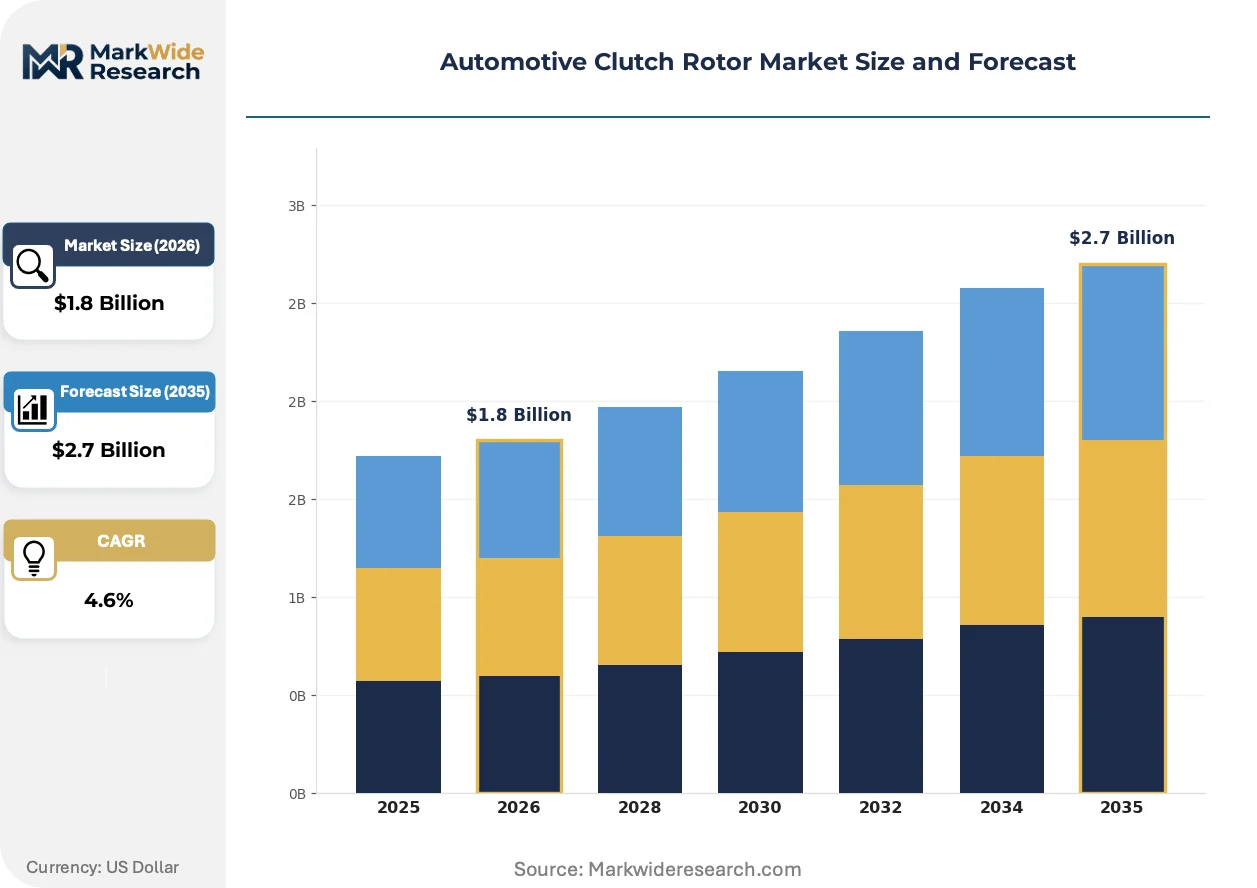
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Clutch, Automatic Clutch, Dual Clutch, Performance Clutch Material: Steel, Aluminum, Carbon, Composite Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Workshops |
| Companies Covered | Ogura Industrial Corp, BorgWarner, Exedy Corporation, Aisin Corporation, Schaeffler AG, Vortex Engineering Works India Private Limited, Indo Flux Engineers, Global Autotech Pvt. Ltd., LUK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Clutch Rotor Market Strategic Shifts
Material substitution and regulatory tightening are compressing traditional rotor design cycles while opening procurement advantages for suppliers with certified lightweight and low-emission production.
Aluminum rotor castings are overtaking forged steel in Chinese passenger car applications as MIIT mandates tighten. Domestic OEMs are qualifying lighter designs at accelerated pace to meet fleet-average targets. This shift is compressing legacy foundry margins while rewarding integrated suppliers with captive casting capacity.
ECHA REACH restrictions on hexavalent chromium in surface coatings are forcing European suppliers to reformulate friction-facing chemistries. Qualification timelines for new coatings have extended by eight to fourteen months, freezing incumbent supplier relationships. German precision manufacturers are responding by vertically controlling coating application to protect OEM contracts.
Aftermarket procurement in Latin America and Southeast Asia is fragmenting toward independent distributors as vehicle parc aging outpaces OEM service network expansion. Fleet operators in São Paulo and Jakarta are sourcing replacement rotors through regional trading houses rather than authorized dealers. This channel shift is compressing brand premiums while expanding volume opportunities for certified secondary suppliers with localized inventory.
Automotive Clutch Rotor Market Segmentation
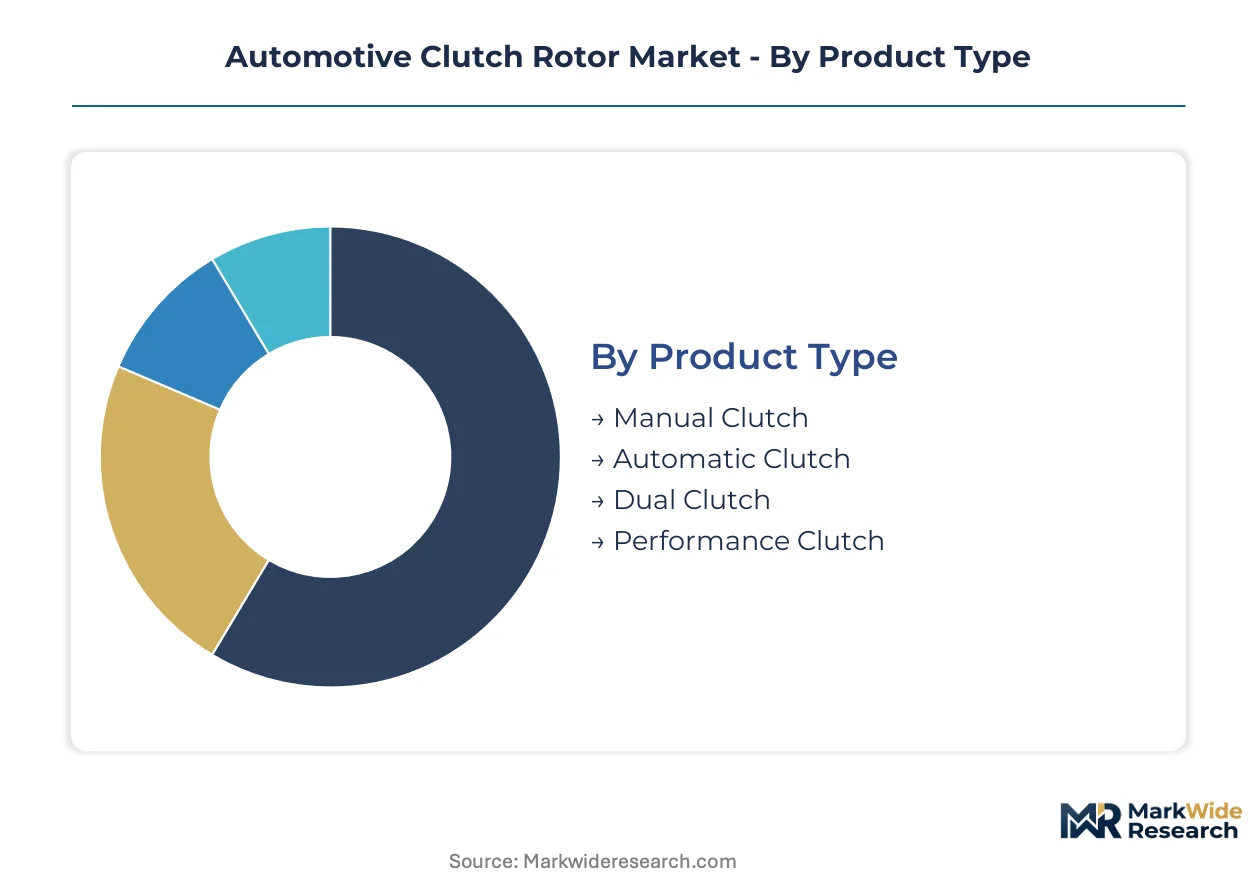
Clutch rotor procurement patterns diverge sharply between integrated powertrain modules and standalone replacement components. Understanding these structural splits reveals where margin pools concentrate and which material transitions are compressing legacy supplier economics.
Product Type:
Standalone manual clutch rotors dominate replacement channels, while embedded dual-clutch and automatic variants require deeper OEM integration partnerships.
- Manual Clutch:Friction-coupled disc assemblies measuring 200-400 mm in diameter operate within 300-500°C thermal cycles. Demand concentrates in Indian and Brazilian passenger car segments where cost sensitivity shapes fleet procurement decisions and transmission loads intensify on aging highway infrastructure.
- Dual Clutch:Carbon-composite facings enable sub-200 millisecond shift speeds in performance applications. German and Chinese OEMs are pulling material upgrades through supply chains as shift-speed requirements harden competitive positioning in premium segments.
- Automatic Clutch:Torque-converter integration reduces assembly complexity for vehicle assemblers seeking module consolidation.
- Performance Clutch:Ceramic-matrix composites threaten traditional friction-facing volumes in high-performance electric vehicle couplings.
Volume placements concentrate in Manual Clutch; the faster expansion belongs to Dual Clutch.
Material:
Cost tier stratification separates forged steel legacy supply from aluminum foundry specialists capturing MIIT-mandated lightweighting contracts.
- Steel:Traditional forged rotors retain aftermarket dominance where surface flatness tolerances below 0.05 mm prevent shudder. EPA particulate emissions rules for Midwest foundries are raising production costs for North American suppliers serving legacy OEM programs.
- Aluminum:Cast designs qualify at accelerated pace under China's MIIT fuel-efficiency mandates. Domestic OEMs are abandoning steel rotors to meet fleet-average targets, compressing legacy foundry margins while rewarding integrated suppliers with captive casting capacity.
- Carbon:High-performance facings command premium positioning in European performance segments.
- Composite:Multi-material laminates address thermal cycling durability in heavy-duty commercial applications.
Steel retains the largest installed base; aluminum is gaining share fastest as regulatory pressure intensifies.
Vehicle Type:
Application severity determines material specification, with commercial duty cycles demanding thicker cross-sections than passenger car equivalents.
- Passenger Cars:Aluminum rotor castings overtake forged steel in Chinese applications as MIIT mandates tighten. Domestic OEM qualification timelines have compressed from eighteen months to under twelve for lightweight designs meeting fleet-average targets.
- Heavy-Duty Trucks:400 mm diameter rotors with 12 mm thickness withstand intensified transmission loads. Indian and Brazilian logistics operators are expanding orders as commercial fleet renewal accelerates on aging highway infrastructure.
- Commercial Vehicles:Mid-duty applications bridge material specifications between passenger and heavy-duty requirements.
- Motorcycles:Compact 200 mm rotors prioritize heat dissipation in high-revving powertrains.
Passenger Cars absorb the highest unit volumes; Heavy-Duty Trucks follow the steepest expansion trajectory.
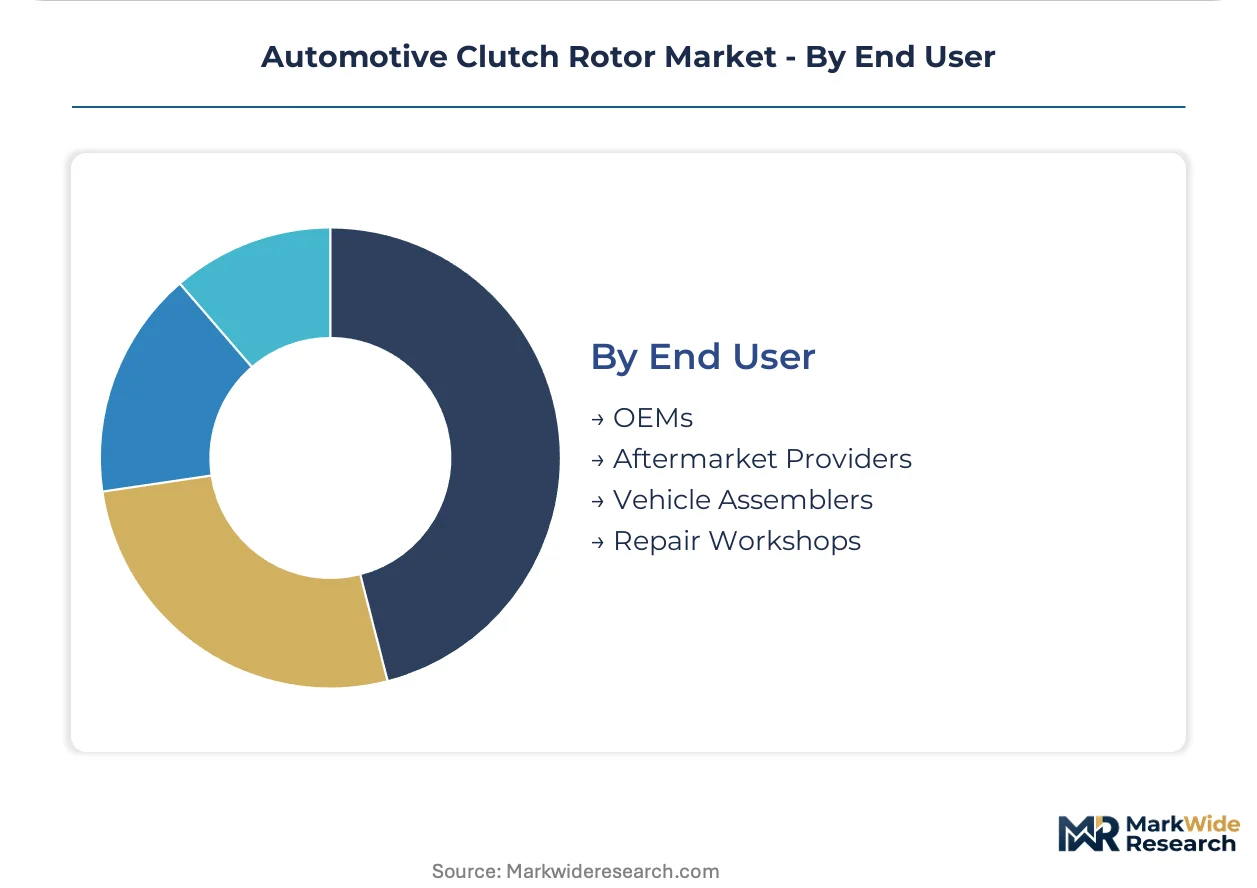
End User:
Customer type dictates channel economics, with OEM contracts requiring qualification investment that aftermarket players avoid.
- OEMs:Direct supply relationships demand ECHA REACH compliance for hexavalent chromium alternatives in surface coatings. German precision manufacturers are vertically controlling coating application to protect contracts as qualification timelines extend eight to fourteen months.
- Aftermarket Providers:Fragmented procurement in São Paulo and Jakarta is shifting toward independent distributors. Fleet operators source replacement rotors through regional trading houses rather than authorized dealers, compressing brand premiums while expanding volume opportunities for certified secondary suppliers.
- Vehicle Assemblers:Module consolidation preferences favor integrated torque-converter and rotor designs.
- Repair Workshops:Localized inventory requirements concentrate margin pools in Latin America and Southeast Asia where vehicle aging extends replacement cycles beyond OEM warranty periods.
Aftermarket Providers move the highest unit volumes; OEMs command the strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry-grade aluminum from Shanxi Province and high-strength steel from the Ruhr Valley anchor clutch rotor manufacturing across distinct regulatory environments. Raw-material proximity shapes regional competitive positioning as fuel-efficiency mandates and emissions rules diverge.
China
Domestic OEMs are accelerating aluminum rotor qualification timelines to meet MIIT fleet-average fuel-efficiency targets. The Ministry of Industry and Information Technology mandates have compressed supplier approval cycles from eighteen months to under twelve. Yangtze River Delta foundries in Jiangsu and Zhejiang provinces are capturing procurement windows as lightweight casting capacity expands.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria anchor European supply for dual-clutch transmission rotors. ECHA REACH restrictions on hexavalent chromium in surface coatings have extended qualification timelines eight to fourteen months, freezing incumbent supplier relationships. Stuttgart-area manufacturers are vertically integrating coating application to protect OEM contracts.
India
Commercial fleet operators in Maharashtra and Gujarat are expanding heavy-duty clutch rotor orders as highway infrastructure ages and transmission loads intensify. The Bureau of Indian Standards maintains quality certification requirements for automotive friction materials. Pune and Chennai industrial corridors concentrate foundry capacity serving both domestic OEMs and export markets.
Brazil
Logistics operators in São Paulo state are sourcing replacement rotors through independent distributors rather than authorized dealers as vehicle parc aging accelerates. ANVISA workplace safety standards govern friction-material handling in remanufacturing facilities. The ABC Paulista industrial belt hosts secondary suppliers capturing aftermarket volume from aging commercial fleets.
United States
EPA particulate emissions rules for Midwest steel and aluminum foundries are raising production costs for rotor suppliers serving Detroit-area OEMs. FDA oversight of friction-material dust exposure mandates ventilation upgrades in remanufacturing facilities. Michigan and Ohio industrial clusters face margin compression from regulatory compliance investments.
Automotive Clutch Rotor Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue aluminum foundry specialization and integrated module consolidation. The vendor base stratifies across three tiers: precision forging specialists serving European premium OEMs, high-volume casting operations capturing Chinese lightweighting contracts, and regional aftermarket distributors anchoring Latin American and Southeast Asian replacement channels. Dominant competitive moves include vertical integration into coating application and captive casting capacity expansion.
Among Germany-based precision manufacturers, Schaeffler AG exemplifies the integrated module archetype, while BorgWarner occupies a position bridging dual-clutch transmission expertise with rotor supply relationships. Japanese supplier Exedy Corporation represents the Asia-Pacific aftermarket anchor, with Indonesian and Thai facilities supporting regional distribution density.
| Leading Market Players |
|---|
| Ogura Industrial Corp |
| BorgWarner |
| Exedy Corporation |
| Aisin Corporation |
| Schaeffler AG |
| Vortex Engineering Works India Private Limited |
| Indo Flux Engineers |
| Global Autotech Pvt. Ltd. |
| LUK |
| Others |
Value Chain & Pricing Dynamics
German premium OEM procurement concentration anchors contract-based long-term offtake agreements that bundle rotor supply with torque-converter module integration. This buyer structure compresses pricing transparency while rewarding suppliers with ECHA REACH coating certification and captive foundry capacity.
Pricing Analysis
Warranty and service bundling separates OEM direct contracts from unbundled aftermarket transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Cost compression in legacy steel rotor tiers is intensifying because Chinese MIIT mandates accelerate aluminum design qualification. Fleet operators in São Paulo and Jakarta exhibit highest price sensitivity, while Stuttgart-area OEMs prioritize shift-speed performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German and Chinese vehicle assemblers seeking integrated module consolidation. Foundry-grade aluminum from Jiangsu and Zhejiang provinces and high-strength steel from the Ruhr Valley feed rotor manufacturing. Single-source vulnerability concentrates in Yangtze River Delta casting capacity serving domestic Chinese OEM programs. Distribution runs through authorized dealer networks for OEM supply and independent trading houses for Latin American aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECHA REACH hexavalent chromium restrictions erect barrier-to-entry moats for European suppliers with qualified coating formulations.
For Market Incumbents: Anchor OEM relationships through backward integration into surface coating application, protecting contracts as qualification timelines extend. Accelerate captive aluminum foundry expansion in Jiangsu province to capture MIIT-mandated lightweighting procurement. Ceramic-matrix composite substitution in electric vehicle couplings threatens traditional friction-facing volumes in premium segments. For New Entrants and Emerging Players: Launch via independent distributor networks in São Paulo and Jakarta aftermarket channels where vehicle parc aging outpaces OEM service expansion. Target heavy-duty commercial fleet renewal in Maharashtra and Gujarat where Bureau of Indian Standards certification creates qualified supplier scarcity. Pursue aluminum casting specialization with MIIT-compliant lightweight designs for Chinese domestic OEM qualification. For Investors and Strategic Acquirers: The window for entry favors aluminum foundry specialists with captive Yangtze River Delta capacity and REACH-compliant coating infrastructure. Long-term viability centers on suppliers positioned for EU Green Deal carbon-border adjustment premiums ahead of implementation. Monitor German OEM dual-clutch transmission platform decisions as inflection indicator for carbon-composite facing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Application | Protects German OEM contracts from ECHA REACH qualification delays. |
| Aluminum Foundry Capacity Expansion | Captures MIIT-mandated lightweighting procurement from Chinese domestic OEMs. |
| Aftermarket Distribution Partnership | Secures volume positioning in São Paulo and Jakarta independent trading channels. |
| Carbon-Composite Facing Qualification | Enables dual-clutch transmission supply relationships with Stuttgart-area assemblers. |
| EU Green Deal Carbon Certification | Positions Indian and Chinese exporters for premium European OEM sourcing. |
Study Parameters
Multi-period observation of MIIT qualification timelines, ECHA REACH compliance migration, and commercial fleet renewal patterns anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and foundry operations directors. Secondary validation drew from vehicle production databases, customs trade records, IHS Markit registration data, and regulatory filing repositories. Bottom-up segment sizing triangulated against top-down OEM procurement budget analysis.
Segment-weighting across product type, material specification, vehicle class, and regional production cluster shaped the analytical framework. CAGRs derived from production volume trajectories and content-per-vehicle assumptions across the projection horizon. Forecast inputs incorporated MIIT fleet-average efficiency targets, EPA foundry emissions compliance costs, and dual-clutch transmission platform penetration curves.
The model assumes a particular technology adoption path; alternative pathways for ceramic-matrix composite substitution in electric vehicle couplings would alter the outlook for traditional friction-facing demand. Forecasts reflect assumptions regarding regulatory implementation timing and OEM platform consolidation decisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Diesel Engine Market
Powertrain
Automatic Transmission Market
Powertrain
Engine Flush Market
Powertrain
Automotive Driveline Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Automotive Engine Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Brazil Automotive Actuators Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Automotive Haptic Accelerator Pedal Market