
 Automotive Belt Tensioner Pulley Market | 2026-2036
Automotive Belt Tensioner Pulley Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Belt Tensioner Pulley Market Analytics
Modular belt-drive system bundling is restructuring how OEMs source tensioner pulleys, shifting procurement from standalone components to integrated accessory-drive modules. Gates Corporation leverages its vertically integrated rubber-to-metal manufacturing to anchor long-term supply contracts with Detroit automakers. Continental competes through its Continental Belts and Pulleys division, which specializes in polymer-overmolded tensioner designs for European premium platforms.
An automotive belt tensioner pulley is a spring-loaded or fixed-position rotational component, typically manufactured from sintered steel or glass-reinforced polyamide, that maintains optimal serpentine belt tension to prevent slippage and reduce parasitic engine load. Its primary industrial purpose is to extend belt service life and improve accessory-drive efficiency in internal combustion and hybrid powertrains. Automatic tensioner configurations dominate OEM fitments due to their self-adjusting spring mechanisms, while the aftermarket channel sustains higher volumes for manual replacement units as vehicle fleets age. Steel pulleys retain the largest material share in heavy-duty commercial applications, though aluminum variants are gaining ground in passenger vehicles where weight reduction directly impacts fuel economy compliance.
The EPA enforces Corporate Average Fuel Economy standards that tighten accessory-drive efficiency thresholds, compelling suppliers to engineer lower-friction bearing architectures. REACH and RoHS frameworks in Europe restrict heavy-metal content in surface coatings, reshaping material selection for pulley finishes and spring components. NHTSA defect-investigation protocols in the United States create recall exposure for tensioner failures, elevating quality-system investments across the supply base. Stakeholders must monitor the pace of hybrid powertrain penetration and assess whether dedicated tensioner designs for belt-driven starter-generator systems warrant dedicated R&D allocation.
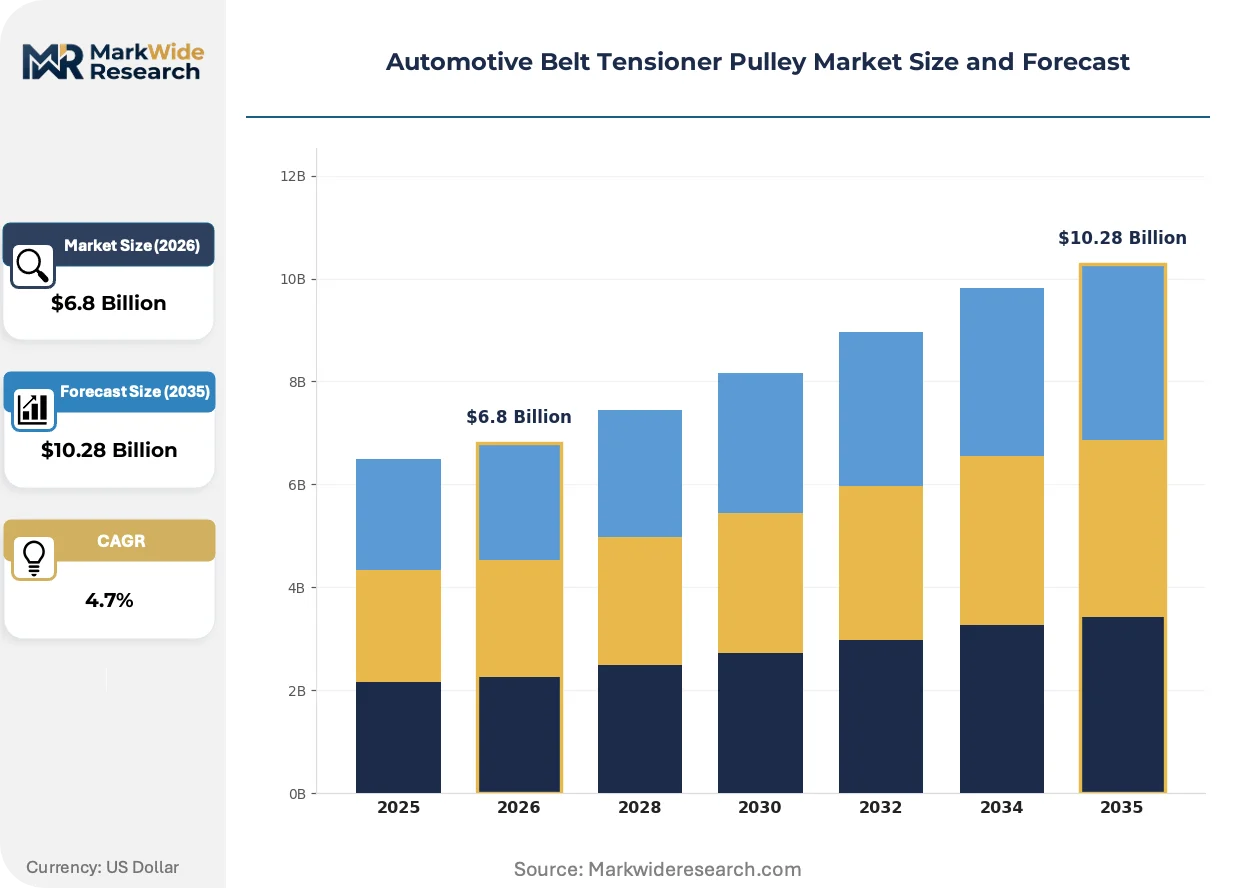
Market Dynamics
OEM bundling of integrated accessory-drive modules is collapsing standalone component procurement, forcing tensioner pulley suppliers to embed within larger system architectures or exit direct OEM relationships entirely.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Tightening accessory-drive efficiency thresholds compel adoption of low-friction bearing architectures across Detroit automaker platforms.
- Hybrid powertrain proliferation:Belt-driven starter-generator systems in 48V mild-hybrid architectures require dedicated tensioner designs with enhanced damping characteristics.
- China ICE production concentration:Domestic automakers in Shanghai and Guangzhou sustain volume demand for automatic tensioner configurations in mass-market passenger vehicles.
Market Restraints
- Steel input cost volatility:Sintered steel powder prices fluctuate with ferrous scrap markets, compressing margin stability for heavy-duty commercial pulley manufacturers.
- Supply concentration risk:German and Japanese bearing suppliers dominate precision ball-bearing supply for automatic tensioner mechanisms, creating single-source vulnerability.
- Electric vehicle substitution:Battery-electric powertrains eliminate accessory-drive belts entirely, eroding addressable market in premium passenger segments.
Strategic Opportunities
- India aftermarket expansion:Aging vehicle fleets in Delhi and Mumbai generate replacement demand for manual tensioner kits through independent service channels.
- EU Green Deal circularity mandates:Remanufacturing incentives create white space for refurbished tensioner assemblies with verified spring fatigue life.
- Polymer-overmolded convergence:Glass-reinforced polyamide pulleys fused with stamped steel hubs enable weight reduction without sacrificing load capacity.
Industry Challenges
- REACH coating compliance timelines:European suppliers face compressed certification cycles for hexavalent-chrome-free surface treatments on spring components.
- Integration complexity with modular belt-drive systems:Tensioner engineers must coordinate damping specifications with alternator and AC compressor suppliers under unified program management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Belt Tensioner Pulley Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Heavy-Duty, Light-Duty Material: Plastic, Aluminum, Steel, Composite Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Performance Vehicles End User: OEMs, Aftermarket, Repair Shops, Fleet Companies |
| Companies Covered | Gates Corporation, Continental, Dayco, Schaeffler, SKF, Litens Automotive Group, Hutchinson, NTN, Mitsuboshi Belting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Belt Tensioner Pulley Market Evolving Landscape
Material substitution and regulatory compression are forcing simultaneous evolution in pulley construction, surface engineering, and procurement architecture across the value chain.
Glass-reinforced polyamide pulleys with metal hub inserts are rewriting load-bearing assumptions for passenger vehicle accessory drives. Tier 1 suppliers in Stuttgart and Detroit are qualifying these hybrid constructions for alternator and power steering applications. The technology is rewriting supplier qualification protocols by demanding polymer rheology expertise alongside traditional metalworking capabilities.
REACH restrictions on heavy-metal content in surface coatings are forcing wholesale reformulation of pulley finishes and spring platings across European manufacturing footprints. Chromium-free passivation layers and zinc-nickel alloys now dominate new platform approvals. Premium German OEMs have accelerated supplier audits to verify coating chemistry documentation ahead of 2025 enforcement milestones.
Fleet operators and independent repair chains are consolidating aftermarket purchasing through integrated belt-kit bundles rather than standalone tensioner orders. Distributors in the US Midwest and Rhine-Ruhr corridor now stock pre-assembled modules containing pulley, bearing, and damping arm. This pattern is most visible in commercial vehicle segments where downtime costs override component-level price sensitivity.
Automotive Belt Tensioner Pulley Market Segmentation
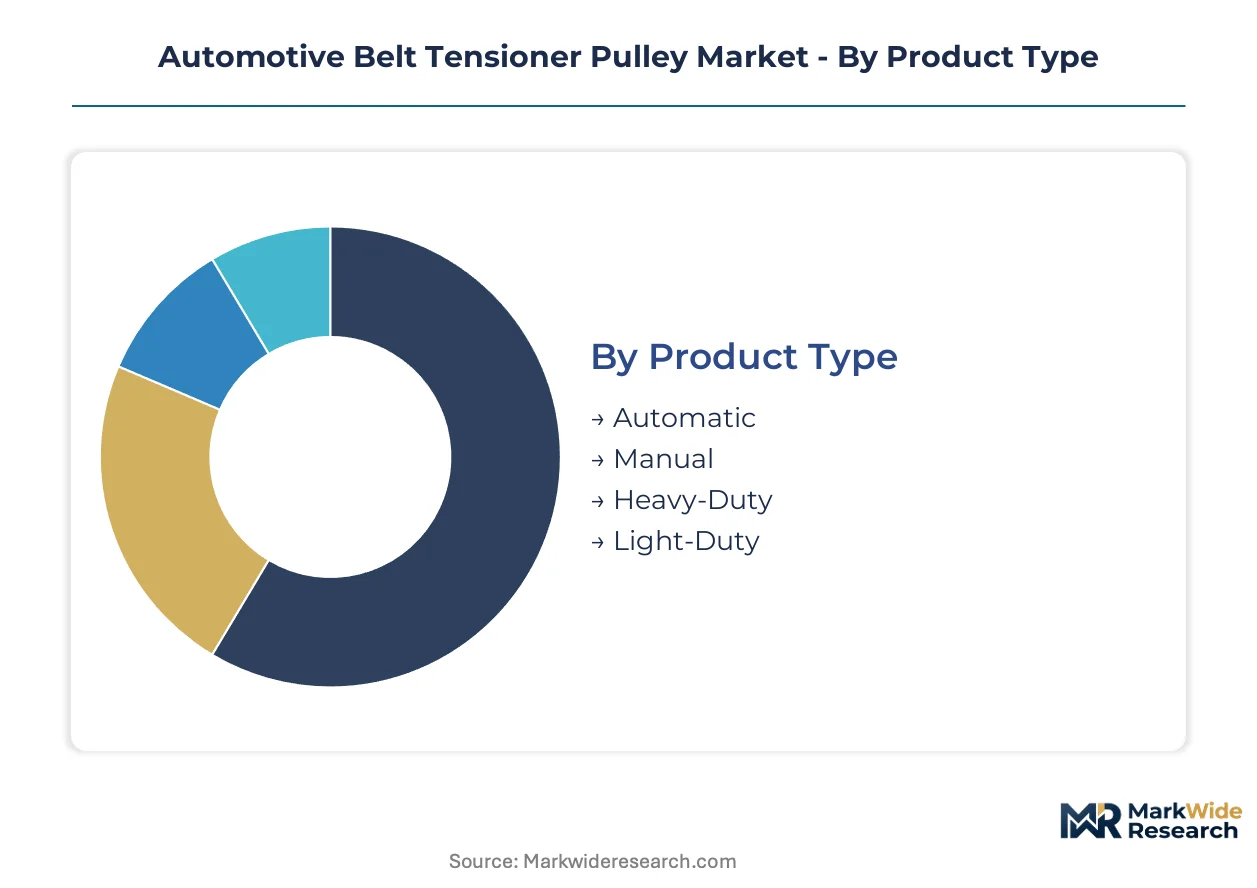
Segmentation in the automotive belt tensioner pulley market reveals how procurement power, material science, and powertrain architecture fragment demand across distinct buyer profiles and technical specifications. Understanding these divisions exposes where margin concentrates and where suppliers must adapt their engineering and channel strategies.
Product Type:
Automatic tensioners command premium pricing from OEMs seeking reduced warranty exposure, while manual configurations dominate cost-sensitive replacement channels.
- Automatic:Spring-loaded mechanisms with self-adjusting damping arms maintain optimal belt tension across thermal expansion cycles. Passenger vehicle OEMs in Germany and the United States specify these for 48V mild-hybrid belt-driven starter-generator systems where tension precision prevents NVH issues.
- Manual:Fixed-position pulleys require periodic adjustment via threaded pivot bolts. Fleet operators in India favor these for aging commercial vehicles where labor costs remain low and component simplicity enables roadside repair.
- Heavy-Duty:Reinforced bearing housings and thicker damping springs withstand sustained high-load operation in long-haul trucking applications.
- Light-Duty:Compact stamped-steel constructions serve economy passenger cars with minimal accessory loads.
Automatic configurations lead volumes today; Heavy-Duty is gaining share fastest in commercial electrification transition segments.
Material:
Material selection trade-offs center on weight reduction versus load capacity, with regulatory pressure on surface coatings reshaping supplier capabilities.
- Steel:Sintered powder-metal pulleys with induction-hardened raceways deliver maximum fatigue resistance. Commercial vehicle manufacturers in the United States specify these for alternator drives exceeding 15kW continuous load.
- Composite:Glass-reinforced polyamide fused with stamped steel hubs achieves 40% mass reduction versus solid metal. Stuttgart-based Tier 1 suppliers are qualifying these for European premium platforms where every gram impacts CO2 fleet averages.
- Plastic:Unreinforced thermoplastic pulleys serve low-tension idler positions in economy vehicle accessory drives.
- Aluminum:Cast or machined variants balance thermal conductivity with moderate weight savings in performance applications.
Steel retains the largest installed base; Composite is expanding most quickly as polymer-overmolded designs penetrate mid-range passenger segments.
Application:
Application segmentation tracks how duty cycles and operating environments dictate tensioner durability specifications and replacement frequency.
- Passenger Vehicles:Multi-ribbed serpentine configurations integrate alternator, AC compressor, and power steering pumps on single belts. Chinese domestic automakers in Shanghai sustain the highest procurement volumes for mass-market automatic tensioner assemblies.
- Commercial Vehicles:Severe-duty cycles with extended idle operation demand enhanced bearing sealing and corrosion-resistant coatings. Long-haul fleets operating across the Rhine-Ruhr corridor prioritize integrated belt-kit bundles to minimize roadside failures.
- Off-Road Vehicles:Contamination-resistant sealed bearings protect against dust and moisture ingress in construction and agricultural machinery.
- Performance Vehicles:High-RPM damping characteristics and reduced rotational inertia support supercharger and racing applications.
Passenger Vehicles anchor current demand; Commercial Vehicles show the steepest expansion trajectory as hybrid powertrain penetration extends belt-driven accessory architectures.
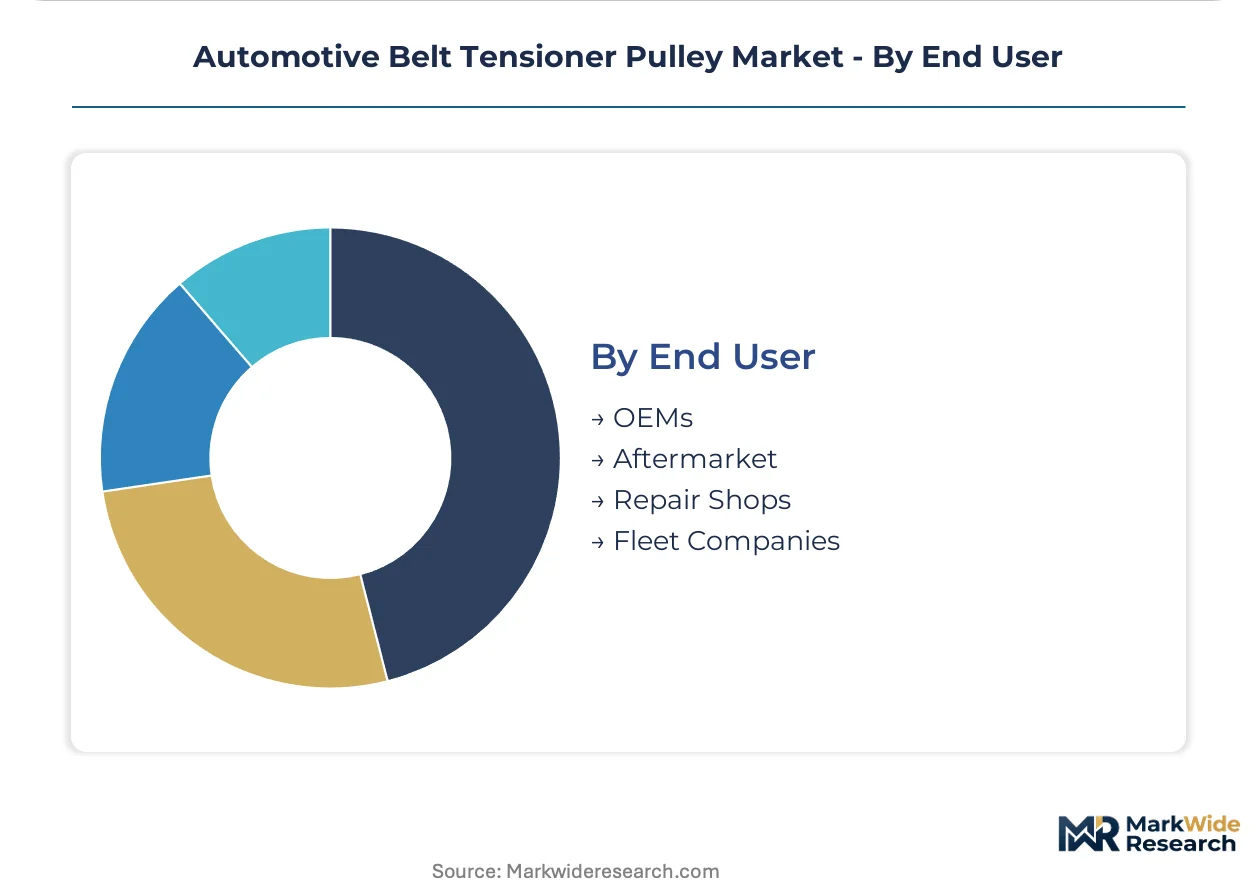
End User:
End user channels diverge sharply in technical sophistication, price sensitivity, and brand loyalty, forcing suppliers to maintain parallel product lines.
- OEMs:Original equipment manufacturers specify tensioners as integrated modules within complete accessory-drive systems. Detroit automakers require TS 16949-certified suppliers with statistical process control on spring fatigue life.
- Aftermarket:Independent distributors and e-commerce platforms serve DIY installers and small repair garages. Mumbai-based parts traders stock manual tensioner kits for Maruti and Tata vehicle parcs exceeding ten years average age.
- Repair Shops:Professional service bays demand pre-assembled kits with installation tools and torque specifications included.
- Fleet Companies:Centralized procurement of bulk belt-drive modules emphasizes total cost of ownership over unit price.
OEMs dominate value capture; Aftermarket channels deliver the highest unit volumes through fragmented independent distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive belt tensioner pulley industry traces its modern scaling to German precision engineering clusters that pioneered integrated accessory-drive systems for European premium platforms during the 1980s and 1990s.
United States
Detroit automakers specify automatic tensioner configurations for 48V mild-hybrid belt-driven starter-generator systems across light truck and SUV platforms. EPA Corporate Average Fuel Economy standards tighten accessory-drive efficiency thresholds annually, compelling suppliers to engineer lower-friction bearing architectures. Manufacturing concentration spans Michigan and Ohio, where Tier 1 suppliers operate TS 16949-certified facilities serving Ford, General Motors, and Stellantis assembly plants.
Germany
Stuttgart-based OEMs drive demand for polymer-overmolded tensioner designs that reduce rotational mass and improve CO2 fleet compliance. REACH restrictions on hexavalent-chrome surface coatings force wholesale reformulation of spring platings and pulley finishes ahead of 2025 enforcement milestones. The Baden-Württemberg and North Rhine-Westphalia industrial corridors host the densest concentration of tensioner R&D and precision bearing supply.
China
Domestic automakers in Shanghai and Guangzhou sustain the highest procurement volumes for mass-market automatic tensioner assemblies in internal combustion and hybrid passenger vehicles. MIIT fuel consumption regulations and dual carbon goals pressure suppliers to improve accessory-drive efficiency without sacrificing durability. The Yangtze River Delta and Pearl River Delta manufacturing basins concentrate stamping, sintering, and assembly capacity for both indigenous brands and joint ventures.
India
Aging vehicle fleets in Delhi and Mumbai generate replacement demand for manual tensioner kits through independent aftermarket channels serving Maruti and Tata vehicle parcs. BIS automotive component standards govern quality certification for domestic manufacturing, though enforcement varies across state-level industrial zones. The Maharashtra and Tamil Nadu automotive clusters host the primary tensioner assembly operations supplying both OEM fitments and aftermarket distributors.
Japan
Keiretsu-affiliated suppliers anchor automatic tensioner production for hybrid powertrains that dominate domestic and export passenger vehicle platforms. METI energy efficiency guidelines and JIS standards shape material selection and damping specification requirements. The Aichi and Kanagawa prefectures concentrate precision bearing and tensioner mechanism manufacturing within Toyota and Honda supply networks.
Automotive Belt Tensioner Pulley Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive rubber-to-metal and bearing manufacturing capabilities. Tier 1 suppliers compete through integrated accessory-drive module bundling that collapses standalone component procurement. Three archetypes dominate: vertically integrated belt-system specialists, precision bearing manufacturers extending into tensioner assemblies, and diversified automotive suppliers leveraging polymer expertise. M&A activity concentrates on polymer-overmolded technology acquisitions and regional aftermarket distribution networks.
Within the integrated belt-system tier, Gates Corporation and Continental exemplify archetypes combining rubber compounding with metal forming capabilities. Dayco occupies a position bridging OEM module supply and aftermarket channel density. Among precision bearing specialists, Schaeffler and SKF represent European engineering heritage applied to automatic tensioner mechanisms. These named companies anchor the competitive map without exhausting the supplier base, which includes additional regional fabricators and technology specialists.
| Leading Market Players |
|---|
| Gates Corporation |
| Continental |
| Dayco |
| Schaeffler |
| SKF |
| Litens Automotive Group |
| Hutchinson |
| NTN |
| Mitsuboshi Belting |
| Others |
Value Network & Pricing Analysis
Precision bearing machinists in Stuttgart and Aichi command wage premiums that compress margin spreads between premium OEM-grade and economy aftermarket tensioner tiers. Labor-cost differentials between German engineering clusters and Chinese manufacturing basins drive pricing stratification across automatic, manual, and heavy-duty product configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement architecture in this market. Price differentiation hinges on ISO/TS 16949 certification status and volume-scale commitments from Detroit automakers versus independent Mumbai distributors. Pricing pressure stems from steel powder input volatility squeezing heavy-duty commercial pulley manufacturers. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while German premium OEMs prioritize damping precision over unit cost.
Supply Chain Analysis
Freight cost escalation on precision ball-bearing shipments from Japan and Germany to North American assembly plants is reshaping regional sourcing strategies. Manufacturing concentrates in China, Germany, and the United States, with sintered steel powder, glass-reinforced polyamide resin, and precision bearings as critical inputs. Single-source vulnerability around Japanese and German bearing suppliers creates structural risk. Distribution runs through Tier 1 integrated module suppliers rather than direct component sales to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
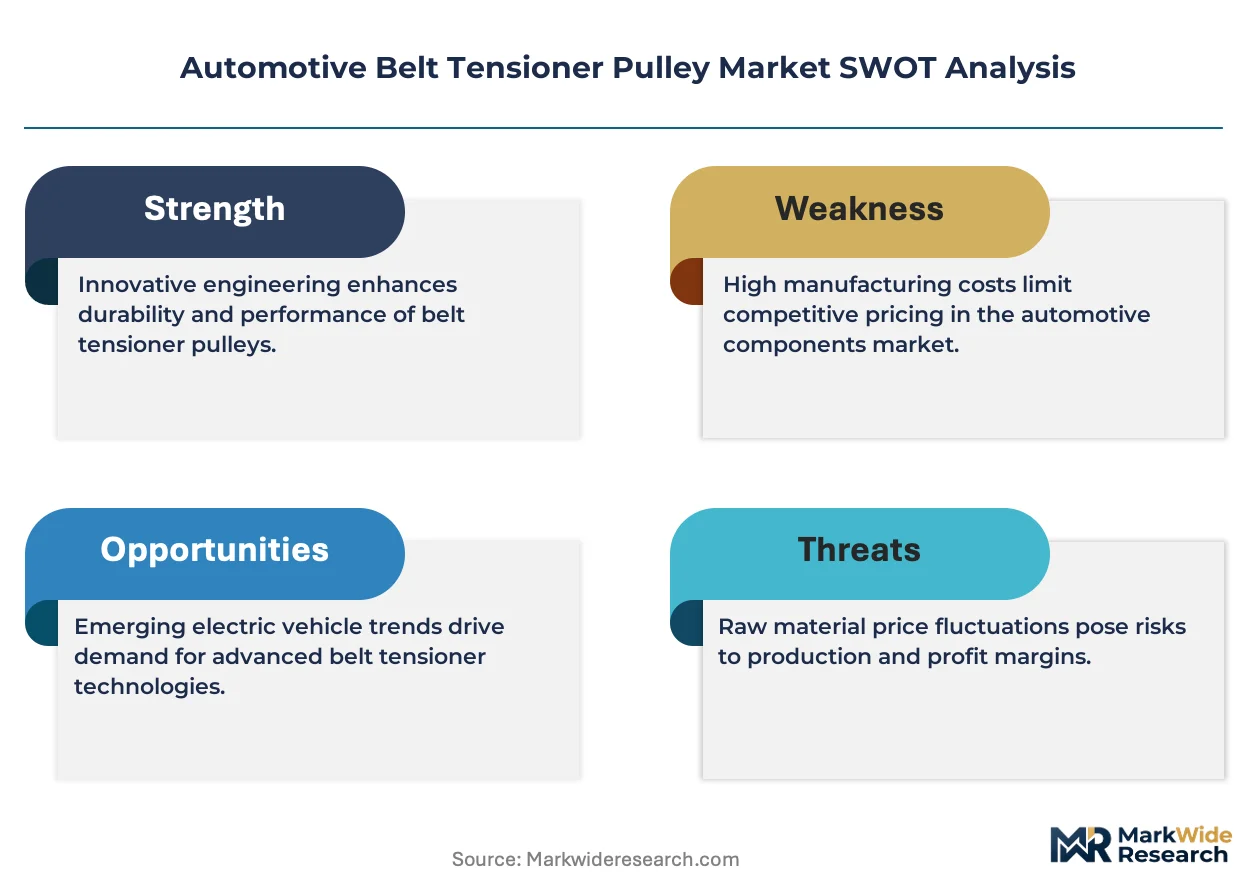
Analyst Recommendations
This market functions as a stable compounder anchored by persistent ICE and hybrid production volumes that sustain replacement demand across decades-long vehicle parcs.
For Market Incumbents: Deploy backward integration into sintered steel powder production to offset ferrous scrap volatility compressing heavy-duty pulley margins. Simultaneously deepen polymer-overmolded R&D capabilities to defend against composite substitution threats from emerging Asian suppliers. Control aftermarket channel density through pre-assembled belt-kit bundling that locks out standalone tensioner competitors. For New Entrants and Emerging Players: Independent fleet operators in India's aging commercial vehicle parc represent the most penetrable buyer archetype. Target manual tensioner kit distribution through Mumbai and Delhi aftermarket channels where labor costs favor simple pivot-bolt designs over automatic mechanisms. Pursue white-label manufacturing partnerships with established bearing suppliers to bypass capital-intensive damping-arm engineering. For Investors and Strategic Acquirers: Diversified automotive suppliers with captive polymer compounding capabilities are the most active acquirer in this space, seeking polymer-overmolded tensioner technology to complete accessory-drive module portfolios. Five-to-ten-year viability rests on hybrid powertrain persistence and commercial vehicle electrification timelines. Monitor 48V mild-hybrid platform ramp rates as the critical inflection signal for dedicated belt-driven starter-generator tensioner demand.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-Overmolded Technology Acquisition | Glass-reinforced polyamide pulleys with steel hubs enable 40% mass reduction for Stuttgart OEMs. |
| Regional Aftermarket Distribution Consolidation | Integrated belt-kit bundling through Midwest US distributors captures fleet operator loyalty. |
| Hexavalent-Chrome-Free Coating Certification | REACH-compliant zinc-nickel spring platings unlock 2025 European platform approvals. |
| 48V Mild-Hybrid Tensioner Platform Development | Enhanced damping specifications for belt-driven starter-generators anchor Detroit automaker contracts. |
| India Manufacturing Footprint Expansion | Maharashtra and Tamil Nadu assembly operations serve domestic OEM and aftermarket channels. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors in Mumbai and Detroit, and precision bearing manufacturing heads grounded this analysis. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA fuel economy filings, and REACH compliance documentation. Bottom-up and top-down triangulation cross-checked segment-level demand against national powertrain production forecasts.
Bottom-up modeling aggregated content-per-vehicle assumptions across passenger, commercial, and off-road segments by propulsion architecture and regional production cluster. Top-down verification anchored aggregate market value against disclosed supplier revenues and macroeconomic automotive production indices. CAGRs emerged from regression analysis of historical penetration rates and regulatory efficiency threshold trajectories. Hybrid powertrain adoption curves and commercial vehicle fleet replacement cycles served as key forecast inputs.
Inputs from OEM platform engineers and Tier 1 procurement leads were available through the study window; gaps in proprietary damping-arm fatigue testing data introduce uncertainty bands around automatic tensioner longevity assumptions. Forecasts reflect documented assumptions about ICE phase-out timelines and hybrid architecture persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Clutch Friction Plate Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Drive Shaft Market
Powertrain
Gas Engine Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Racing Clutches Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Europe Automatic Transmission for Passenger Car Market