
 EV Thermal Management System Market | 2026-2036
EV Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
EV Thermal Management System Market Analysis
OEM procurement of integrated thermal modules is consolidating as battery-electric platforms standardize on 800-volt architectures. DENSO Corporation leverages its power electronics cooling heritage to anchor contracts with Japanese and European automakers. MAHLE GmbH competes through its integrated e-axle thermal systems, while Hanon Systems specializes in refrigerant-based heat pump assemblies for cold-climate vehicle programs.
An EV Thermal Management System regulates battery, motor, and power electronics temperatures through liquid coolant loops, refrigerant circuits, and phase change materials, maintaining cell temperatures between 15°C and 35°C to prevent thermal runaway and preserve cycle life. Active Cooling dominates value capture due to its necessity in high-energy-density battery packs, while Heat Pump technology leads growth as cold-weather range preservation becomes a purchase criterion. Liquid Cooling occupies the largest installed base, though Phase Change Materials are gaining traction in solid-state battery prototypes where conventional fluid channels face geometric constraints.
NHTSA battery thermal propagation standards, ECHA REACH restrictions on fluorinated refrigerants, and MIIT new energy vehicle efficiency mandates collectively force redesigns of coolant chemistries and system architectures. China's GB standards for battery safety testing and the EU's F-Gas Regulation on high-GWP refrigerants further constrain supplier design choices. Stakeholders must monitor regulatory divergence between refrigerant phase-down schedules and battery thermal runaway test protocols to avoid stranded engineering investments.
Market Dynamics
800-volt battery architectures are forcing wholesale redesigns of coolant flow rates, pump specifications, and heat exchanger sizing across supplier engineering departments.
Growth Catalysts
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology requires new energy vehicles to meet stringent thermal efficiency thresholds, compelling automakers to upgrade from air-cooled to liquid-cooled battery packs.
- High-Energy-Density Cells:Lithium-ion chemistries exceeding 300 Wh/kg generate heat loads that demand active thermal regulation, expanding the addressable hardware base for cooling module suppliers.
- German Fleet Electrification:Logistics operators across Bavaria and Baden-Württemberg are procuring integrated cooling systems for medium-duty electric trucks, consolidating supplier relationships.
Market Restraints
- Copper and Aluminum Volatility:Heat exchanger fabrication depends on base metal prices that swing with commodity cycles, compressing module margins during inflationary periods.
- Fluorinated Refrigerant Supply Concentration:ECHA REACH restrictions on high-GWP chemistries have thinned the European supplier base for compliant refrigerants, creating procurement bottlenecks.
- Geometric Constraints in Solid-State Designs:Next-generation cell architectures with ceramic electrolytes resist conventional channel-based cooling, limiting retrofit opportunities.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are drawing cooling system suppliers to Gujarat and Tamil Nadu manufacturing corridors.
- Refrigerant-to-Coolant Convergence:Integrated heat pump architectures that merge R-1234yf circuits with glycol loops enable cold-climate range recovery, opening premium vehicle segments.
- Direct-to-Fleet Distribution:Electrified logistics operators in California and Texas are bypassing traditional tiered distribution to source thermal modules directly from Tier-1 suppliers.
Industry Challenges
- Thermal Simulation Talent Scarcity:Computational fluid dynamics expertise for battery pack modeling commands premium wages, constraining supplier engineering bandwidth.
- NHTSA Propagation Test Certification:Battery thermal runaway validation protocols require months of testing cycles, delaying platform launches and freezing engineering resources.
- Legacy HVAC Integration Complexity:Cabin climate systems from prior vehicle generations resist seamless coupling with new battery cooling loops, forcing redundant control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Thermal Management System Market |
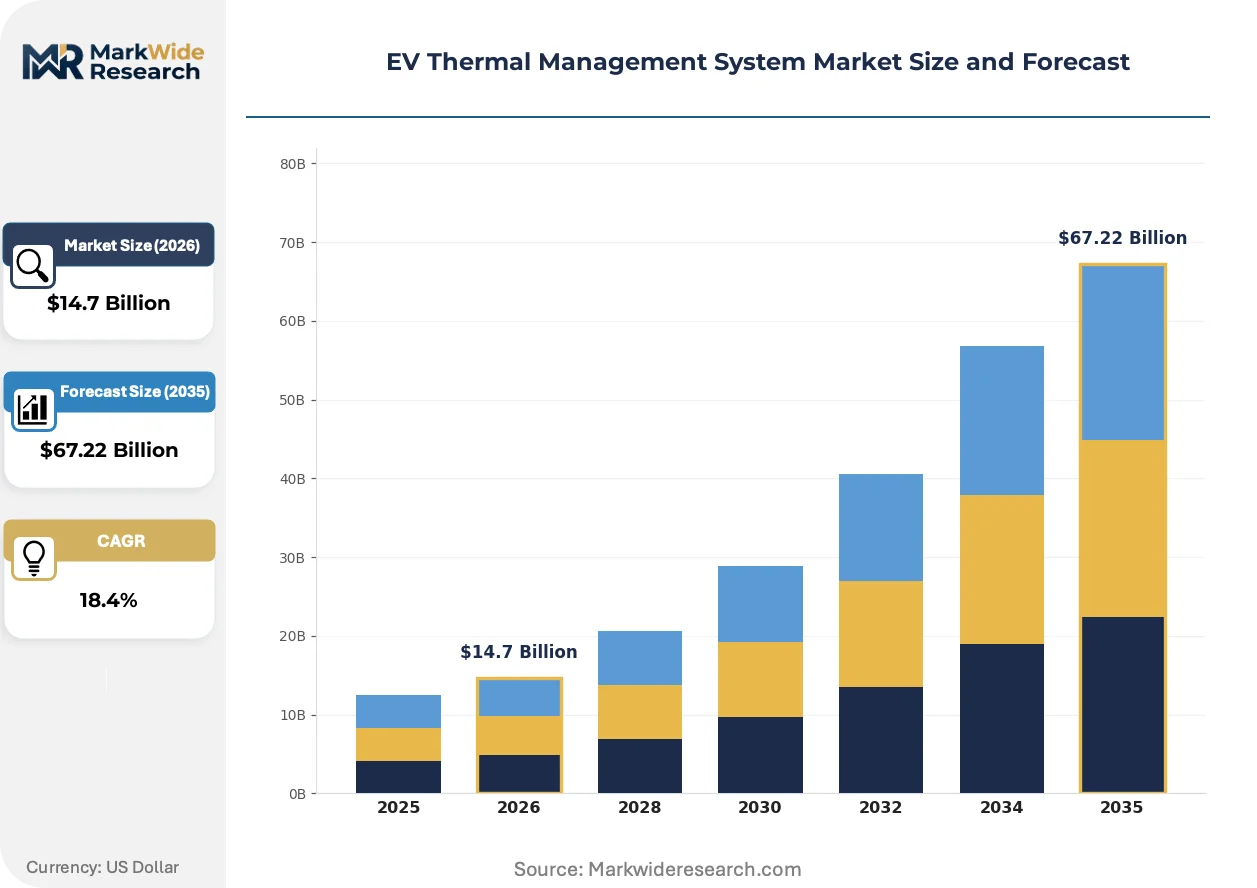
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $67.22 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Cooling, Passive Cooling, Heating Systems, Thermal Energy Storage End User: OEMs, Aftermarket Providers, Fleet Operators, Rental Services Technology: Liquid Cooling, Air Cooling, Phase Change Materials, Heat Pumps Application: Battery Systems, Electric Motors, Power Electronics, HVAC Systems |
| Companies Covered | MAHLE GmbH, Sanden Holdings Corporation, DENSO Corporation, Yinlun Machinery, Aotecar New Energy Technology, Hanon Systems, Sanhua Intelligent Controls, Gentherm Incorporated, Valeo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Thermal Management System Market Emerging Trajectories
Engineering teams are converging on unified thermal circuits that merge power electronics, battery, and cabin conditioning into single refrigerant architectures.
Immersion cooling using dielectric fluids is overtaking cold plate designs in high-performance electric vehicle programs. Porsche and Rimac engineering specifications now specify direct cell contact with engineered fluids rather than indirect glycol circulation. This shift is compressing the addressable market for traditional aluminum cold plate fabricators while expanding opportunities for fluorinated fluid compounders.
The EU F-Gas Regulation is accelerating refrigerant chemistry transitions across supplier R&D pipelines. Manufacturers must phase down high-GWP compounds in heat pump assemblies, forcing reformulation of working fluids and compressor lubricants. German and French automakers are most exposed, with 2027 compliance deadlines already freezing architecture decisions for 2030 model year vehicles.
Fleet procurement departments are consolidating supplier relationships around vertically integrated thermal module providers. Large logistics operators in the United States now specify single-source accountability for battery cooling, cabin HVAC, and power electronics conditioning. This concentration is most visible in California's Central Valley, where temperature extremes punish fragmented thermal system sourcing.
EV Thermal Management System Market Segmentation
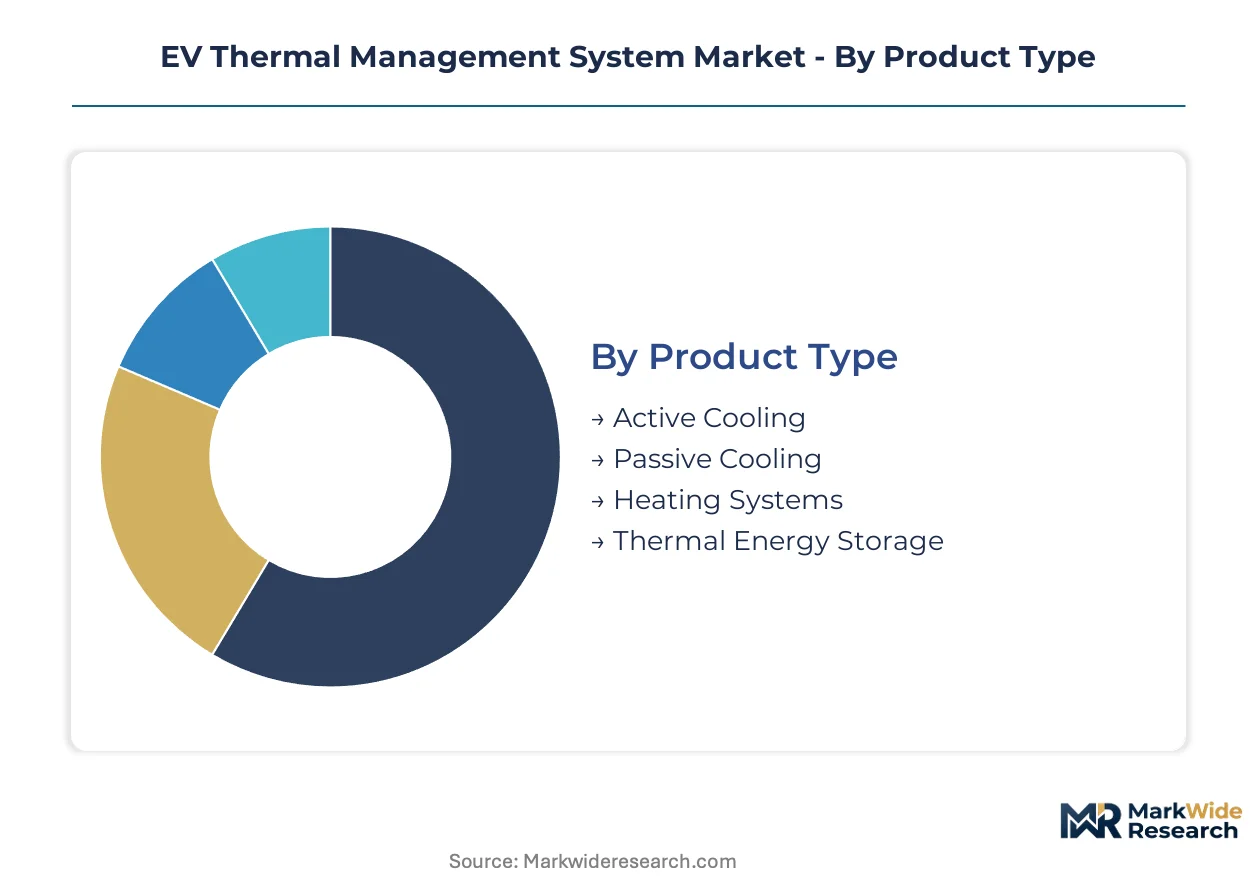
Segmentation in EV thermal management reveals how engineering specifications diverge across voltage architectures and climate zones. Procurement patterns cluster around integrated module suppliers capable of serving multiple temperature regulation functions simultaneously.
Product Type:
Upgrade cycles accelerate as 400-volt platforms migrate to 800-volt architectures, forcing wholesale replacements of pumps, heat exchangers, and control modules.
- Active Cooling:Pump-driven liquid circulation through cold plates and chiller circuits handles heat loads exceeding 300 Wh/kg cell densities. German and Chinese automakers specify these systems for performance electric sedans where thermal runaway prevention is non-negotiable.
- Passive Cooling:Conductive heat sinks and natural convection assemblies serve low-cost urban mobility vehicles with modest energy densities. Indian two-wheeler electrification programs and Southeast Asian microcar initiatives concentrate procurement here due to cost constraints.
- Heating Systems:Positive temperature coefficient heaters and high-voltage immersion elements maintain battery temperatures during sub-zero charging cycles.
- Thermal Energy Storage:Phase-change material reservoirs buffer transient heat spikes in solid-state battery prototypes undergoing pre-commercial validation.
Active Cooling sits at the top of the volume ranking, with Thermal Energy Storage climbing the fastest.
End User:
Customer concentration patterns reflect diverging technical capabilities across the value chain, with direct procurement reshaping traditional tiered distribution.
- OEMs:Integrated platform engineering teams specify complete thermal architectures during vehicle development cycles, locking in multi-year supply agreements with DENSO, MAHLE, and Hanon Systems for 800-volt programs.
- Fleet Operators:California and Texas logistics providers now source battery cooling modules directly from Tier-1 suppliers, bypassing aftermarket distributors to secure single-source accountability for temperature-critical assets operating in desert corridors.
- Aftermarket Providers:Independent service networks focus on refrigerant recharge, pump replacement, and sensor recalibration for out-of-warranty vehicles.
- Rental Services:Short-term mobility operators prioritize rapid thermal system diagnostics and modular component swaps to minimize fleet downtime.
OEMs command the largest procurement volumes, while Fleet Operators are gaining share fastest through direct sourcing initiatives.
Technology:
Technology selection tracks regulatory pressure on refrigerant chemistries and geometric constraints in next-generation cell architectures.
- Liquid Cooling:Glycol-water mixtures circulating through aluminum cold plates dominate current production, with MIIT mandates in China and NHTSA thermal propagation standards in the United States cementing this architecture as the baseline for high-energy-density packs.
- Heat Pumps:Refrigerant-based systems recovering waste heat from power electronics and ambient air deliver cold-climate range preservation. ECHA REACH restrictions on high-GWP compounds are forcing rapid reformulation of working fluids across European supplier R&D pipelines.
- Air Cooling:Forced convection through finned heat sinks persists in cost-sensitive applications with lower thermal loads.
- Phase Change Materials:Paraffin and salt-hydrate compounds absorbing latent heat at constant temperature suit solid-state designs where fluid channels face geometric constraints.
Liquid Cooling holds the dominant installed position, with Heat Pumps expanding most quickly on cold-weather range imperatives.
Application:
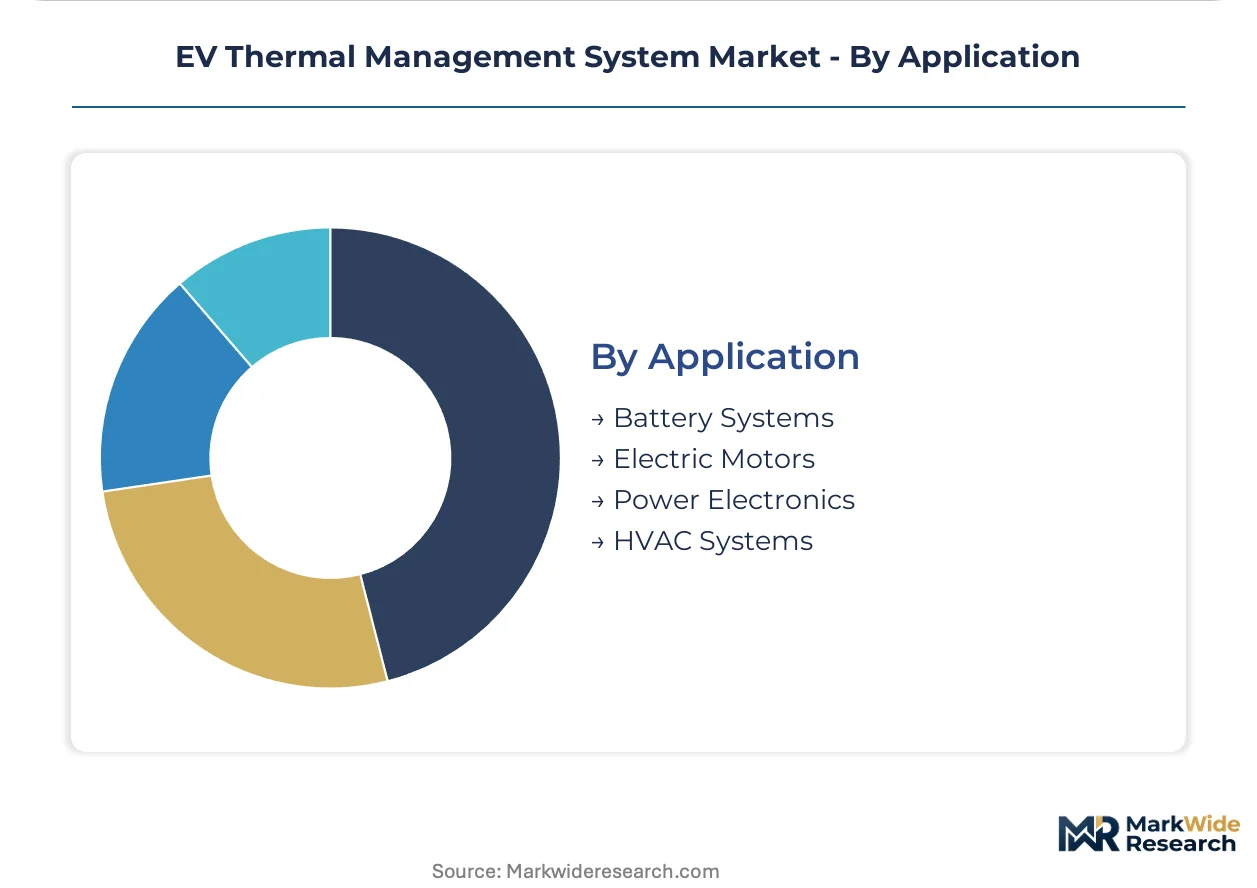
Application segmentation reveals converging thermal circuits that merge previously isolated temperature regulation functions into unified architectures.
- Battery Systems:Cell-level temperature uniformity within 15°C to 35°C bands determines cycle life and safety certification. German automakers and Chinese battery manufacturers specify multi-zone cooling to prevent thermal gradients that accelerate degradation.
- Power Electronics:Silicon carbide inverters and onboard chargers generate localized heat spikes demanding dedicated cooling loops with higher flow rates than battery circuits.
- Electric Motors:Stator windings and rotor bearings require oil or glycol cooling to maintain efficiency at sustained high loads.
- HVAC Systems:Cabin climate control increasingly shares refrigerant circuits with battery conditioning through integrated heat pump architectures.
Battery Systems anchor procurement volumes, with Power Electronics gaining priority fastest as 800-voltage architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's fleet electrification programs outpace North American deployment timelines, while China's MIIT mandates compress supplier upgrade cycles faster than ECHA regulatory phases in Europe.
China
MIIT efficiency mandates for new energy vehicles compel automakers to abandon air-cooled battery packs for liquid-cooled architectures. GB standards for battery safety testing impose thermal runaway propagation protocols that reshape supplier qualification criteria. The Yangtze River Delta manufacturing corridor concentrates cooling module production for domestic EV platforms and export programs.
Germany
Logistics operators in Bavaria and Baden-Württemberg procure integrated cooling systems for medium-duty electric trucks, consolidating supplier relationships around single-source accountability. The EU F-Gas Regulation phases down high-GWP refrigerants in heat pump assemblies, forcing 2027 compliance deadlines for 2030 model year vehicles. Stuttgart's engineering clusters anchor development of 800-volt thermal architectures for premium electric sedans.
United States
California and Texas logistics providers source battery cooling modules directly from Tier-1 suppliers, bypassing aftermarket distributors to secure temperature-critical asset protection in desert corridors. NHTSA battery thermal propagation standards mandate months-long validation protocols that freeze engineering resources and delay platform launches. The Central Valley's electrified freight hubs concentrate demand for unified thermal circuits merging battery, cabin, and power electronics conditioning.
Japan
METI carbon neutrality roadmaps accelerate domestic EV platform development, expanding procurement of integrated thermal modules from established supplier relationships. JIS standards for automotive thermal systems constrain coolant chemistry selections and heat exchanger material specifications. Nagoya's automotive engineering clusters host development programs for refrigerant-to-coolant convergence architectures.
India
PLI scheme incentives for advanced chemistry cell manufacturing draw cooling system suppliers to Gujarat and Tamil Nadu production corridors. BIS standards for battery safety testing emerge as domestic EV adoption scales beyond two-wheeler segments. Chennai's manufacturing belt concentrates module assembly operations serving both domestic automakers and export markets.
EV Thermal Management System Market Vendor Landscape
German and Japanese producers anchor the premium tier through integrated e-axle and power electronics cooling heritage; Chinese specialists hold volume positions through cost-optimized module fabrication for domestic EV platforms. The supplier base stratifies across three archetypes: diversified automotive conglomerates with thermal system divisions, pure-play cooling module specialists, and diversified industrial component fabricators extending into EV applications. Competitive moves concentrate on strategic partnerships for 800-volt architecture development and geographic expansion into India PLI corridors.
Within the diversified automotive supplier tier, MAHLE GmbH and DENSO Corporation exemplify integrated thermal system providers leveraging legacy powertrain cooling expertise into battery-electric platforms. Hanon Systems occupies a position among refrigerant-based heat pump specialists serving cold-climate vehicle programs. These three entities represent contrasting geographic anchors—German, Japanese, and Korean respectively—within a competitive structure where regional regulatory alignment increasingly determines supplier qualification.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Sanden Holdings Corporation |
| DENSO Corporation |
| Yinlun Machinery |
| Aotecar New Energy Technology |
| Hanon Systems |
| Sanhua Intelligent Controls |
| Gentherm Incorporated |
| Valeo Group |
| Others |
Supply Flow & Price Mechanics
ECHA REACH restrictions on fluorinated refrigerants gate qualified supply access and premium-tier pricing power for heat pump assemblies serving European OEM programs. Suppliers holding compliant chemistry portfolios command 15-20% price premiums over conventional refrigerant providers facing phase-down deadlines.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing corridor are reshaping price floors for liquid cooling modules as domestic cell production scales. Three-tier pricing structure across premium, standard, and economy levels separates immersion-cooled high-performance systems from glycol-based architectures and passive air-cooled assemblies. Cost compression in standard-tier cold plates is intensifying because aluminum extrusion capacity expanded faster than 800-volt platform adoption. Fleet operators in California's Central Valley demonstrate lowest price sensitivity due to asset-critical temperature requirements, while Indian two-wheeler electrification programs drive economy-tier procurement.
Supply Chain Analysis
Freight costs from Chinese cooling module production hubs to European assembly plants have compressed margins for Tier-1 suppliers serving Stuttgart and Munich engineering clusters. Manufacturing concentrates in China, Germany, and Japan, with each geography anchoring distinct technology tiers. Supply chains draw from copper and aluminum base metal markets, fluorinated refrigerant compounders, and precision pump manufacturers. Single-source vulnerability in high-GWP refrigerant supply creates procurement bottlenecks for European heat pump programs. Distribution runs through OEM platform engineering teams for original equipment, with direct-to-fleet channels emerging in California and Texas logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV thermal management functions as a stable compounder anchored by irreplaceable hardware content per vehicle as electrification penetration deepens across passenger and commercial segments.
For Market Incumbents: To counter margin compression from commodity metal volatility, DENSO and MAHLE should deepen backward integration into aluminum cold plate fabrication and secure long-term offtake agreements with copper suppliers. Certification investment in NHTSA thermal propagation test protocols creates switching costs that freeze competitor qualification timelines. Channel control through direct fleet procurement relationships in California and Texas logistics corridors defends pricing power against aftermarket distributors. For New Entrants and Emerging Players: Fleet procurement departments represent the most penetrable buyer archetype as electrified logistics operators bypass traditional tiered distribution for single-source thermal accountability. India's PLI scheme corridors in Gujarat and Tamil Nadu offer white-space manufacturing access with production-linked incentive coverage. A go-to-market angle targeting refrigerant-to-coolant convergence architectures for cold-climate range recovery opens premium vehicle segments underserved by legacy HVAC suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play cooling module specialists without power electronics heritage, as diversified conglomerates trade at integration premiums. Long-term viability favors suppliers with 800-volt architecture qualification and solid-state battery cooling R&D pipelines. The signal to watch is MIIT mandate acceleration forcing air-to-liquid cooling upgrades across Chinese EV platforms, which would inflect module demand sharply upward.| Strategic Initiative | Industry Significance |
|---|---|
| 800-Volt Architecture Qualification | Locks in multi-year supply agreements with German and Japanese OEM platform teams. |
| Refrigerant Chemistry Reformulation | Enables ECHA REACH compliance for European heat pump assembly contracts. |
| Direct Fleet Distribution Buildout | Bypasses aftermarket channels to capture California and Texas logistics procurement. |
| Immersion Cooling R&D Investment | Positions for Porsche and Rimac high-performance electric vehicle specifications. |
| India Manufacturing Footprint Expansion | Captures PLI scheme incentives serving domestic automakers and export markets. |
Methodological Framework
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, fleet operations managers, and thermal system R&D directors grounded qualitative findings in operational reality. Secondary validation drew from NHTSA regulatory filings, MIIT new energy vehicle efficiency disclosures, ECHA REACH substance restriction updates, and vehicle production databases. Bottom-up module demand estimates triangulated against top-down electrification penetration forecasts across passenger and commercial segments.
Segmentation outputs reflect disaggregation by cooling technology type, voltage architecture tier, end-user procurement channel, and regional regulatory cluster across the analysis window. CAGRs were derived from installed base replacement cycles, platform standardization timelines, and mandate-driven upgrade imperatives. Key inputs included 800-volt migration curves, solid-state battery commercialization pathways, and refrigerant phase-down schedules under EU F-Gas Regulation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state battery geometric constraints, copper price volatility, and divergence between regional thermal runaway test protocols. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
US Electric Vehicle Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market