
 New Energy Vehicle Scroll Compressor Market | 2026-2036
New Energy Vehicle Scroll Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
New Energy Vehicle Scroll Compressor Market Insights
Modular thermal management packaging is consolidating buyer choice around integrated compressor-inverter-refrigerant modules rather than standalone components. Denso Corporation leverages its inverter technology leadership to anchor premium module supply for Japanese and European OEMs. Hanon Systems competes through geographic dominance in Korean and Chinese passenger vehicle programs. Shanghai Highly (Group) specializes in cost-optimized scroll platforms for domestic Chinese e-bus and commercial vehicle thermal systems.
New Energy Vehicle Scroll Compressors are positive-displacement machines using interleaved spiral wraps to compress refrigerant with volumetric efficiencies above ninety percent and near-isothermal compression profiles, purpose-built for electric vehicle thermal management where coefficient of performance directly impacts range. Air Conditioning Compressors occupy the dominant revenue position due to cabin cooling load requirements in warm-climate markets, while Heat Pump Compressors represent the fastest-expanding category as OEMs eliminate resistive heating to preserve winter range. Inverter Technology leads technology segmentation by value since variable-speed drives match compressor output to thermal load with precision unavailable from fixed-speed alternatives.
China's MIIT enforces GB standards for refrigerant leakage and energy efficiency that compressors must satisfy for NEV subsidy eligibility, while the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants and forces compressor redesigns for lower-global-warming-potential fluids. The US EPA SNAP program and California Air Resources Board rules similarly constrain refrigerant chemistry and thermal system efficiency thresholds for vehicles sold in North America. Stakeholders must monitor which refrigerant-transition pathway each major regulator prioritizes, as compressor sealing materials and lubricant compatibility requirements diverge meaningfully between R-1234yf and CO2 systems.
Market Dynamics
Modular thermal management packaging is consolidating procurement decisions around integrated compressor-inverter-refrigerant modules, compressing supplier margins for standalone component vendors while rewarding system-level integrators with design-in permanence.
Growth Catalysts
- MIIT dual carbon goals:China's GB standards for refrigerant leakage and energy efficiency mandate compressor redesigns, forcing domestic OEMs to upgrade thermal systems for NEV subsidy eligibility.
- Heat pump deployment:Battery electric passenger vehicle programs in cold-climate markets are eliminating resistive cabin heating, pulling variable-speed scroll compressors into winter range preservation strategies.
- Yangtze River Delta concentration:Manufacturing clusters around Shanghai and Suzhou anchor integrated module production capacity, reducing logistics costs for domestic Chinese OEMs and export-bound Tier 1 suppliers.
Market Restraints
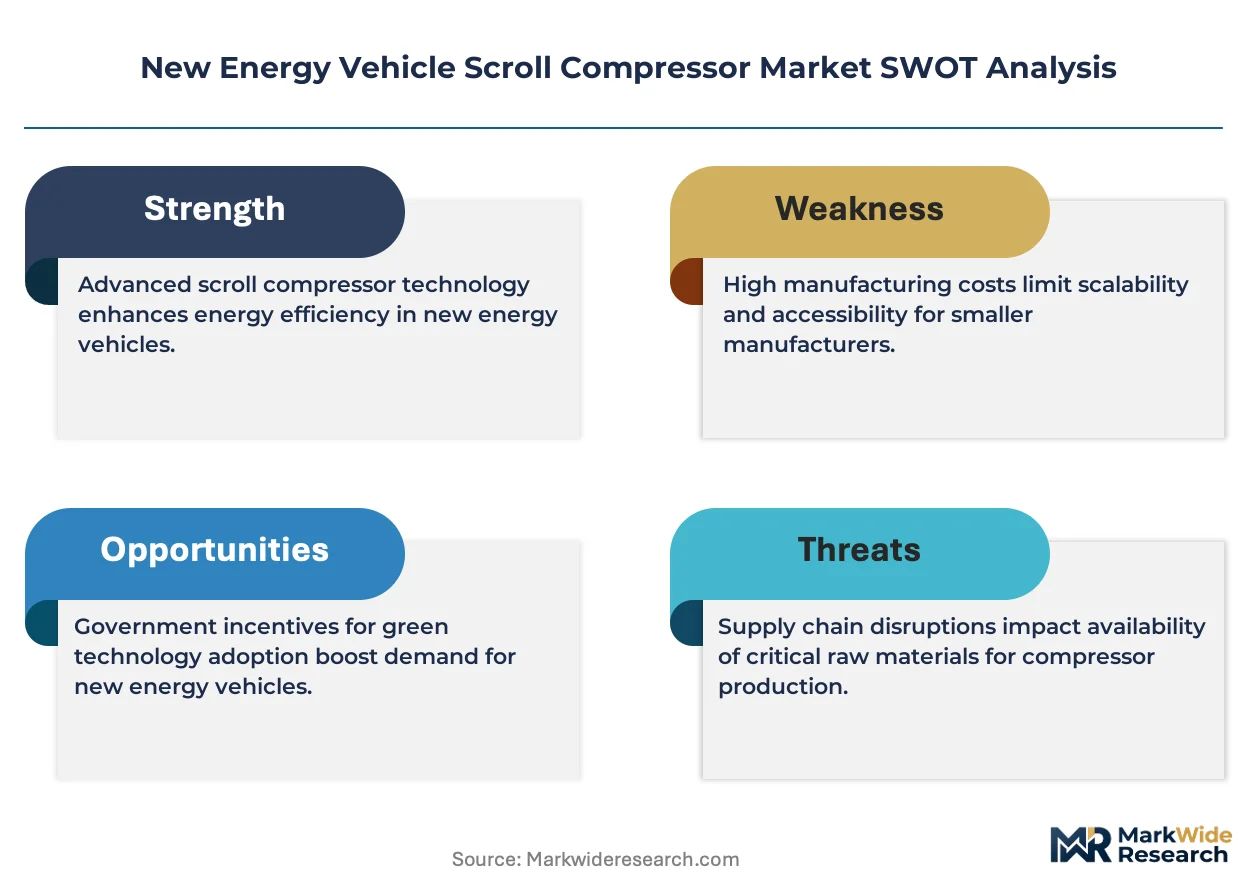
- Copper and rare-earth price volatility:Inverter scroll compressors depend on permanent magnet motors and copper windings, exposing margins to commodity swings that fixed-price automotive contracts cannot pass through.
- Refrigerant transition friction:The EU F-Gas Regulation phases down hydrofluorocarbon availability, forcing simultaneous redesigns of sealing materials, lubricants, and compressor displacement ratios for lower-global-warming-potential fluids.
- Single-source inverter dependency:Automotive-grade silicon carbide power modules concentrate among a handful of semiconductor foundries, creating supply vulnerability for compressor manufacturers without captive inverter production.
Strategic Opportunities
- Commercial vehicle electrification:Electric buses and medium-duty trucks in China remain underpenetrated by integrated thermal modules, opening volume for cost-optimized scroll platforms purpose-built for fleet duty cycles.
- CO2 heat pump convergence:Transcritical CO2 systems for extreme cold climates require compressor architectures with pressure ratings above 10 MPa, a technical white space where early movers capture patent position.
- US EPA SNAP alignment:California Air Resources Board rules on refrigerant chemistry create a regulatory tailwind for compressor designs already compliant with EU F-Gas thresholds, enabling platform reuse across export programs.
Industry Challenges
- Systems integration talent scarcity:Compressor manufacturers lack embedded software engineers capable of optimizing inverter-control algorithms for real-time thermal load matching, forcing reliance on automotive Tier 1 partners for calibration.
- Homologation timeline compression:GB standard updates and EU F-Gas implementation schedules compress certification windows, requiring parallel validation tracks that strain testing laboratory capacity and engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Energy Vehicle Scroll Compressor Market |
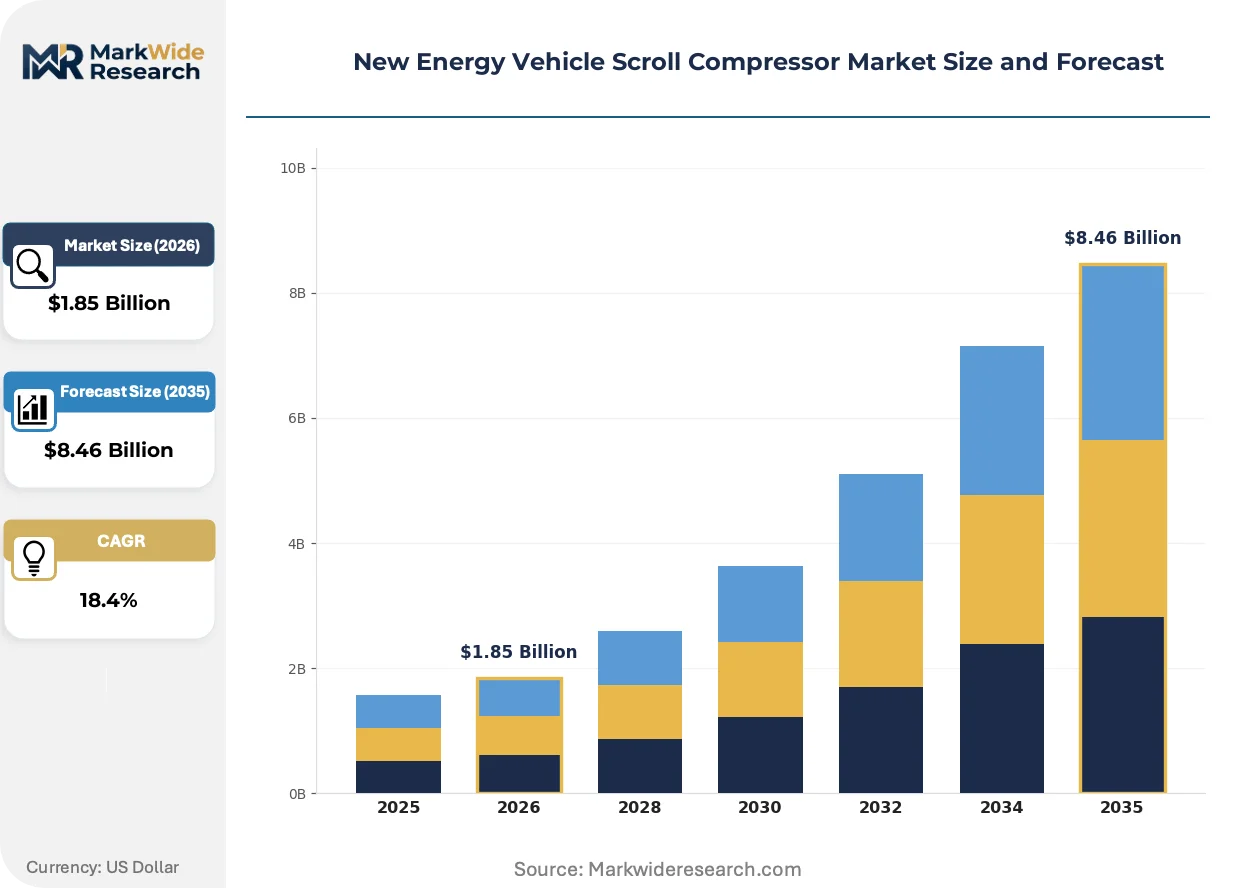
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigeration Compressors, Air Conditioning Compressors, Heat Pump Compressors, Auxiliary Compressors Technology: Scroll Technology, Inverter Technology, Variable Speed Technology, Fixed Speed Technology End User: Passenger Vehicles, Commercial Vehicles, Specialty Vehicles, E-Buses Application: Cooling Systems, HVAC Systems, Thermal Management, Integrated Systems |
| Companies Covered | Sanden Corporation, Hanon Systems, Denso Corporation, Mahle GmbH, Valeo, Aotecar, Shanghai Highly (Group), Shanghai Benling Scroll Compressor, BOCK GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Energy Vehicle Scroll Compressor Market Trends and Innovations
Refrigerant chemistry transitions and power electronics integration are compressing product lifecycles, forcing compressor manufacturers to architect platforms for fluid flexibility and thermal load variability rather than fixed operating points.
Silicon carbide inverter drives are rewriting the thermal management value chain by enabling switching frequencies above 20 kHz, shrinking motor size and improving part-load efficiency. European and Japanese OEMs are embedding these drives into heat pump modules for battery electric passenger vehicles. The technology is compressing the performance gap between scroll and alternative compression architectures at the critical 3-5 kW cabin cooling load range.
The EU F-Gas Regulation mandates an 80% phase-down of hydrofluorocarbon refrigerants by 2030, forcing compressor manufacturers to validate sealing elastomers and lubricant miscibility for R-1234yf and CO2 alternatives. Automotive thermal system suppliers are responding with dual-compatible platform architectures that minimize retooling between refrigerant generations. Heat pump compressor categories face the steepest redesign burden due to their exposure to high-pressure transients and wider temperature extremes.
Automotive OEMs are consolidating compressor procurement around thermal module integrators capable of delivering coefficient-of-performance guarantees rather than standalone hardware. Tier 1 suppliers are absorbing inverter calibration and refrigerant charge optimization responsibilities that previously sat with vehicle manufacturers. This pattern is most visible in German and Japanese battery electric vehicle programs, where thermal system efficiency directly impacts WLTP range certification.
New Energy Vehicle Scroll Compressor Market Segmentation
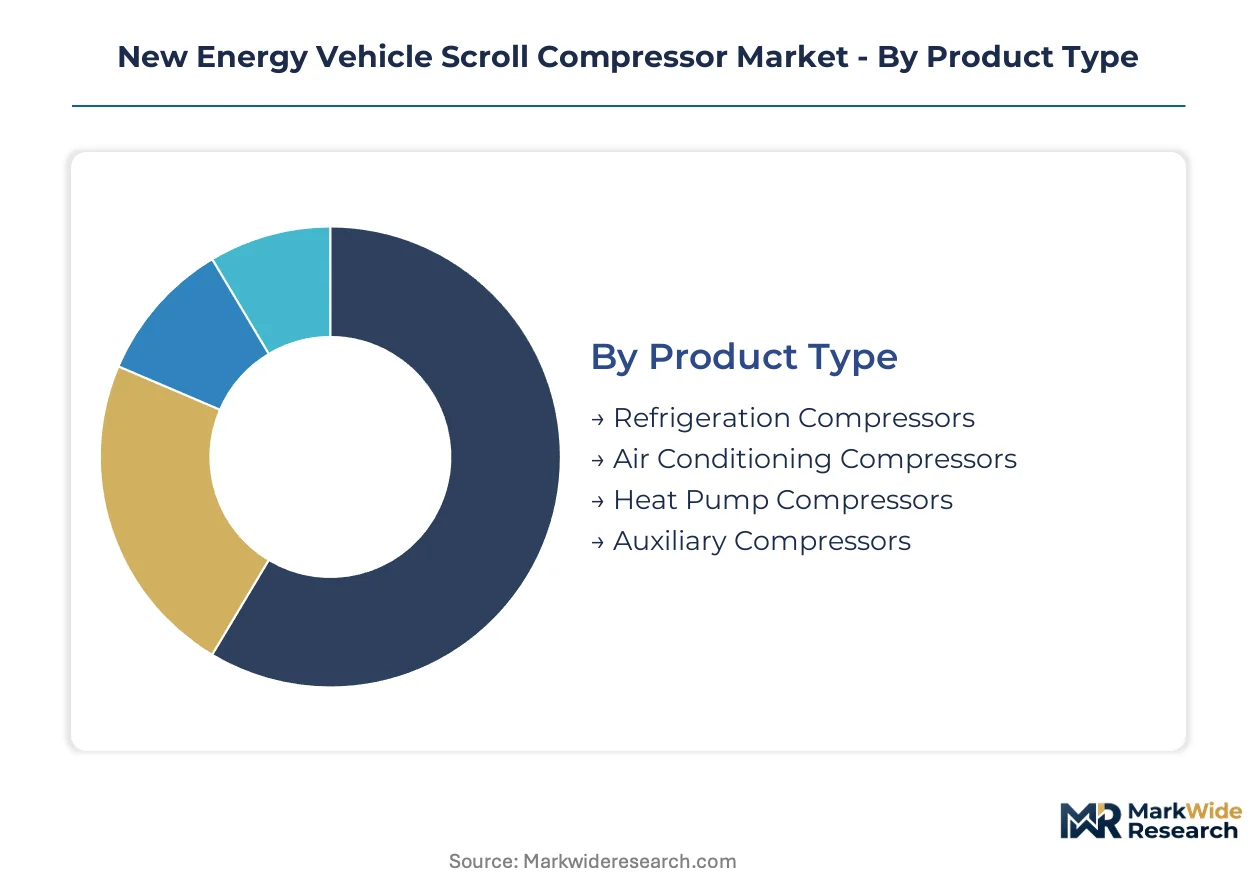
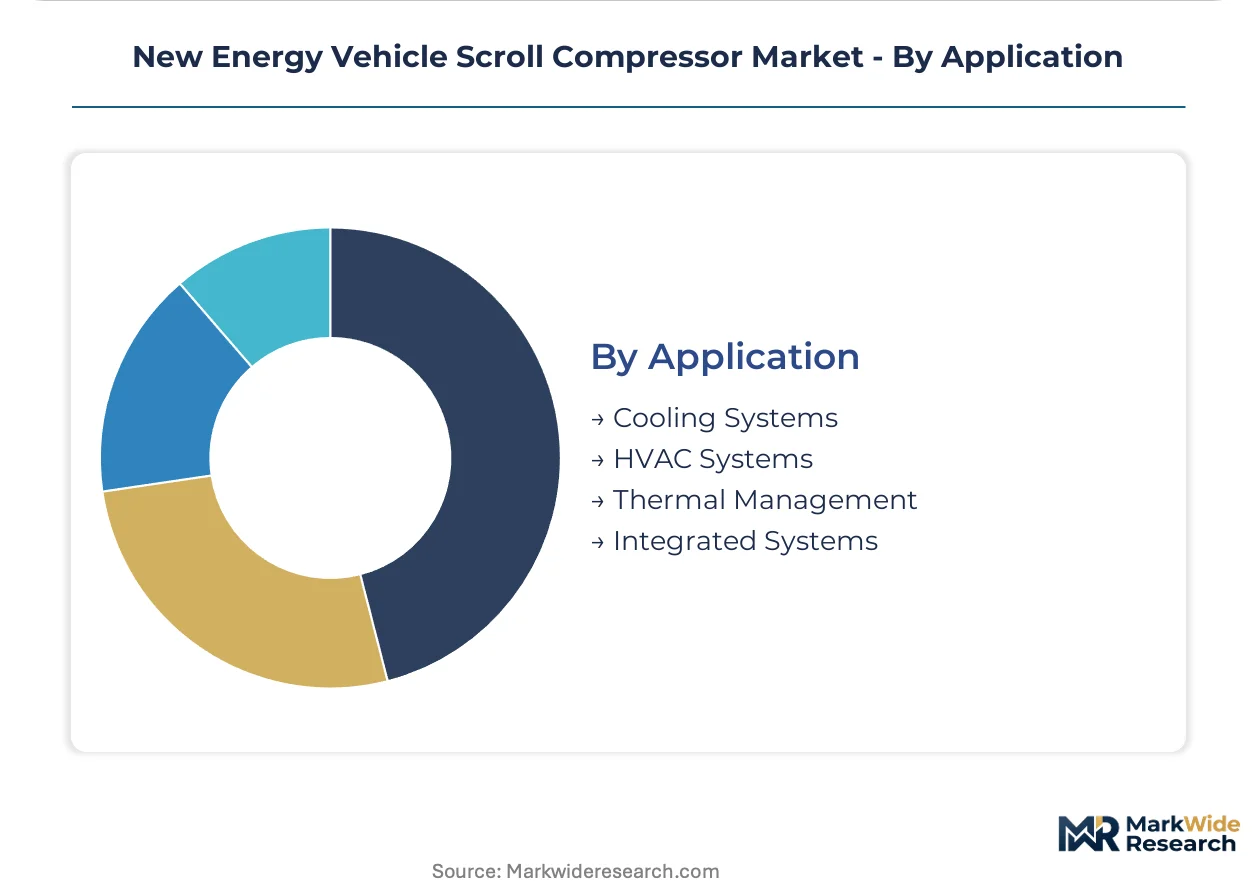
Compressor procurement patterns fragment sharply across thermal load requirements, refrigerant chemistry transitions, and vehicle electrification architectures. Supplier specialization and module integration intensity vary dramatically by segment, reshaping competitive positioning and margin capture opportunities.
Product Type:
Supply-side concentration clusters around integrated module platforms capable of spanning multiple refrigerant chemistries and thermal load ranges.
- Air Conditioning Compressors:Positive-displacement scroll machines deliver cabin cooling loads above 3 kW with volumetric efficiencies exceeding ninety percent. Chinese, Japanese, and German passenger vehicle programs anchor procurement volumes for warm-climate markets where thermal comfort directly impacts consumer satisfaction scores.
- Heat Pump Compressors:Variable-speed scroll architectures operate across wider temperature and pressure envelopes to enable winter cabin heating without resistive elements. Cold-climate battery electric vehicle programs in Scandinavia, northern China, and Japan are expanding procurement fastest as OEMs eliminate range penalties from traditional heating.
- Refrigeration Compressors:Compact scroll units serve battery thermal conditioning and power electronics cooling loops in high-performance electric vehicles.
- Auxiliary Compressors:Standalone units support supplemental cooling for fast-charging thermal management and rear-cabin zones in premium vehicle configurations.
Today's leader: Air Conditioning Compressors. Tomorrow's challenger: Heat Pump Compressors.
Technology:
Cost tier stratification separates premium inverter-equipped platforms from fixed-speed alternatives serving price-sensitive commercial applications.
- Inverter Technology:Silicon carbide power modules enable switching frequencies above 20 kHz, shrinking motor mass and enabling precise thermal load matching. European and Japanese OEMs specify these drives for WLTP range certification, concentrating design wins in premium battery electric passenger vehicle programs.
- Variable Speed Technology:Pulse-width-modulated drives balance cost and efficiency for mid-market electric vehicles where part-load optimization matters but silicon carbide economics do not yet close.
- Scroll Technology:Interleaved spiral wrap geometry delivers near-isothermal compression profiles purpose-built for refrigerant systems requiring high reliability and low noise signatures.
- Fixed Speed Technology:On-off cycling compressors serve cost-optimized e-bus and fleet commercial vehicle thermal systems where capital expenditure constraints override efficiency optimization.
Today's leader: Inverter Technology. Tomorrow's challenger: Variable Speed Technology.
End User:
Application maturity spreads unevenly, with passenger vehicle programs absorbing integrated modules while commercial segments remain fragmented.
- Passenger Vehicles:Battery electric platforms in China, Germany, and Japan specify integrated compressor-inverter-refrigerant modules with coefficient-of-performance guarantees. WLTP and CLTC range certification protocols force thermal system efficiency to the center of procurement decisions.
- E-Buses:Chinese domestic OEMs and municipal fleet operators drive volume for cost-optimized scroll platforms purpose-built for high-duty-cycle urban operation. Yangtze River Delta manufacturing clusters anchor supply proximity to this demand.
- Commercial Vehicles:Medium-duty electric trucks in North American and European last-mile delivery applications are expanding thermal module penetration as fleet operators electrify.
- Specialty Vehicles:Electric construction equipment and agricultural machinery present emerging demand for ruggedized compressor architectures with enhanced vibration tolerance.
Today's leader: Passenger Vehicles. Tomorrow's challenger: E-Buses.
Application:
Margin capture concentrates in integrated system architectures where suppliers assume calibration and refrigerant charge optimization responsibilities.
- Thermal Management:Unified compressor architectures serve combined battery, cabin, and power electronics cooling loops. German and Japanese OEMs consolidate procurement around Tier 1 integrators capable of delivering system-level efficiency guarantees rather than standalone hardware.
- HVAC Systems:Cabin comfort modules incorporate scroll compressors with variable-speed drives for precise temperature and humidity control across ambient conditions from desert heat to arctic cold.
- Cooling Systems:Dedicated compressor circuits address fast-charging thermal loads and power electronics heat rejection in high-performance electric vehicles.
- Integrated Systems:Multi-function thermal modules consolidate previously separate compressor, inverter, and heat exchanger components into single packaged units.
Today's leader: Thermal Management. Tomorrow's challenger: Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scroll compressor manufacturing for electric vehicles originated in Japanese automotive supply chains during the 1990s hybrid era, migrated to German precision engineering clusters for European electrification programs, and now concentrates in China's Yangtze River Delta for battery electric vehicle mass production.
China
Domestic OEM procurement for battery electric passenger vehicles and municipal e-bus fleets drives volume demand. MIIT enforces GB standards for refrigerant leakage and energy efficiency that compressors must satisfy for NEV subsidy eligibility. The Yangtze River Delta manufacturing cluster around Shanghai and Suzhou anchors integrated module production capacity for domestic OEMs and export-bound Tier 1 suppliers.
Japan
Premium battery electric vehicle programs from domestic OEMs specify silicon carbide inverter-equipped scroll modules for WLTP range certification. METI coordinates industry transitions toward lower-global-warming-potential refrigerants through collaborative R&D consortia. The Kanto region around Tokyo hosts concentrated design centers for thermal system integration with vehicle electronics architectures.
Germany
Luxury battery electric passenger vehicle manufacturers mandate coefficient-of-performance guarantees from thermal module integrators rather than standalone compressor procurement. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants and forces compressor redesigns for CO2 and R-1234yf alternatives. Baden-Württemberg's automotive supplier ecosystem specializes in high-pressure compressor architectures for transcritical CO2 heat pump systems.
South Korea
Domestic battery electric vehicle OEMs and energy storage system manufacturers pull integrated thermal management modules for winter range preservation. The national industrial regulator coordinates refrigerant transition timelines aligned with EU F-Gas implementation schedules. The Seoul Capital Area concentrates inverter power electronics manufacturing that feeds into compressor module assembly operations.
United States
California Air Resources Board rules on refrigerant chemistry and thermal system efficiency constrain compressor designs for vehicles sold in North America. The EPA SNAP program similarly limits hydrofluorocarbon availability and pushes adoption of lower-global-warming-potential alternatives. Michigan's automotive engineering corridor hosts validation facilities for cold-climate heat pump performance testing.
New Energy Vehicle Scroll Compressor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across inverter integration depth and refrigerant platform flexibility. The vendor base stratifies into three tiers: system-level integrators delivering coefficient-of-performance guarantees, component specialists supplying scroll compression elements to module assemblers, and regional fabricators serving cost-optimized commercial vehicle applications. Dominant competitive moves include geographic expansion into underpenetrated e-bus and medium-duty truck segments, and technology licensing partnerships to secure silicon carbide inverter supply.
Within the system-integrator tier, Denso Corporation and Sanden Corporation exemplify premium positioning through captive inverter technology and established relationships with Japanese and European OEMs. Shanghai Highly (Group) occupies a position in the cost-optimized segment, representing Chinese manufacturing scale advantages for domestic e-bus and commercial vehicle thermal systems. Hanon Systems exemplifies geographic specialization, anchoring supply relationships with Korean and Chinese passenger vehicle programs through concentrated regional engineering presence.
| Leading Market Players |
|---|
| Sanden Corporation |
| Hanon Systems |
| Denso Corporation |
| Mahle GmbH |
| Valeo |
| Aotecar |
| Shanghai Highly (Group) |
| Shanghai Benling Scroll Compressor |
| BOCK GmbH |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance mandates gate qualified supply access and premium-tier pricing power, forcing compressor manufacturers to absorb redesign costs for lower-global-warming-potential refrigerants while OEMs consolidate procurement around integrated module suppliers capable of delivering coefficient-of-performance guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide inverter-equipped modules from pulse-width-modulated alternatives and fixed-speed commodity platforms. Price differentiation hinges on certification grade for EU F-Gas and China MIIT GB standards alongside volume scale commitments from domestic OEMs. Cost compression in economy-tier fixed-speed compressors is intensifying because Chinese e-bus fleet operators prioritize capital expenditure minimization over efficiency optimization. Commercial vehicle procurement teams exhibit highest price sensitivity, while German and Japanese passenger vehicle OEMs prioritize thermal system efficiency for WLTP range certification.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for silicon carbide power modules and permanent magnet motors, compressing single-source dependencies among Tier 1 integrators. Manufacturing concentrates in China, Japan, and Germany, with the Yangtze River Delta anchoring integrated module assembly and Baden-Württemberg specializing in high-pressure CO2 compressor architectures. Raw material dependencies draw from copper winding suppliers, rare-earth magnet producers, and refrigerant-grade aluminum casting foundries. Single-source vulnerability concentrates in automotive-grade silicon carbide foundries. Distribution runs through OEM-direct contracting with Tier 1 thermal system integrators rather than aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where cost-optimized scroll platform production in China's Yangtze River Delta exploits lower manufacturing overhead against premium inverter module engineering in Germany and Japan, while EU F-Gas regulatory stringency creates compliance cost differentials that favor early refrigerant-transition movers.
For Market Incumbents: To counter silicon carbide inverter supply concentration among semiconductor foundries, Denso Corporation and Sanden Corporation should deepen captive power electronics production through backward integration into module packaging, while expanding validation laboratory capacity in China to compress GB standard homologation timelines for domestic OEM programs.
For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass incumbent Tier 1 relationships with municipal e-bus operators in China's second-tier cities, offering cost-optimized scroll platforms with remote diagnostics bundling. Target medium-duty electric truck thermal management in North American last-mile delivery as the most penetrable segment, where fleet electrification timelines outrun established supplier relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists supplying scroll compression elements to module assemblers without captive inverter technology or refrigerant platform flexibility. Long-term viability over the next decade hinges on CO2 heat pump patent position and silicon carbide supply security. Watch for MIIT GB standard update announcements as the inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Flexibility Investment | Dual-compatible architectures for R-1234yf and CO2 minimize retooling between regulatory generations. |
| Silicon Carbide Inverter Backward Integration | Captive power module production reduces dependency on concentrated semiconductor foundry supply. |
| Yangtze River Delta Capacity Expansion | Proximity to Chinese OEM production clusters compresses logistics costs for domestic and export programs. |
| CO2 Heat Pump Patent Development | Transcritical pressure rating capabilities above 10 MPa open extreme cold-climate market positioning. |
| Tier 1 Thermal Module Partnership | Design-in permanence with German and Japanese OEMs secures coefficient-of-performance guarantee contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, thermal system integration specialists, and compressor manufacturing operations heads with secondary validation against MIIT GB standard filings, EU F-Gas implementation schedules, vehicle production databases, and customs trade data for copper and rare-earth magnet flows. Bottom-up segment sizing triangulated against top-down OEM thermal system content assumptions.
Segment-weighting approaches applied differential growth rates across inverter technology, variable speed, and fixed speed categories, with propulsion architecture and regional production cluster dimensions layered across the analysis window. CAGRs derived from fitted growth curves calibrated to OEM electrification program announcements and refrigerant transition timelines. Forecast inputs incorporated silicon carbide adoption trajectories and heat pump penetration assumptions for cold-climate markets.
Refrigerant chemistry transition delays, silicon carbide supply disruptions, and MIIT subsidy policy adjustments are the dominant revision risks to the outlook. Deviation in EU F-Gas phase-down implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Car Oil Filter Market
Powertrain
India Automotive Engine Oils Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Tachometer Market
Powertrain
Engines Market
Powertrain
EV Powertrain Market
Powertrain
Global Industrial Engine Market
Powertrain
Crate Engines Market