
 France Automotive Engine Oils Market | 2026-2036
France Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Engine Oils Market Foresight
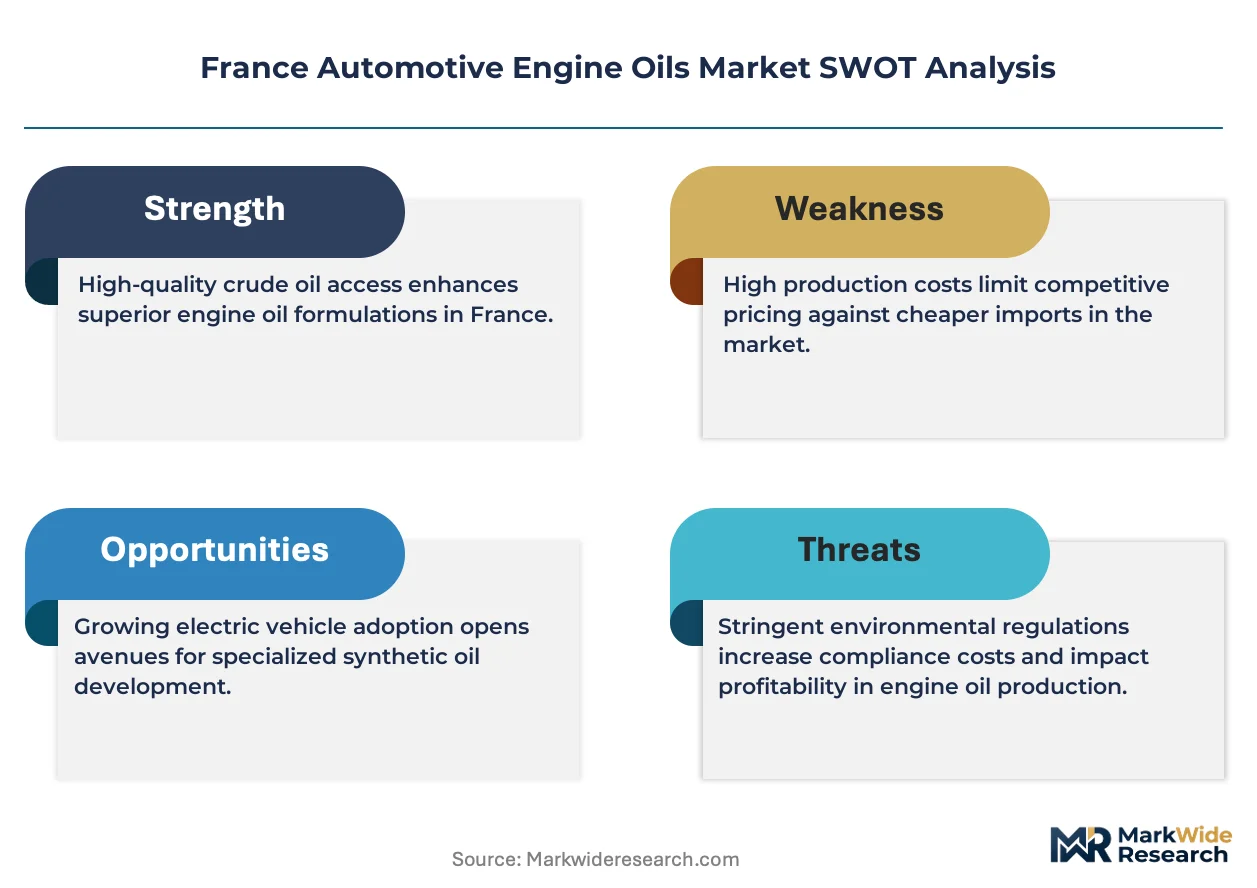
France is tilting toward higher-specification lubricant production to serve stringent domestic and EU-wide emissions rules. TotalEnergies anchors its position through backward integration into base oil refining and additive formulation. Shell plc leverages extensive workshop partnerships across the Île-de-France region. Castrol differentiates via motorsport-derived technology transfer into consumer-grade synthetics.
France automotive engine oils are formulated lubricants designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines, typically comprising base oils plus detergent, dispersant, anti-wear, and viscosity modifier additives. Their primary commercial purpose is extending engine life while enabling compliance with tightening exhaust emission limits. Synthetic formulations command the strongest margin pools as OEM fill specifications shift toward lower-viscosity grades such as 0W-20 and 5W-30. The viscosity grade dimension shows 5W-30 occupying the largest volume position due to its compatibility with both gasoline and light diesel passenger vehicles. Distribution through workshops and automotive dealers remains the dominant channel for premium product placement.
France's national regulator enforces REACH chemical compliance and EU vehicle emission standards that directly shape lubricant additive packages and labeling requirements. The EU F-Gas Regulation and broader Green Deal frameworks pressure formulators to reduce carbon intensity across the product lifecycle. ANSM oversees occupational exposure limits at blending facilities. Stakeholders must monitor how Paris-aligned carbon pricing and potential internal combustion phase-out timelines reshape long-term demand for engine oil formulations versus electrification-adjacent fluids.
Market Dynamics
The EU Green Deal is compressing formulation timelines as ANSM enforces REACH chemical compliance and Paris-aligned carbon pricing reshapes lifecycle accountability for lubricant producers.
Growth Catalysts
- EU F-Gas Regulation:Tightening fluorinated gas controls force formulators toward lower-carbon additive packages, accelerating synthetic lubricant substitution across commercial fleets.
- Paris metropolitan cluster:Concentrated aftermarket demand in Île-de-France creates density economies for premium 0W-20 and 5W-30 grade distribution through workshop networks.
- Lower-viscosity grades:OEM fill specifications shifting toward 0W-20 and 5W-30 enable fuel economy gains that align with Euro 7 emission preparation timelines.
Market Restraints
- Base oil supply concentration:European Group II/III base oil refining capacity limits domestic sourcing flexibility, exposing blenders to import dependency from Middle Eastern and Asian suppliers.
- REACH registration costs:ECHA chemical compliance burdens disproportionately constrain small and mid-size formulators from introducing novel additive chemistries.
- Electrification substitution:Battery electric vehicle penetration in French passenger fleets threatens long-term internal combustion engine oil demand volumes.
Strategic Opportunities
- Rhône-Alpes manufacturing corridor:Industrial vehicle density around Lyon and Grenoble offers underpenetrated demand for heavy-duty diesel engine oil formulations.
- Workshop channel digitization:E-commerce integration with independent garage networks enables direct-to-technician premium synthetic placement outside dealer capture.
- EU CSRD reporting:Mandatory sustainability disclosure creates competitive differentiation for suppliers with verified lifecycle carbon intensity data.
Industry Challenges
- Additive chemist talent scarcity:Specialized formulation expertise for low-SAPS (sulfated ash, phosphorus, sulfur) packages remains concentrated among retiring cohorts at major blenders.
- Dual certification timelines:Simultaneous ACEA and API sequence testing extends product launch cycles by 18-24 months for new viscosity grade introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Engine Oils Market |
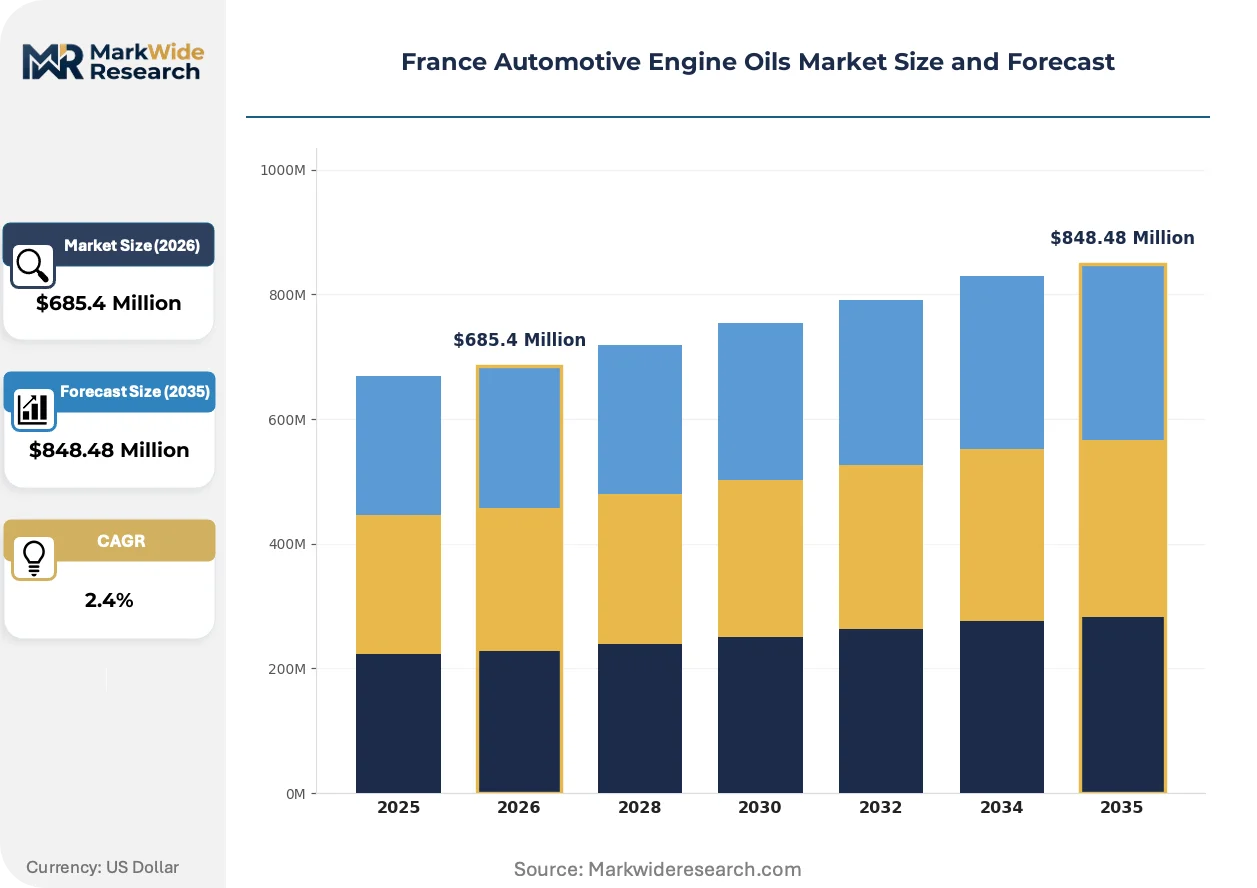
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $848.48 Million |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Synthetic, Semi-Synthetic, High-Mileage, Racing Oils, Bio-Based Viscosity Grade: 5W-30, 10W-40, 15W-40, 0W-20, 20W-50 End User: Passenger Vehicle Owners, Commercial Fleet Managers, Aftermarket Service Providers, Motorbike Users Distribution Channel: Automotive Dealers, E-commerce Platforms, Gas Stations, Specialty Stores, Workshops |
| Companies Covered | BP p.l.c., FUCHS, TotalEnergies, Liqui Moly, Castrol, Shell plc, Motul, IGOL, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Engine Oils Market Shifts & Advancements
Digital fluid monitoring and predictive maintenance platforms are rewiring how lubricant value is captured, shifting revenue from product sales toward performance-guaranteed service relationships.
Artificial intelligence-driven oil condition sensors are virtualizing traditional drain interval determination. Fleet operators in the Paris metropolitan cluster deploy real-time viscosity and oxidation monitoring to extend service intervals by 30-40 percent. This technology is virtualizing the historical role of fixed-mileage maintenance schedules, compressing aftermarket transaction frequency while raising per-unit premium synthetic attach rates.
REACH chemical restriction amendments are eliminating certain zinc dialkyldithiophosphate concentrations from passenger vehicle formulations. French blenders reformulate anti-wear packages to maintain Euro 6d engine protection standards without restricted chemistries. The passenger car motor oil segment absorbs the steepest compliance costs, passing formulation R&D burdens through to OEM fill and service fill pricing.
Workshop procurement consolidation is compressing supplier counts as large garage chains centralize lubricant buying. Independent multi-brand networks in Rhône-Alpes and Provence-Alpes-Côte d'Azur negotiate direct supply agreements with major blenders, displacing traditional distributor intermediaries. This pattern concentrates most visibly in the light commercial vehicle service segment, where national fleet accounts demand unified pricing across regional workshop footprints.
France Automotive Engine Oils Market Segmentation
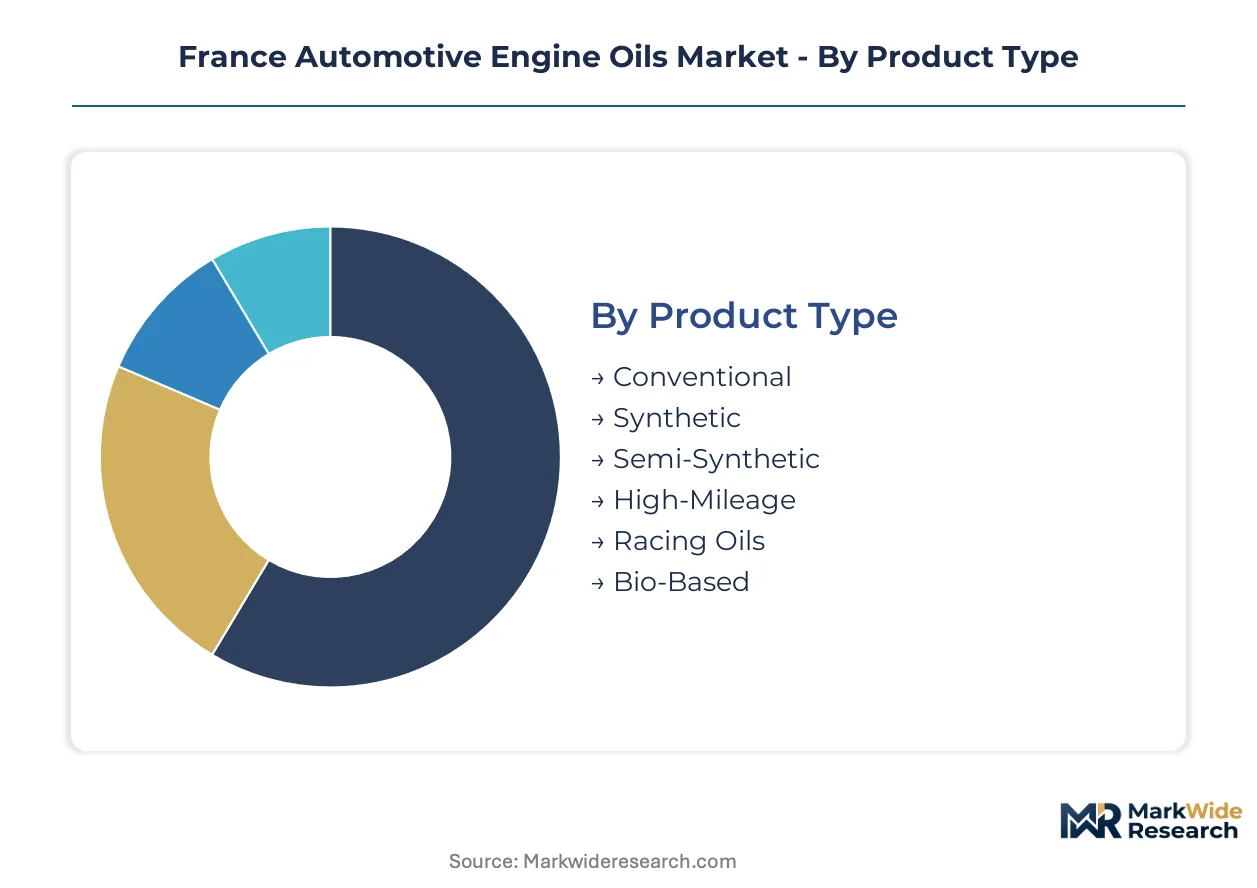
Segmentation in the France automotive engine oils market reveals how formulation chemistry, viscosity engineering, and channel economics divide commercial opportunity. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier resource allocation.
Product Type:
Mature synthetic formulations dominate commercial returns while emerging bio-based alternatives test regulatory acceptance under EU Green Deal frameworks.
- Synthetic:Fully formulated polyalphaolefin and ester-based lubricants deliver thermal stability for extended drain intervals. Paris metropolitan fleet operators specify these grades to meet Euro 7 pre-compliance fuel economy targets while minimizing depot maintenance downtime.
- Semi-Synthetic:Blended formulations combine Group III base oils with synthetic additives to balance performance and cost. Rhône-Alpes light commercial vehicle workshops favor this tier for customer vehicles outside warranty coverage where OEM fill specifications permit flexibility.
- Conventional:Mineral-based formulations serve aging vehicle parc segments in peripheral French regions with less stringent emissions compliance requirements.
- High-Mileage:Seal conditioner additives target vehicles exceeding 100,000 kilometers in second ownership markets concentrated in Provence-Alpes-Côte d'Azur.
- Racing Oils:ZDDP-rich formulations for motorsport applications fall outside standard emissions compliance requirements.
- Bio-Based:Renewable feedstock lubricants remain experimental under REACH bioaccumulation testing protocols.
Synthetic handles the majority of throughput; bio-based is expanding most quickly on share as carbon intensity disclosure requirements mature.
Viscosity Grade:
Cost tier differentiation separates premium low-viscosity specifications from standard multigrade offerings serving divergent OEM warranty requirements.
- 5W-30:The workhorse multigrade specification balances cold-start pumpability with high-temperature film strength. French passenger vehicle service fill demand concentrates here due to ACEA C3 compatibility across gasoline and light diesel powertrains.
- 0W-20:Ultra-low viscosity formulations reduce hydrodynamic friction losses for hybrid and downsized turbocharged engines. Île-de-France dealer networks push this grade for new vehicle servicing to align with manufacturer fuel economy claims.
- 10W-40:Higher viscosity reserve for older European engine designs without variable valve timing complexity.
- 15W-40:Heavy-duty diesel specification for commercial vehicle applications in Lyon-Grenoble logistics corridors.
- 20W-50:Limited demand in classic vehicle restoration and high-performance aftermarket segments.
5W-30 commands the largest volume position; 0W-20 shows the steepest expansion trajectory as OEM fill specifications tighten.
End User:
Customer type segmentation maps directly to procurement behavior, with fleet managers centralizing purchasing through tender processes while individual owners respond to workshop recommendation.
- Commercial Fleet Managers:National and regional logistics operators consolidate lubricant procurement through multi-year supply agreements. These buyers mandate lifecycle carbon data under EU CSRD reporting obligations, favoring suppliers with verified Scope 3 emissions documentation.
- Passenger Vehicle Owners:Individual consumers rely on workshop technician recommendations for service fill decisions. Brand loyalty remains low; price sensitivity increases with vehicle age.
- Aftermarket Service Providers:Independent garage chains and franchise networks negotiate direct blender relationships, bypassing traditional distributor margins. Procurement centralization accelerates in Rhône-Alpes and Provence-Alpes-Côte d'Azur regional consolidations.
- Motorbike Users:Niche segment with distinct friction modifier requirements for wet clutch compatibility.
Commercial Fleet Managers drive the majority of premium synthetic volume; Aftermarket Service Providers are gaining share fastest through procurement consolidation.
Distribution Channel:
Geography of demand concentrates channel investment around the Paris metropolitan cluster and Rhône-Alpes manufacturing corridor.
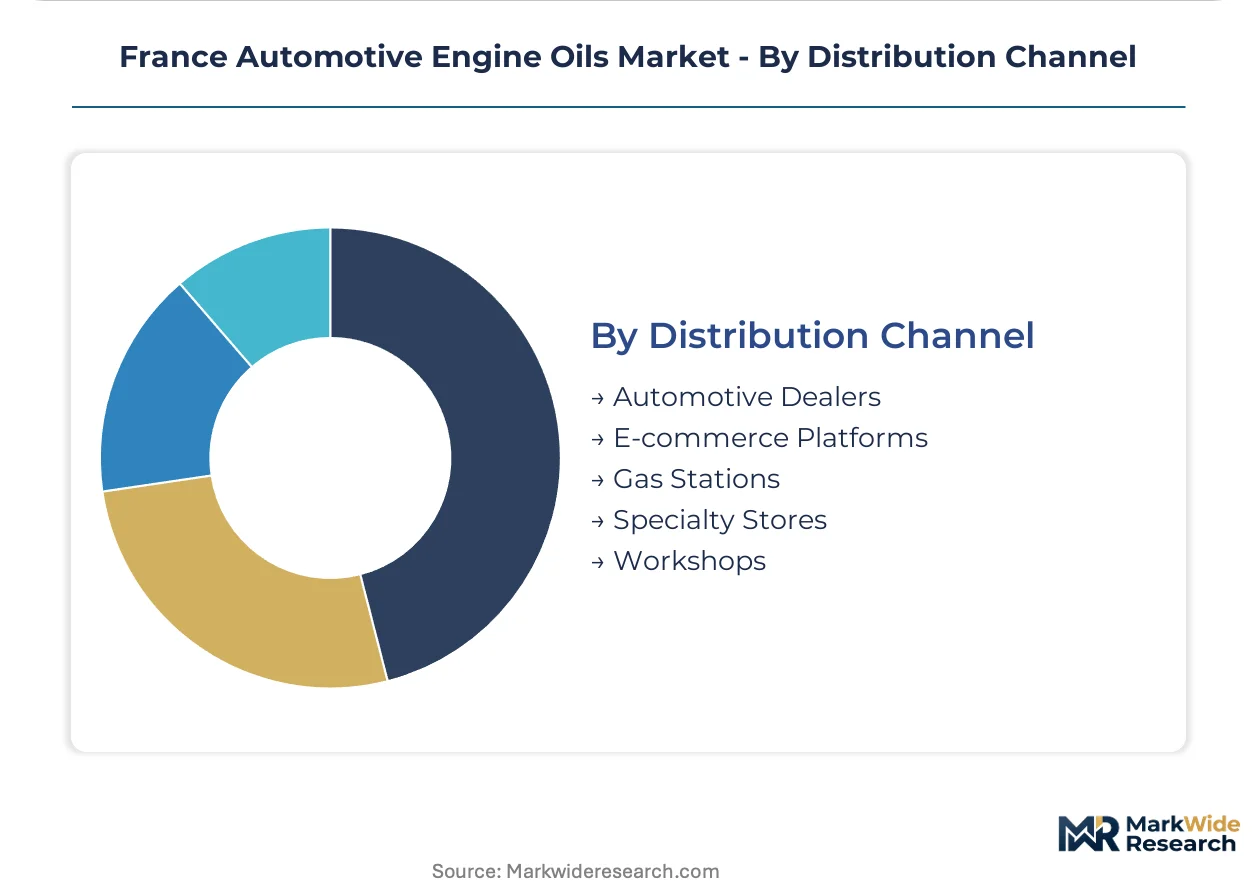
- Workshops:Independent and franchise garage networks remain the dominant channel for service fill placement. Technician recommendation influences consumer choice more than brand advertising in French aftermarket culture.
- Automotive Dealers:OEM-captive service centers enforce strict fill specifications during warranty periods. Dealer channel synthetic attach rates exceed independent workshop averages.
- E-commerce Platforms:Direct-to-consumer lubricant sales grow among enthusiast segments comfortable with self-service maintenance. Amazon France and specialized automotive marketplaces capture this demand.
- Gas Stations:Emergency top-up and convenience purchasing for highway corridor locations.
- Specialty Stores:Concentrated in motorsport and classic vehicle restoration supply chains.
Workshops handle the majority of throughput; E-commerce Platforms are climbing the fastest on share as DIY maintenance culture spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil refining and additive formulation capacity clusters around the Rhine-Ruhr corridor and Rotterdam-Antwerp port complex, positioning French blenders within a tightly integrated northwest European supply network.
Île-de-France
Paris metropolitan fleet operators drive premium synthetic demand through Euro 7 pre-compliance procurement. ANSM enforces REACH chemical exposure limits at blending facilities throughout the region. Workshop networks in Seine-Saint-Denis and Val-de-Marne concentrate aftermarket service fill volume for light commercial vehicles.
Auvergne-Rhône-Alpes
Lyon-Grenoble logistics corridors generate heavy-duty diesel engine oil consumption from refrigerated transport and manufacturing supply chains. The EU F-Gas Regulation pressures cold-chain operators toward lower-carbon lubricant specifications. Industrial vehicle density around Saint-Étienne and Chambéry offers underpenetrated demand for extended-drain formulations.
Provence-Alpes-Côte d'Azur
Second-ownership vehicle markets exceeding 100,000 kilometers concentrate high-mileage formulation demand. CSRD reporting obligations begin penetrating mid-size fleet operators in Marseille and Nice. Independent garage chains in Var and Alpes-Maritimes centralize procurement through direct blender negotiations.
Hauts-de-France
Cross-border commercial traffic with Belgium and the Netherlands sustains highway corridor lubricant consumption. E-commerce distribution platforms capture growing DIY maintenance demand around Lille metropolitan area. Regional blending facilities serve northern European export markets through Calais-Dunkirk logistics infrastructure.
France Automotive Engine Oils Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in base oil and additive supply. The France automotive engine oils market structures around three tiers: integrated energy majors with captive refining, independent blenders with regional formulation expertise, and specialty lubricant houses with motorsport technology transfer. Consolidation pressure intensifies as workshop procurement centralization favors suppliers with national distribution density. Strategic moves cluster on backward integration into Group III base oil sourcing and ACEA/API dual certification acceleration.
Among integrated energy majors, TotalEnergies anchors the domestic tier through backward integration into base oil refining and additive formulation. Shell plc occupies a position leveraging extensive workshop partnerships across the Île-de-France region. Castrol exemplifies motorsport-derived technology transfer into consumer-grade synthetics. These three represent distinct competitive archetypes: captive supply chain control, channel density economics, and performance brand premiumization.
| Leading Market Players |
|---|
| BP p.l.c. |
| FUCHS |
| TotalEnergies |
| Liqui Moly |
| Castrol |
| Shell plc |
| Motul |
| IGOL |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
REACH chemical registration cost volatility determines both the premium-to-economy pricing spread across French lubricant tiers and the geographic sourcing decisions of domestic blenders seeking additive package alternatives. This regulatory chokepoint compresses margins for mid-tier formulators while rewarding integrated majors with captive additive capabilities.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by mandating lower-carbon additive packages that stratify synthetic formulations across premium, standard, and economy levels. Price differentiation hinges on ACEA C3 certification grade and volume scale of workshop procurement contracts. Cost compression in semi-synthetic tiers is intensifying because Rhône-Alpes garage chains centralize purchasing through tender processes. Commercial fleet managers exhibit the lowest price sensitivity due to CSRD reporting obligations, while individual passenger vehicle owners in peripheral regions show the highest.
Supply Chain Analysis
Export-control restrictions on fluorinated gas precursor technologies limit domestic additive manufacturing flexibility for French blenders. Base oil supply concentrates in Belgium, the Netherlands, and Germany through the Rotterdam-Antwerp refining cluster. Raw material dependencies include Group III base oils, polyalphaolefin feedstocks, and viscosity modifier polymers. Single-source vulnerability from Middle Eastern Group II/III imports creates exposure to freight rate volatility. Distribution runs through workshop networks and automotive dealers, with e-commerce platforms capturing enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workshop procurement digitization is shifting the France automotive engine oils market toward platform-economics dynamics where API data exchange and predictive maintenance interoperability determine supplier lock-in. This ecosystem inflection rewards early movers who embed lubricant replenishment into fleet management software workflows.
For Market Incumbents: Build certification moats through accelerated ACEA/API dual sequence testing for 0W-20 and 5W-30 grades to outpace smaller competitors facing REACH registration bottlenecks. Deepen backward integration into Group III base oil sourcing through offtake agreements with Rotterdam-Antwerp refiners. Channel control via exclusive workshop partnerships in Île-de-France defends against e-commerce disintermediation. For New Entrants and Emerging Players: Build out white-space presence in heavy-duty diesel formulations for Lyon-Grenoble logistics corridors where incumbent coverage remains thin. Target the Rhône-Alpes manufacturing corridor's industrial vehicle segment through direct garage chain negotiations bypassing traditional distributors. A go-to-market angle anchored on verified lifecycle carbon intensity data captures CSRD-mandated fleet procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional blenders with ACEA-certified formulation libraries and established workshop networks. Long-term viability hinges on electrification-adjacent fluid diversification capabilities beyond internal combustion engine oils. Acquisition targets should demonstrate additive chemistry expertise for low-SAPS packages. The signal to watch is battery electric vehicle penetration rates in French commercial fleets as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Captive Group III supply from Rotterdam-Antwerp insulates blenders from import volatility. |
| Workshop Channel Digitization | E-commerce integration with independent garages in Rhône-Alpes displaces distributor intermediaries. |
| ACEA/API Dual Certification Acceleration | Compressed 18-24 month testing timelines enable faster premium grade market entry. |
| Predictive Maintenance Platform Partnerships | AI-driven oil condition monitoring with Paris fleet operators extends service interval capture. |
| CSRD-Aligned Carbon Disclosure Investment | Verified Scope 3 documentation secures tender preference from EU Green Deal-compliant buyers. |
Research Methodology
Desk research of customs trade data, ECHA chemical registration filings, and ACEA technical bulletins preceded structured interviews with lubricant formulation chemists, commercial fleet procurement directors, and independent garage chain operators. Primary fieldwork across the Paris metropolitan cluster and Rhône-Alpes manufacturing corridor validated secondary estimates of workshop channel volumes. Bottom-up triangulation of regional consumption patterns against top-down capacity analysis from northwest European refiners anchored market sizing.
Assumptions held fixed include REACH chemical restriction timelines and EU Green Deal carbon pricing trajectories across the modeling period. Variable inputs encompassed battery electric vehicle penetration scenarios and workshop procurement consolidation rates. Segmentation modeling covered product type, viscosity grade, end user archetype, and distribution channel. CAGRs derived from historical volume elasticities against vehicle parc growth and OEM fill specification shifts. Forecast inputs included Euro 7 pre-compliance procurement intensity and synthetic substitution curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Asian state-affiliated energy majors would shift outcomes through supply-side price disruption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Automotive Powertrain Components Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Reciprocating Engine Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Timing Belt Kits Market
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
Modular Belt Drive Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Gear Reduction Starter Market
Powertrain
Exhaust Flexible Couplings Market