
 Automotive Camshaft Market | 2026-2036
Automotive Camshaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Camshaft Market Intelligence
The EU Green Deal is recalibrating camshaft material specifications across European supply chains. MAHLE GmbH leverages its forged-steel expertise to meet stricter CO2 thresholds in passenger car powertrains. Thyssenkrupp AG anchors its position through integrated casting-to-machining operations in Germany. Schaeffler AG specializes in variable valve timing modules that align with OEM electrification roadmaps.
An automotive camshaft is a rotating shaft with precisely machined lobes that actuate intake and exhaust valves through direct mechanical contact with lifters or rocker arms, typically manufactured from chilled cast iron or forged alloy steel with surface hardness exceeding 50 HRC after induction hardening. Its primary purpose is to synchronize valve events with piston position to optimize volumetric efficiency and exhaust gas recirculation rates. Double overhead camshaft architectures dominate premium passenger car segments where high-RPM breathing efficiency commands margin premiums. Variable camshaft timing systems represent the fastest-growing product category as OEMs pursue Miller-Atkinson cycle implementations for hybrid powertrains. Cast iron persists in high-volume commercial vehicle applications where cost-per-unit trumps weight reduction targets.
EPA tailpipe standards, Euro 7 emission frameworks, and China's MIIT fuel consumption regulations collectively tighten tolerances on valve event precision and cam lobe profile accuracy. NHTSA corporate average fuel economy rules in the United States push OEMs toward camshaft-actuated cylinder deactivation and variable lift strategies. Stakeholders must monitor how battery electric vehicle penetration reshapes camshaft demand in passenger segments while commercial and hybrid applications sustain tooling investments.
Market Dynamics
Variable valve timing architectures are displacing fixed-lobe designs as OEMs pursue Miller-Atkinson cycle implementations for hybrid powertrains, forcing foundries to retool casting lines and machine shops to acquire multi-axis grinding capacity for asymmetric cam profiles.
Growth Catalysts
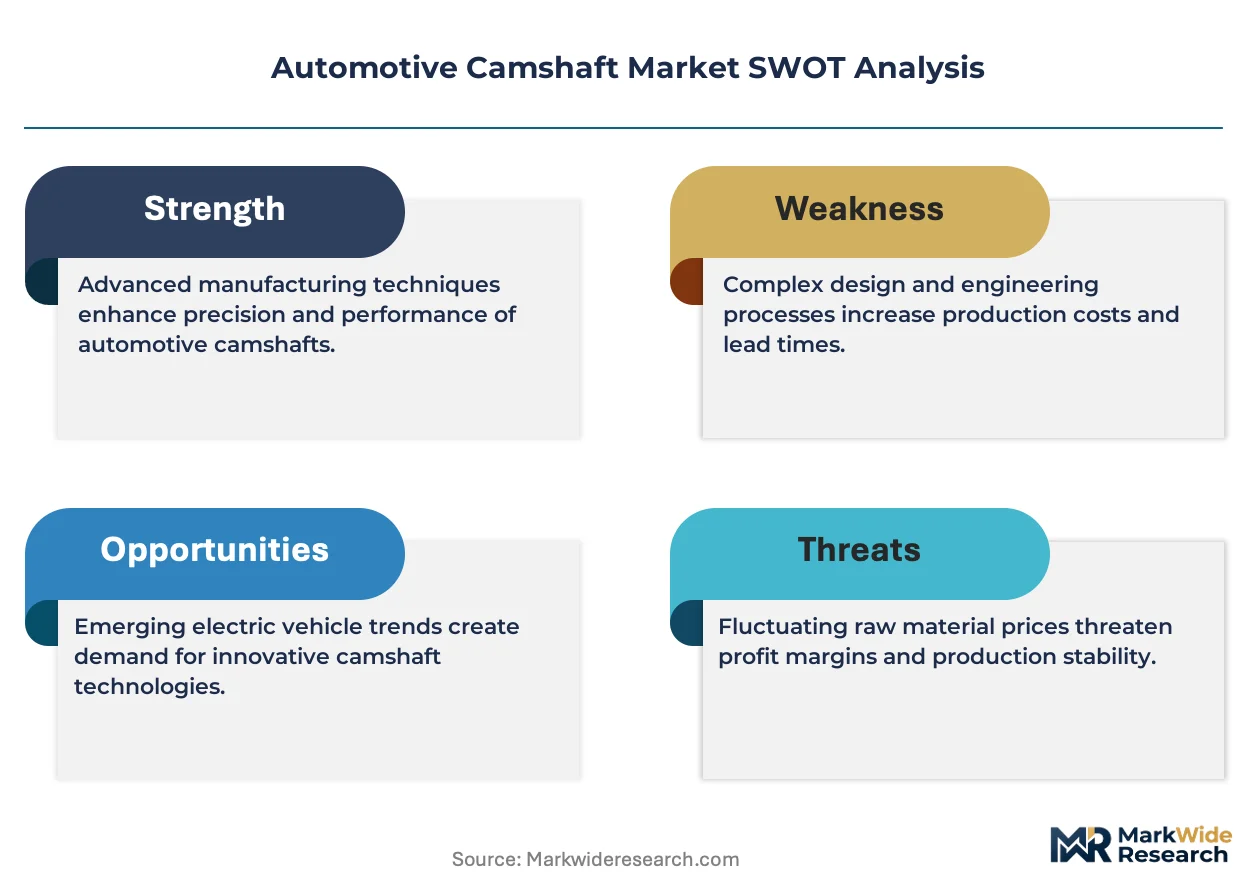
- EPA Tier 4 and Euro 7 benchmarks:Tightening emission thresholds in the United States and European Union are mandating precision valve-train actuation, expanding demand for hollow tubular camshafts with internal oil passages that reduce weight while maintaining torsional rigidity.
- India's Chennai-Pune corridor:Light commercial vehicle production clusters in Tamil Nadu and Maharashtra are scaling procurement of overhead camshaft configurations as domestic fleet operators upgrade to BS VI-compliant powertrains.
- Hybrid powertrain proliferation:Camshaft-actuated cylinder deactivation systems are penetrating mid-size passenger segments as NHTSA corporate average fuel economy rules tighten compliance windows for model year fleets.
Market Restraints
- Scrap steel and ferroalloy volatility:Input cost swings for forged alloy steel camshafts compress margin predictability at independent machine shops lacking backward integration into billet production.
- Single-source concentration in chill casting:European OEMs rely on a concentrated supplier base in Germany's Ruhr industrial zone for high-volume cast iron camshaft blanks, creating vulnerability to energy price shocks.
- Battery electric vehicle substitution:Elimination of valve trains in pure electric architectures threatens volume sustainability in passenger car camshaft demand by 2030.
Strategic Opportunities
- Mexico's Bajío manufacturing cluster:Querétaro and Guanajuato assembly plants serving North American OEMs present white space for localized camshaft machining capacity to reduce cross-border logistics exposure.
- China's MIIT dual carbon policy:Domestic fuel consumption regulations are accelerating adoption of variable cam phasing in light commercial vehicles, opening import substitution opportunities for local forged-steel suppliers.
- Additive manufacturing convergence:Hybrid processes combining near-net-shape 3D printing with precision grinding are enabling low-volume production of prototype camshafts for performance engine builders.
Industry Challenges
- Induction hardening technician scarcity:Specialized heat treatment expertise for achieving 50+ HRC surface hardness on asymmetric lobe profiles is concentrating at German and Japanese equipment OEMs, limiting foundry workforce expansion.
- Multi-axis grinding capex intensity:Five-axis CNC cam grinders requiring seven-figure capital outlays are consolidating machining capacity at Tier 1 suppliers, squeezing independent job shops from premium passenger car contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Camshaft Market |
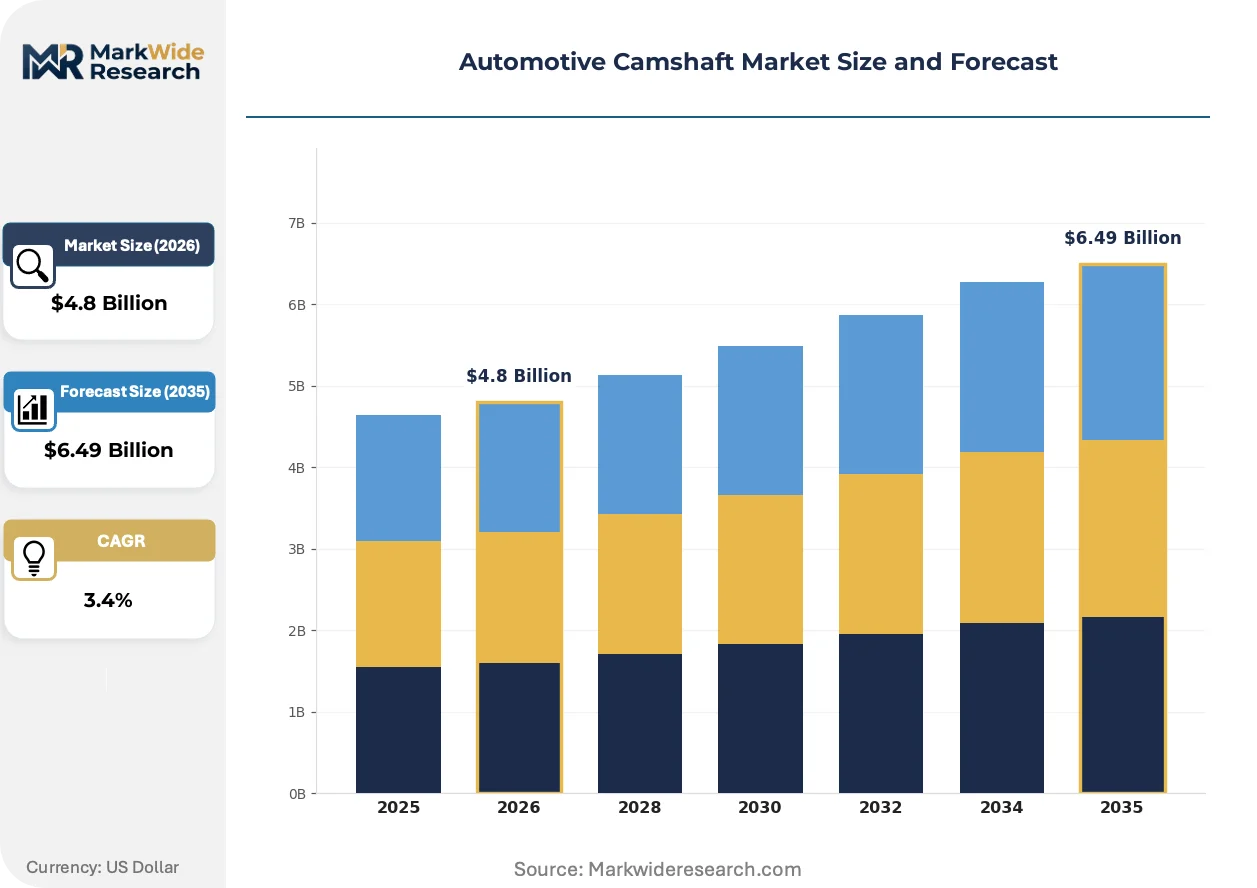
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.49 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Overhead Camshaft, Double Overhead Camshaft, Variable Camshaft Timing, Roller Camshaft Material: Aluminum, Steel, Cast Iron, Composite Material Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Linamar Corporation, Aisin Seiki Co., Ltd., MAHLE GmbH, Elgin Industries, Musashi Seimitsu Industry Co., Ltd., Thyssenkrupp AG, BorgWarner Inc., Melling Engine Parts, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Camshaft Market Strategic Shifts & Innovations
Camshaft engineering is bifurcating toward modular variable timing systems for hybrid applications and cost-optimized fixed designs for commercial durability, with material science and regulatory chemistry shaping competitive differentiation.
Hollow forged steel camshafts with internal oil galleries are electrifying powertrain architectures by enabling 15-20% mass reduction over solid chilled iron alternatives without sacrificing torsional stiffness. Premium passenger car OEMs in Germany and Japan are adopting these architectures for turbocharged direct-injection engines. The technology is electrifying supplier R&D budgets toward integrated cam phaser modules that combine hydraulic actuation with electric motor control.
REACH chemical restrictions and the EU Green Deal are recalibrating surface treatment specifications across European supply chains, banning hexavalent chromium conversion coatings traditionally applied to cam lobe journals. MAHLE GmbH and Thyssenkrupp AG are transitioning to trivalent chromium and plasma electrolytic oxidation processes. Passenger car segments face the steepest compliance timeline, with full phase-out required by 2026 for new platform introductions.
Direct sourcing contracts between OEM powertrain divisions and camshaft machine shops are displacing traditional Tier 1 distributor intermediaries in North America and Western Europe. Ford and General Motors have established preferred supplier programs with dedicated machining capacity for variable valve timing modules. This pattern is most visible in Michigan's automotive supplier corridor, where captive tooling investments now precede multi-year volume commitments.
Automotive Camshaft Market Segmentation
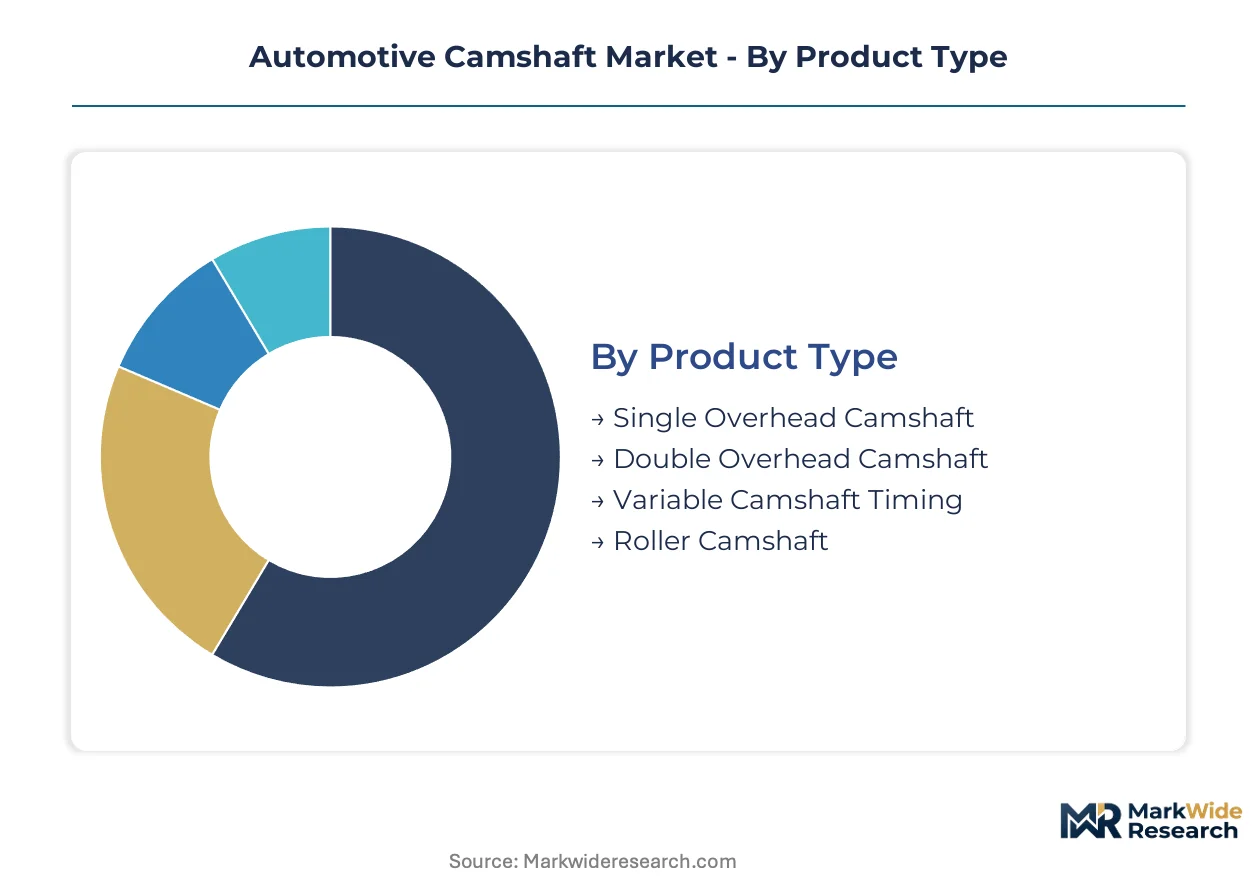
Camshaft procurement patterns diverge sharply between integrated powertrain modules and standalone component sales, with material specifications and vehicle electrification timelines reshaping supplier portfolios across each slice.
Product Type:
Standalone camshaft assemblies serve legacy internal combustion platforms, while integrated variable timing modules embed directly into hybrid powertrain architectures.
- Single Overhead Camshaft:One camshaft per cylinder bank actuates both intake and exhaust valves through rocker arms, a mechanically simple architecture that dominates light commercial vehicle production in India's Chennai-Pune corridor where BS VI compliance demands cost-efficient valve-train solutions.
- Double Overhead Camshaft:Separate intake and exhaust camshafts enable four-valve-per-cylinder configurations with precise lobe profiles, commanding premium positioning in German and Japanese passenger car segments where high-RPM breathing efficiency justifies machining complexity.
- Variable Camshaft Timing:Hydraulic or electric phasers advance or retard camshaft position relative to crankshaft timing, enabling Miller-Atkinson cycle operation for hybrid fuel economy gains.
- Roller Camshaft:Needle-bearing roller followers replace sliding contact to reduce friction losses, finding niche application in high-performance engine builds.
Volume placements concentrate in Single Overhead Camshaft configurations; the faster expansion belongs to Variable Camshaft Timing modules.
Material:
Cost-to-performance ratios separate commodity cast iron from engineered forged alloys, with weight-driven applications pulling toward hollow steel architectures.
- Cast Iron:Chilled cast iron with flake graphite microstructure delivers 50+ HRC surface hardness after induction hardening at the lowest unit cost, anchoring high-volume commercial vehicle production where durability trumps mass reduction.
- Steel:Forged alloy steel with internal oil galleries achieves 15-20% mass reduction over solid alternatives, penetrating turbocharged direct-injection passenger car segments in Germany and Japan where torsional stiffness requirements persist.
- Aluminum:Lightweight extrusions with steel bearing inserts address motorcycle and small-displacement applications.
- Composite Material:Carbon fiber reinforced polymer shafts remain experimental, constrained by thermal expansion mismatch with steel bearing surfaces.
Cast Iron captures the highest shipment tonnage; Steel alloys are climbing the fastest as hollow architectures proliferate.
Vehicle Type:
Electrification timelines fragment demand, with pure electric architectures eliminating valve trains while hybrid platforms sustain camshaft engineering investments.
- Passenger Cars:Double overhead camshaft and variable timing configurations dominate as NHTSA corporate average fuel economy rules push OEMs toward cylinder deactivation and cam-phasing strategies in mid-size segments.
- Commercial Vehicles:Single overhead camshaft designs in cast iron persist for diesel durability, with EPA Tier 4 and Euro 7 emission benchmarks driving precision grinding tolerances in heavy-duty fleets.
- Motorcycles:Compact single-cylinder and V-twin engines favor lightweight aluminum or low-displacement steel shafts.
- Electric Vehicles:Battery electric powertrains eliminate camshaft demand entirely, threatening volume sustainability in passenger segments by 2030.
Commercial Vehicles anchor current procurement tonnage; hybrid-enabled Passenger Car applications show the steepest technology upgrade trajectory.
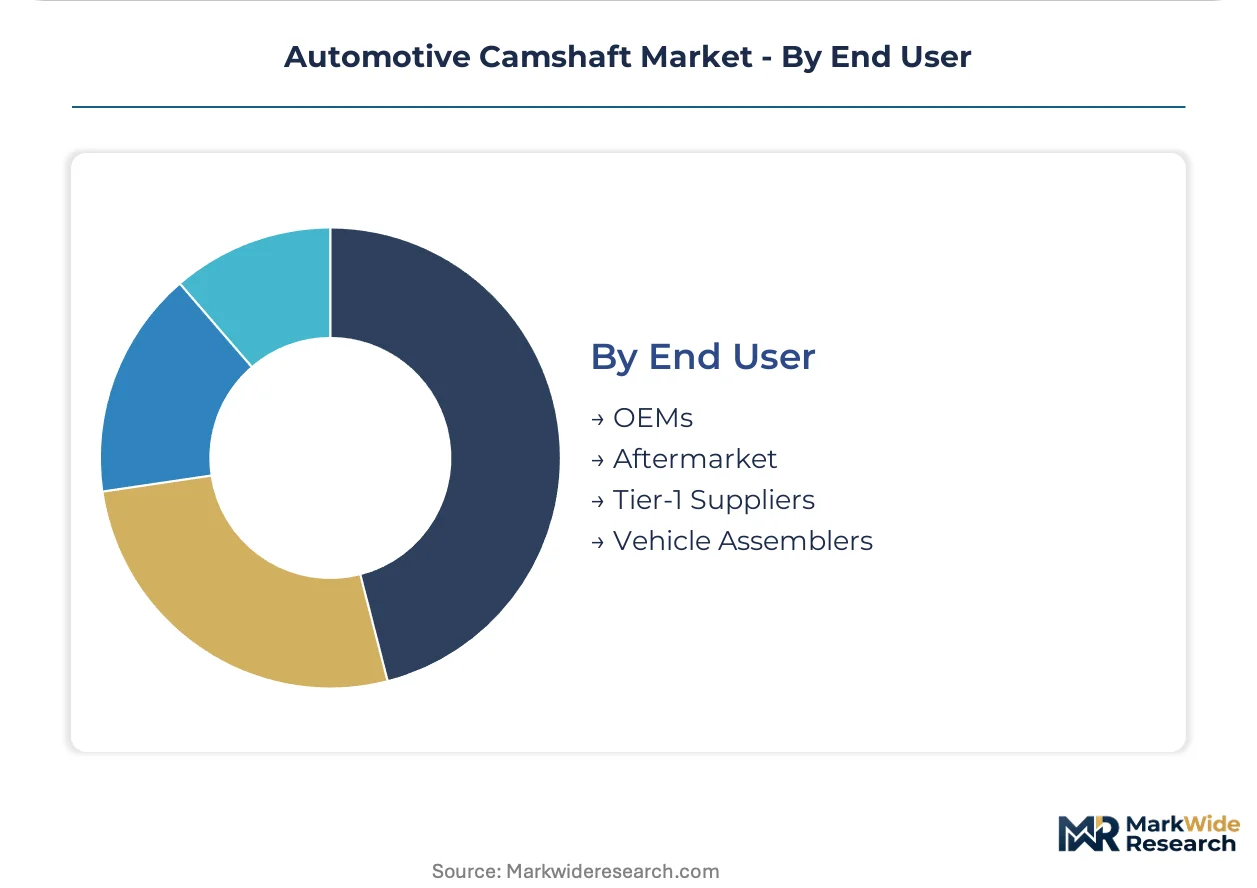
End User:
Supply chain compression is displacing traditional distributor tiers, with direct OEM contracting reshaping margin capture across the value chain.
- OEMs:Ford and General Motors have established preferred supplier programs with dedicated machining capacity for variable valve timing modules, bypassing traditional Tier-1 intermediaries in Michigan's automotive supplier corridor.
- Tier-1 Suppliers:MAHLE GmbH and Schaeffler AG integrate camshaft production into powertrain module assemblies, capturing value through bundled variable timing system sales.
- Aftermarket:Independent repair channels source replacement camshafts for legacy vehicle parc, concentrated in regions with aging fleet demographics.
- Vehicle Assemblers:Contract manufacturers in Mexico's Bajío cluster procure finished camshaft assemblies for final powertrain integration.
OEM direct sourcing commands the largest contract values; Tier-1 Suppliers are gaining share fastest through integrated module offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chennai-Pune automotive corridor anchors procurement intensity for overhead camshaft configurations as India's light commercial vehicle fleet operators upgrade to BS VI-compliant powertrains. EPA Tier 4 and Euro 7 emission benchmarks are tightening valve-train precision requirements across manufacturing clusters in three continents.
United States
NHTSA corporate average fuel economy rules push OEMs toward camshaft-actuated cylinder deactivation in mid-size passenger segments. EPA tailpipe standards mandate precision valve event timing for compliance. Michigan's automotive supplier corridor concentrates direct sourcing contracts between Ford, General Motors, and dedicated machining capacity for variable valve timing modules.
Germany
EU Green Deal recalibrates camshaft material specifications across European supply chains with REACH chemical restrictions banning hexavalent chromium conversion coatings. KBA type-approval processes enforce surface treatment compliance timelines. Thyssenkrupp AG anchors integrated casting-to-machining operations in the Ruhr industrial zone for high-volume cast iron camshaft blanks.
Japan
METI fuel efficiency standards accelerate adoption of hollow forged steel camshafts with internal oil galleries for mass reduction in turbocharged direct-injection engines. JIS quality certifications govern induction hardening specifications. Toyota City and Nagoya manufacturing clusters specialize in variable cam phaser modules combining hydraulic actuation with electric motor control.
Mexico
Querétaro and Guanajuato assembly plants serving North American OEMs present white space for localized camshaft machining capacity. USMCA regional content requirements incentivize nearshoring of powertrain component production. Bajío manufacturing cluster procurement is scaling for overhead camshaft configurations to reduce cross-border logistics exposure.
China
MIIT dual carbon policy and domestic fuel consumption regulations accelerate variable cam phasing adoption in light commercial vehicles. GB standards prescribe tolerances for valve-train precision. Yangtze River Delta manufacturing bases concentrate import substitution opportunities for local forged-steel suppliers serving hybrid powertrain platforms.
Automotive Camshaft Market Key Industry Players
The competitive structure tilts toward integrated powertrain module suppliers with captive machining capacity. Foundries with backward integration into billet production command margin predictability that independent machine shops cannot match. Three archetypes dominate: German-Japanese forged-steel specialists, Ruhr-based chill casting integrated operations, and North American direct-sourcing contract manufacturers. Consolidation pressures concentrate five-axis CNC grinding capacity at Tier 1 suppliers while squeezing independent job shops from premium passenger car contracts.
Among German-based integrated suppliers, Thyssenkrupp AG and MAHLE GmbH exemplify the forged-steel and casting-to-machining archetypes respectively. Schaeffler AG occupies a position within the variable valve timing module specialist tier. These three entities represent the competitive positioning that regulatory chemistry and OEM electrification roadmaps are rewarding across European and North American supply chains.
| Leading Market Players |
|---|
| Linamar Corporation |
| Aisin Seiki Co., Ltd. |
| MAHLE GmbH |
| Elgin Industries |
| Musashi Seimitsu Industry Co., Ltd. |
| Thyssenkrupp AG |
| BorgWarner Inc. |
| Melling Engine Parts |
| Schaeffler AG |
| Others |
Cost & Logistics Intelligence
A material-performance bifurcation between hollow forged-steel architectures and chilled cast-iron commodity grades manifests in divergent pricing power and supplier concentration patterns across automotive powertrain supply chains. Premium passenger car OEMs in Germany and Japan pay yield premiums for 15-20% mass reduction and torsional stiffness, while commercial vehicle operators in India's Chennai-Pune corridor anchor volume procurement at cost-optimized cast-iron price points.
Pricing Analysis
Yield-based pricing anchors hollow forged-steel camshafts where mass reduction translates directly to fuel economy compliance outcomes under NHTSA corporate average fuel economy rules. Three-tier pricing structure across premium, standard, and economy levels separates variable valve timing modules with integrated phasers from fixed-lobe SOHC assemblies and bare replacement shafts. Pricing pressure stems from scrap steel and ferroalloy volatility compressing margin predictability at independent machine shops lacking backward integration into billet production. Tier 1 suppliers with captive forging capacity exhibit lowest price sensitivity; independent job shops face acute cost compression.
Supply Chain Analysis
Cross-border freight costs from Germany's Ruhr industrial zone to European OEM assembly plants concentrate procurement leverage at integrated casting-to-machining operations. Supply draws from Germany, Japan, and China for forged-steel billets; India's Tamil Nadu and Maharashtra clusters for cast-iron blanks; and Mexico's Bajío region for nearshored machining capacity. Raw material dependencies rest on ferrochrome for hardenability, scrap steel for forging feedstock, and specialized grinding wheels for asymmetric lobe profiles. Single-source concentration in chill casting creates vulnerability to energy price shocks. Distribution runs through direct OEM contracting programs displacing traditional Tier 1 intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as players pursue captive control over induction hardening capacity and five-axis grinding equipment to defend margin structures against input volatility.
For Market Incumbents: Deepen backward integration into billet production and induction hardening equipment ownership to offset scrap steel price volatility. Acquire multi-axis grinding capacity in Germany or Japan where specialized technician expertise concentrates, insulating against workforce scarcity that threatens expansion timelines. Defend position against battery electric vehicle substitution by pivoting R&D toward hybrid powertrain variable timing modules.
For New Entrants and Emerging Players: Capture white space in Mexico's Bajío manufacturing cluster where localized machining capacity lags OEM assembly plant expansion under USMCA regional content requirements. Target direct sourcing contracts with North American OEM powertrain divisions that are bypassing traditional Tier 1 intermediaries. Pursue additive manufacturing convergence for prototype and low-volume performance engine builder segments.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated powertrain module suppliers given OEM electrification roadmaps sustaining variable valve timing engineering investments through hybrid proliferation. Long-term viability hinges on exposure to commercial vehicle durability demand and hybrid passenger car technology upgrade cycles. Watch battery electric vehicle penetration rates in premium passenger segments as volume sustainability inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Production | Captive forging capacity insulates margin structures against ferroalloy price volatility at Thyssenkrupp-scale operations. |
| Multi-Axis Grinding Capacity Expansion | Five-axis CNC investment concentrates premium passenger car contract capture away from independent job shops. |
| Variable Valve Timing Module Development | Integrated phaser-hydraulic-electric modules align with Toyota and Honda hybrid powertrain roadmaps. |
| Nearshored Machining in Mexico | Querétaro and Guanajuato assembly proximity reduces cross-border logistics exposure under USMCA rules. |
| Surface Treatment Compliance Transition | Trivalent chromium and plasma electrolytic oxidation processes satisfy EU Green Deal REACH chemical restrictions. |
Research Approach
Document review covered vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and regulatory submissions to EPA and KBA, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and induction hardening equipment specialists. Secondary validation drew from customs trade records, foundry capacity surveys, and OEM powertrain division technical disclosures. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Historical production trajectories were cross-referenced against expert panel inputs from powertrain engineering and procurement functions. Segmentation modeling spanned product type, material grade, vehicle propulsion architecture, and regional production cluster across the projection horizon. CAGRs were derived from slope analysis of segment-specific adoption curves, with hybrid powertrain penetration and emission regulation phase-in schedules serving as primary demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery electric vehicle substitution rates and ferroalloy price volatility. Forecasts reflect documented assumptions about regulatory compliance timelines and OEM platform introduction cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Brazil Automotive Actuators Market
Powertrain
Crankshaft Oil Market
Powertrain
South America Automotive Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Yaw Damper Market
Powertrain
Timing Belt Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Spark Plugs Market
Powertrain
Gear Reduction Starter Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market