
 Transmission Mounting Brackets Market | 2026-2036
Transmission Mounting Brackets Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Mounting Brackets Market Analysis
Electric vehicle powertrain architectures is recalibrating demand specifications across the Transmission Mounting Brackets Market. BorgWarner leverages its powertrain integration expertise to supply brackets engineered for high-torque electric motor mounts. Continental anchors European OEM relationships through its precision aluminum bracket portfolio designed for modular skateboard platforms. Guangzhou Zunyue Auto Parts competes on cost-optimized steel variants serving domestic Chinese vehicle assemblers expanding EV output.
Transmission mounting brackets are structural automotive components, typically fabricated from stamped steel, cast aluminum, or molded rubber-polyurethane composites, that secure the transmission assembly to the vehicle chassis while isolating drivetrain vibrations. Their primary purpose is to maintain powertrain alignment under torque load, thermal cycling, and road-induced stress across internal combustion, hybrid, and fully electric vehicle architectures. Aluminum brackets command premium positioning in OEM channels due to weight-reduction mandates, while polyurethane variants gain traction in aftermarket performance upgrades for durability. Steel brackets sustain volume dominance in fleet and commercial vehicle segments where cost thresholds override mass optimization.
The US NHTSA crashworthiness standards and EPA fuel-economy regulations compel bracket redesigns that reduce mass without compromising structural integrity under collision loads. China's MIIT enforces GB standards for component recyclability, pushing domestic suppliers toward separable multi-material bracket designs. The EU's REACH framework restricts certain rubber curing agents, redirecting European sourcing toward compliant polyurethane formulations. Stakeholders must monitor how battery-electric platform standardization reshapes bracket load-path requirements as skateboard architectures eliminate traditional transmission tunnel mounting points.
Market Dynamics
Electric vehicle skateboard architectures are dismantling traditional transmission tunnel mounting configurations, forcing bracket suppliers to engineer chassis-integrated solutions that manage high-torque electric motor loads across distributed attachment points.
Growth Catalysts
- REACH compliance mandates:The EU's chemical restrictions on rubber curing agents are redirecting European sourcing toward compliant polyurethane bracket formulations, opening material substitution revenue streams for specialized compounders.
- GB standards recyclability:China's MIIT-enforced component separability rules are compelling domestic suppliers to develop multi-material bracket designs with disassembly-ready interfaces.
- Aluminum stamping advances:High-pressure die-casting improvements are reducing aluminum bracket unit costs, accelerating OEM adoption for mass-market electric vehicle platforms.
Market Restraints
- Magnesium price volatility:Lightweight alloy feedstock cost swings are compressing margins for bracket suppliers committed to mass-reduction specifications in premium vehicle segments.
- Tooling concentration risk:Stamping die fabrication capacity clusters in Germany's Ruhr Valley and China's Jiangsu province, creating geographic chokepoints for new program launches.
- Steel bracket substitution ceiling:Commercial fleet procurement teams resist aluminum upcharges despite fuel-economy regulations, locking suppliers into low-margin volume contracts.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced automotive components are attracting bracket manufacturers to establish localized supply for domestic electric vehicle assembly.
- Modular platform standardization:Converging battery-electric architectures across OEMs are creating bracket design commonality opportunities, reducing engineering amortization per program.
- Aftermarket polyurethane upgrades:Performance vehicle owners are retrofitting durability-focused brackets through direct-to-consumer channels, bypassing traditional distribution markups.
Industry Challenges
- Multi-material bonding expertise:Integrating aluminum carriers with polyurethane isolators requires specialized adhesive process control that exceeds traditional stamping shop capabilities.
- Crash certification timelines:NHTSA structural integrity validation for new bracket geometries extends program development cycles, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Mounting Brackets Market |
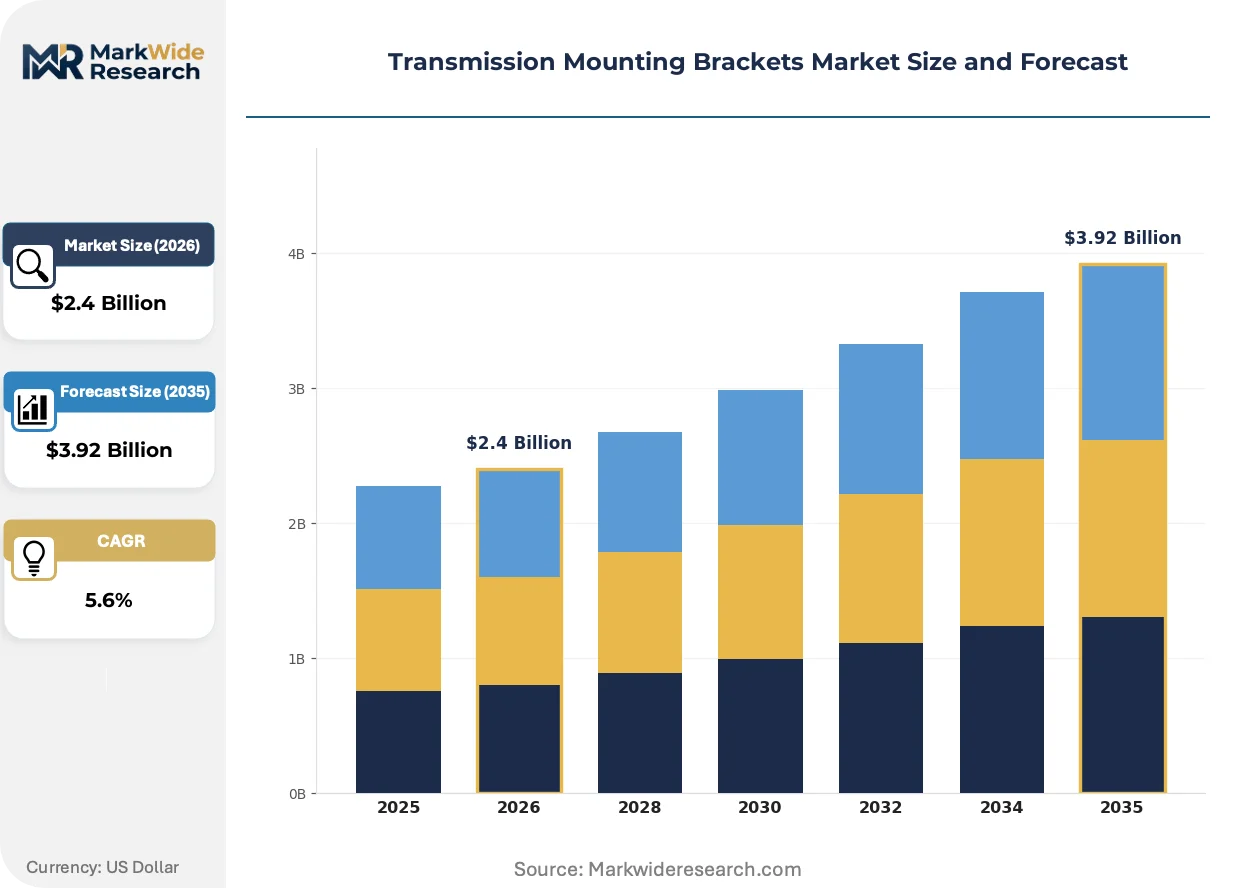
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Polyurethane, Aluminum, Steel End User: Automotive OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Installation Type: Onshore, Offshore, DIY, Professional Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Dorman Products, Continental, A & A Manufacturing, Anchor Industries, Innovative Mounts, Guangzhou Zunyue Auto Parts, Guangzhou Kowze Auto Parts, Benchao Auto Parts, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Mounting Brackets Market Emerging Trajectories
Bracket engineering is pivoting from passive vibration isolation to active load management as electric powertrains impose torque profiles that exceed conventional rubber-isolator damping capacity.
Additive-manufactured aluminum lattice brackets are electrifying structural design possibilities for low-volume electric vehicle programs. Niche performance EV builders are adopting topology-optimized brackets that integrate cooling channel pass-throughs and wiring harness routing. This topology freedom is compressing the traditional stamping-to-casting tooling timeline from months to weeks.
EPA fuel-economy fleet averaging is tightening mass-reduction requirements across light-duty vehicle categories. The regulation is forcing bracket suppliers to document gram-level savings through material substitution and geometry optimization. Passenger car segments are responding fastest, with aluminum variants displacing steel in platforms above compact class.
Automotive procurement teams are consolidating bracket sourcing under powertrain system integrators rather than discrete component suppliers. Tier-1 powertrain module suppliers are absorbing bracket specification authority, compressing direct OEM relationships for standalone bracket manufacturers. This consolidation is most visible in Germany's automotive corridor, where drivetrain integration contracts now bundle bracket supply with motor and inverter packages.
Transmission Mounting Brackets Market Segmentation
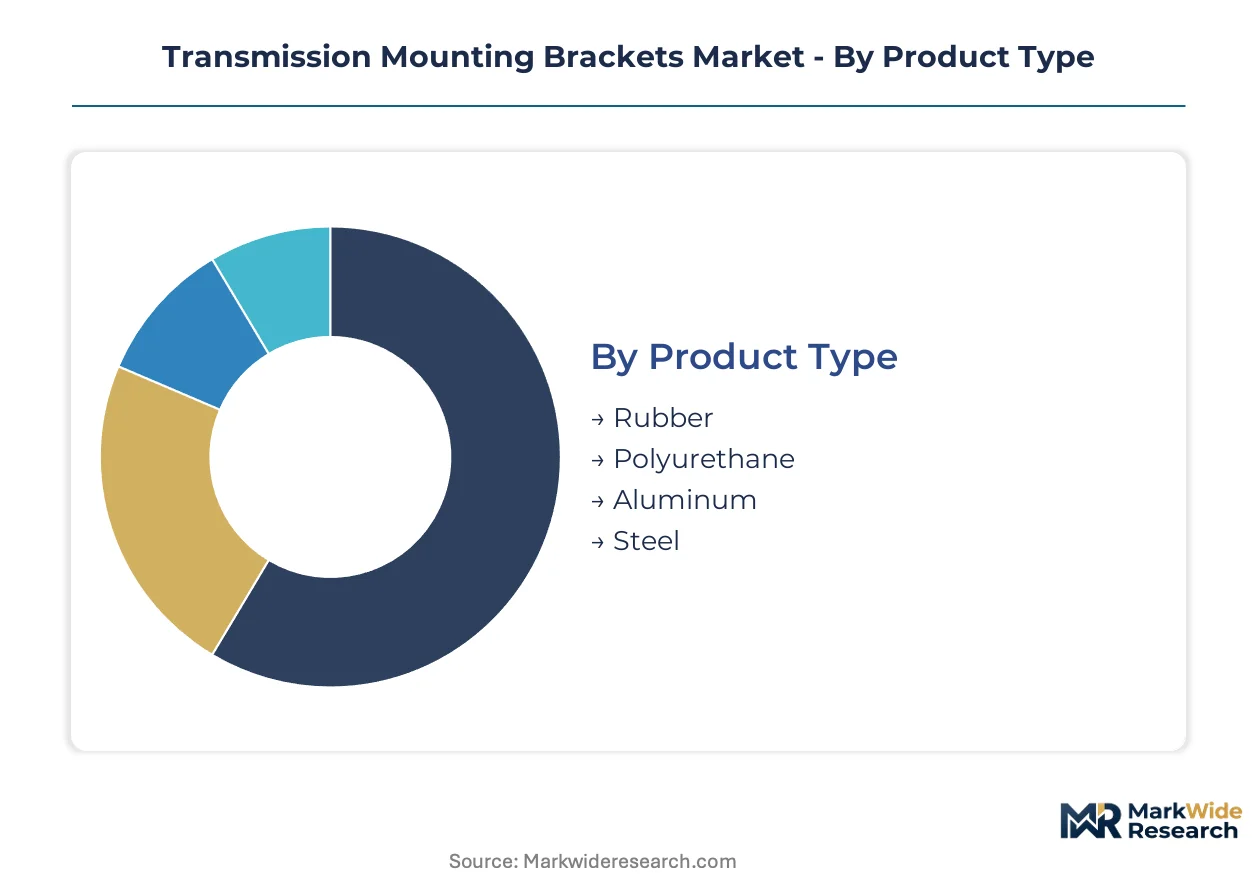
Transmission mounting bracket segmentation reveals how material selection, customer procurement patterns, and installation complexity fragment supplier strategies. Understanding these divides clarifies where engineering investment yields margin versus where cost discipline dominates.
Product Type:
Volume concentration favors stamped steel for fleet and commercial contracts, while premium positioning clusters on aluminum and advanced polymer formulations serving OEM mass-reduction mandates.
- Aluminum:High-pressure die-cast or stamped aluminum brackets deliver 40-60% mass reduction versus steel equivalents. Demand concentrates in Germany's premium OEM corridor and China's Yangtze River Delta electric vehicle assembly belt, driven by EPA fleet averaging and MIIT fuel-consumption regulations that penalize excess curb weight.
- Polyurethane:Injection-molded thermoset polyurethane isolators bond to aluminum carriers for tunable damping characteristics. European sourcing is accelerating as REACH restrictions on traditional rubber curing agents redirect compounder capacity toward compliant formulations; this segment climbs fastest among performance aftermarket channels.
- Rubber:Natural and synthetic rubber isolators remain cost-optimized for high-volume internal combustion platforms where vibration frequencies fall within conventional damping ranges.
- Steel:Stamped mild and high-strength steel brackets sustain fleet operator procurement dominance where acquisition cost thresholds override lifetime fuel-economy gains.
Mature deployment sits with steel variants serving commercial vehicle segments. Newer deployment is concentrated in aluminum-polyurethane hybrid brackets engineered for electric powertrain torque profiles.
End User:
Procurement authority is shifting from discrete component buyers toward system integrators, fragmenting direct OEM relationships while consolidating tier-1 powertrain module contracts.
- Automotive OEMs:Direct specification authority for aluminum and multi-material brackets, with sourcing increasingly bundled under drivetrain integration contracts rather than discrete component procurement.
- Vehicle Assemblers:Contract manufacturers and joint-venture assembly operations in China's manufacturing belt drive steel bracket volume through cost-optimized supply agreements.
- Aftermarket Providers:Polyurethane upgrade demand flows through performance specialists and direct-to-consumer channels, bypassing traditional distribution markups.
- Fleet Operators:Commercial procurement teams resist aluminum upcharges despite regulatory pressure, locking suppliers into long-term steel bracket contracts with minimal price escalation clauses.
System integration is concentrating procurement leverage with automotive OEMs. Margin capture is shifting toward aftermarket providers selling durability upgrades.
Installation Type:
Technical complexity and liability exposure stratify installation economics, with professional channels commanding premium pricing for crash-critical powertrain alignment.
- Professional:Certified technician installation dominates OEM warranty coverage and fleet maintenance contracts, requiring torque-specified fastening and alignment verification.
- Onshore:Domestic assembly plant installation captures bracket supply bundled with chassis marriage operations, particularly in Germany's automotive corridor and the US Midwest assembly hub.
- Offshore:Low-cost country assembly integration concentrates in China's manufacturing belt and Mexico's border maquiladora operations for North American vehicle exports.
- DIY:Enthusiast self-installation concentrates in polyurethane aftermarket retrofits where warranty exposure is minimal and online instructional content reduces technical barriers.
Complex installation sits with professional channels managing OEM liability. Simplified installation is expanding in DIY aftermarket segments.
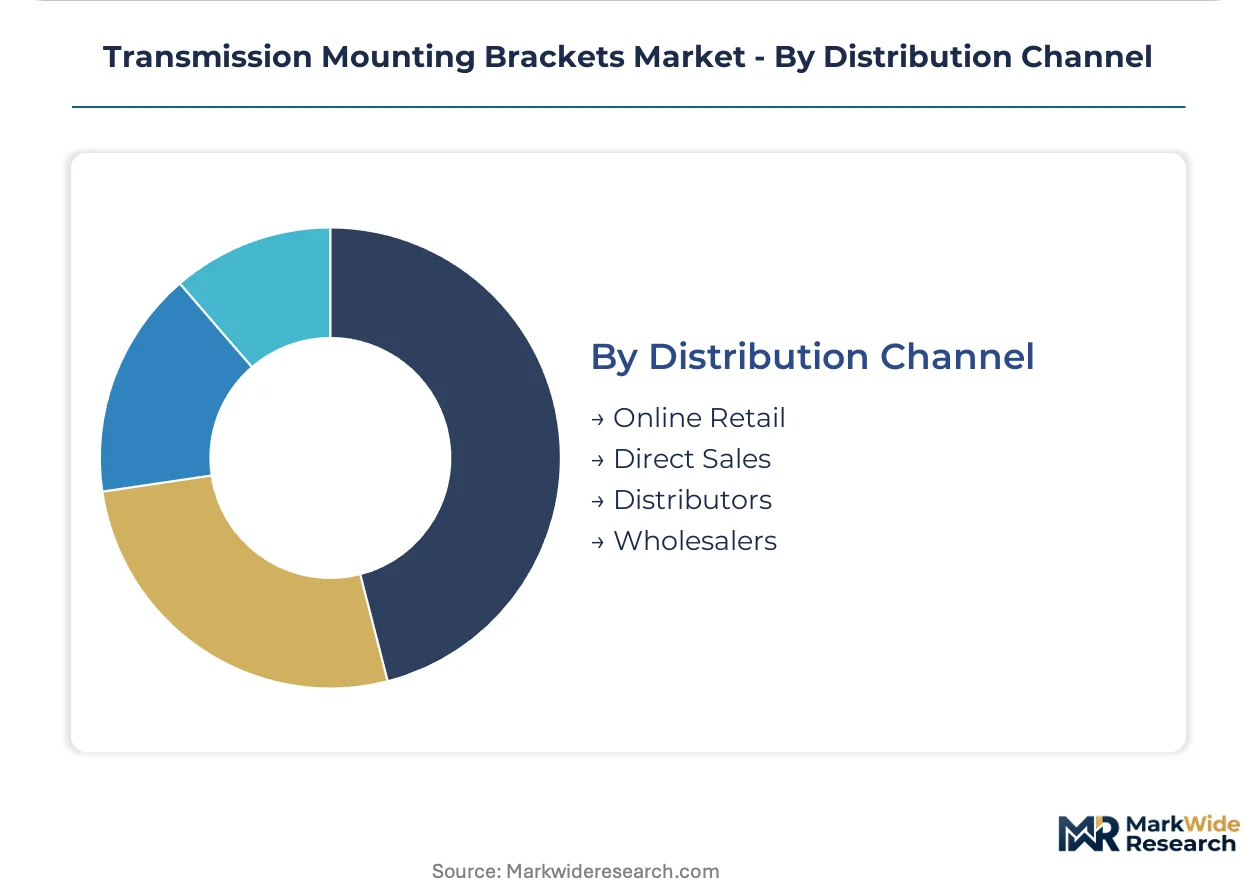
Distribution Channel:
Channel economics reflect customer scale and technical support requirements, with direct sales consolidating among large fleet accounts and tier-1 integrators.
- Direct Sales:OEM and tier-1 powertrain integrator procurement operates through long-term supply agreements with engineering collaboration and program-specific tooling investment.
- Distributors:Regional automotive parts distributors serve independent repair facilities and smaller fleet operators with mixed-brand bracket inventories.
- Online Retail:Direct-to-consumer polyurethane bracket sales are compressing traditional aftermarket distribution margins, particularly among performance vehicle owners.
- Wholesalers:Volume aggregators supply price-sensitive commercial fleet maintenance operations with steel bracket replacements.
Relationship-intensive distribution concentrates with direct sales to integrators. Transactional efficiency is gaining share fastest in online retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones and automotive special economic zones are concentrating transmission mounting bracket production near major vehicle assembly corridors. China's Yangtze River Delta manufacturing belt, Germany's automotive corridor, and the US Midwest assembly hub anchor supply chain density for this component category.
China
MIIT fuel-consumption regulations and GB standards for component recyclability are accelerating aluminum bracket adoption across domestic EV platforms. The Yangtze River Delta manufacturing belt hosts concentrated stamping and die-casting capacity serving BYD, NIO, and Tesla Shanghai. Guangzhou-based suppliers compete on cost-optimized steel variants for volume internal combustion programs.
Germany
REACH chemical restrictions on rubber curing agents are redirecting compounder capacity toward compliant polyurethane formulations. The Baden-Württemberg and Bavaria automotive corridors house precision aluminum bracket fabrication for BMW, Mercedes-Benz, and Porsche electric architectures. Tier-1 powertrain integrators here are consolidating bracket sourcing under bundled drivetrain contracts.
United States
NHTSA crashworthiness standards and EPA fleet fuel-economy averaging compel gram-level mass reduction in bracket engineering. The Michigan-Ohio-Indiana assembly corridor maintains steel bracket dominance for commercial fleet procurement, while California-based EV startups drive aluminum specification for premium electric platforms. Tooling partnerships with Canadian fabricators support cross-border supply security.
India
PLI scheme production-linked incentives for advanced automotive components are attracting bracket manufacturers to establish localized supply. The Tamil Nadu and Maharashtra industrial corridors host emerging EV assembly operations from Tata Motors and Mahindra. Domestic stampers are upgrading aluminum die-casting capabilities to serve export programs for European OEMs.
Mexico
USMCA tariff preferences and proximity to US Midwest assembly plants position border maquiladora operations as nearshore bracket suppliers. The Nuevo León and Baja California automotive corridors host stamping operations serving Ford, GM, and Stellantis export programs. Steel bracket fabrication dominates given commercial fleet cost thresholds in North American markets.
Transmission Mounting Brackets Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-1 powertrain integrators absorbing specification authority from standalone bracket suppliers. The market structure tilts toward consolidation in OEM channels while fragmenting across aftermarket distributors and direct-to-consumer channels. Three archetypes dominate: multinational powertrain system integrators bundling bracket supply with motor and inverter packages; regional metal-forming specialists serving cost-optimized fleet contracts; and polyurethane compounders capturing performance aftermarket upgrades. Competitive moves concentrate on M&A-driven powertrain integration and aluminum die-casting capacity expansion near EV assembly hubs.
Among multinational system integrators, BorgWarner and Continental exemplify the bundled-supply archetype, leveraging powertrain integration expertise to specify chassis-integrated bracket solutions for high-torque electric motor mounts. Guangzhou Zunyue Auto Parts represents the China-based fabricator tier competing on cost-optimized steel variants for domestic vehicle assemblers expanding EV output. These three anchors illustrate how geographic specialization and customer segment focus stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Dorman Products |
| Continental |
| A & A Manufacturing |
| Anchor Industries |
| Innovative Mounts |
| Guangzhou Zunyue Auto Parts |
| Guangzhou Kowze Auto Parts |
| Benchao Auto Parts |
| BorgWarner |
| Others |
Supply Flow & Price Mechanics
Captive aluminum die-casting operations in Germany's Ruhr Valley and China's Jiangsu province anchor supplier pricing power by internalizing high-pressure tooling capacity that OEMs cannot readily replicate. This backward integration into precision metal-forming insulates tier-1 integrators from spot-market volatility while compressing margin capture for standalone stamping houses dependent on outsourced fabrication.
Pricing Analysis
Short lead-time premiums of 15-25% apply to aluminum bracket orders requiring sub-8-week delivery windows for EV platform launches, while spot inventory of steel variants trades at discounts to contract baselines. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant polyurethane formulations from conventional rubber isolators and commodity steel stampings. Cost compression in fleet steel brackets is intensifying because commercial procurement teams resist aluminum upcharges despite EPA fuel-economy mandates. Fleet operators exhibit highest price sensitivity, locking suppliers into multi-year contracts with minimal escalation clauses, while premium OEM channels absorb aluminum premiums for mass-reduction compliance.
Supply Chain Analysis
Aluminum ingot supply rests on smelter concentration in China, Russia, and the Gulf states, with high-purity primary aluminum drawing from Canadian hydro-powered operations for European automotive specifications. Polyurethane precursor chemicals hinge on German and Belgian specialty chemical producers, while rubber compounding feeds from Thai and Indonesian natural rubber plantations. Single-source vulnerability concentrates in high-pressure die-casting tooling fabricated exclusively by German and Japanese machine builders. Distribution runs through tier-1 powertrain integrators bundling bracket supply with motor and inverter packages, bypassing traditional component distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tooling fabrication chokepoints in Germany's Ruhr Valley and China's Jiangsu province prop pricing power by constraining new program launch capacity, creating supply-constrained conditions favoring incumbent integrators with captive die-casting operations.
For Market Incumbents: Anchor market position through backward integration into aluminum high-pressure die-casting capacity near EV assembly hubs in the US Midwest and China's Yangtze River Delta. Defend against tier-1 powertrain bundling by securing standalone OEM relationships through crash-certification investment that accelerates NHTSA validation timelines. Prioritize REACH-compliant polyurethane formulation R&D to capture European material substitution revenue as ECHA restrictions tighten. For New Entrants and Emerging Players: Aftermarket polyurethane upgrade specialists represent the most penetrable buyer archetype, with direct-to-consumer channels bypassing traditional distribution markups. Target performance EV builders in California and niche European sports car manufacturers requiring topology-optimized aluminum lattice brackets for low-volume programs. Pursue white-label supply agreements with Amazon and RockAuto digital platforms to establish brand presence without legacy distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by tier-1 powertrain integrators seeking aluminum bracket fabrication capabilities for skateboard platform contracts. Long-term viability favors suppliers with demonstrated multi-material bonding expertise integrating aluminum carriers with polyurethane isolators. Watch for battery-electric platform standardization across OEMs as the inflection signal triggering consolidation urgency among standalone bracket manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Die-Casting | Captive high-pressure tooling capacity insulates margins from German and Chinese fabrication chokepoints. |
| REACH-Compliant Polyurethane Formulation Investment | ECHA chemical restrictions redirect European sourcing toward compliant compounders with certified supply. |
| Topology-Optimized Additive Manufacturing Capability | Lattice bracket designs compress tooling timelines from months to weeks for niche EV builders. |
| Crash Certification Acceleration Programs | NHTSA structural integrity validation expertise shortens OEM program development cycles. |
| Direct-to-Consumer Digital Channel Development | Online retail bypasses traditional aftermarket distribution markups for polyurethane upgrade demand. |
Methodological Framework
Document review covered vehicle production databases, IHS Markit registration data, SEC 10-K filings from tier-1 suppliers, and MIIT fuel-consumption regulation filings, complemented by interviews with OEM platform engineers, tier-1 powertrain procurement managers, aluminum die-casting plant managers, and aftermarket distribution channel heads. Secondary validation drew from NHTSA crashworthiness standards documentation, ECHA REACH substance restrictions, and EPA fleet fuel-economy averaging reports. Bottom-up bracket demand modeling triangulated against top-down automotive production forecasts across the analysis window.
Segmentation outputs reflect vehicle class, propulsion architecture, material grade tier, and regional production cluster dimensions modeled throughout the forecast period. CAGRs derived from regression analysis of historical bracket content per vehicle trajectories, weighted by EV platform rollout schedules and regulatory compliance deadlines. Industry-specific inputs incorporated aluminum stamping yield improvements and polyurethane compounder capacity expansion timelines.
Revisions become necessary when battery-electric platform standardization accelerates beyond modeled adoption curves, or when magnesium price volatility disrupts lightweight alloy substitution economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Small Gas Engine Market
Powertrain
Global Automotive Clutch Market
Powertrain
Transmission Fluids Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Natural Gas Engines Market
Powertrain
Automotive Half Shaft Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Automotive Coil Spring Market
Powertrain
Global Driveline Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
CNG Powertrain Market
Powertrain
Clutch Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Variable Displacement Compressor Market