
 Automotive Engine Degreasers Market | 2026-2036
Automotive Engine Degreasers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Degreasers Market Analysis
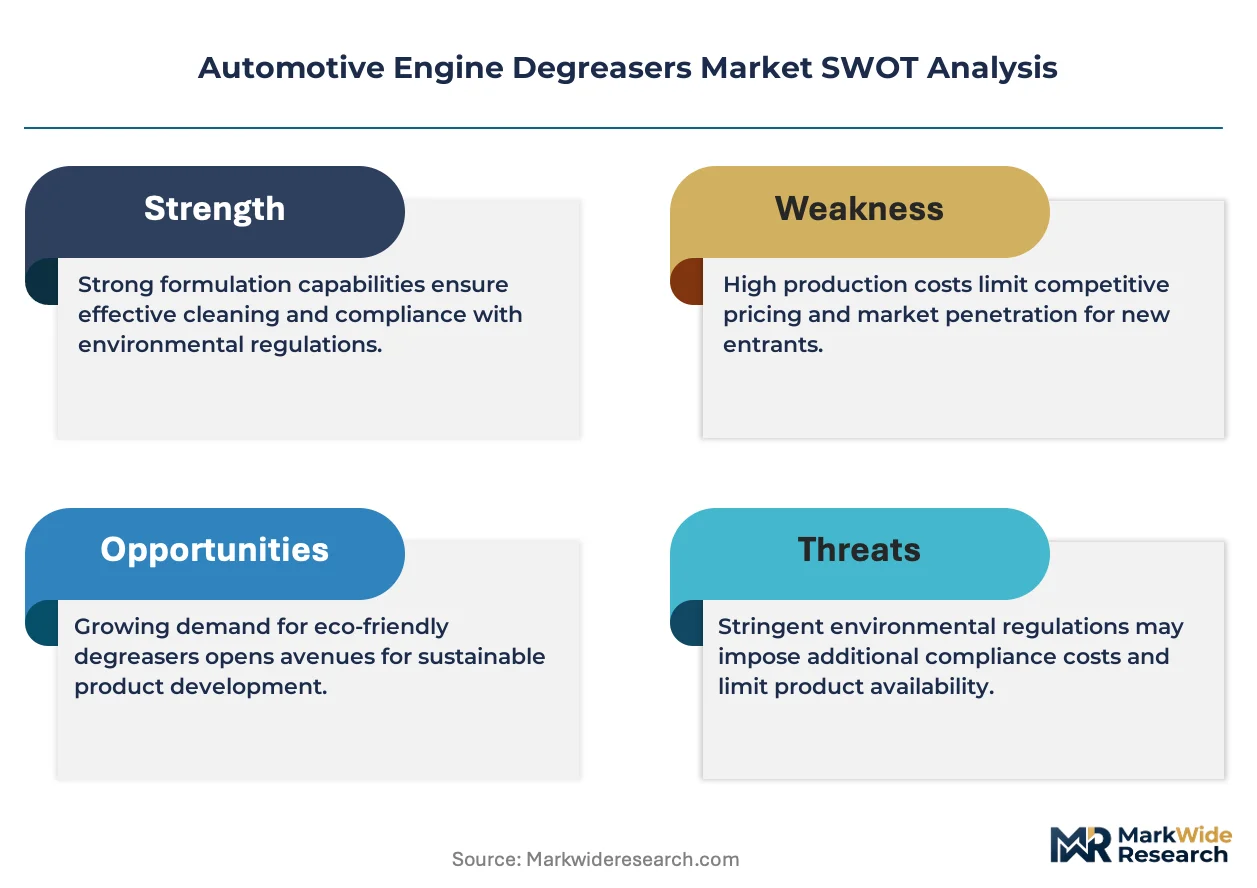
Buyer concentration among fleet operators is expanding as logistics companies bring more maintenance in-house, shifting volume from fragmented individual consumers toward contract-based supply agreements. WD-40 Company leverages its retail channel density to sustain consumer access, while Zep Inc. anchors commercial and industrial accounts through direct distribution. Fuchs Group differentiates with specialized formulations for OEM validation protocols.
Automotive engine degreasers are formulated cleaning agents designed to dissolve petroleum-based soils, carbon deposits, and grease accumulations from internal combustion engine components, typically delivered as aqueous emulsions, hydrocarbon solvents, or bio-based surfactant blends with flash points and pH levels calibrated for aluminum and rubber compatibility. Aqueous degreasers lead volume due to regulatory tailwinds, while biodegradable variants represent the fastest-expanding category as fleet sustainability targets harden. Spray bottles dominate aftermarket convenience channels, though drums command the margin pool in industrial direct sales.
The EPA regulates VOC content under 40 CFR Part 59, while OSHA's Hazard Communication Standard governs workplace exposure labeling; California Air Resources Board rules further tighten allowable solvent thresholds, pushing manufacturers toward water-based and bio-derived chemistries. The EU REACH framework and F-Gas Regulation constrain solvent imports for suppliers serving parallel export markets. Stakeholders must monitor evolving state-level chemical restriction cascades and fleet electrification timelines that will redefine degreaser duty cycles and formulation requirements.
Market Dynamics
Fleet electrification timelines are compressing degreaser duty cycles while EPA and California Air Resources Board VOC restrictions force immediate reformulation of solvent-based chemistries toward aqueous and bio-derived alternatives.
Growth Catalysts
- Fleet In-House Maintenance:Logistics operators are expanding captive service bays across Texas and Southeast automotive corridors, consolidating fragmented aftermarket demand into multi-year supply agreements.
- EPA Safer Choice Program:Federal procurement preferences for low-emission chemistries are pulling aqueous formulations into government vehicle maintenance contracts.
- Aluminum Engine Block Proliferation:OEM validation protocols for pH-neutral degreasers are expanding addressable volume as manufacturers protect lightweight powertrain components.
Market Restraints
- Petrochemical Feedstock Volatility:Surfactant and solvent input costs fluctuate with crude oil indices, compressing margin on hydrocarbon-based formulations.
- California VOC Threshold Compression:Air Resources Board rules tightening allowable solvent content create compliance friction for national product lines.
- Aqueous Performance Ceiling:Water-based chemistries struggle with carbonized deposit removal on heavy-duty diesel blocks, limiting substitution depth.
Strategic Opportunities
- Biodegradable Surfactant Convergence:Plant-derived alkyl polyglucosides combined with enzymatic cleaners open premium positioning for fleet sustainability targets.
- Concentrate Dilution Systems:On-site mixing equipment reduces shipping mass and plastic packaging, creating recurring revenue attachments for industrial accounts.
- EV Thermal Management Cleaning:Battery pack and electric motor degreasing protocols represent nascent application white space as electrification accelerates.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in surfactant synergy and corrosion inhibition for multi-metal compatibility commands premium compensation and extends R&D timelines.
- Multi-Jurisdiction Labeling Burden:OSHA Hazard Communication Standard, EPA registration, and state-level disclosure requirements fragment packaging workflows.
- Legacy Equipment Compatibility:Aqueous chemistries demand stainless steel dispensing infrastructure incompatible with existing solvent-based parts washer installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Degreasers Market |
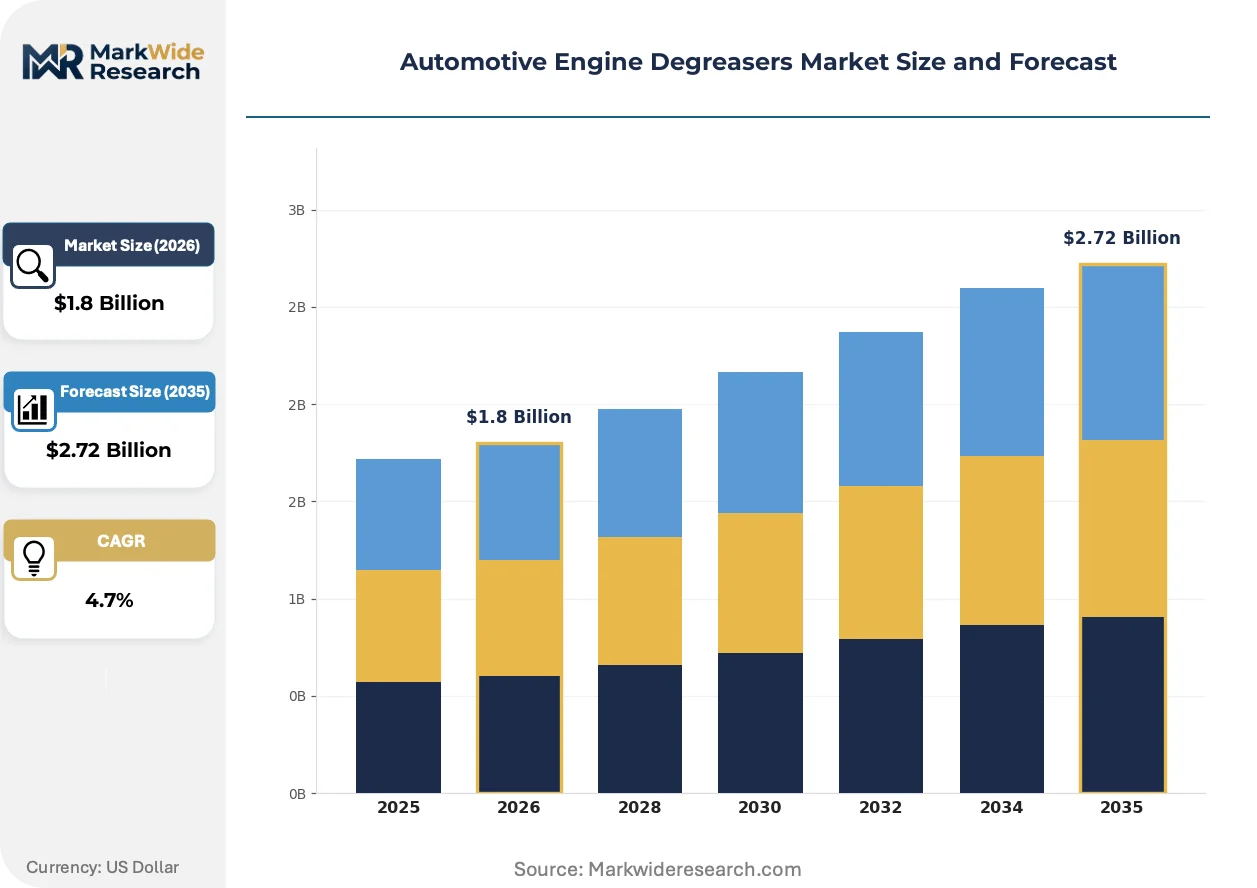
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Degreasers, Solvent-Based Degreasers, Biodegradable Degreasers, Heavy-Duty Degreasers Application: Automotive, Industrial, Marine, Aviation End User: OEMs, Aftermarket Repair Shops, Fleet Operators, Individual Consumers Packaging Type: Cans, Drums, Pails, Spray Bottles |
| Companies Covered | 3M, WD-40 Company, Zep Inc., GUNK, Penray, ABRO Industries, Valvoline, Fuchs Group, The B'laster Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Degreasers Market Emerging Trajectories
Bio-based surfactant technology is consolidating market share as regulatory pressure compounds with fleet sustainability mandates, while procurement patterns favor concentrated formulations that reduce logistics intensity.
Enzymatic degreaser technology is consolidating performance validation across heavy-duty fleet maintenance protocols. Protease and lipase blends break down organic soils at ambient temperatures, cutting energy costs for heated wash systems. Fleet operators in California and Texas are piloting these formulations, compressing adoption timelines from niche to standard specification within five years.
California Air Resources Board VOC thresholds are tightening faster than federal baselines, creating a bifurcated compliance landscape. Manufacturers must maintain parallel product lines or surrender solvent-based revenue in the state. Aqueous and bio-derived chemistries capture disproportionate shelf space in California distribution, with spillover influence on Southeast fleet procurement standards.
Direct distribution contracts are displacing traditional wholesale channels for volume fleet accounts. Zep Inc. and industrial specialists are building captive logistics networks to serve centralized maintenance facilities. This pattern concentrates most visible in Texas and Georgia, where megafleet operators negotiate formulation customization and drum-to-tote delivery schedules.
Automotive Engine Degreasers Market Segmentation
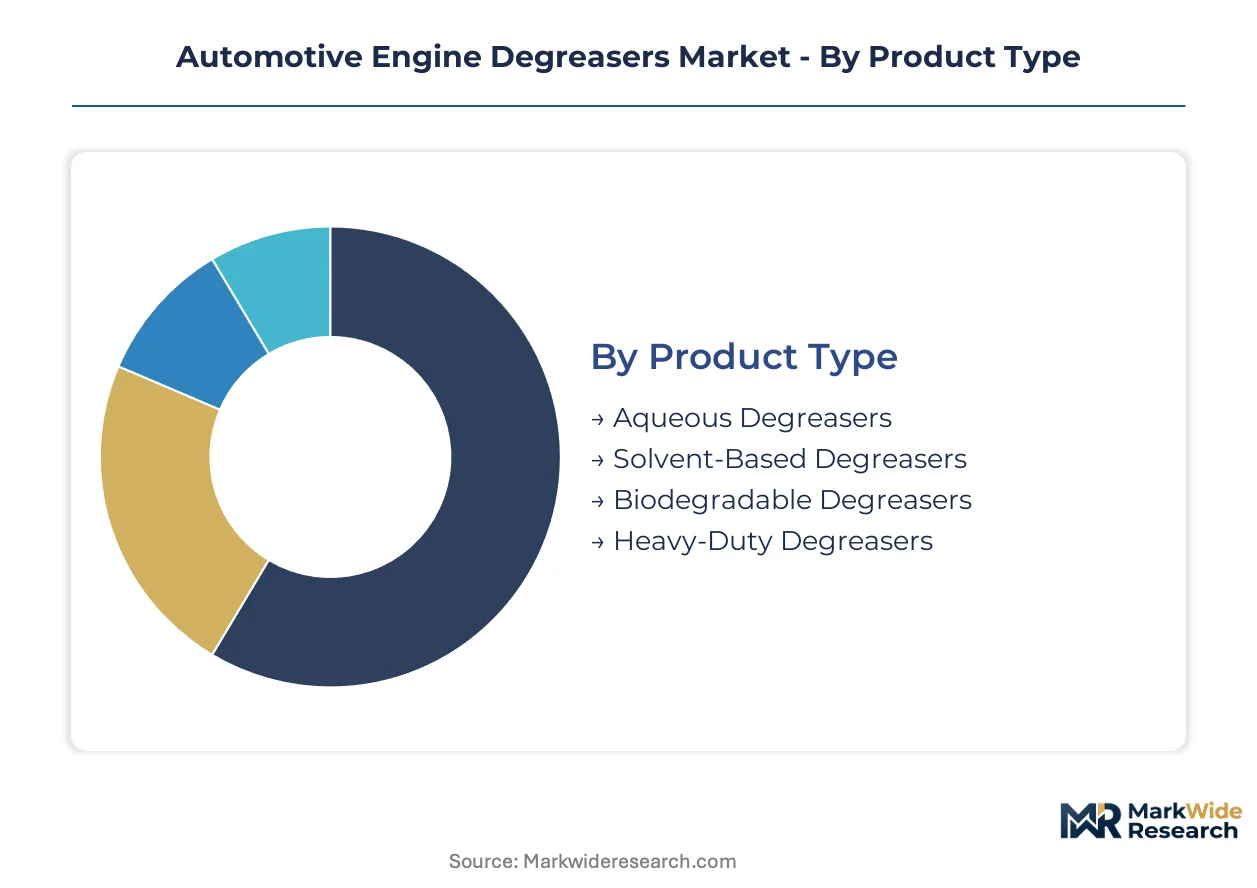
Automotive engine degreaser procurement patterns diverge sharply across formulation chemistry, application intensity, and packaging economics. Fleet electrification timelines and EPA VOC enforcement are compressing replacement cycles for legacy solvent formulations while opening specification windows for bio-derived alternatives.
Product Type:
Reformulation investments track the upgrade cycle from hydrocarbon solvents to aqueous and bio-based chemistries as regulatory thresholds tighten.
- Aqueous Degreasers:Water-based emulsions with surfactant packages calibrated for aluminum compatibility dominate procurement volumes under EPA Safer Choice preferences. Fleet operators in Texas and Southeast automotive corridors are consolidating specifications around pH-neutral aqueous formulations to satisfy multi-metal engine block cleaning protocols without corrosion risk.
- Solvent-Based Degreasers:Hydrocarbon and chlorinated formulations retain residual share for carbonized deposit removal on heavy-duty diesel applications where aqueous performance hits practical limits. California Air Resources Board VOC thresholds are forcing phased withdrawal from state-procured contracts, compressing addressable geography for this chemistry class.
- Biodegradable Degreasers:Plant-derived alkyl polyglucosides and enzymatic surfactant blends address fleet sustainability targets with ambient-temperature cleaning performance.
- Heavy-Duty Degreasers:High-pH caustic formulations serve industrial remanufacturing and marine engine overhaul applications requiring aggressive soil penetration.
Volume placements concentrate in aqueous degreasers; the faster expansion belongs to biodegradable formulations.
Application:
End-use intensity correlates with engine duty cycles and maintenance protocol standardization across transportation modes.
- Automotive:Passenger vehicle and light-truck maintenance drives highest absolute volume through aftermarket retail and service bay channels. Southeast US manufacturing clusters and Texas fleet hubs anchor demand concentration as captive maintenance capabilities expand.
- Industrial:Power generation equipment, agricultural machinery, and construction vehicle cleaning protocols specify concentrated formulations delivered in bulk tote systems. OSHA Hazard Communication Standard compliance costs elevate procurement thresholds for smaller industrial accounts.
- Marine:Saltwater corrosion protection requirements and EPA vessel general permit discharge rules favor biodegradable chemistries with rapid aquatic toxicity degradation profiles.
- Aviation:FAA-approved formulations for turbine engine cleaning command premium positioning through specialized distributors serving MRO facilities.
Procurement scale peaks in automotive applications; aviation specifications carry the steepest margin premiums.
End User:
Buyer consolidation patterns reshape channel economics as volume aggregates toward contract-based supply relationships.
- OEMs:Validation protocols for production-line engine cleaning and warranty-service specifications drive formulation standardization. Aluminum engine block proliferation requires pH-neutral degreasers compatible with lightweight powertrain materials.
- Aftermarket Repair Shops:Fragmented demand across independent service bays sustains spray-bottle and aerosol convenience packaging through wholesale distribution. Margin compression from parts retailer consolidation pressures procurement flexibility.
- Fleet Operators:Logistics companies expanding in-house maintenance capabilities in Georgia and Texas are displacing traditional wholesale channels with direct drum and tote supply agreements. Multi-year contracts enable formulation customization and scheduled delivery logistics.
- Individual Consumers:DIY maintenance segment concentrates in retail auto parts chains and mass merchandisers, with WD-40 Company channel density sustaining access.
Contract value concentrates with fleet operators; OEM validation requirements impose the longest qualification timelines.
Packaging Type:
Logistics intensity and dispensing infrastructure compatibility govern format selection across customer tiers.
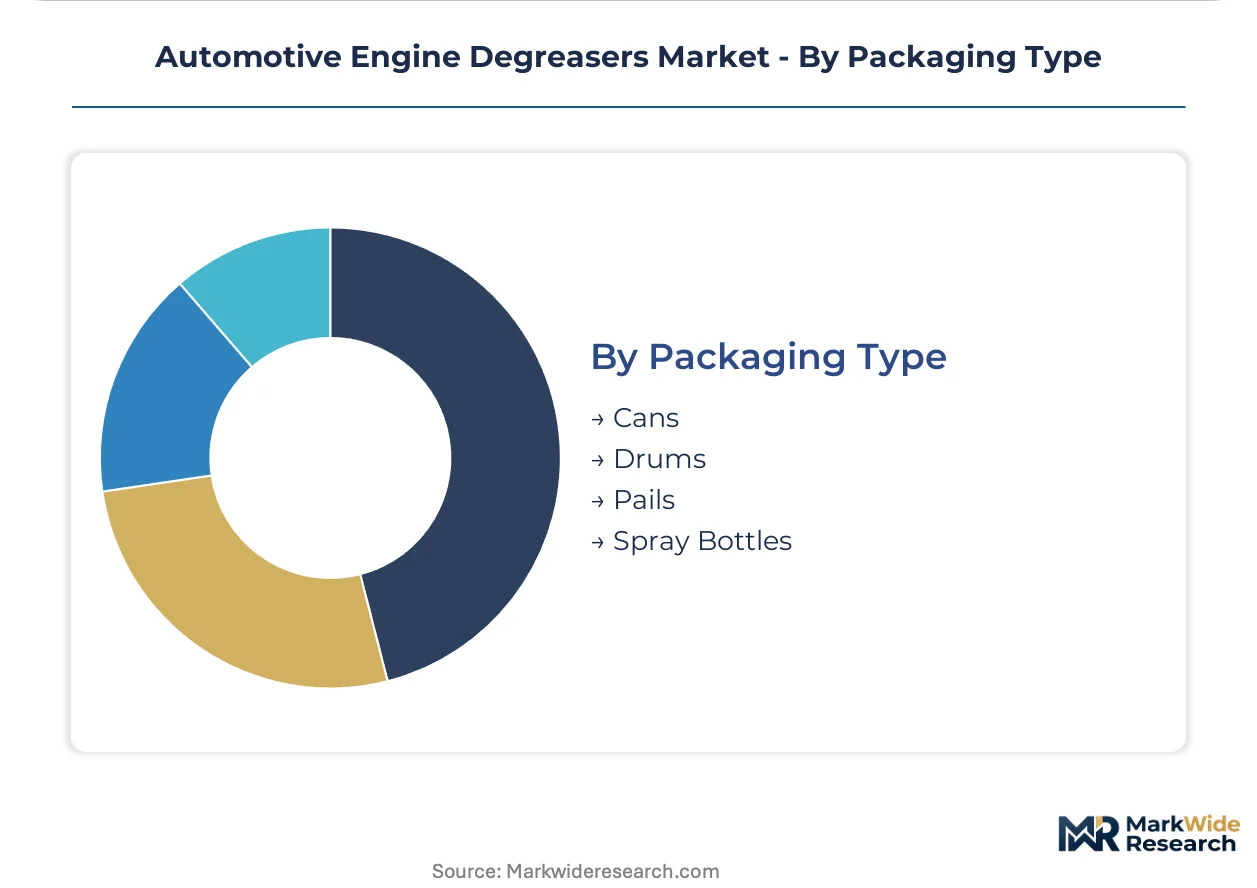
- Spray Bottles:Trigger-spray polyethylene containers dominate aftermarket convenience channels and consumer retail, offering immediate-use accessibility without dilution equipment. Shelf space competition in auto parts chains drives packaging differentiation.
- Drums:Steel and fiber drums command industrial direct sales margins, serving centralized maintenance facilities with high-volume dispensing systems. Fleet operators in Texas negotiate drum-to-tote delivery schedules with formulation specialists.
- Cans:Aerosol and screw-top metal containers address spot-cleaning applications and field service portability requirements.
- Pails:Five-gallon polyethylene pails bridge mid-volume service bay needs with stackable storage economics.
Unit volume peaks in spray bottles; drum formats capture the margin pool in industrial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet maintenance consolidation concentrates procurement volume in the United States, particularly across Texas and Southeast automotive corridors, while regulatory divergence between California and federal EPA standards fragments formulation requirements.
United States
Texas fleet hubs and Georgia manufacturing clusters anchor North American demand as logistics operators expand captive service bays. EPA Safer Choice program preferences pull aqueous formulations into federal vehicle maintenance contracts. Southeast automotive manufacturing corridors concentrate OEM validation activity for pH-neutral degreasers protecting aluminum engine blocks.
Germany
Automotive OEM supply chain proximity drives specification standardization for production-line engine cleaning protocols. EU REACH framework and F-Gas Regulation constrain solvent import portfolios for suppliers serving parallel export markets. Baden-Württemberg manufacturing clusters enforce stringent multi-metal compatibility requirements extending qualification timelines.
China
Domestic automotive production scale generates aftermarket volume through independent service networks and fleet maintenance expansion. MIIT emission standards and GB technical regulations pressure reformulation toward water-based chemistries. Yangtze River Delta manufacturing bases concentrate surfactant production capacity serving regional formulation demand.
Japan
Premium automotive export quality standards propagate stringent degreaser specifications through global supply chains. METI chemical management frameworks and JIS standards govern workplace exposure limits and product labeling requirements. Kanto region automotive clusters maintain validation protocols for precision engine component cleaning applications.
India
Commercial vehicle fleet expansion and two-wheeler density create fragmented aftermarket demand across independent repair networks. BIS quality standards and state-level pollution control board rules tighten solvent discharge parameters for industrial users. Maharashtra and Gujarat manufacturing corridors concentrate automotive production driving OEM specification adoption.
Automotive Engine Degreasers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based specialization and concentrate dilution system attachments. The vendor base stratifies across formulation chemistries rather than geographic coverage, with aqueous specialists capturing regulatory tailwinds and solvent-based incumbents defending heavy-duty diesel applications. Three archetypes dominate: diversified chemical conglomerates with surfactant backward integration, regional formulation specialists serving fleet direct contracts, and retail-channel brands leveraging distribution density. Competitive moves center on M&A for surfactant supply security and strategic partnerships for enzymatic technology licensing.
Within the diversified chemical tier, 3M and Fuchs Group exemplify multinational positioning across industrial and automotive validation protocols. Zep Inc. and WD-40 Company anchor the Americas-focused direct distribution and retail channel vectors respectively. Among specialized degreaser formulators, GUNK and The B'laster Corporation occupy positions in the North American aftermarket convenience segment, while ABRO Industries represents the emerging-market export specialist archetype serving price-sensitive service bay networks.
| Leading Market Players |
|---|
| 3M |
| WD-40 Company |
| Zep Inc. |
| GUNK |
| Penray |
| ABRO Industries |
| Valvoline |
| Fuchs Group |
| The B'laster Corporation |
| Others |
Supply Flow & Price Mechanics
Crude oil index volatility cascades through surfactant and hydrocarbon solvent costs, compressing margins on legacy formulations while aqueous and bio-derived alternatives capture pricing power through EPA Safer Choice procurement preferences. Fleet operators in Texas and Georgia leverage multi-year contract scale to negotiate drum-to-tote delivery schedules, fragmenting pricing tiers between retail convenience packaging and industrial direct sales.
Pricing Analysis
Volume concentrates in spray-bottle retail formats where shelf-space competition erodes margin, while drum and tote formats for fleet direct contracts capture superior economics through formulation customization and scheduled logistics. Price differentiation separates pH-neutral aqueous formulations validated for aluminum engine blocks from commodity solvent-based cleaners facing California Air Resources Board compliance friction. Pricing pressure intensifies on hydrocarbon-based products as petrochemical feedstock indices fluctuate, with individual consumers showing highest price sensitivity and OEM validation-tier buyers accepting premium positioning for multi-metal compatibility guarantees.
Supply Chain Analysis
Single-source vulnerability sits with concentrated surfactant production in the Yangtze River Delta, where alkyl polyglucoside and enzymatic cleaner precursor manufacturing anchors global bio-based formulation supply. Raw material dependencies include petroleum-derived solvents, plant-derived surfactants, and corrosion inhibition additives sourced from China, Germany, and domestic US chemical corridors. Supply chain risk centers on tariff exposure for imported enzymatic technology and California-specific VOC compliance requirements fragmenting national product lines. Distribution runs through direct fleet contracts displacing traditional wholesale channels, with Zep Inc. and industrial specialists building captive logistics networks for centralized maintenance facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where California VOC threshold compression and fleet electrification timelines force solvent-dependent formulators toward exit or acquisition. Regulatory compliance costs and R&D chemist scarcity advantages scaled aqueous specialists.
For Market Incumbents: Hedge hydrocarbon formulation exposure by accelerating aqueous and enzymatic R&D investment to capture EPA Safer Choice procurement preferences before California rules cascade to Southeast fleet standards. Secure backward integration into surfactant supply or captive enzymatic technology licensing to defend margin position against feedstock volatility and formulation chemist scarcity.
For New Entrants and Emerging Players: Enter via EV thermal management cleaning protocols and battery pack degreasing specifications, white-space applications where validation protocols remain undefined and first-mover qualification timelines compress competitive response. Target fleet sustainability officers in Texas and Georgia with biodegradable surfactant blends and on-site concentrate dilution systems that create recurring revenue attachments.
For Investors and Strategic Acquirers: Distressed-cycle entries favor aqueous formulation specialists with EPA Safer Choice certifications and established fleet direct contracts in the Southeast automotive corridor. Long-term viability hinges on electrification-adjacent cleaning protocol development and surfactant backward integration; watch for California Air Resources Board rule spillover into federal procurement standards as the inflection signal for accelerated aqueous adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Supply | Captive alkyl polyglucoside production insulates margin from petrochemical index volatility and China supply concentration. |
| Enzymatic Technology Licensing Agreement | Protease and lipase blend access accelerates ambient-temperature formulation validation for fleet sustainability targets. |
| Long-term Supply Agreement with Fleet Operators | Multi-year drum-to-tote contracts in Texas and Georgia lock volume and enable formulation customization. |
| Green Manufacturing Transition | Bio-derived chemistry conversion captures EPA Safer Choice procurement preferences and California shelf-space allocation. |
| Joint Venture for Concentrate Dilution Systems | On-site mixing equipment attachments create recurring revenue and reduce plastic packaging logistics intensity. |
Methodological Framework
Document review covered EPA registration databases, OSHA Hazard Communication Standard filings, and California Air Resources Board rulemaking records, complemented by interviews with fleet maintenance directors, OEM validation engineers, surfactant procurement leads, and aftermarket distribution channel managers. Secondary validation drew from customs trade data, chemical industry association reports, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up segment sizing triangulated against top-down market aggregation across formulation chemistry, application intensity, and packaging economics.
Model outputs span value and volume projections across the analysis window, with segmentation dimensions including product type (aqueous, solvent-based, biodegradable, heavy-duty), end user archetype (OEM, fleet operator, aftermarket repair, consumer), and regional production cluster. CAGRs derive from regression analysis of historical formulation substitution patterns and regulatory enforcement trajectories, incorporating fleet electrification timelines and EPA VOC threshold evolution as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated electrification adoption or state-level chemical restriction cascades beyond California. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and surfactant technology maturation curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Clutch Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Europe Turbocharger Market
Powertrain
Yaw Damper Market
Powertrain
Automotive Powertrain Market
Powertrain
Global Industrial Engine Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Dual Clutch Transmission (DCT) Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Car Drive System Market
Powertrain
Crankshaft Oil Market
Powertrain
Exhaust Flexible Couplings Market