
 Europe Container Terminal Operations Market | 2026-2036
Europe Container Terminal Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Container Terminal Operations Market Analysis
ISO 14001 environmental management certification is reorganizing competitive access across European container terminals. HHLA International leverages its Hamburg hub infrastructure to sustain Baltic-North Sea transshipment dominance. APM Terminals anchors its position through Rotterdam's Maasvlakte automated stack operations. CMA CGM Terminals differentiates via vertical integration with parent fleet scheduling at Marseille-Fos.
Europe container terminal operations encompass the berthing, stowage, and intermodal transfer of standardized shipping containers through port facilities equipped with gantry cranes reaching 23+ container rows across and terminal operating systems processing 30+ moves per crane hour. These operations function as the critical interface between deep-sea vessel networks and European hinterland rail, barge, and truck distribution. Automated terminals command premium handling rates due to labor cost arbitrage and 24-hour consistency, while semi-automated terminals represent the fastest-growing category as legacy ports retrofit without full greenfield capital commitment. IoT solutions and AI-based systems concentrate where real-time berth optimization yields measurable vessel turnaround compression.
EU Green Deal emissions targets and the F-Gas Regulation constrain refrigerant choices for reefer container maintenance yards, while ECHA's REACH framework governs anti-corrosion coatings on handling equipment. Terminal operators must integrate these standards into capital planning or face restricted port access. Stakeholders should monitor how EU AI Act risk classifications affect automated crane decision systems before committing to next-generation terminal upgrades.
Market Dynamics
The EU Green Deal's emissions trading framework is forcing terminal operators to restructure capital allocation toward shore power infrastructure and electrified handling equipment, compressing returns on legacy diesel-dependent assets.
Growth Catalysts
- Mediterranean cold chain expansion:Pharmaceutical and perishable food distributors are routing temperature-controlled cargo through Barcelona, Valencia, and Marseille-Fos, expanding reefer container throughput at these hubs.
- EU AI Act compliance preparation:Terminal operators investing in automated crane decision systems ahead of risk classification deadlines are securing first-mover advantage in berth optimization software.
- Hamburg-Le Havre corridor concentration:Mega-vessel deployment patterns are consolidating transshipment volumes along this axis, rewarding terminals with 23+ row gantry crane capacity.
Market Restraints
- Shore power infrastructure capex:The EU Green Deal's emissions trading requirements mandate vessel-to-grid connections that cost €8-15 million per berth retrofit, straining mid-size port balance sheets.
- F-Gas refrigerant constraints:ECHA's REACH framework and the F-Gas Regulation are phasing out conventional refrigerants for reefer maintenance yards, forcing equipment replacement before depreciation cycles complete.
- Labor cost arbitrage erosion:Automated terminals in Rotterdam and Hamburg are narrowing the efficiency gap with semi-automated competitors, reducing the premium capture window for full automation investments.
Strategic Opportunities
- Baltic Sea feeder integration:Polish and Lithuanian ports remain underpenetrated by automated terminal systems, creating entry points for operators with proven TOS platforms.
- Rail-barge intermodal convergence:Germany's inland waterway-rail junctions offer white space for terminals integrating real-time berth scheduling with hinterland modal shift incentives.
- CSRD reporting alignment:The EU's Corporate Sustainability Reporting Directive creates demand for carbon-accounting terminal services that operators can productize as premium offerings to liner customers.
Industry Challenges
- Crane automation technician scarcity:Terminal operating systems processing 30+ moves per crane hour require specialized maintenance skills that outpace European vocational training output.
- Legacy TOS integration friction:Semi-automated terminals retrofitting without full greenfield commitment face software architecture constraints that limit real-time optimization gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Container Terminal Operations Market |
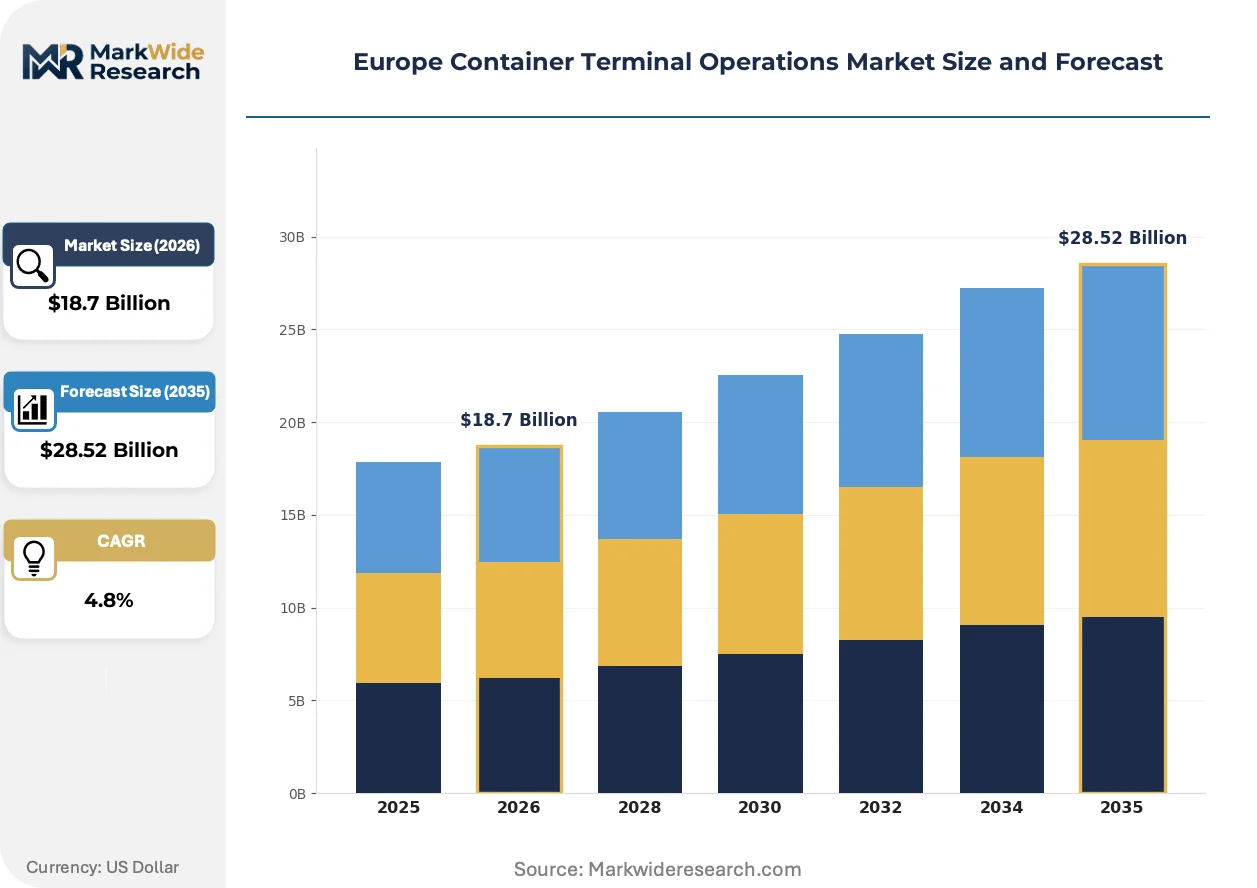
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Terminals, Semi-Automated Terminals, Conventional Terminals, Greenfield Terminals Technology: IoT Solutions, AI-based Systems, Robotics, Cloud Computing End User: Shipping Companies, Freight Forwarders, Logistics Providers, Terminal Operators Service Type: Loading, Unloading, Storage, Maintenance |
| Companies Covered | Hutchison Port Holdings, CMA CGM Terminals, APM Terminals, Yilport Holding, HHLA International, Hamburger Hafen und Logistik, Terminal Investment Limited, Cosco Shipping Ports, PSA International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Container Terminal Operations Market Emerging Trajectories
Artificial intelligence and electrification are restructuring how European terminals balance labor productivity against regulatory compliance, with automation investments increasingly justified by emissions targets rather than throughput alone.
AI-based berth optimization systems are supplanting manual stowage planning and fixed scheduling windows. Mediterranean and North Sea terminals with 24-hour vessel call density are deploying these platforms fastest. The technology is compressing vessel turnaround times by 12-18% where crane-to-TOS integration reaches full deployment.
The EU AI Act's risk classification framework for automated decision systems is mandating human-in-the-loop protocols for crane operations. Terminal operators must redesign control room architectures and retrain supervisory staff. German and Dutch ports with the deepest automation investments are establishing compliance templates now to avoid operational interruptions.
Service unbundling is fragmenting traditional terminal contracts. Liner customers are separating stevedoring from intermodal coordination, selecting specialized providers for each function. This pattern concentrates in the Hamburg-Le Havre corridor where mega-vessel operators possess procurement leverage to disaggregate service tiers.
Europe Container Terminal Operations Market Segmentation
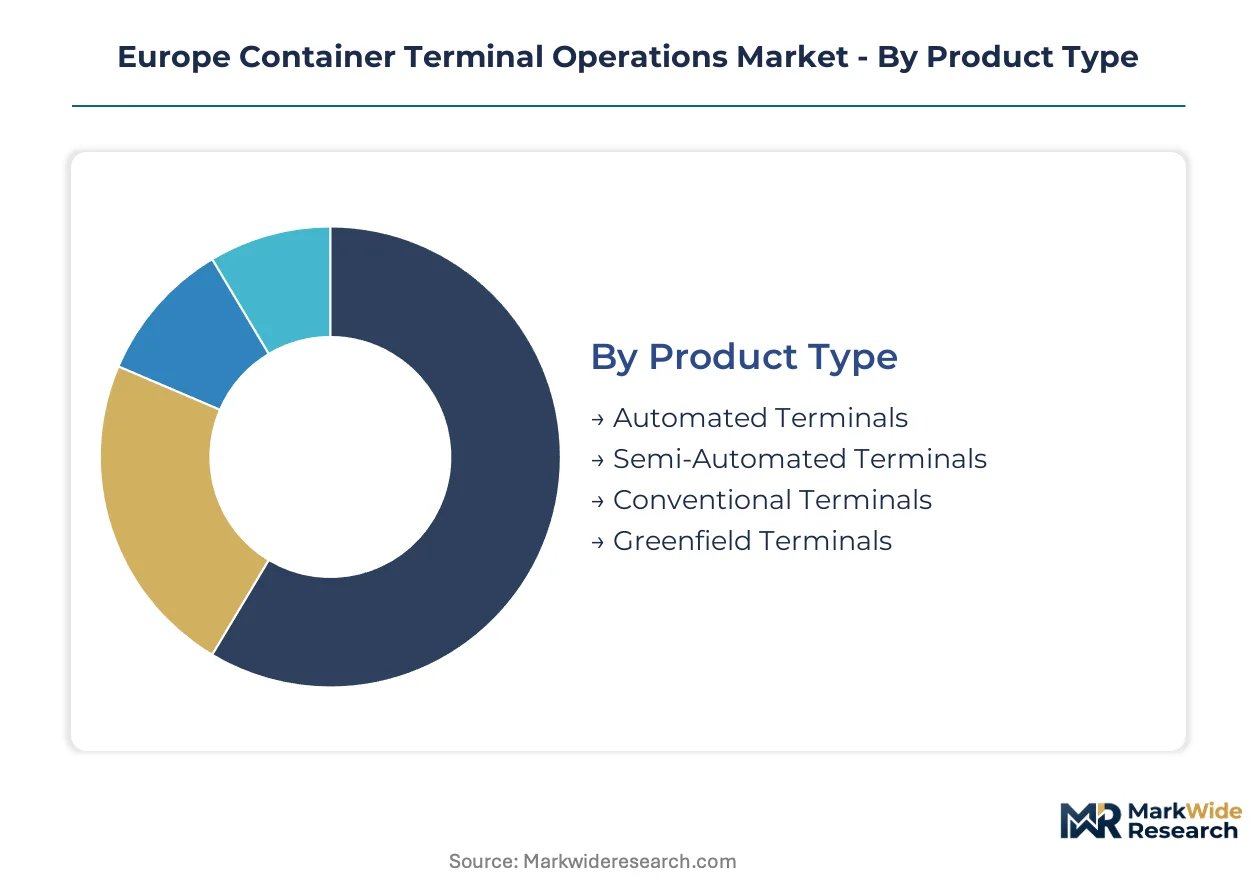
Terminal configuration choices in Europe increasingly hinge on emissions compliance timelines and labor cost trajectories rather than throughput alone. Segmentation reveals where capital flows concentrate as operators balance EU Green Deal mandates against automation payback periods.
Product Type:
EU Green Deal shore power mandates and ETS carbon pricing are fragmenting investment patterns across terminal categories.
- Automated Terminals:Gantry crane systems reaching 23+ container rows with terminal operating systems processing 30+ moves per hour. Rotterdam's Maasvlakte and Hamburg's Altenwerder deploy these configurations to capture premium handling rates through 24-hour labor cost arbitrage and consistent turnaround compression.
- Semi-Automated Terminals:Retrofitted legacy infrastructure blending manual and automated stacking with partial TOS integration. Barcelona, Valencia, and Marseille-Fos are expanding this category fastest as Mediterranean hubs seek automation gains without full greenfield capital commitment.
- Conventional Terminals:Diesel-dependent equipment with manual stowage planning and fixed scheduling windows.
- Greenfield Terminals:Purpose-built facilities incorporating electrified handling equipment and vessel-to-grid infrastructure from commissioning.
Semi-automated terminals handle the majority of throughput; greenfield terminals are climbing the fastest on share as EU emissions deadlines harden.
Technology:
Cost tier differentiation separates proven platforms from emerging systems still seeking scale validation.
- IoT Solutions:Sensor networks monitoring reefer container temperature, crane fatigue, and berth occupancy in real time. These systems concentrate at Mediterranean cold chain hubs where pharmaceutical and perishable cargo volumes justify sensor density.
- AI-based Systems:Machine learning platforms optimizing vessel stowage sequences and crane dispatch algorithms. North Sea terminals with dense 24-hour call patterns deploy these tools to compress turnaround times.
- Robotics:Automated guided vehicles and autonomous straddle carriers for horizontal container transport.
- Cloud Computing:Distributed data architectures enabling multi-terminal coordination and predictive maintenance scheduling.
IoT solutions command the widest installed base; AI-based systems are expanding most quickly as EU AI Act compliance templates mature.
End User:
Customer type determines service bundling preferences and procurement leverage across the Hamburg-Le Havre corridor.
- Shipping Companies:Mega-vessel operators with dedicated terminal contracts and fleet scheduling integration. CMA CGM and similar carriers are disaggregating stevedoring from intermodal coordination, forcing terminals to unbundle traditional service packages.
- Freight Forwarders:Intermediaries consolidating less-than-container-load cargo and negotiating space allocations across multiple liner services.
- Logistics Providers:Cold chain specialists and pharmaceutical distributors routing temperature-controlled cargo through Barcelona and Valencia.
- Terminal Operators:Third-party facility managers contracting port authorities for concession rights and infrastructure access.
Shipping companies drive the largest contract values; logistics providers are gaining share fastest as reefer throughput expands.
Service Type:
Margin structure varies sharply between vessel-facing and landside activities.
- Loading:Crane-based container placement onto vessels with stowage planning coordination. Automated terminals capture premium rates here through consistent move counts and reduced vessel stay times.
- Unloading:Discharge operations sequenced by customs clearance status and hinterland modal connection schedules.
- Storage:Yard occupancy management including reefer container plugging and monitoring. ECHA REACH framework and F-Gas Regulation constraints on refrigerant choices are elevating maintenance costs for this segment.
- Maintenance:Crane servicing, TOS updates, and equipment lifecycle management.
Loading generates the highest revenue per move; storage is expanding fastest as dwell times lengthen and cold chain infrastructure demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal emissions trading requirements are redirecting capital toward shore power infrastructure and electrified handling equipment. Hamburg-Le Havre corridor terminals absorb the largest transshipment volumes as mega-vessel deployment patterns consolidate. Mediterranean hubs capture cold chain cargo growth from pharmaceutical and perishable food distributors.
Germany
Hamburg's Altenwerder terminal processes dense mega-vessel calls through automated gantry systems reaching 23+ container rows. The EU AI Act mandates human-in-the-loop protocols for crane decision systems here. HHLA International anchors Baltic-North Sea transshipment dominance from this northern hub.
Netherlands
Rotterdam's Maasvlakte automated stack operations command premium handling rates through 24-hour labor cost arbitrage. Shore power retrofit investments of €8-15 million per berth strain balance sheets under EU emissions trading deadlines. The Randstad cluster concentrates Europe's deepest automation deployments.
Spain
Barcelona and Valencia terminals expand semi-automated configurations to capture Mediterranean cold chain throughput. ECHA's REACH framework and F-Gas Regulation constrain refrigerant choices for reefer maintenance yards. These hubs route temperature-controlled pharmaceutical cargo between European and North African markets.
France
Marseille-Fos leverages vertical integration with parent fleet scheduling to differentiate container handling services. The EU Green Deal accelerates vessel-to-grid infrastructure commitments across Provence-Alpes-Côte d'Azur. CMA CGM Terminals coordinates berth optimization with liner network timing from this southern gateway.
Poland
Gdańsk and Gdynia remain underpenetrated by automated terminal operating systems despite rising Baltic feeder volumes. Polish ports absorb transshipment spillover as Hamburg-Le Havre corridor capacity tightens. These facilities present entry points for operators with proven TOS platforms seeking expansion.
Europe Container Terminal Operations Market Vendor Landscape
Listed leaders compete with private specialists across terminal concession rights and automation technology deployment. The vendor base clusters around three tiers: global port operators with multi-continental networks, regional specialists dominating single-country corridors, and carrier-affiliated terminals leveraging fleet integration. Strategic moves concentrate on semi-automated retrofits of legacy infrastructure and shore power partnerships with port authorities.
Within the carrier-integrated tier, CMA CGM Terminals and APM Terminals exemplify fleet-scheduling coordination advantages. HHLA International anchors the regional specialist category through its Hamburg hub dominance. Hutchison Port Holdings occupies a position among diversified global operators with Mediterranean and North Sea exposure.
| Leading Market Players |
|---|
| Hutchison Port Holdings |
| CMA CGM Terminals |
| APM Terminals |
| Yilport Holding |
| HHLA International |
| Hamburger Hafen und Logistik |
| Terminal Investment Limited |
| Cosco Shipping Ports |
| PSA International |
| Others |
Supply Flow & Price Mechanics
Electrified gantry crane retrofits displacing diesel-dependent equipment are redrawing procurement geography across European terminals while compressing handling rate premiums previously captured through labor cost arbitrage alone.
Pricing Analysis
Certification level creates the primary spread between automated and semi-automated terminal handling rates, with ISO 14001 environmental management and EU AI Act compliance templates commanding 15-25% premiums over conventional configurations. Three-tier pricing structure across premium automation, standard semi-automated, and economy conventional terminals reflects differential shore power readiness and crane-to-TOS integration depth. Cost compression in the semi-automated tier is intensifying because Mediterranean hubs are retrofitting legacy infrastructure without full greenfield capital commitment. Freight forwarders consolidating less-than-container-load cargo exhibit highest price sensitivity, while mega-vessel operators with dedicated terminal contracts prioritize turnaround consistency over per-move economics.
Supply Chain Analysis
Strategic stockpiling of vessel-to-grid infrastructure components precedes EU Green Deal emissions trading deadlines, while just-in-time crane automation technician deployment characterizes maintenance operations at 24-hour terminals. Equipment manufacturing concentrates in Germany, South Korea, and China, with gantry crane superstructures and terminal operating system software drawing from distinct supplier ecosystems. Supply chain risk centers on single-source vulnerability for AI-based berth optimization modules trained on proprietary vessel call pattern datasets. Distribution runs through port authority concession frameworks that bundle infrastructure access with electrification compliance timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal operating system interoperability is emerging as the platform-economics inflection point, with API standardization across Hamburg-Le Havre corridor operators enabling multi-terminal coordination that reshapes competitive moats.
For Market Incumbents: Shield Baltic-North Sea transshipment dominance by accelerating shore power partnerships with German and Dutch port authorities before EU emissions trading deadlines harden. Consolidate crane automation technician training pipelines through vocational alliances with Hamburg and Rotterdam technical institutes to preempt capability scarcity. Vertical integration into reefer container maintenance yards offsets F-Gas Regulation refrigerant cost pressures through captive service revenue. For New Entrants and Emerging Players: EU AI Act compliance fast-track investments in human-in-the-loop crane control architectures open procurement channels at German and Dutch terminals retrofitting automated decision systems. Polish and Lithuanian Baltic feeder ports present the most penetrable geography, with underdeployed TOS platforms and rising transshipment spillover from Hamburg-Le Havre corridor capacity constraints. Go-to-market positioning as carbon-accounting terminal service providers aligns with CSRD reporting mandates driving liner customer procurement criteria. For Investors and Strategic Acquirers: EU AI Act risk classification deadlines reshape the acquisition landscape toward terminal operators with established compliance templates and retrained supervisory staff architectures. Long-term viability favors semi-automated retrofit specialists over greenfield developers given capital intensity constraints and compressed automation premium windows. Signal to monitor: berth optimization software vendor consolidation rates as crane-to-TOS integration becomes the bottleneck for turnaround compression gains.| Strategic Initiative | Industry Significance |
|---|---|
| Shore Power Infrastructure Partnership | EU Green Deal ETS compliance secures port authority concession renewals at Rotterdam and Hamburg. |
| AI Act Compliance Template Development | Human-in-the-loop crane protocols establish first-mover advantage in berth optimization software procurement. |
| Semi-Automated Terminal Retrofit | Barcelona and Valencia expansions capture Mediterranean cold chain throughput without full greenfield capital. |
| Baltic Feeder Port TOS Deployment | Gdańsk and Gdynia automation penetrates underdeveloped Polish and Lithuanian transshipment corridors. |
| Carbon-Accounting Service Productization | CSRD-aligned terminal offerings command premium positioning with liner customers facing disclosure mandates. |
Methodological Framework
Desk research of EU regulatory filings, port authority concession agreements, and terminal operator sustainability disclosures preceded structured interviews with terminal operating system vendors, crane automation engineers, port authority planning officers, and liner fleet scheduling managers. Primary fieldwork across Hamburg, Rotterdam, Barcelona, and Marseille-Fos validated throughput assumptions and electrification capex timelines. Secondary sources included ECHA REACH substance databases, EU AI Act implementation guidance, and customs trade data for container flow patterns. Bottom-up terminal capacity modeling triangulated against top-down EU trade corridor demand projections.
Variance decomposition across terminal configuration segments, technology deployment tiers, and end-user contract structures anchored the analytical framework over the projection horizon. Segmentation dimensions encompassed automation level, crane row capacity, TOS integration depth, reefer throughput share, and hinterland modal connectivity. CAGRs derived from vessel deployment pattern analysis and EU emissions compliance timeline phasing. Industry-specific inputs included mega-vessel call density forecasts and shore power retrofit completion schedules.
Underlying assumptions cover EU Green Deal implementation continuity and AI Act risk classification adherence, with deviation risk concentrated in labor cost arbitration erosion and crane automation technician supply constraints. Forecasts reflect these conditions without scenario weighting. Revision becomes warranted when semi-automated terminal retrofit adoption crosses threshold penetration rates that compress automation premium capture windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Ocean Freight Software Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
North America Logistics Market