
 Automotive Half Shaft Market | 2026-2036
Automotive Half Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Half Shaft Market Analysis
Software-defined torque vectoring services is repositioning half shafts from passive mechanical links to active chassis control elements. GKN Automotive leverages its eDrive integration expertise to bundle half shafts with electric axle systems. Hyundai WIA Corporation anchors its position through captive supply relationships with Hyundai Motor Group. ZF Friedrichshafen competes on mechatronic half shaft modules that interface with adaptive suspension controllers.
An automotive half shaft is a rotating drivetrain component that transmits torque from the differential to the wheel hub while accommodating suspension travel and steering angles, typically manufactured from induction-hardened alloy steel or hollow aluminum extrusions with precision-machined splined ends. Its primary function is to deliver power to the driven wheels while maintaining constant rotational velocity through the articulation range of the suspension. Constant velocity half shafts dominate OEM fitments due to their universal joint geometry that eliminates speed variation at extreme steering angles, while aluminum material adoption is accelerating as manufacturers chase mass reduction targets without sacrificing torsional fatigue limits. The aftermarket channel occupies a distinct margin pool driven by collision repair and high-mileage fleet turnover, though OEM volumes sustain the bulk of contract manufacturing capacity.
NHTSA crashworthiness standards, EPA corporate average fuel economy regulations, and ISO 26262 functional safety requirements collectively dictate half shaft design validation protocols and material certification pathways in the United States market. ECE R94 homologation in Europe and China's GB/T automotive structural standards add parallel compliance layers for suppliers serving multiple manufacturing geographies. Stakeholders must monitor how battery electric vehicle platform consolidation reshapes torque loading specifications and whether in-wheel motor architectures eventually bypass conventional half shaft configurations entirely.
Market Dynamics
Electric vehicle platform consolidation is compressing half shaft specifications while simultaneously demanding higher torque density from lighter assemblies, forcing suppliers to revalidate hollow aluminum extrusions against legacy solid steel fatigue benchmarks.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:United States OEMs must shed driveline mass to meet fleet-wide efficiency targets, accelerating hollow steel and aluminum half shaft procurement.
- China's NEV penetration surge:Domestic battery electric vehicle production volumes are creating dedicated supply contracts for high-torque half shaft architectures.
- Induction hardening process advances:New heat treatment protocols extend torsional fatigue life of lightweight alloys without wall thickness penalties.
Market Restraints
- Aluminum ingot price volatility:LME aluminum fluctuations compress margin on hollow extrusion programs already burdened by tooling amortization.
- German supplier concentration:Premium CV joint technology remains captive to a narrow tier of Stuttgart-region component houses.
- In-wheel motor substitution threat:Hub-mounted electric motors eliminate half shafts entirely, though volume deployment remains limited to urban delivery prototypes.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives attract half shaft manufacturing for export-oriented compact vehicle platforms.
- Software-defined torque vectoring:Mechatronic half shaft modules that interface with chassis controllers command premium positioning.
- Collision repair channel digitization:B2B platforms are disintermediating traditional wholesale distributors in North American aftermarket sourcing.
Industry Challenges
- ISO 26262 functional safety certification:Active half shaft modules require ASIL-rated validation timelines that extend program gates by 8-14 months.
- Legacy press-fit joint integration:New lightweight materials exhibit incompatible thermal expansion coefficients with established wheel hub assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Half Shaft Market |
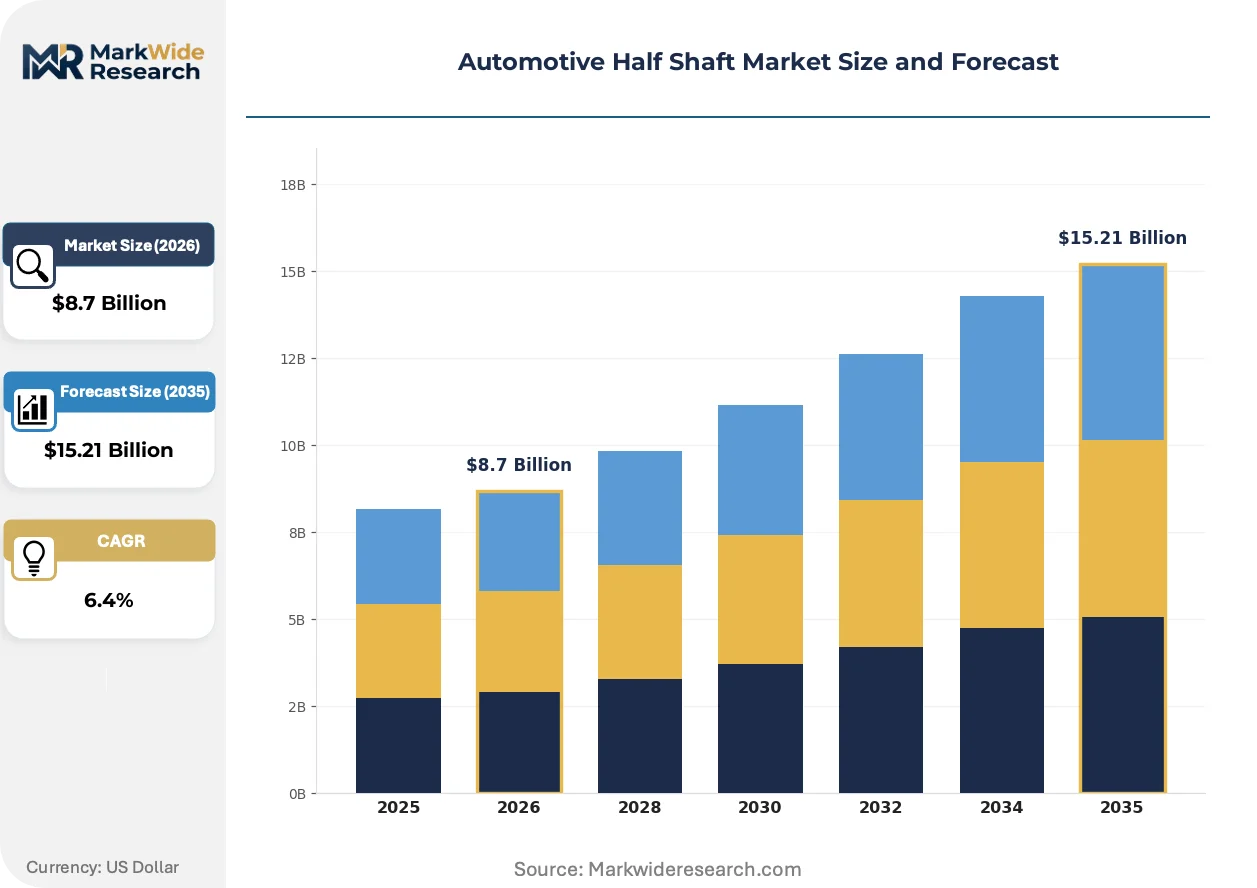
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Velocity, Semi-Independent, Rigid, Flexible End User: Passenger Vehicles, Commercial Vehicles, Light Trucks, Heavy Machinery Material: Steel, Aluminum, Composite, Magnesium Sales Channel: OEM, Aftermarket, Online Retail, Distributors |
| Companies Covered | JTEKT Corporation, Hyundai WIA Corporation, GKN Automotive, Magna International, Nexteer Automotive, Dana Incorporated, NTN Corporation, ZF Friedrichshafen, American Axle & Manufacturing Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Half Shaft Market Emerging Trajectories
Hollow aluminum extrusion is displacing solid steel forgings as the dominant material platform, while regulatory pressure on fleet emissions compresses design validation cycles and procurement patterns consolidate around integrated axle system suppliers.
Carbon fiber-reinforced polymer hybrid shafts are absorbing torsional loads in motorsport-derived road car programs. Porsche and McLaren procurement specifications now mandate braided CFRP overwraps on aluminum cores for unsprung mass reduction. This construction is absorbing development budgets from conventional alloy research and forcing tier suppliers to license composite winding IP.
NHTSA crashworthiness standards are tightening intrusion resistance requirements for front-wheel-drive architectures. The updated FMVSS 208 testing protocols demand half shaft retention under 35 mph offset barrier impacts. United States OEMs are responding with thicker-walled intermediate shaft designs that trade mass efficiency for litigation risk mitigation.
Fleet operators are unbundling half shaft replacement from comprehensive maintenance contracts. Large rental and logistics buyers now source driveline components through direct vendor agreements rather than dealer service networks. This pattern is most pronounced in Texas and Florida markets where high-mileage fleet density supports dedicated aftermarket distribution centers.
Automotive Half Shaft Market Segmentation
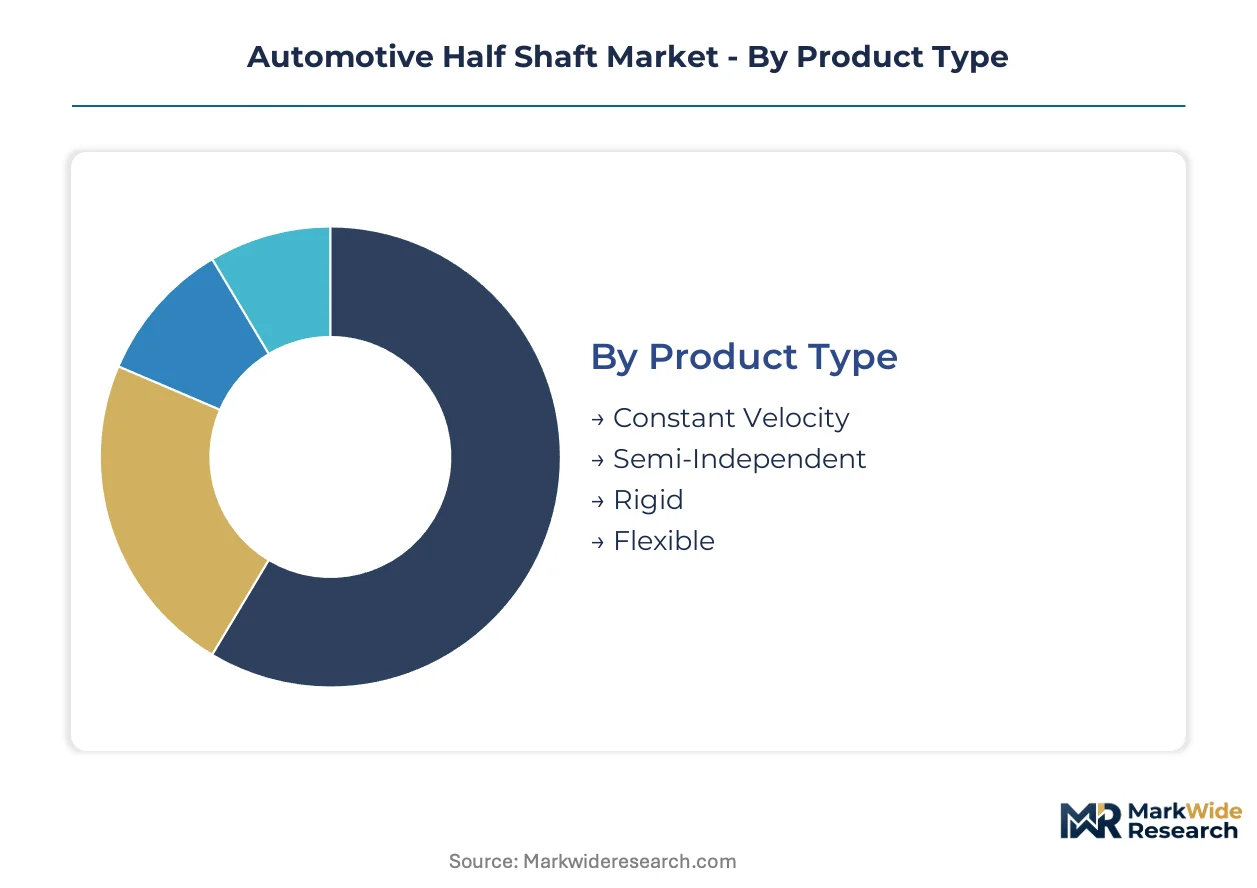
Half shaft procurement patterns diverge sharply across vehicle architectures and supply channels. Material selection and joint geometry specifications respond to distinct torque loading, durability, and regulatory compliance requirements in each segment cluster.
Product Type:
Joint geometry dictates fatigue life, articulation range, and NVH performance in buyer specifications.
- Constant Velocity:Rzeppa or double-offset joint configurations maintain zero angular velocity variation through 52-degree steering angles. Battery electric vehicle platforms in China and Germany specify high-torque variants with reinforced cage retainers to manage instantaneous motor torque delivery.
- Semi-Independent:Tripod joint assemblies accommodate plunge motion in front-wheel-drive transverse powertrains. Japanese and Korean compact vehicle programs favor this geometry for packaging efficiency in tight engine bays.
- Rigid:Solid tubular shafts without articulation joints serve solid rear axle applications in heavy-duty pickup trucks.
- Flexible:Elastomer-damped couplings isolate driveline shock in off-highway machinery and agricultural equipment.
Constant Velocity leads on scale; Semi-Independent leads on momentum.
End User:
Vehicle mass and duty cycle determine torque density requirements and replacement frequency.
- Passenger Vehicles:Unibody architectures with independent suspension dominate procurement volumes. Hollow aluminum shafts are gaining share fastest in European C-segment and D-segment electric vehicle programs where unsprung mass reduction directly extends range certification.
- Commercial Vehicles:Ladder-frame trucks and vans subject half shafts to sustained high-torque operation. North American fleet operators are consolidating specifications around induction-hardened steel assemblies with predictive maintenance sensor integration.
- Light Trucks:Body-on-frame SUVs and compact pickups split demand between steel durability and aluminum efficiency targets.
- Heavy Machinery:Mining and construction equipment demands forged alloy shafts with spline diameters exceeding 80mm.
Passenger Vehicles concentrate revenue; Commercial Vehicles concentrate margin.
Material:
Density and torsional stiffness tradeoffs shape supplier tooling investments and OEM platform decisions.
- Steel:Induction-hardened 4140 and 4340 alloy grades retain dominance in high-torque commercial applications. German and US suppliers are advancing hollow extrusion techniques to preserve fatigue performance at reduced mass.
- Aluminum:6061-T6 and 7075-T6 hollow extrusions achieve 40-45% mass reduction versus solid steel. EPA fuel economy enforcement is accelerating US OEM adoption for front-wheel-drive electric vehicle architectures.
- Composite:Carbon fiber overwrap hybrid constructions serve motorsport-derived road cars.
- Magnesium:AZ91D castings remain experimental for non-structural shaft components.
Steel retains volume leadership; Aluminum climbs the fastest.
Sales Channel:
Contract structure and margin capture differ fundamentally between captive supply and independent distribution.
- OEM:Long-term supply agreements with integrated axle system suppliers lock in 5-7 year program commitments. Tier 1 suppliers bundle half shafts with electric drive units to secure platform exclusivity.
- Aftermarket:Collision repair and high-mileage fleet replacement drive demand through jobber distributors and service chains. Texas and Florida fleet density supports dedicated regional distribution centers.
- Online Retail:B2B platforms are disintermediating traditional wholesale channels for standard replacement shafts.
- Distributors:Independent warehouse distributors maintain inventory for same-day fulfillment to repair facilities.
OEM anchors revenue stability; Aftermarket anchors margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's battery electric vehicle production scales faster than Germany's precision component exports, creating divergent procurement patterns across manufacturing geographies. The United States enforces fuel economy mandates that accelerate lightweight material adoption. India leverages production incentives to capture export-oriented manufacturing.
China
Domestic NEV penetration drives demand for high-torque half shaft architectures with reinforced cage retainers. MIIT's dual carbon goals pressure OEMs toward aluminum-intensive designs. The Yangtze River Delta concentrates integrated axle system suppliers serving BYD and NIO platforms.
Germany
Premium CV joint technology remains captive to Stuttgart-region component houses supplying BMW and Mercedes-Benz electric architectures. ECE R94 homologation dictates crashworthiness validation protocols. Baden-Württemberg's supplier corridor advances hollow steel extrusion techniques for mass-critical applications.
United States
EPA corporate average fuel economy enforcement accelerates hollow steel and aluminum half shaft procurement for front-wheel-drive electric vehicles. NHTSA's updated FMVSS 208 protocols demand thicker-walled intermediate shaft designs. Michigan and Ohio anchor Tier 1 supplier engineering centers for integrated driveline systems.
India
The PLI scheme for auto components attracts half shaft manufacturing for export-oriented compact vehicle platforms serving Southeast Asian markets. BIS structural standards govern material certification pathways. Tamil Nadu and Gujarat concentrate forging capacity for induction-hardened alloy shafts.
Japan
Tripod joint assemblies dominate compact vehicle programs from Toyota and Honda, prioritizing packaging efficiency in transverse powertrains. METI's industrial standards coordinate supplier quality benchmarks. The Nagoya industrial corridor maintains captive supply relationships for precision-machined splined ends.
Automotive Half Shaft Market Vendor Landscape
Top-tier vendors anchor integrated axle system supply, while mid-tier fabricators compete on standalone half shaft contracts. The vendor structure stratifies around electric driveline integration capability, with premium positioning commanding multi-year platform exclusivity. Three archetypes dominate: full-system integrators bundling half shafts with eDrive units, standalone shaft specialists serving aftermarket channels, and captive suppliers aligned with single OEM groups. Competitive moves concentrate on strategic partnerships for composite winding IP and capacity expansion for hollow aluminum extrusion programs.
Within the full-system integrator tier, GKN Automotive and ZF Friedrichshafen exemplify positioning through electric axle bundling strategies. Hyundai WIA Corporation anchors the captive supplier archetype through its alignment with Hyundai Motor Group. Among standalone specialists, JTEKT Corporation and NTN Corporation occupy positions defined by precision joint geometry expertise. Dana Incorporated and American Axle & Manufacturing Holdings, Inc. represent North American-scale fabrication capacity serving fleet and commercial vehicle procurement. Nexteer Automotive and Magna International sit within the chassis integration tier, leveraging mechatronic module development for software-defined torque vectoring applications.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Hyundai WIA Corporation |
| GKN Automotive |
| Magna International |
| Nexteer Automotive |
| Dana Incorporated |
| NTN Corporation |
| ZF Friedrichshafen |
| American Axle & Manufacturing Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
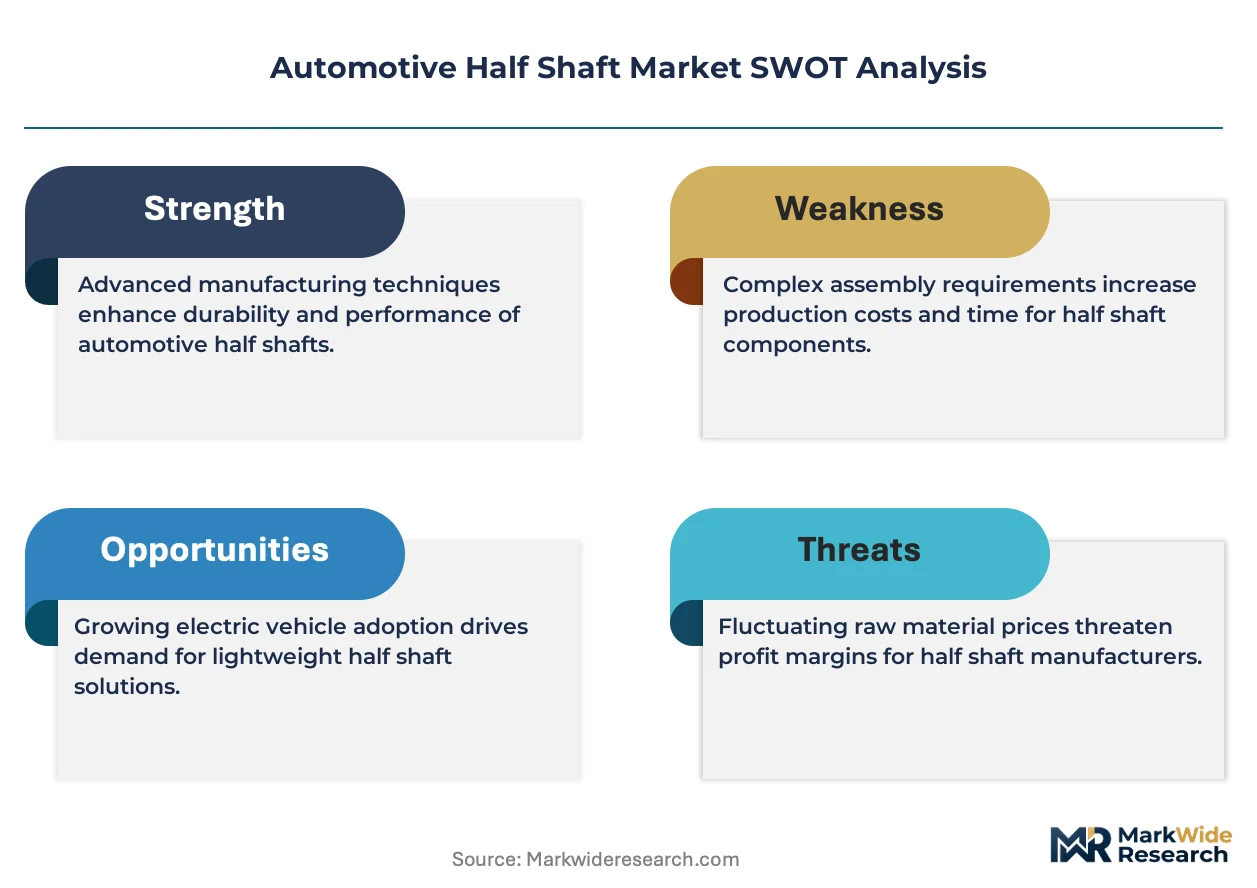
Precision forging specialists in Baden-Württemberg anchor labor-cost differentials that widen pricing-tier spreads between Stuttgart-region premium CV joint suppliers and Tamil Nadu export-oriented fabricators serving compact vehicle programs.
Pricing Analysis
Capacity additions in Tamil Nadu and Gujarat are reshaping price floors for induction-hardened alloy shafts, compressing margins on standard-grade assemblies while premium mechatronic modules with ISO 26262 certification command sustained premiums. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by torque density ratings and after-sales service bundling. Cost compression in hollow aluminum extrusion programs is intensifying because LME aluminum volatility outpaces tooling amortization schedules. Fleet operators in Texas and Florida exhibit highest price sensitivity through unbundled direct vendor agreements, while German premium OEMs remain least sensitive due to platform exclusivity contracting.
Supply Chain Analysis
Aluminum ingot supply rests on Chinese smelter output and Australian bauxite extraction, with induction-hardened steel bar stock drawing from German and Japanese specialty mill capacity. Hollow extrusion tooling and precision-machined splined ends represent critical component dependencies. Single-source vulnerability concentrates in Stuttgart-region CV joint cage retainers for high-torque electric vehicle architectures. Distribution runs through captive Tier 1 supply agreements with integrated axle system suppliers, supplemented by regional aftermarket distribution centers in high-mileage fleet corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's PLI scheme for auto components creates geographic-arbitrage potential against German labor-cost structures, with Tamil Nadu forging capacity offering 40-60% cost differentials on standard-grade shafts.
For Market Incumbents: Deploy hollow aluminum extrusion capacity additions in India to defend margin position against Chinese NEV platform consolidation. Secure ASIL-rated functional safety certification ahead of software-defined torque vectoring integration timelines. In-wheel motor substitution threats in urban delivery segments demand active monitoring of hub-mounted electric motor prototypes. For New Entrants and Emerging Players: Composite winding IP for carbon fiber-reinforced polymer hybrid shafts offers technology-first positioning in motorsport-derived road car procurement. White-space targets include collision repair channel digitization in North American aftermarket and high-torque half shaft architectures for China's domestic NEV producers. Go-to-market execution should anchor on B2B platform partnerships disintermediating traditional wholesale distributors. For Investors and Strategic Acquirers: Integrated electric axle system suppliers are the most active acquirer in this space, seeking captive half shaft manufacturing to secure platform exclusivity. Long-term viability hinges on aluminum-intensive design capability and mechatronic module development for software-defined vehicle architectures. Watch battery electric vehicle platform consolidation rates as inflection indicator for torque loading specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hollow Aluminum Extrusion Scale-Up | EPA fuel economy enforcement accelerates lightweight material procurement from US OEMs. |
| Software-Defined Torque Vectoring Investment | Mechatronic half shaft modules interface with adaptive suspension controllers from ZF Friedrichshafen. |
| India PLI Scheme Manufacturing Footprint | Production-linked incentives attract export-oriented capacity for Southeast Asian compact vehicle platforms. |
| Composite Winding IP Partnership | Carbon fiber overwrap licensing from motorsport suppliers enables unsprung mass reduction programs. |
| Aftermarket Channel Digitization | B2B platforms disintermediate traditional wholesale distributors in Texas and Florida fleet corridors. |
Methodological Framework
Multiple input streams — OEM platform engineering specifications, Tier 1 supplier production schedules, and aftermarket distributor inventory records — were reconciled through structured primary interviews with procurement directors, driveline system architects, and fleet maintenance operators. Secondary validation drew from NHTSA FMVSS filings, EPA corporate average fuel economy compliance data, vehicle production databases, and aluminum ingot trade statistics. Bottom-up shaft unit economics and top-down automotive driveline market sizing were triangulated to anchor volume estimates.
Historical shipment patterns were cross-referenced against panel input from platform engineering teams to inform trajectory assumptions across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, material grade tier, and regional production cluster dimensions. CAGRs were derived from fitted growth curves applied to normalized baseline data, with electric vehicle penetration rates and hollow aluminum adoption curves serving as primary forecast inputs.
The model holds under stable EPA enforcement intensity and aluminum price corridors; deviation in NHTSA crashworthiness protocol updates or in-wheel motor commercialization timelines would shift torque loading specifications and material substitution patterns. A small set of named triggers — MIIT dual carbon goal acceleration, German supplier consolidation, and Texas fleet electrification rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Clutch Actuator Market
Powertrain
Automotive Power Modules Market
Powertrain
Fuel Injection Systems Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Global Automotive Damper Pulley Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Automotive Carburetor Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Japan Electro Hydraulic Power Steering Market