
 Automotive Transmission Fluid Market | 2026-2036
Automotive Transmission Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Transmission Fluid Market Insights
China is rewriting capacity dynamics in automotive transmission fluid manufacturing as domestic blenders expand high-volume facilities to serve Asia-Pacific OEM demand. ExxonMobil Corporation leverages its integrated base oil and additive supply chain to maintain cost leadership across automatic and CVT fluid grades. Shell plc anchors its position through technology leadership in low-viscosity formulations designed for electrified powertrains. Fuchs Petrolub SE specializes in precision-engineered dual-clutch transmission fluids for German and Chinese automakers.
Automotive transmission fluid comprises base oils blended with friction modifiers, anti-wear agents, and viscosity index improvers engineered to transfer torque, cool clutch packs, and synchronize gear engagement across mechanical and automated transmissions. The fluid grade dimension stratifies sharply: premium formulations command margin pools from OEM fill contracts, while mid-grade products dominate aftermarket volume through independent garages and fleet operators. Automatic transmission fluid occupies the largest share of demand, though CVT-specific formulations represent the fastest-growing product type as continuously variable transmissions penetrate compact and mid-size vehicle segments.
The US EPA and NHTSA impose fuel-economy standards that directly shape viscosity grade requirements and additive package approvals for transmission fluids sold in North America. China's SAMR enforces GB standards that govern friction durability and oxidation stability, while India's BIS certification mandates product testing for imported and domestically blended lubricants. Stakeholders must monitor how electrification shifts fluid demand from mechanical transmissions toward e-axle and thermal management fluids without assuming direct substitution timelines.
Market Dynamics
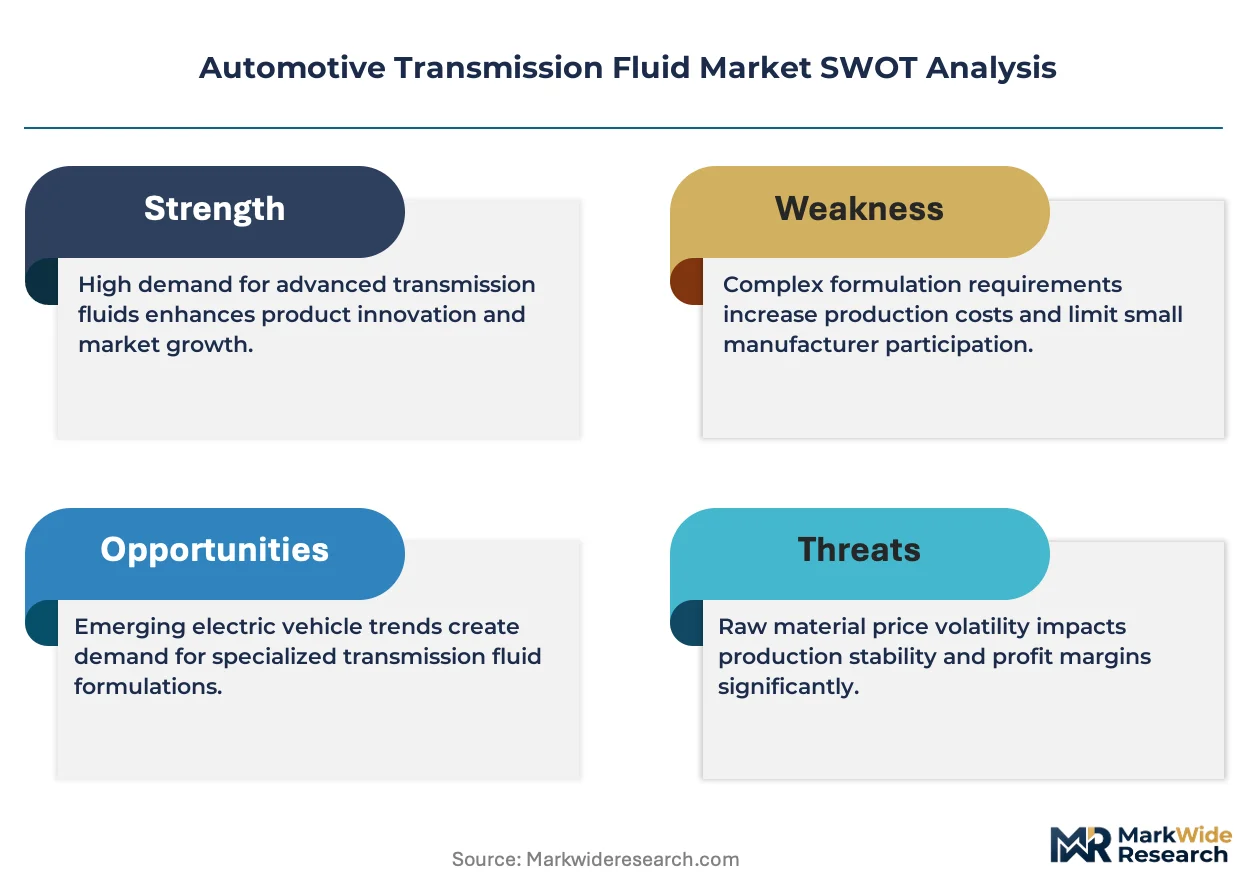
Electrification of powertrains is fragmenting demand away from mechanical transmission fluids toward thermal management and e-axle lubricants, forcing blenders to reconfigure product portfolios before volume erosion accelerates.
Growth Catalysts
- China's GB standards alignment:NMPA-mandated friction durability specifications are compelling domestic and multinational blenders to upgrade additive packages, creating replacement demand for certified formulations.
- CVT penetration in compact vehicles:Continuously variable transmission installations in mass-market segments are expanding the addressable market for specialized high-shear-stability fluids.
- India's automotive manufacturing corridors:Production clustering around Chennai and Pune is generating concentrated OEM fill demand for transmission fluids serving export and domestic vehicle programs.
Market Restraints
- Group III+ base oil cost volatility:Hydrocracked feedstock prices track crude differentials and refinery utilization, compressing blender margins during upstream tightness.
- Additive package supplier concentration:Specialty chemical production for friction modifiers and anti-wear agents concentrates among a limited set of European and North American suppliers, creating single-source vulnerability.
- Extended drain intervals:OEM-specified service life for automatic transmission fluids now exceeds 100,000 kilometers in many vehicle classes, reducing aftermarket volume velocity.
Strategic Opportunities
- India's BIS certification expansion:Mandatory testing protocols for imported lubricants create entry barriers that domestic blenders can exploit through local compounding facilities.
- E-axle thermal management fluids:Electric vehicle powertrains require dielectric coolants with lubrication properties, opening formulation white space distinct from legacy ATF chemistry.
- Direct OEM technical partnerships:Co-development agreements for electrified powertrain fluids enable early specification capture before industry standards crystallize.
Industry Challenges
- Formulation chemist scarcity:Expertise in tribology and electrified powertrain fluid design concentrates among aging specialists, constraining R&D velocity for mid-tier blenders.
- Dual-certification timelines:Simultaneous OEM approval processes for automatic and CVT fluid grades extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Transmission Fluid Market |
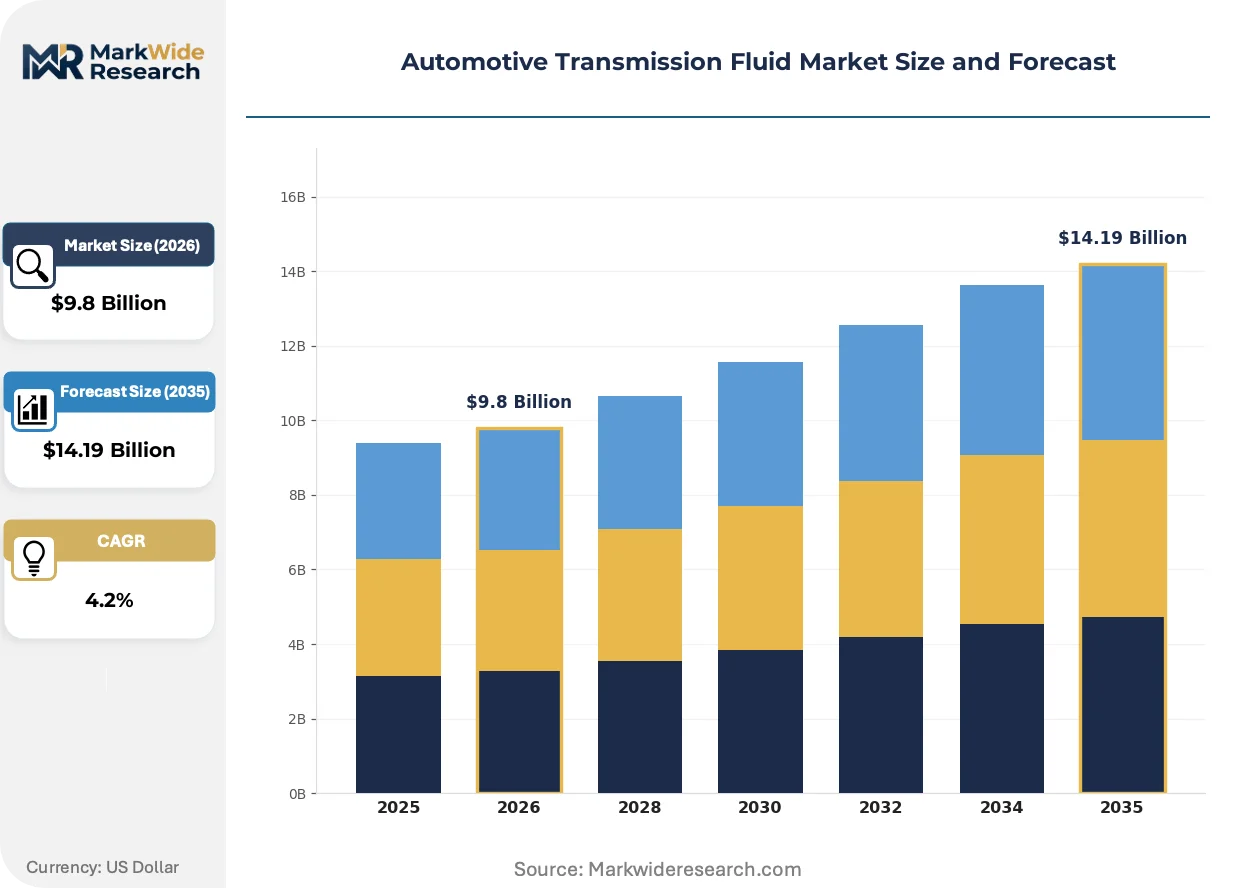
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, CVT, Dual-Clutch Fluid Grade: LOW, MID, HIGH, Premium End User: OEMs, Aftermarket Providers, Fleet Operators, Independent Garages Packaging Type: Bulk, Drums, Bottles, Pouches |
| Companies Covered | ExxonMobil Corporation, Shell plc, BP plc, TotalEnergies SE, Chevron Corporation, Valvoline Inc., Fuchs Petrolub SE, Phillips 66 Company, Idemitsu Kosan Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Transmission Fluid Market Trends and Innovations
Fluid chemistry is diverging along powertrain electrification fault lines, with conventional transmission lubricants facing functional displacement while thermal-electric fluids demand entirely new performance architectures.
Low-viscosity ATF formulations are hybridizing friction control and cooling functions previously handled by separate powertrain fluids. OEMs in Germany and Japan are adopting 0W-8 and 0W-12 viscosity grades for 8-speed and 10-speed automatic transmissions to meet NHTSA fuel economy targets. This convergence is compressing the distinction between transmission lubricants and engine oils in hybrid vehicle applications.
China's SAMR enforcement of updated GB standards for oxidation stability and copper corrosion is tightening market access for uncertified imports. Domestic blenders with integrated additive compounding capabilities are capturing share from traders dependent on bulk import routes. The regulatory friction most affects mid-grade aftermarket products lacking OEM backing.
Fleet operators and independent garages are consolidating purchasing through distributor alliances that demand technical support and inventory guarantees beyond commodity supply. This channel evolution concentrates volume among lubricant marketers with field engineering presence in manufacturing corridors. The shift is most visible in India's commercial vehicle aftermarket, where national fleet contracts displace fragmented state-level procurement.
Automotive Transmission Fluid Market Segmentation
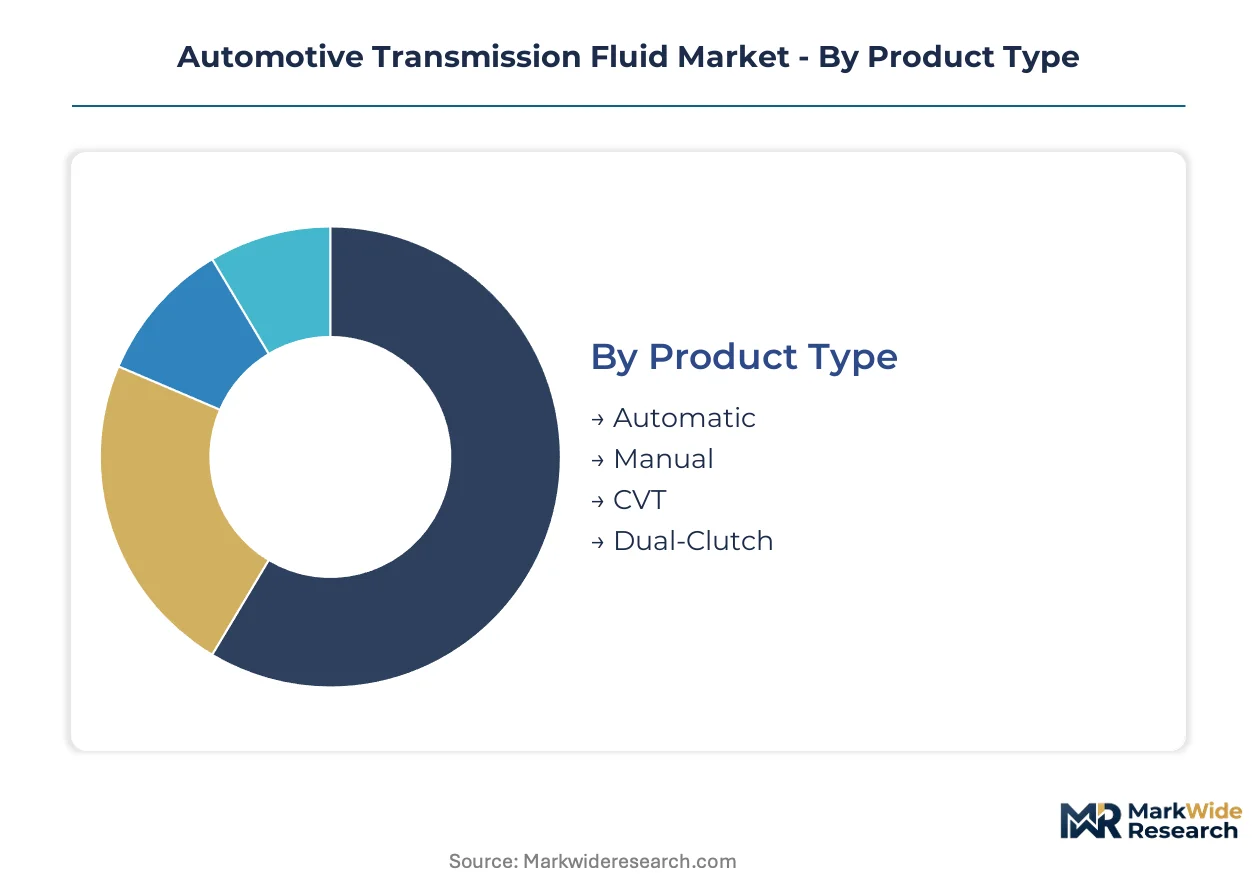
Automotive transmission fluid segmentation reveals how powertrain diversity and supply chain economics fragment demand across incompatible specifications. Each dimension—product chemistry, performance tier, customer channel, and logistics format—creates distinct margin pools and technical barriers to entry.
Product Type:
Cost tier differentiation separates legacy mechanical systems from precision-engineered automated transmissions requiring specialized friction chemistry.
- Automatic:Formulations balance torque converter lockup friction with clutch pack durability across 6-speed to 10-speed architectures. OEM fill contracts in Germany and Japan concentrate demand for low-viscosity 0W-8 and 0W-12 grades meeting NHTSA fuel economy mandates. Extended drain intervals now exceeding 100,000 kilometers compress aftermarket velocity.
- CVT:High-shear-stability base oils with metal-to-metal friction modifiers prevent belt slip in push-belt and chain-driven variable transmissions. China's compact vehicle production around Shanghai and Guangzhou drives fastest adoption as domestic automakers expand CVT installations in mass-market segments.
- Manual:Synchronizer-focused formulations with EP additives serve declining but persistent demand in commercial vehicles and enthusiast passenger cars.
- Dual-Clutch:Wet-clutch specific fluids with controlled friction characteristics manage heat rejection during rapid gear changes in performance and luxury vehicle segments.
Automatic commands the established base. The steepest expansion runs through CVT.
Fluid Grade:
Application intensity determines how additive investment and base oil quality translate into specification compliance and OEM approval.
- LOW:Mineral and Group I base oil formulations serve price-sensitive aftermarket channels in emerging markets where drain interval extension remains limited. India's independent garage network in Chennai and Pune corridors generates concentrated volume despite margin compression.
- MID:Group II and Group III hydrocracked bases with standard additive packages balance performance and cost for fleet operators and regional OEM fill programs. China's SAMR enforcement of updated GB standards is tightening access for uncertified imports in this tier.
- HIGH:Group III+ synthetic bases with OEM-specific additive approvals command premium positioning for warranty-compliant service.
- Premium:Fully synthetic PAO and ester-based formulations with extended drain certification capture first-fill contracts and luxury vehicle aftermarket.
MID grade anchors volume throughput. Premium grade captures margin expansion.
End User:
Customer type dictates specification authority, with OEM technical approval creating entry barriers that aftermarket channels cannot replicate.
- OEMs:First-fill and warranty service specifications require co-development agreements and extended field testing protocols. ExxonMobil and Shell leverage integrated supply chains to secure multi-year fill contracts with German and Japanese automakers.
- Aftermarket Providers:Distributor alliances consolidate purchasing power and demand inventory guarantees plus technical support beyond commodity supply. National fleet contracts in India's commercial vehicle segment displace fragmented state-level procurement.
- Fleet Operators:Centralized lubricant procurement with bulk delivery requirements concentrates volume among marketers with field engineering presence in manufacturing corridors.
- Independent Garages:Price-sensitive spot purchasing through regional distributors dominates emerging market service channels.
OEMs control specification architecture. Aftermarket Providers aggregate fragmented service demand.
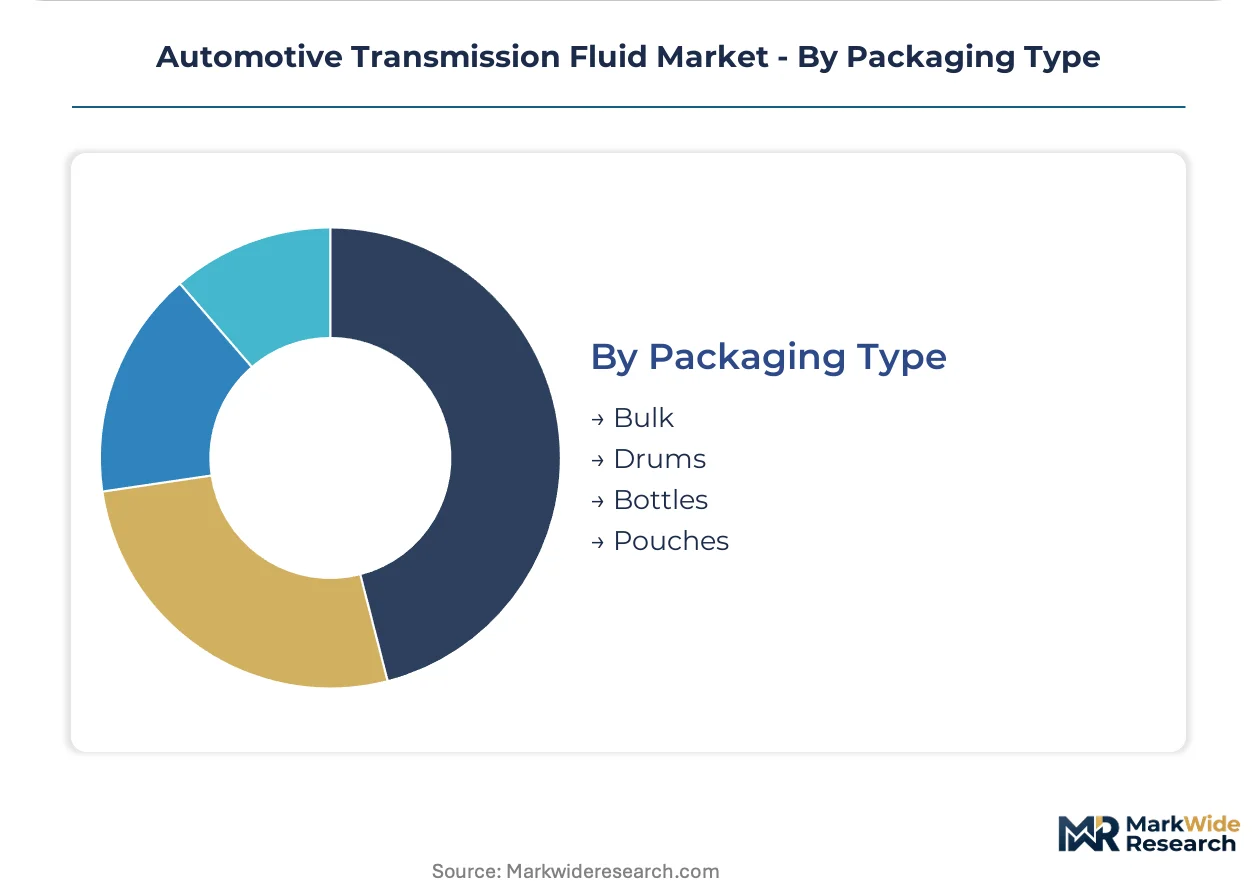
Packaging Type:
Volume scale and logistics infrastructure determine packaging economics, with bulk and drum formats serving production-scale consumption while retail formats address dispersed service points.
- Bulk:Tanker and tote deliveries serve OEM assembly plants and large fleet maintenance facilities with direct-to-equipment fluid dispensing. China's domestic blender expansion around Ningbo and Qingdao prioritizes bulk terminal infrastructure.
- Drums:200-liter steel and poly containers balance portability with unit economics for mid-scale workshops and regional distributors. India's BIS certification requirements for imported lubricants favor domestic drum compounding over bulk import.
- Bottles:1-liter to 5-liter retail formats serve consumer DIY and small independent garage top-off demand.
- Pouches:Flexible single-use packaging addresses emergency roadside and remote service applications with minimal waste disposal burden.
Bulk and Drums dominate production-linked consumption. Bottles capture retail service fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes transmission fluid through CVT-dominant compact vehicle production, while Germany and the United States prioritize low-viscosity formulations for multi-speed automatic transmissions in premium segments.
China
Domestic automakers in Shanghai and Guangzhou corridors are expanding CVT installations in mass-market passenger vehicles. SAMR enforces updated GB standards for oxidation stability and copper corrosion that tighten market access for uncertified imports. Ningbo and Qingdao host expanding domestic blender facilities with integrated bulk terminal infrastructure serving Asia-Pacific OEM demand.
Germany
Automakers specify 0W-8 and 0W-12 viscosity grades for 8-speed and 10-speed automatic transmissions to meet fuel economy targets. KBA type-approval processes govern additive package certifications for warranty-compliant service fluids. Bavaria and Baden-Württemberg concentrate precision lubricant R&D and first-fill contract negotiations with transmission system suppliers.
United States
EPA and NHTSA fuel-economy standards directly shape viscosity grade requirements and additive package approvals for transmission fluids. Extended drain intervals exceeding 100,000 kilometers now dominate OEM specifications for light-duty vehicles. Michigan and Ohio manufacturing corridors generate concentrated demand for automatic transmission fluids serving domestic and export vehicle programs.
India
Production clustering around Chennai and Pune corridors generates concentrated OEM fill demand for transmission fluids serving export and domestic vehicle programs. BIS certification mandates product testing for imported and domestically blended lubricants, creating entry barriers favoring local compounding. Maharashtra and Tamil Nadu host expanding drum compounding facilities that bypass bulk import certification requirements.
Japan
METI coordinates with automakers on low-viscosity fluid specifications for hybrid powertrain applications. JIS standards govern friction durability testing protocols for CVT and dual-clutch transmission fluids. Kanto and Chubu regions concentrate additive package development and technical partnerships between lubricant marketers and transmission system manufacturers.
Automotive Transmission Fluid Market Competitive Landscape
Capability concentration sits with integrated majors possessing captive base oil and additive supply chains; scale advantage sits with regional blenders leveraging local certification and logistics infrastructure. The market structures around three tiers: multinational oil majors with full integration, mid-tier regional compounders with OEM fill relationships, and independent blenders serving price-sensitive aftermarket channels. Two strategic archetypes dominate competitive positioning: chemistry-led formulators capturing premium OEM contracts, and logistics-led distributors consolidating fragmented garage networks. Capacity expansion and direct OEM technical partnerships represent the dominant competitive moves as electrification reshapes product portfolios.
Within the integrated major tier, ExxonMobil Corporation and Shell plc occupy positions defined by upstream control over base oil refining and additive synthesis. Fuchs Petrolub SE exemplifies the precision-formulation archetype, representing specialists that anchor competitive positioning through powertrain-specific fluid development rather than commodity scale. These three entities span the capability spectrum from global supply chain integration to application-engineered chemistry, with each archetype defending distinct margin pools against electrification-driven volume displacement.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| BP plc |
| TotalEnergies SE |
| Chevron Corporation |
| Valvoline Inc. |
| Fuchs Petrolub SE |
| Phillips 66 Company |
| Idemitsu Kosan Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Group III+ base oil hydrocracking across Asia-Pacific is compelling blenders to accept tighter margins and accelerate long-term offtake negotiations with additive suppliers. This utilization squeeze transmits directly into pricing posture, as captive supply chains command premium positioning over traders exposed to spot feedstock volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational blenders and additive package suppliers, insulating OEM fill programs from spot base oil swings. Pricing stratifies across premium, standard, and economy tiers keyed to GB standard certification status and drain interval certification. Cost compression in mid-grade aftermarket channels is intensifying because India's BIS testing requirements favor domestic compounders with lower compliance overhead. Fleet operators exhibit highest price sensitivity due to centralized procurement and volume consolidation, while OEM technical partnerships demonstrate lowest sensitivity given warranty compliance imperatives.
Supply Chain Analysis
Extended payment terms from Chinese domestic blenders are restructuring supplier financing dynamics across the additive tier, compressing working capital for European friction modifier specialists. Manufacturing concentrates in China, Germany, and the United States, with feedstock supply anchored in South Korean and Singaporean hydrocracker output. The chain draws from Group II/III base oils, polyalphaolefin synthetics, and proprietary friction modifier packages. Single-source vulnerability concentrates among three European additive houses. Distribution runs through bulk terminals serving OEM assembly plants, drum networks for regional distributors, and retail bottles for independent garages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through an OEM inventory restocking phase as automakers rebuild transmission fluid safety stocks depleted during semiconductor-constrained production curtailments.
For Market Incumbents: Pre-empt e-axle fluid specification capture by embedding chemists within German and Japanese OEM electrification programs before industry standards crystallize. Secure backward integration into additive synthesis to defend margin position against feedstock volatility and supplier concentration risk. Prioritize drum compounding investments in Maharashtra and Tamil Nadu to exploit India's BIS certification barriers. For New Entrants and Emerging Players: Build out thermal management fluid formulation capabilities targeting Chinese EV powertrain manufacturers in Shanghai and Guangzhou corridors. India's domestic aftermarket for CVT fluids presents the most penetrable white space given fragmented independent garage networks and limited multinational field presence. Pursue technical partnership entry with domestic automakers seeking co-development agreements outside established supplier relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across e-axle and thermal management fluid R&D as electrification forces entirely new chemistry architectures. The five-to-ten-year viability window favors blenders with integrated additive capabilities and OEM fill relationships rather than pure traders. Target acquisition archetypes: regional compounders with SAMR GB standard pre-certification and established drum distribution in Indian manufacturing corridors. Monitor NHTSA fuel economy standard tightening as the critical inflection signal for low-viscosity formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct OEM Technical Partnership | Co-development agreements with German automakers secure first-fill specification lock-in before standards crystallize. |
| Domestic Blender Capacity Expansion | Integrated facilities in Ningbo and Qingdao reduce import dependency and capture SAMR GB standard compliance premiums. |
| E-Axle Fluid Formulation Development | Dielectric coolant chemistry opens margin pools distinct from legacy ATF as electrification displaces mechanical transmissions. |
| Drum Compounding Localization | Maharashtra and Tamil Nadu facilities bypass India's BIS bulk import certification and serve Chennai-Pune manufacturing corridors. |
| Additive Package Backward Integration | Captive friction modifier synthesis mitigates single-source vulnerability from European specialty chemical suppliers. |
Research Methodology
A standing panel of OEM platform engineers, aftermarket distributor procurement leads, and additive package R&D directors provided ongoing calibration against secondary validation through customs trade data, vehicle production databases, and SEC filings from integrated oil majors. Primary fieldwork with Tier 1 supplier technical teams and domestic blender operations in China supplemented the practitioner input. Bottom-up volume builds across product type, fluid grade, and end-user segments were triangulated against top-down market sizing from trade flow analysis.
Scenario-bracketing framed demand projections across the analysis window, with low-case assumptions incorporating accelerated EV penetration eroding mechanical transmission fluid demand and high-case assumptions preserving hybrid architectures sustaining ATF volumes. Segmentation dimensions modeled include transmission architecture, base oil group tier, OEM versus aftermarket channel, and regional regulatory cluster. CAGRs were derived from production-linked consumption curves adjusted for drain interval extension effects. Forecast inputs incorporated IHS Markit vehicle registration data and SAMR GB standard implementation timelines.
Stress conditions across crude price volatility, EV adoption velocity, and regulatory standard enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding powertrain mix evolution and certification timeline adherence. Macroeconomic contraction, unanticipated regulatory relaxation, or breakthroughs in solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Turbine Housing for Automobile Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Drive Shaft Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Automotive TCU Market
Powertrain
CNG Powertrain Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Automotive Conversion Kit Market
Powertrain
High Speed Engine Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Turbocharger Actuators Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Transmission Oil Filters Market