

Synchronizer for Dual-Clutch Transmissions (DCT) Market Size, Share, and Industry Trends Forecast 2026-2036
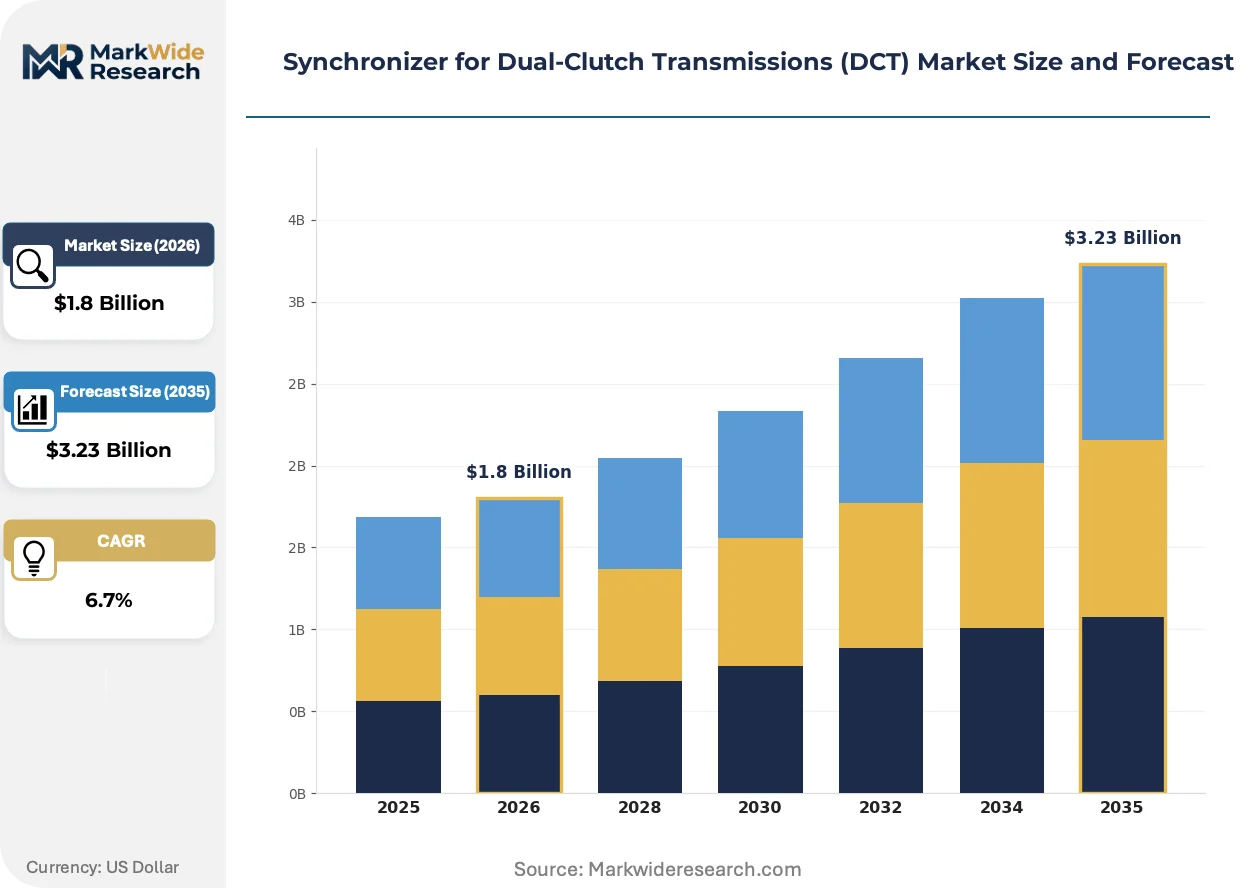
Synchronizer for Dual-Clutch Transmissions (DCT) Market Insights
Consolidation among European and Asian OEM transmission procurement groups is recalibrating supplier negotiation leverage across the synchronizer value chain. BorgWarner leverages its integrated mechatronics portfolio to capture bundled DCT module contracts. Schaeffler anchors high-volume conical and multi-cone synchronizer supply through captive forging and precision machining operations in Germany and China. ZF Friedrichshafen competes by extending its transmission systems expertise backward into proprietary synchronizer hub designs for in-house DCT platforms.
A synchronizer for dual-clutch transmissions is a friction-based shifting element that matches rotational speeds between gear sets before mechanical engagement, typically employing brass-based conical rings with molybdenum-coated surfaces operating at engagement pressures exceeding 20 bar to enable sub-200-millisecond gear changes. Its primary commercial purpose is to protect gear teeth from clash damage while delivering the seamless torque-transfer characteristics that distinguish DCT architectures from conventional automatics. Multi-cone synchronizers command the highest unit values within the product type dimension due to their torque capacity advantage in performance-oriented passenger vehicles and SUVs. Carbon composite technology variants represent the fastest-expanding technology segment as thermal load tolerance becomes critical for electrified DCT applications with integrated motor torque fill.
EPA Corporate Average Fuel Economy standards and Euro 7 emissions frameworks directly shape DCT penetration rates by penalizing torque-converter automatics with higher parasitic losses, thereby expanding the addressable synchronizer market. China's MIIT new-energy vehicle integration mandates and NHTSA fuel-economy compliance pathways in the United States further bifurcate product requirements between efficiency-optimized and performance-calibrated synchronizer specifications. Stakeholders must monitor how electrified DCT architectures with torque-fill motors alter heat-load profiles and material specifications for next-generation friction elements.
Market Dynamics
Electrified powertrain torque-fill architectures are redefining thermal-load thresholds for friction elements, forcing synchronizer suppliers to recalibrate material specifications and engagement-pressure tolerances across their product portfolios.
Growth Catalysts
- Euro 7 emissions frameworks:Stringent efficiency mandates penalize torque-converter parasitic losses, accelerating DCT penetration across European passenger vehicle lineups.
- China MIIT new-energy vehicle integration:Domestic OEMs expand electrified DCT adoption to meet dual carbon goals while preserving performance characteristics.
- Carbon composite friction rings:Enhanced thermal tolerance enables higher engagement pressures in motor-assisted shift scenarios, opening specification upgrades.
Market Restraints
- Copper and molybdenum price volatility:Brass-based conical ring production faces margin compression from concentrated raw material supply chains.
- German forging capacity concentration:Captive precision machining operations in Bavaria and Baden-Württemberg create geographic supply vulnerability.
- Continuously variable transmission substitution:Hybrid-dedicated CVT architectures capture efficiency-focused segments in Japanese and Korean compact vehicles.
Strategic Opportunities
- Indian compact SUV segment:Underpenetrated DCT adoption among domestic brands creates white space for multi-cone synchronizer specification upgrades.
- Electrified DCT torque-fill integration:Convergence of motor-assisted shifting with high-performance friction materials enables premium pricing in performance variants.
- US NHTSA fuel-economy compliance pathways:Fleet-average mandates push Detroit Three toward faster-shifting architectures in mid-size truck and SUV programs.
Industry Challenges
- Tribology and thermal management expertise:Scarce engineering talent capable of modeling friction-interface behavior under electrified torque profiles limits supplier R&D velocity.
- ISO 26262 functional safety certification:Extended validation timelines for shift-actuation software integration compress program launch windows.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synchronizer for Dual-Clutch Transmissions (DCT) Market Trends and Innovations
Friction-material science and mechatronics integration are converging to redefine synchronizer performance benchmarks, with thermal management emerging as the decisive competitive differentiator across supplier portfolios.
Carbon composite friction-ring technology is modularizing synchronizer architectures for electrified DCT applications. Tier-1 suppliers in Germany and South Korea are adopting these materials for 48V mild-hybrid torque-fill programs. The technology is modularizing what were previously discrete thermal-management subsystems into unified friction-element designs.
EPA Corporate Average Fuel Economy standards are tightening enforcement thresholds for passenger vehicle fleets. Automakers face escalating penalties for torque-converter-equipped vehicles, redirecting transmission procurement toward DCT architectures. US-based OEMs are responding by qualifying multi-cone synchronizers for light-truck applications previously served by conventional automatics.
Consolidated transmission procurement groups are unbundling after-sales service from initial equipment supply. Major European and Asian OEMs now negotiate separate lifecycle contracts for replacement synchronizer kits. This pattern is most visible in Germany, where captive service networks capture recurring revenue from high-wear conical ring replacements.
Synchronizer for Dual-Clutch Transmissions (DCT) Market Segmentation
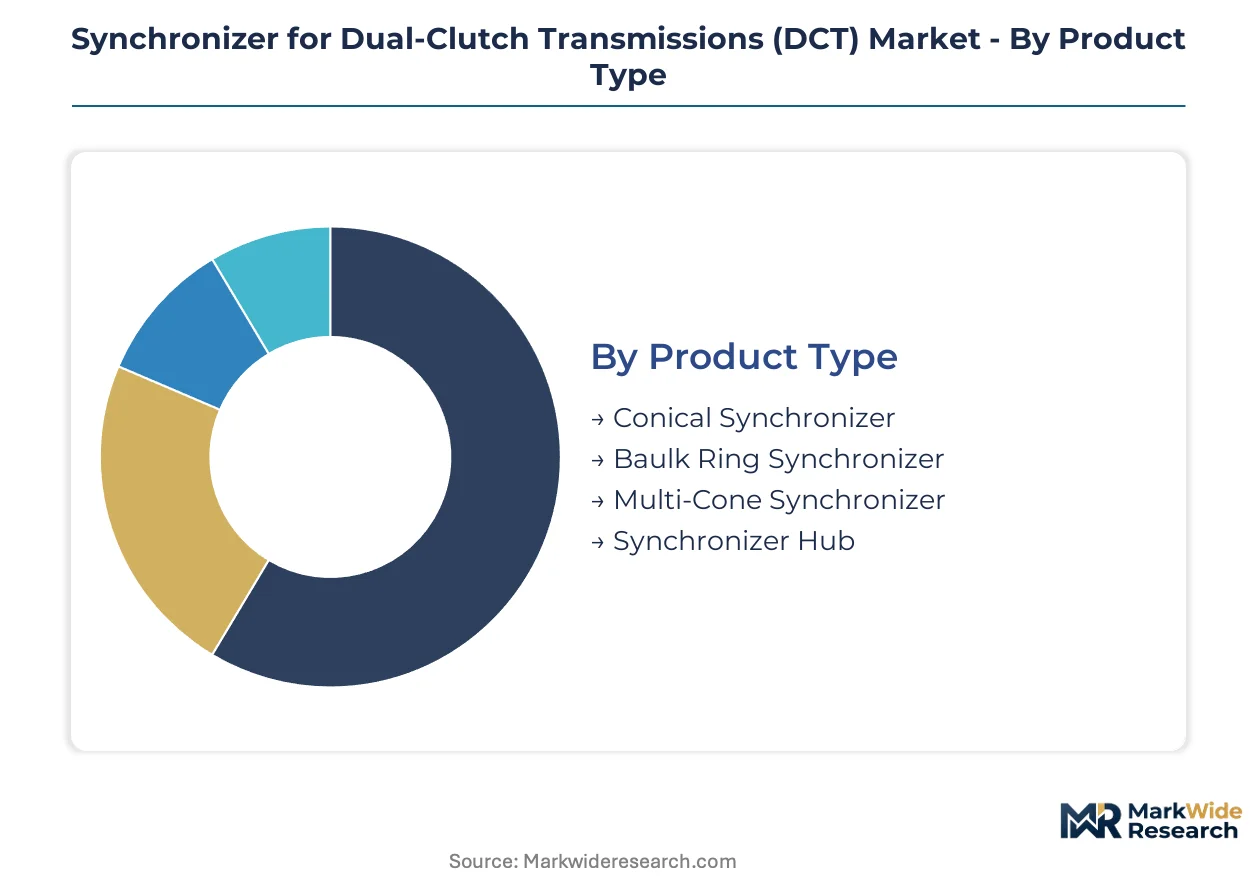
DCT synchronizer procurement splits across friction-element geometries, thermal-material technologies, vehicle duty cycles, and supply-chain tiers. Each dimension carries distinct margin profiles and replacement-cycle economics that reshape supplier prioritization.
Product Type:
Upgrade cycles from single-cone to multi-cone architectures dominate procurement negotiations, with OEMs bundling hub-and-ring combinations into module contracts.
- Conical Synchronizer:Brass-molybdenum conical rings form the baseline friction interface for mass-market passenger DCTs. Chinese OEMs source these in highest volumes for compact sedan programs serving domestic and Southeast Asian export markets.
- Multi-Cone Synchronizer:Stacked friction surfaces multiply torque capacity without enlarging package diameter, enabling sub-150-millisecond shifts in performance SUVs. German and South Korean premium brands specify these for electrified DCT torque-fill architectures where thermal load spikes.
- Baulk Ring Synchronizer:Blocking-ring designs persist in cost-optimized light commercial vehicle transmissions.
- Synchronizer Hub:Splined hub forgings anchor module integration strategies among vertically integrated transmission suppliers.
Conical Synchronizer sits at the top of the volume ranking, with Multi-Cone Synchronizer climbing the fastest.
Technology:
Material thermal tolerance now determines specification tier more than geometric complexity, with carbon composites commanding premium positioning in electrified architectures.
- Carbon Composite:Carbon-fiber reinforced friction rings withstand engagement temperatures exceeding 300°C, enabling higher pressure plate loads in 48V mild-hybrid torque-fill applications. South Korean suppliers lead qualification programs for domestic OEM electrified DCT platforms.
- Triple Cone:Three friction-surface architectures maximize torque density for sports utility vehicle towing ratings. North American light-truck programs adopt these to replace torque-converter automatics under NHTSA fuel-economy compliance pressure.
- Double Cone:Intermediate thermal capacity serves mid-size passenger vehicle segments.
- Hybrid Synchronizer:Mixed-material constructions balance cost and performance for emerging market compact SUVs.
Carbon Composite commands the steepest expansion trajectory, while Double Cone retains the broadest installed base across production lines.
Application:
Vehicle duty-cycle severity dictates friction-material grade and replacement-kit pricing, with off-highway applications running highest per-unit wear rates.
- Passenger Vehicles:Compact and mid-size sedans generate baseline volumes for brass-cone synchronizers. Chinese domestic brands drive specification standardization across A-segment and B-segment platforms.
- Sports Utility Vehicles:Higher mass and towing loads force multi-cone adoption in C-segment and D-segment crossovers. German premium OEMs integrate carbon-composite rings in performance SUV electrified DCT variants.
- Light Commercial Vehicles:Delivery van and small-cargo applications prioritize durability over shift speed.
- Off-Highway Equipment:Construction and agricultural machinery impose extreme thermal cycling on friction elements.
Passenger Vehicles anchor procurement volumes, though Sports Utility Vehicles are gaining share fastest in supplier backlogs.
End User:
Channel structure fragments between captive OEM supply, tier-1 module integration, and aftermarket replacement economics with divergent margin profiles.
- OEMs:Volkswagen Group, Hyundai Motor Group, and Geely Holding negotiate direct synchronizer supply for in-house DCT production. These procurement groups unbundle after-sales service contracts to capture lifecycle revenue from high-wear conical ring replacements.
- Tier-1 Suppliers:BorgWarner and ZF Friedrichshafen bundle synchronizer hubs into complete mechatronic transmission modules. Their integration strategies backward into friction-element supply compress standalone synchronizer supplier margins.
- Remanufacturers:Reconditioned transmission programs in Germany and the United States create secondary demand for replacement ring kits.
- Aftermarket Distributors:Independent service networks stock conical ring sets for out-of-warranty DCT repairs.
OEMs dominate direct procurement volumes, with Tier-1 Suppliers expanding their share through module-integration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in precision forging and tribology concentrate around Stuttgart, Shanghai, and Seoul, anchoring synchronizer R&D and production networks across three continents.
United States
NHTSA fuel-economy compliance pathways push Detroit Three automakers toward faster-shifting DCT architectures in light-truck and SUV programs. The EPA Corporate Average Fuel Economy standards penalize torque-converter parasitic losses, redirecting procurement budgets toward multi-cone synchronizer specifications. Michigan-based transmission engineering clusters in Detroit and Auburn Hills coordinate module integration with Tier-1 suppliers.
Germany
Euro 7 emissions frameworks accelerate DCT penetration across Volkswagen Group and BMW passenger vehicle lineups. The KBA enforces stringent type-approval standards for shift-actuation systems, extending validation timelines for new friction-material qualifications. Bavarian forging operations in Schweinfurt and Baden-Württemberg machining centers anchor captive synchronizer hub production for in-house DCT platforms.
China
MIIT new-energy vehicle integration mandates drive domestic OEMs toward electrified DCT architectures with torque-fill motors. Dual carbon goals from the State Council pressure automakers to preserve performance characteristics while cutting fleet emissions. Yangtze River Delta manufacturing bases in Shanghai and Jiangsu province host precision machining operations serving Geely, BYD, and SAIC transmission programs.
South Korea
Hyundai Motor Group and Kia expand DCT adoption across compact and mid-size segments for domestic and export markets. The MFDS oversees automotive component safety certification, though MIIT alignment pressures shape supplier qualification protocols for Chinese-bound production. Seoul Capital Area engineering centers lead carbon-composite friction-ring development for 48V mild-hybrid torque-fill applications.
India
Domestic compact SUV brands underpenetrate DCT adoption, creating specification-upgrade opportunities for multi-cone synchronizer suppliers. BIS automotive component standards tighten quality benchmarks for imported friction elements, favoring localized forging partnerships. Tamil Nadu and Gujarat automotive clusters in Chennai and Sanand host emerging transmission assembly operations for Maruti Suzuki and Tata Motors programs.
Synchronizer for Dual-Clutch Transmissions (DCT) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the synchronizer value chain, creating a tiered structure where scale advantages clash with technical depth. The market consolidates around transmission-system integrators with backward integration into friction-element supply, compressing standalone component margins. Three archetypes dominate: captive in-house producers, independent precision-forging specialists, and module-integrating Tier-1 suppliers. Competitive moves center on bundled mechatronic module contracts and geographic expansion into underpenetrated SUV segments.
Within the integrated systems tier, ZF Friedrichshafen and BorgWarner exemplify the module-integration archetype, leveraging transmission engineering depth to capture bundled DCT contracts. Schaeffler occupies a position among focused precision-component specialists, anchoring high-volume conical and multi-cone supply through captive forging operations. These three represent divergent strategic postures: systems integration versus component specialization versus captive vertical control.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| BorgWarner |
| Schaeffler |
| Magna International |
| Continental |
| Valeo |
| Getrag |
| Hyundai Transys |
| Punch Powertrain |
| Others |
Pricing and Supply Chain Analysis
Carbon-composite versus brass-molybdenum performance divergence splits synchronizer procurement into parallel pricing ecosystems, with thermal-grade certification tiers commanding 40-60% premiums while commodity conical rings face relentless cost-down pressure from Chinese forging networks. This bifurcation concentrates supply chain investment in Germany and South Korea for premium specifications, while mass-market volumes flow through Yangtze River Delta machining clusters serving domestic OEM consolidation.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for brass-conical synchronizers, compressing margins on standard-grade components while carbon-composite rings maintain pricing power through MIIT new-energy vehicle thermal certification requirements. Three-tier pricing structure across premium carbon-composite, certified multi-cone, and economy brass-cone levels reflects engagement-pressure tolerances and motor-assisted shift compatibility. Price erosion runs through commodity single-cone specifications as Geely and BYD consolidate procurement volumes, while German OEMs exhibit lowest price sensitivity for Euro 7-compliant torque-fill architectures.
Supply Chain Analysis
Direct-to-OEM channels handle Volkswagen Group and Hyundai Motor Group hyperscale buyer demand, bypassing traditional tier-1 module distributors for hub-and-ring combination contracts. Geographic supply concentration centers on Germany for precision forging, China for high-volume machining, and South Korea for carbon-composite friction-ring development. Raw material dependencies draw from Zambian copper concentrates, Chilean molybdenum processing, and Japanese carbon-fiber precursor supply. Single-source vulnerability in Bavarian captive forging operations creates exposure to KBA type-approval delays. Distribution runs through consolidated transmission procurement groups unbundling after-sales service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where electrified DCT torque-fill specifications are displacing commodity brass-cone demand, rewarding suppliers with thermal-management R&D depth and penalizing pure-volume players.
For Market Incumbents: Anchor backward integration into carbon-composite friction-ring production to defend margin position against Schaeffler's captive forging advantages in Germany and China. Prioritize ISO 26262 functional safety certification investment to compress rival qualification timelines for shift-actuation software integration. Consolidate module-contract bargaining power by bundling hub-and-ring combinations with mechatronic actuation systems, responding to BorgWarner's integrated DCT platform strategy. For New Entrants and Emerging Players: Digital aftermarket platforms for replacement synchronizer kits offer the most penetrable entry vector, exploiting European OEM unbundling of lifecycle service contracts from initial equipment supply. Target India's underpenetrated compact SUV segment where Maruti Suzuki and Tata Motors lack multi-cone specification depth. Qualify carbon-composite rings through South Korean 48V mild-hybrid programs as a beachhead for Chinese electrified DCT expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone synchronizer specialists lack thermal-tribology modeling capabilities for electrified torque profiles. Five-to-ten year viability favors precision-forging operations with captive carbon-composite development or tier-1 module integration partnerships. Acquisition target archetype: German or South Korean mid-cap friction-material specialists with MIIT qualification pathways. Monitor copper-molybdenum price volatility spreads as margin inflection signal for brass-cone dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Composite Friction-Ring Qualification | MIIT electrified DCT mandates in China create premium specification upgrade pathway for thermal-tolerant materials. |
| Backward Integration into Precision Forging | Captive hub production in Bavaria and Baden-Württemberg insulates ZF and Schaeffler from raw material volatility. |
| ISO 26262 Functional Safety Certification | KBA extended validation timelines compress program launch windows for non-certified shift-actuation suppliers. |
| Indian Compact SUV Specification Upgrade | BIS quality benchmarks favor localized forging partnerships for Maruti Suzuki and Tata Motors DCT adoption. |
| Aftermarket Service Contract Unbundling | Volkswagen Group captive networks capture recurring revenue from high-wear conical ring replacement economics. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and tribology R&D directors grounded this analysis in operational reality across transmission manufacturing clusters. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA CAFE compliance filings, and Euro 7 regulatory impact assessments. Bottom-up and top-down triangulation reconciled component-level pricing with module-contract value flows.
Bottom-up modeling segmented volume and value across friction-element geometries, thermal-material technologies, vehicle duty cycles, and supply-chain tiers throughout the forecast period. Analytical frameworks derived CAGRs from OEM platform rollout schedules, DCT penetration curves by vehicle class, and replacement-cycle economics for aftermarket synchronizer kits. Industry-specific inputs included engagement-pressure specifications for motor-assisted shift scenarios and carbon-composite thermal tolerance qualification timelines.
Copper-molybdenum price volatility, KBA type-approval delays, and CVT substitution in Japanese compact hybrids are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on electrified DCT adoption rates and thermal-load profile evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.