
 Diesel Particulate Filter (DPF) Market | 2026-2036
Diesel Particulate Filter (DPF) Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Particulate Filter (DPF) Market Outlook
Commercial fleet operators is rotating toward OEM-integrated DPF systems as aftermarket retrofitting loses cost advantage on new vehicle acquisitions. Faurecia SE leverages its exhaust after-treatment integration expertise to anchor European OEM supply chains. Tenneco Inc. competes through manufacturing scale across North American commercial vehicle platforms. Johnson Matthey PLC specializes in catalyzed soot filter technology that combines particulate capture with passive regeneration capability.
A diesel particulate filter is an exhaust after-treatment device constructed from porous ceramic substrates, typically silicon carbide or cordierite, with cellular geometries engineered to trap soot particles while permitting exhaust gas flow; its primary function is to reduce particulate matter emissions from compression-ignition engines below regulatory thresholds. Wall-flow filter architectures dominate current production volumes due to their established filtration efficiency above 95 percent for particulate mass. Active regeneration technology leads technology segmentation because engine-out conditions in urban commercial duty cycles frequently fail to trigger passive thermal regeneration. Ceramic filters command premium positioning in high-temperature applications where thermal shock resistance determines replacement intervals.
EPA Tier 4 and Euro VI emissions frameworks mandate specific particulate number limits that force engine manufacturers to specify DPF systems as standard equipment rather than optional compliance add-ons. China's Ministry of Ecology and Environment enforces China VI standards that align with European test cycles, creating parallel certification requirements for multinational suppliers. California Air Resources Board operates supplemental in-use testing protocols that extend regulatory scrutiny to vehicles already in service. Stakeholders must monitor divergence between European and Chinese test procedures as regulatory misalignment threatens to fragment product validation requirements.
Market Dynamics
Active regeneration technology now dominates DPF system specifications as urban commercial duty cycles fail to generate sufficient exhaust temperatures for passive thermal regeneration, forcing fleet operators to prioritize systems with fuel-fired or electric heating elements over simpler passive designs.
Growth Catalysts
- China VI Standards:China's Ministry of Ecology and Environment enforces particulate number limits that mandate DPF installation on all new heavy-duty diesel vehicles, creating replacement demand across domestic and imported truck fleets.
- Silicon Carbide Substrates:Advanced ceramic materials with higher thermal shock resistance enable extended service intervals in high-temperature applications, reducing total cost of ownership for long-haul operators.
- California In-Use Testing:The California Air Resources Board operates supplemental protocols that extend regulatory scrutiny to vehicles already in service, accelerating aftermarket retrofit and replacement cycles.
Market Restraints
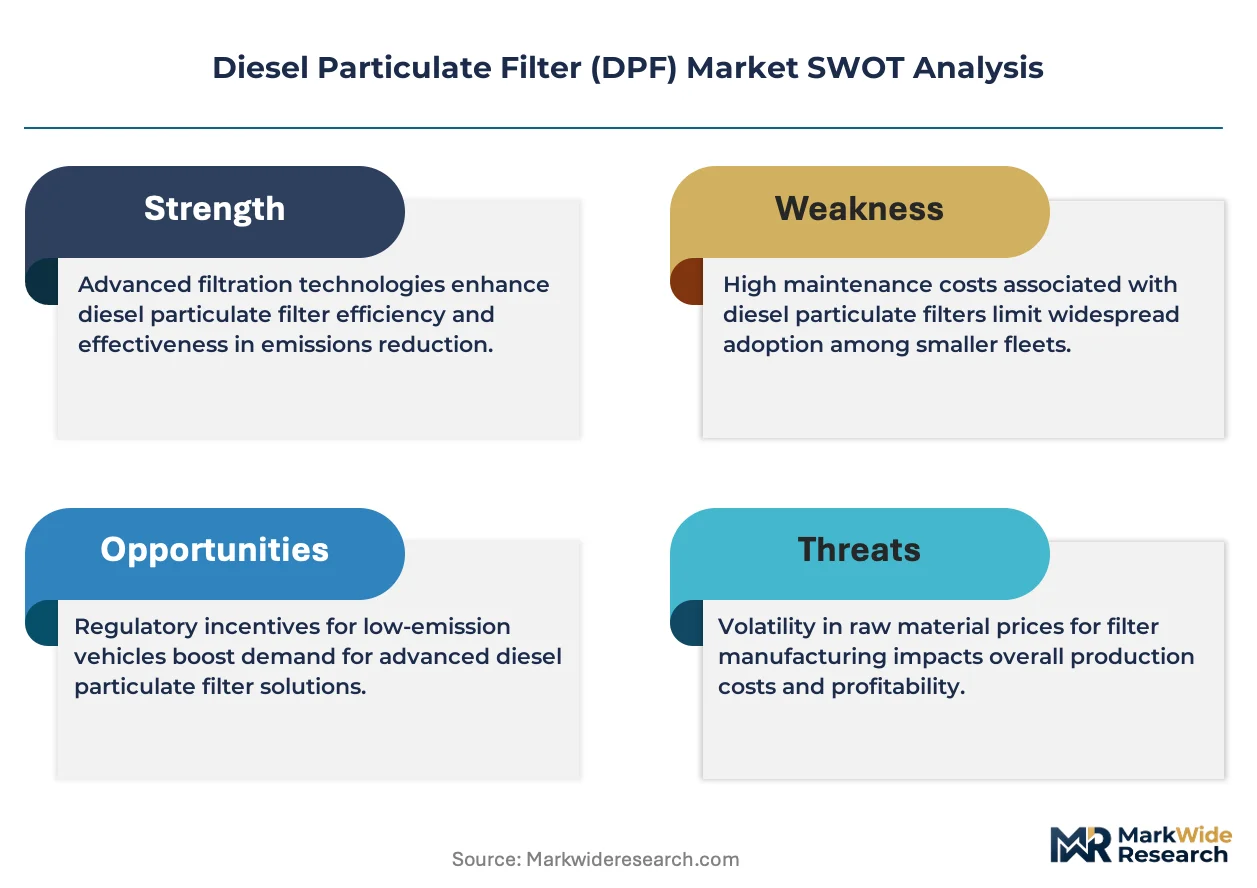
- Precious Metal Cost Volatility:Platinum and palladium prices embedded in catalyzed soot filter formulations create margin pressure for system integrators when commodity markets spike.
- Supply Concentration in Germany:Substrate manufacturing for high-performance applications clusters among specialized German ceramic producers, exposing buyers to single-source risk during capacity constraints.
- Battery Electric Substitution:Zero-emission powertrains in urban delivery segments eliminate exhaust after-treatment requirements entirely, compressing addressable market scope in specific duty cycles.
Strategic Opportunities
- India BS VI Implementation:The country's national automotive regulator mandates DPF fitment on commercial vehicles above specified displacement thresholds, opening fresh demand as enforcement tightens.
- Hybrid Powertrain Integration:Mild-hybrid diesel architectures require modified thermal management strategies that favor advanced filter substrates with faster light-off characteristics.
- Telematics-Enabled Predictive Maintenance:Connected vehicle platforms allow fleet managers to optimize regeneration scheduling based on actual soot loading rather than fixed intervals, creating service revenue attachment.
Industry Challenges
- Ceramic Engineer Talent Scarcity:Specialized expertise in porous media design and thermal stress modeling concentrates among aging workforce cohorts in traditional automotive supply bases.
- Dual Certification Burden:Divergence between European and Chinese test procedures forces suppliers to maintain parallel validation protocols, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Particulate Filter (DPF) Market |
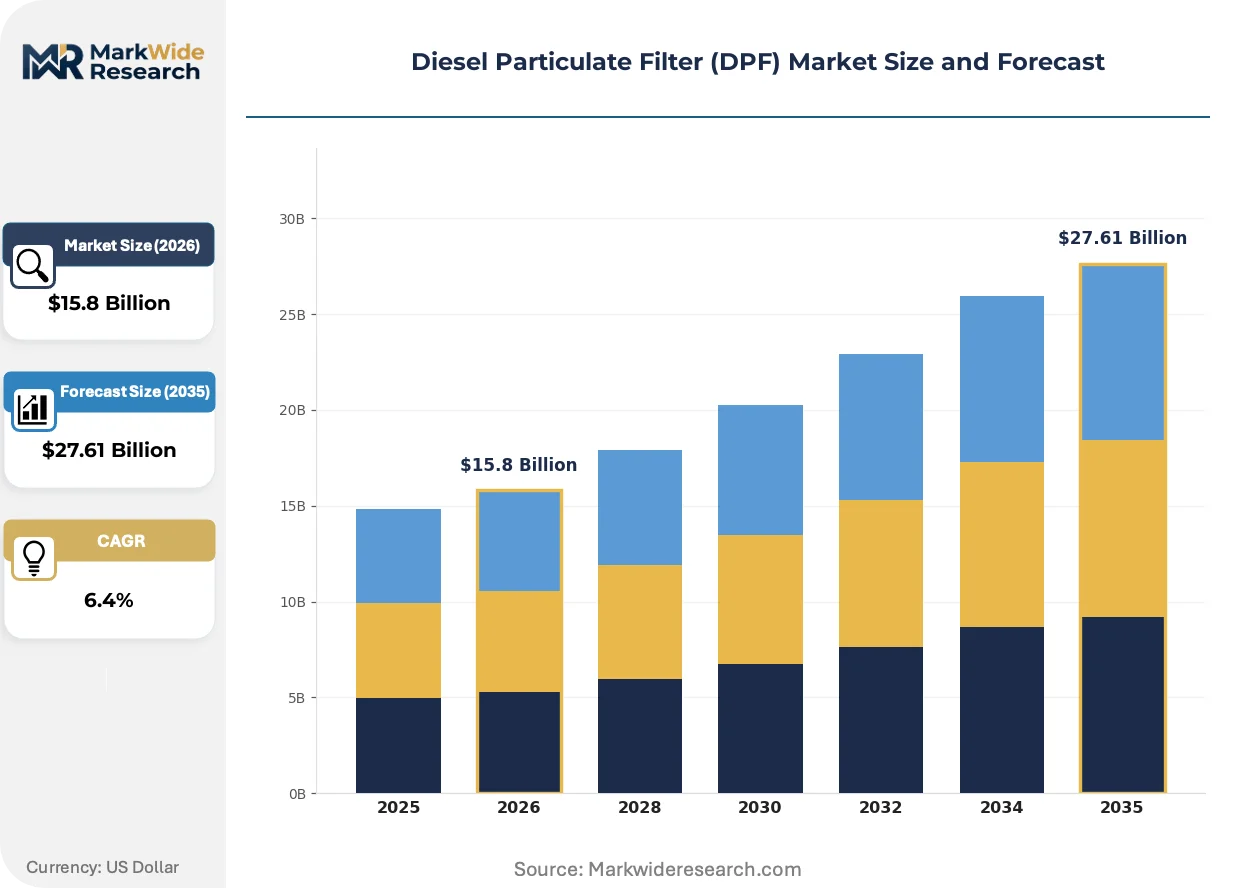
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $27.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidation Catalyst, Wall-Flow Filter, Particulate Filter, Ceramic Filter Technology: Active Regeneration, Passive Regeneration, Hybrid Systems, Thermal Management End User: Commercial Vehicles, Passenger Cars, Construction Equipment, Marine Installation Type: OEM, Aftermarket, Retrofitting, Integrated Systems |
| Companies Covered | Faurecia SE, Tenneco Inc., BASF SE, Corning Incorporated, Continental AG, Johnson Matthey PLC, Denso Corporation, Bosal International, NGK Insulators Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Particulate Filter (DPF) Market Strategic Shifts
Material science advances and connected vehicle architectures are restructuring how DPF systems are specified, monitored, and serviced across commercial vehicle platforms.
Silicon carbide filter substrates are fragmenting the traditional cordierite-dominated supply base by offering superior thermal conductivity and mechanical strength for engines with higher exhaust gas temperatures. European OEMs specify SiC for premium heavy-duty platforms where regeneration frequency and durability determine warranty exposure. The technology is fragmenting procurement patterns as fleet operators segment their specifications by duty cycle severity rather than applying uniform filter grades across mixed fleets.
EPA Tier 4 Final and Euro VI Stage D frameworks tighten particulate number limits below 6x10^11 particles per kilometer, eliminating engine calibration strategies that previously avoided DPF fitment through combustion optimization alone. Engine manufacturers now specify wall-flow filters as standard equipment rather than optional compliance add-ons. North American on-highway segments face the most acute certification pressure as the California Air Resources Board extends in-use testing to vehicles beyond their initial type-approval period.
Fleet procurement departments now bundle DPF maintenance into full-service lease arrangements rather than treating after-treatment as a separate capital item. Commercial vehicle lessors absorb regeneration-related fuel consumption and periodic ash cleaning costs into per-mile pricing. This shift concentrates most visibly in United States regional trucking operations where owner-operators previously bore aftermarket replacement risk directly.
Diesel Particulate Filter (DPF) Market Segmentation
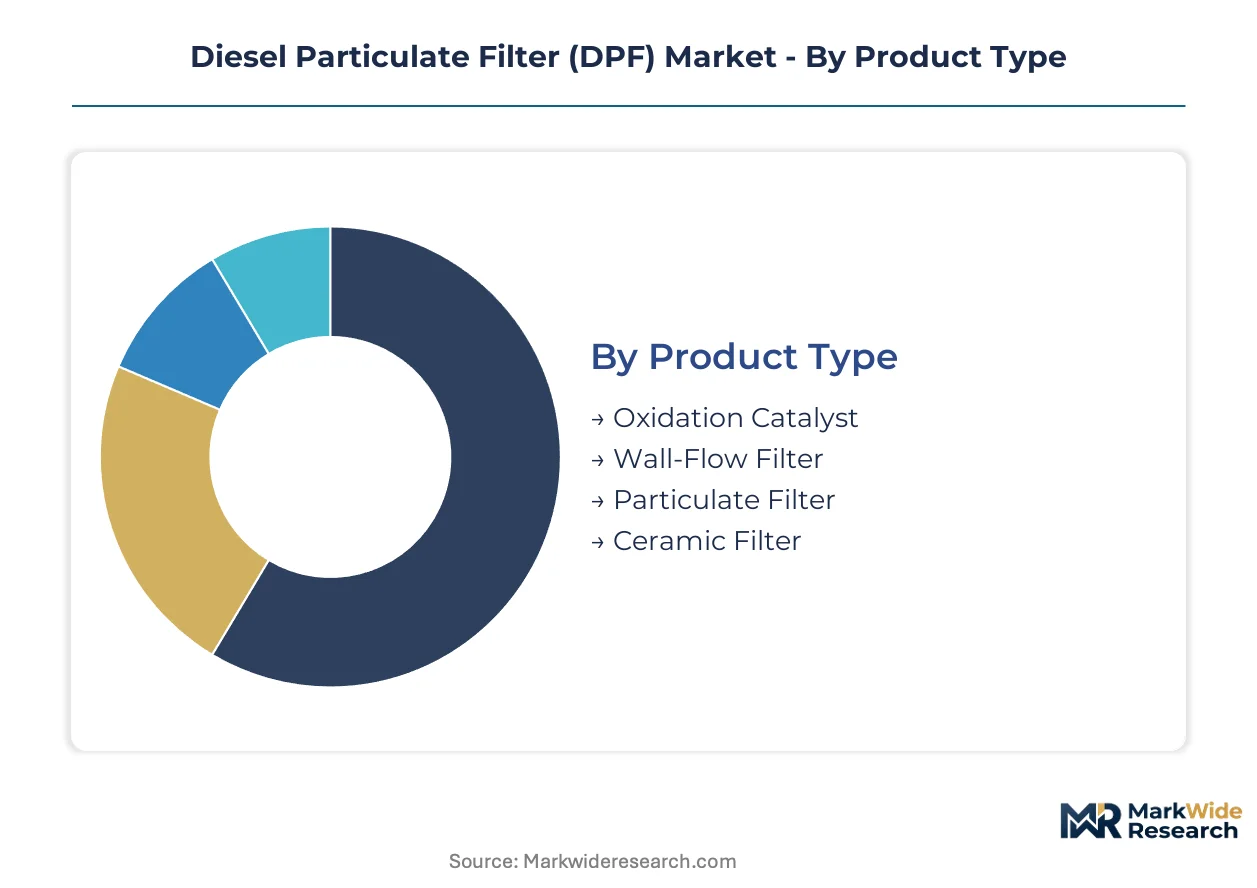
DPF procurement patterns diverge sharply across vehicle platforms and regulatory environments, forcing suppliers to maintain parallel product architectures. Segmentation discipline separates high-volume standardized applications from specialized configurations where thermal durability commands premium positioning.
Product Type:
Battery electric substitution pressure concentrates heaviest on oxidation catalyst segments where mild-hybrid architectures already reduce exhaust flow volumes, while wall-flow filters retain structural demand from Euro VI and EPA Tier 4 mandates.
- Wall-Flow Filter:Cellular ceramic geometries with alternating plugged channels force exhaust through porous walls, trapping particulate mass above 95 percent efficiency. Demand clusters in German heavy-duty OEM supply chains where regeneration frequency determines warranty exposure. Cordierite variants dominate cost-sensitive fleets; silicon carbide substrates penetrate premium long-haul specifications.
- Ceramic Filter:Silicon carbide and aluminum titanate formulations deliver thermal shock resistance above 1,200°C for high-output engines with aggressive regeneration cycles. China VI enforcement drives specification upgrades in domestic truck manufacturing where extended service intervals reduce total ownership cost.
- Particulate Filter:Compact designs for passenger car underfloor packaging balance filtration efficiency against backpressure constraints. European diesel passenger vehicle volumes anchor demand despite powertrain electrification trends.
- Oxidation Catalyst:Platinum-group metal coatings on ceramic honeycomb substrates target hydrocarbon and carbon monoxide conversion rather than soot capture directly. Mild-hybrid diesel architectures in urban delivery segments sustain residual demand.
Wall-flow filters anchor the volume base while ceramic filters gain share at the steepest rate.
Technology:
Cost tier stratification separates fuel-consuming active regeneration from capital-light passive designs, with hybrid architectures emerging as the margin-optimized middle ground.
- Active Regeneration:Fuel-fired or electric heating elements elevate exhaust temperatures to 550-650°C when engine-out conditions fail to trigger soot oxidation. Urban commercial duty cycles in California and Germany mandate this specification where stop-start operation prevents passive thermal recovery.
- Passive Regeneration:Continuous soot combustion relies on nitrogen dioxide catalysis at normal operating temperatures, eliminating supplemental fuel consumption. Highway trucking routes with sustained load profiles sustain this lower-cost architecture.
- Hybrid Systems:Dual-mode operation defaults to passive regeneration with active backup activation during extended idle periods. Fleet operators in mixed-duty applications favor this flexibility despite higher upfront system cost.
- Thermal Management:Insulated housings and exhaust gas recirculation integration optimize temperature windows for regeneration efficiency. Cold-climate specifications in Canada and Scandinavia require this enhancement.
Active regeneration commands the revenue concentration while hybrid systems expand most quickly across blended-duty commercial fleets.
End User:
Application severity determines substrate specification, with construction equipment and marine segments tolerating minimal electrification disruption compared to passenger car exposure.
- Commercial Vehicles:Class 8 trucks and regional delivery vehicles generate the installed base volume under EPA Tier 4 and Euro VI mandates. Fleet leasing arrangements now bundle DPF maintenance into per-mile pricing, transferring technical risk from owner-operators to lessors.
- Construction Equipment:Non-road mobile machinery operates under intermittent load profiles that favor active regeneration systems. China and India infrastructure investment sustains replacement demand for excavators and wheel loaders.
- Passenger Cars:European diesel passenger vehicle production retains DPF fitment despite market share erosion to battery electric alternatives. German and French OEMs specify compact underfloor designs with integrated sensors.
- Marine:Medium-speed diesel propulsion in commercial shipping faces IMO Tier III compliance deadlines that expand scrubber and filter adoption. Harbor craft in California and EU ports face additional local particulate regulations.
Commercial vehicles provide the revenue foundation while construction equipment climbs the fastest on infrastructure spending recovery.
Installation Type:
Customer type stratification concentrates margin in OEM-integrated systems as aftermarket retrofitting loses cost advantage on new vehicle acquisitions with embedded compliance.
- OEM:Factory-integrated DPF systems specified during engine certification capture warranty alignment and thermal packaging optimization. North American and European heavy-duty truck manufacturers standardize this channel.
- Aftermarket:Replacement units for in-service vehicles face California Air Resources Board in-use testing scrutiny that accelerates replacement cycles. Independent repair networks stock cordierite alternatives for cost-sensitive operators.
- Retrofitting:Older vehicle fleets in India and Southeast Asia receive add-on systems to meet emerging BS VI and equivalent standards. Installation complexity limits this segment to specialized conversion shops.
- Integrated Systems:Combined DPF-SCR (selective catalytic reduction) modules reduce packaging volume and thermal management complexity. European OEMs favor this consolidation for Euro VI Stage D compliance.
OEM installation anchors the volume base while integrated systems gain share at the steepest rate on packaging efficiency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Substrate manufacturing for high-performance DPF applications clusters among specialized German ceramic producers, creating geographic concentration that exposes buyers to single-source risk during capacity constraints. This supply-side clustering shapes procurement patterns across major demand centers.
Germany
Heavy-duty OEM supply chains in Stuttgart and Munich drive specification of silicon carbide substrates for premium long-haul platforms where regeneration frequency determines warranty exposure. The KBA enforces Euro VI Stage D certification that mandates wall-flow filter fitment on all new commercial vehicles. Manufacturing concentration in Baden-Württemberg anchors European substrate supply.
United States
Class 8 truck production in Michigan and Ohio generates OEM-integrated system demand under EPA Tier 4 Final mandates. The California Air Resources Board operates supplemental in-use testing protocols that extend regulatory scrutiny to vehicles already in service, accelerating aftermarket replacement cycles. Fleet leasing arrangements in the Midwest now bundle DPF maintenance into per-mile pricing structures.
China
Domestic truck manufacturing in Shandong and Hubei provinces drives China VI compliance upgrades across heavy-duty diesel fleets. The Ministry of Ecology and Environment enforces particulate number limits that mandate DPF installation on all new commercial vehicles. Infrastructure investment sustains construction equipment demand in the Yangtze River Delta region.
India
Commercial vehicle production in Maharashtra and Tamil Nadu faces BS VI implementation deadlines that mandate DPF fitment above specified displacement thresholds. The Central Pollution Control Board tightens enforcement on in-service fleets, creating retrofit demand. Specialized conversion shops in Gujarat cluster to serve emerging aftermarket requirements.
Japan
Passenger car diesel volumes in Aichi and Kanagawa prefectures retain compact underfloor filter specifications despite powertrain electrification trends. METI aligns domestic test procedures with European cycles, simplifying certification for multinational suppliers. Ceramic engineering expertise concentrates in the Nagoya industrial corridor.
Diesel Particulate Filter (DPF) Market Competitive Environment
Concentration sits with diversified automotive suppliers that anchor OEM supply chains through exhaust after-treatment integration capabilities. The vendor base separates into three functional tiers: full-system integrators owning thermal packaging and certification relationships; substrate specialists commanding ceramic engineering expertise; and regional fabricators serving cost-sensitive aftermarket channels. Competitive moves center on manufacturing scale expansion and strategic partnerships that secure raw material access.
Among European-integrated suppliers, Faurecia SE and Continental AG exemplify the full-system archetype that captures warranty alignment through factory-integrated specifications. Tenneco Inc. represents North American manufacturing scale across commercial vehicle platforms. Johnson Matthey PLC occupies the catalyzed filter specialization tier, combining particulate capture with passive regeneration capability. These three anchors illustrate how competitive positioning fragments across integration depth rather than geographic coverage alone.
| Leading Market Players |
|---|
| Faurecia SE |
| Tenneco Inc. |
| BASF SE |
| Corning Incorporated |
| Continental AG |
| Johnson Matthey PLC |
| Denso Corporation |
| Bosal International |
| NGK Insulators Ltd. |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 Final and Euro VI Stage D certification gates both supplier qualification and price differentiation simultaneously, forcing substrate manufacturers to absorb validation costs while fleet operators segment procurement by thermal performance grade rather than uniform specifications.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the DPF market, segmenting procurement into silicon carbide premium specifications, cordierite standard alternatives, and aluminum titanate mid-grade options. Price differentiation hinges on thermal shock resistance ratings and OEM warranty alignment, with California Air Resources Board compliance tiers commanding additional certification premiums. Cost compression in cordierite alternatives is intensifying because Chinese domestic producers expand capacity for BS VI retrofit demand. Long-haul fleet operators show lowest price sensitivity where downtime costs dominate, while regional delivery contractors in India prioritize unit economics over performance margins.
Supply Chain Analysis
Baden-Württemberg ceramic engineering clusters in Germany underwrite substrate supply security for European OEM platforms, with Shandong province in China and Aichi prefecture in Japan providing secondary manufacturing depth. Raw material flows draw from South African platinum-group metal deposits, Norwegian silicon carbide precursor sources, and domestic Chinese cordierite clay reserves. Single-source vulnerability concentrates in specialized German producers of high-porosity silicon carbide formulations. Distribution runs through captive OEM supply agreements for factory-integrated systems, with independent aftermarket channels serving retrofit and replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across North American and European logistics networks concentrates buyer power, compressing margin capture for system integrators unable to bundle regeneration services into long-term contracts.
For Market Incumbents: Compound defensive positioning through backward integration into silicon carbide substrate production and captive regeneration service networks. Battery electric substitution in urban delivery segments threatens cordierite volume bases. Capacity addition in Shandong province secures China VI compliance cost structures while hedging German supply concentration.
For New Entrants and Emerging Players: Differentiate on telematics-enabled predictive maintenance platforms that optimize regeneration scheduling for mixed-duty fleets. India BS VI retrofit demand represents the most penetrable geography, with Gujarat conversion shops lacking integrated sensor diagnostics. A go-to-market angle anchored in fleet management software partnerships bypasses entrenched OEM supply relationships.
For Investors and Strategic Acquirers: China VI Stage D enforcement reshapes the acquisition landscape toward substrate specialists with dual-certification capabilities across European and Chinese test cycles. Long-term viability over the next decade rests on ceramic engineering talent retention and thermal packaging integration depth. Watch California Air Resources Board rulemaking on in-use testing extension as the signal for aftermarket replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Capacity Expansion | Baden-Württemberg producers secure thermal durability premiums for Euro VI Stage D platforms. |
| Telematics Platform Integration | Connected vehicle architectures enable predictive regeneration scheduling for California fleet operators. |
| Dual-Certification Investment | Parallel validation protocols reduce product development timelines for China VI and Euro VI alignment. |
| Aftermarket Service Network Buildout | Independent repair channels capture India BS VI retrofit demand through Gujarat conversion shop partnerships. |
| Hybrid System Technology Licensing | Dual-mode regeneration architectures address mixed-duty cycle requirements across German OEM specifications. |
Study Parameters
A spread of perspectives from OEM platform engineers, fleet procurement directors, ceramic substrate manufacturing leads, and aftermarket distribution managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with Tier 1 supplier technical directors and exhaust after-treatment specialists. Secondary validation drew from EPA certification filings, KBA type-approval databases, China VI enforcement bulletins from the Ministry of Ecology and Environment, and commercial vehicle production registries. Bottom-up demand modeling triangulated against top-down regulatory mandate timelines.
Segmentation dimensions modeled span filter substrate material, regeneration technology architecture, vehicle platform classification, installation channel structure, and regional regulatory cluster across the projection horizon. CAGRs derived from regression analysis against historical compliance phase-in patterns and fleet replacement cycle data. Industry-specific forecast inputs incorporated thermal durability testing standards and warranty exposure calculations for long-haul versus urban duty profiles.
Material uncertainties — platinum-group metal price volatility, divergence between European and Chinese test procedures, and battery electric substitution rates in urban delivery — sit outside the modeled envelope. Forecasts reflect assumptions around enforcement continuity and OEM platform standardization decisions. Practitioners should keep alternative scenarios live as California Air Resources Board in-use testing protocols and India BS VI enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Clutch Actuator Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Automotive Coil Spring Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Power Steering Filter Market
Powertrain
Timing Belt Market
Powertrain
High Speed Engine Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Timing Belt Kits Market
Powertrain
Fuel Pumps Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Gasoline Direct Injection (GDI) System Market