
 Automotive Chromium Market | 2026-2036
Automotive Chromium Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Chromium Market Intelligence
The transition toward trivalent chromium plating processes is rewriting the cost and compliance structure for surface finishing in the automotive sector. This shift away from traditional hexavalent chromium is driven by stringent environmental and health regulations. Atotech leverages its chemical formulation expertise to develop high-performance trivalent systems. MacDermid Enthone Industrial Solutions competes by offering a broad portfolio of compliant plating solutions for Tier-1 suppliers. Meanwhile, SRG Global adapts its large-scale production lines to integrate these newer, more complex chemical processes for major vehicle assemblers.
Automotive chromium refers to chromium applied to vehicle components, primarily through electroplating, to provide a decorative finish and superior corrosion resistance. These coatings are engineered to specific thicknesses, often just a few micrometers, to meet stringent OEM durability and appearance standards. Chromium plating solutions constitute the most significant product type, directly feeding the extensive surface coatings application. While vehicle assemblers are the ultimate end-users, Tier-1 suppliers represent the largest procurement segment, sourcing chromium for components like grilles, badges, and interior trim.
Regulatory frameworks are a primary force shaping the market. Mandates from the European Chemicals Agency (ECHA) under REACH and directives from the US Environmental Protection Agency (EPA) severely restrict or ban hexavalent chromium. These rules compel a market-wide shift to alternative chemistries and processes. Decisions on chemical system adoption and supply chain compliance will determine competitive advantage for manufacturers and their suppliers.
Market Dynamics
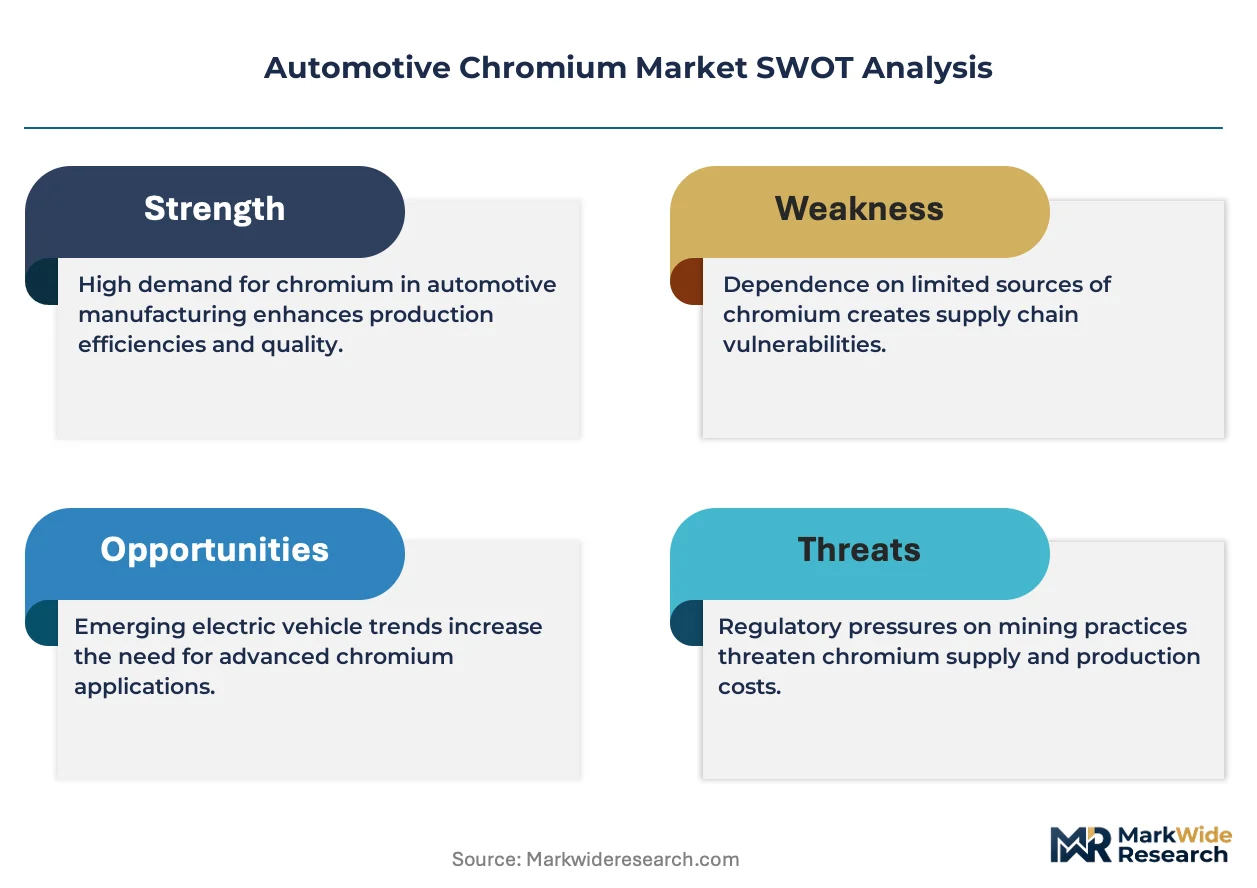
The central structural force is the regulatory mandate to replace hexavalent chromium due to its established health and environmental risks. Directives from the European Chemicals Agency (ECHA) under REACH and rules from the US EPA are compelling a complete chemical and process re-engineering across automotive supply chains.
Growth Catalysts
- Customization Demand:Demand from specialty parts manufacturers for custom and performance applications provides a consistent growth vector for decorative and functional chromium finishes.
- China's Production Scale:High-volume vehicle manufacturing in China creates massive, concentrated demand for chromium-plated components, supporting the entire supply chain's scale.
- Trivalent Chromium Transition:The mandated shift to trivalent chromium, driven by regulations like REACH, stimulates investment in compliant chemical formulations and updated plating lines.
Market Restraints
- Elevated Process Costs:Trivalent chromium systems can involve higher initial capital expenditure and more complex chemical maintenance, raising operational costs for surface finishers.
- Threat from Alternatives:Non-chrome finishes, including Physical Vapor Deposition (PVD) and advanced paint systems, compete directly with chromium for decorative trim applications.
- Performance Disparities:Certain trivalent chromium formulations face challenges in matching the specific deep color and wear resistance characteristics traditionally associated with hexavalent chromium.
Strategic Opportunities
- Electric Vehicle Components:Applying functional chromium coatings to EV parts like battery enclosures for wear and corrosion resistance represents a new application frontier.
- Dark Chromium Finishes:Developing stable black and dark trivalent chromium finishes addresses OEM design demand for "blackout" packages and differentiated model styling.
- Southeast Asian Expansion:Establishing plating operations in automotive hubs like Thailand and Vietnam captures demand from new OEM assembly plants and their supplier networks.
Industry Challenges
- Skilled Labor Scarcity:A shortage of chemical engineers and technicians skilled in managing the more complex chemistries and process controls of trivalent chromium systems hampers adoption.
- Capital-Intensive Retrofitting:Upgrading or replacing entire hexavalent chromium plating lines to accommodate new trivalent processes requires significant capital investment and production downtime for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Chromium Market |
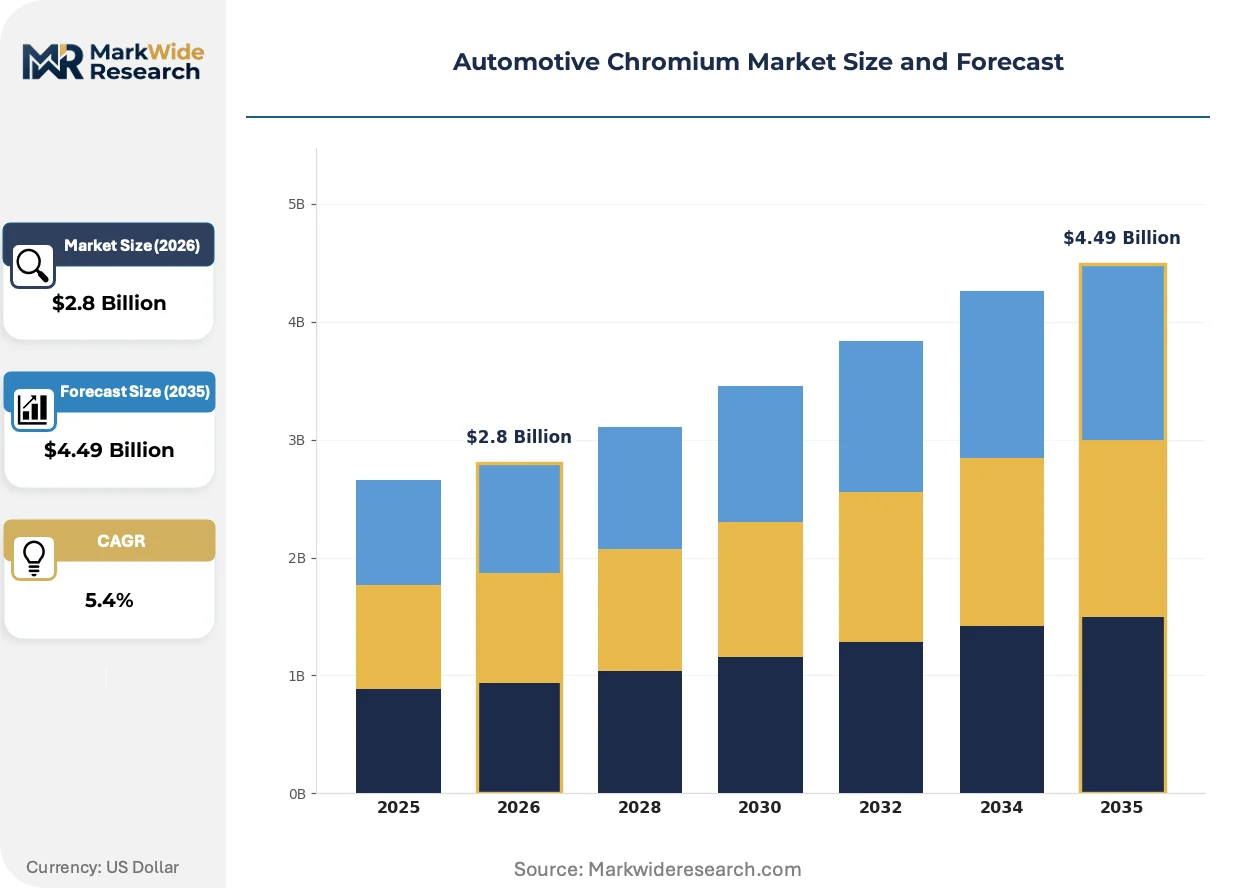
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromium Metal, Chromium Oxide, Chromium Alloys, Chromium Salts, Chromium Plating Solutions Application: Surface Coatings, Catalysts, Corrosion Resistance, Alloy Production, Paint Pigments End User: Vehicle Assemblers, Tier-1 Suppliers, Specialty Parts Manufacturers, Aftermarket Providers Form: Powder, Granules, Chips, Electroplating Bath, Flakes |
| Companies Covered | Atotech, MacDermid Enthone Industrial Solutions, SRG Global, Element Solutions Inc, Sarrel Group, Kakihara Industries, AkzoNobel, PPG Industries, Coventya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Chromium Market Strategic Shifts & Innovations
A convergence of regulatory pressure and technological innovation defines the market's evolution. This dynamic forces changes in chemical composition, process simulation, and OEM procurement strategies for decorative and functional components.
Process simulation and digital twin software allows finishers to model coating deposition and chemical performance. Large Tier-1 suppliers and chemical formulators adopt this to accelerate development and reduce physical prototyping. This advanced modeling is virtualizing the traditionally hands-on process of plating line qualification, compressing timelines for launching compliant finishes.
The European Chemicals Agency's (ECHA) enforcement of REACH authorization deadlines for hexavalent chromium is a definitive market catalyst. These sunset dates create a non-negotiable timeline, compelling a full transition for any company supplying the EU market. Automotive Tier-1 suppliers are therefore expediting validation of trivalent chromium processes to ensure uninterrupted market access.
OEM design teams are moving from standardized finish selection toward collaborative development of specific surface characteristics. This model displaces transactional procurement of cataloged finishes, favoring deeper partnerships between automakers and chemical suppliers. The trend is prominent in the German luxury vehicle segment, where custom dark chrome effects differentiate premium models.
Automotive Chromium Market Segmentation
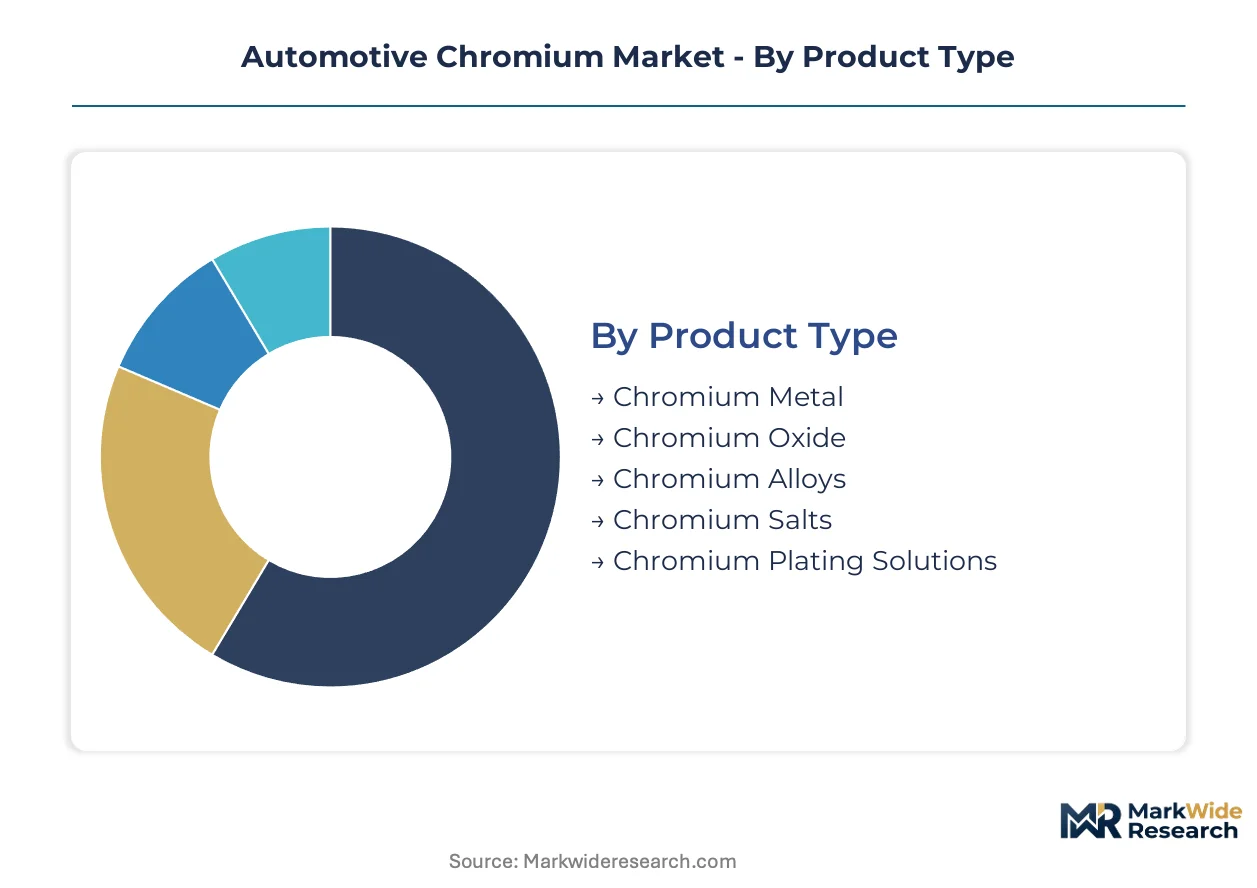
Understanding the Automotive Chromium market requires a granular view of its diverse components and applications. Segmentation illuminates the specific forms of chromium demanded by various automotive processes, from decorative finishes to critical functional coatings. This analysis helps identify where value accrues and which product types address the industry's evolving regulatory and performance requirements.
Product Type:
The use-case spectrum for automotive chromium dictates the chemical form required by manufacturers.
- Chromium Plating Solutions:These aqueous chemical baths contain either hexavalent or, increasingly, trivalent chromium ions used for electroplating. Demand concentrates in China due to its large-scale vehicle production, driving the need for compliant surface finishing.
- Chromium Metal:This high-purity metallic form is crucial for alloying and specialized coating processes like Physical Vapor Deposition (PVD). Its demand is tied to premium vehicle segments seeking enhanced durability and unique aesthetic effects.
- Chromium Oxide:A chemical compound used primarily as a pigment in paints and as a component in certain refractory materials for high-temperature applications.
- Chromium Alloys:These materials combine chromium with other metals to achieve specific properties, such as increased hardness or corrosion resistance in structural components.
- Chromium Salts:Various inorganic chromium compounds serve as precursors for other chromium chemicals or as mordants in specialized industrial processes.
Established volume favors Chromium Plating Solutions; emerging adoption represents the fastest-growing trajectory for Chromium Metal.
Application:
Volume concentration across automotive applications highlights chromium's functional versatility.
- Surface Coatings:This application involves depositing a thin layer of chromium onto a substrate for decorative appeal, wear resistance, and corrosion protection. Tier-1 suppliers widely procure chromium for exterior trim, badges, and interior components.
- Corrosion Resistance:Chromium layers provide a passive oxide film that significantly enhances the longevity of metallic parts, protecting them from environmental degradation. This is particularly critical for under-the-hood components and electric vehicle battery enclosures.
- Catalysts:Chromium compounds function as catalysts in various chemical reactions, though their automotive application is more specialized, often in exhaust treatment systems.
- Alloy Production:Chromium is a key alloying element, imparting hardness and corrosion resistance to steels and other metal matrices used in automotive manufacturing.
- Paint Pigments:Chromium compounds contribute vibrant colors and durability to automotive paints and coatings, though regulatory pressures are shifting formulations.
Functional versatility drives demand for Surface Coatings, while specialized needs elevate Corrosion Resistance.
End User:
Supply concentration within the automotive value chain defines procurement patterns for chromium products.
- Tier-1 Suppliers:These manufacturers produce sub-assemblies and components directly for vehicle assemblers, representing the largest procurement segment for chromium. Their operations often involve extensive electroplating lines for grilles, wheels, and interior accents.
- Vehicle Assemblers:Original Equipment Manufacturers (OEMs) integrate components from Tier-1 suppliers, using chromium directly for final assembly or specialized in-house finishing processes. German luxury vehicle brands often specify custom dark chrome effects.
- Specialty Parts Manufacturers:Smaller firms focus on niche components, custom designs, or performance parts, often requiring bespoke chromium finishes. Their demand provides a consistent growth vector for decorative and functional applications.
- Aftermarket Providers:Companies supplying replacement parts or customization accessories for vehicles after initial sale constitute this segment. Their chromium demand supports repair and personalization markets.
Component integration from Tier-1 Suppliers dominates procurement, with Vehicle Assemblers expanding for direct assembly.
Form:
Maturity of processing and handling requirements differentiate the various physical forms of automotive chromium.
- Electroplating Bath:These liquid solutions are central to the electrodeposition of chromium onto automotive components. The transition to trivalent chromium systems necessitates updated bath chemistries and process controls.
- Powder:Chromium in powder form is utilized in various metallurgical processes, including powder metallurgy, thermal spraying, and as a component in certain advanced coating technologies. Its use is expanding in additive manufacturing applications.
- Granules:Granular chromium is often a raw material for alloy production or in specific chemical manufacturing processes.
- Chips:Chromium chips are typically used in alloying processes, providing a convenient form for melting and blending with other metals.
- Flakes:Flaked chromium can be employed in specialized coatings or as an additive in certain chemical formulations, offering distinct surface area characteristics.
Ease of handling supports Powder, as advanced processes increasingly utilize Electroplating Bath.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive chromium market exhibits a dynamic export-import balance, with significant production capacities often serving international vehicle assembly operations. Regulatory shifts in major manufacturing regions influence material sourcing and demand across continents. China's large-scale vehicle production drives substantial domestic consumption and global trade flows.
China
China's high-volume vehicle manufacturing creates massive, concentrated demand for chromium-plated components. The country's GB standards influence material specifications for automotive surface finishing, especially for export. In the Yangtze River Delta, numerous OEM assembly plants integrate these components into their production lines, driving extensive surface coatings.
Germany
German luxury vehicle brands drive demand for custom dark chrome effects and high-performance finishes. ECHA's REACH regulations compel a market-wide shift to compliant trivalent chromium chemistries across the supply chain. Automakers in Bavaria partner with chemical formulators to develop differentiated model styling for premium models.
United States
United States Tier-1 suppliers procure chromium for a wide range of exterior and interior components, including grilles and badges. The US Environmental Protection Agency (EPA) severely restricts hexavalent chromium, forcing a market-wide shift to alternatives. Automotive manufacturing hubs in Michigan are retrofitting plating lines for trivalent systems and advanced processes.
Mexico
Mexico's expanding automotive production for the North American market fuels demand for plated components and specialized finishes. Local environmental regulations, alongside USMCA trade agreements, shape material compliance requirements for suppliers. The Bajío region sees significant investment in plating operations to support new OEM assembly plants and their extensive supplier networks.
Automotive Chromium Market Key Industry Players
On the supply side, the industry is transitioning from a fragmented base of traditional platers to a more consolidated landscape of specialized chemical formulators and large-scale surface finishers. Strategic archetypes include specialized chemical suppliers focusing on trivalent chromium, integrated plating solution providers, and large-volume component manufacturers adapting their lines. Companies pursue capacity expansion and strategic partnerships to navigate stringent regulatory changes and meet evolving OEM demands for compliant finishes.
Specialists in chemical formulation and plating solutions, Atotech and MacDermid Enthone Industrial Solutions exemplify the shift towards high-performance trivalent systems. These entities focus on developing compliant chemistries and broad portfolios for Tier-1 suppliers. SRG Global occupies a position as a large-scale component manufacturer, adapting its production lines to integrate complex chemical processes for major vehicle assemblers. This grouping reflects the industry's need for both innovative chemistry and large-scale application capabilities.
| Leading Market Players |
|---|
| Atotech |
| MacDermid Enthone Industrial Solutions |
| SRG Global |
| Element Solutions Inc |
| Sarrel Group |
| Kakihara Industries |
| AkzoNobel |
| PPG Industries |
| Coventya |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam freight corridor's cost dynamics influence the pricing of chromium plating solutions, impacting supply concentration from China and downstream price differentiation for automotive components. This market navigates complex material sourcing and process compliance, directly affecting finished part costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for chromium plating solutions, seeking stability and volume discounts. Price differentiation stems from the quality grade of trivalent formulations and the level of customization required for unique aesthetic effects like dark chrome. Pricing pressure arises from the mandated transition to more complex trivalent chemistries, which involve higher initial capital expenditure for surface finishers. Vehicle assemblers in the luxury segment exhibit lower price sensitivity for bespoke finishes, while Tier-1 suppliers procuring for high-volume standard components remain highly price-sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly common within the automotive chromium market, particularly for large Tier-1 suppliers. Geographic supply concentration centers on China, Germany, and the United States, reflecting major automotive production hubs. The supply chain draws from chromium metal and specialized chemical precursors for plating solutions. Regulatory restrictions, such as ECHA's REACH authorization deadlines for hexavalent chromium, pose a significant structural risk across the supply base. Distribution typically runs directly from chemical formulators to Tier-1 suppliers or through specialized electroplating service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is at a platform-economics inflection, driven by the integration of digital twin software and advanced chemical formulation within the automotive manufacturing ecosystem.
For Market Incumbents: Insulate core market share by accelerating investment in high-performance trivalent chromium R&D and securing long-term supply agreements with key Tier-1 suppliers. Address the threat from non-chrome alternatives by enhancing the wear resistance and aesthetic range of compliant trivalent finishes. Capacity additions in automotive manufacturing hubs like Mexico can strengthen regional supply chains and certification investment for new trivalent processes.
For New Entrants and Emerging Players: Establish a beachhead in the electric vehicle component segment by developing functional chromium coatings for battery enclosures and power electronics. Target specialty parts manufacturers with bespoke trivalent finishes, offering advanced process simulation tools as a key go-to-market angle. Underpenetration exists in Southeast Asian automotive assembly markets, presenting opportunities for new plating operations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core plating solution businesses. The long-term viability of chromium in automotive applications remains strong for both decorative and functional purposes. Investors should seek specialized trivalent chemical formulators or advanced plating technology providers. Successful large-scale OEM adoption of a specific dark trivalent finish serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Captures demand from new OEM assembly plants and their supplier networks. |
| Green Manufacturing Transition | Ensures compliance with stringent environmental regulations, particularly in the EU. |
| Long-term Supply Agreements | Secures material flow for Tier-1 suppliers amidst evolving chemical formulations. |
| Technology Licensing for Trivalent Formulations | Accelerates market adoption of compliant and high-performance chromium chemistries. |
| Platform Standardization for Plating Processes | Reduces operational complexity and costs for large-scale automotive component manufacturing. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary validation. Primary insights were gathered from Tier-1 procurement leads, OEM platform engineers, chemical R&D directors, and plating line managers. Secondary data sources included ECHA and EPA regulatory documents, automotive production databases, and chemical industry reports, all triangulated through bottom-up and top-down approaches.
Forecast inputs considered regulatory timelines, global vehicle production volumes, material science advancements in trivalent chromium, and evolving OEM design trends across the analysis window. The analytical framework modeled market segmentation by product type, application, end-user, form, and regional production cluster. Compound annual growth rates were derived from historical trends and projected adoption rates of compliant trivalent systems.
Sensitivities concentrate around unforeseen regulatory changes and rapid material science breakthroughs in alternative finishes. Forecasts reflect assumptions documented at the time of publication, acknowledging potential shifts. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Automotive Straps Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Automotive Bearing Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Pedals Market
Automotive Components
Automotive Radiator Grille Market