
 Electric Vehicle Motor Control Unit Market | 2026-2036
Electric Vehicle Motor Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Motor Control Unit Market Insights
China's Jiangsu and Zhejiang province corridor is rewriting supply geography for EV motor control units as local battery gigafactories pull controller assembly inland. Bosch leverages its Stuttgart engineering base to sustain high-voltage inverter R&D for European OEM platforms. BYD anchors the Asia-Pacific controller landscape through captive vertical integration with its blade battery architecture. Continental AG competes on 800-volt silicon carbide module designs that reduce switching losses in premium passenger applications.
An electric vehicle motor control unit governs torque delivery, speed regulation, and energy recovery in battery-electric and hybrid powertrains through insulated-gate bipolar transistor or silicon carbide switching arrays operating at 400-800 volts DC. Brushless motor controllers dominate passenger vehicle installations where permanent magnet synchronous motors require precise field-oriented commutation. Field-oriented control technology leads commercial vehicle deployments because its dynamic torque response suits variable-load bus and truck duty cycles. Sensorless control architectures are gaining fastest in two-wheeler segments where cost constraints eliminate resolver or encoder hardware.
The EPA tailpipe standards and NHTSA CAFE rules in the United States tighten fleet-average emissions benchmarks that OEMs meet only through expanded EV powertrain procurement. China's MIIT GB/T standards and dual carbon goals mandate domestic controller efficiency certifications that foreign suppliers must obtain through local joint ventures. The EU Green Deal and F-Gas Regulation indirectly shape controller demand by accelerating refrigerant system electrification that shares power electronics with thermal management modules. Stakeholders must monitor silicon carbide substrate supply allocations and foundry capacity commitments before committing platform-level controller sourcing strategies.
Market Dynamics
Silicon carbide substrate shortages are compressing controller production timelines as automotive OEMs dual-source power modules across competing foundry networks. This supply-side tension is forcing tier-one suppliers to renegotiate long-term wafer allocation contracts ahead of platform launches.
Growth Catalysts
- EPA tailpipe standards:Fleet-average emissions benchmarks in the United States mandate expanded EV powertrain procurement across light-duty and commercial vehicle segments.
- Sensorless control architectures:Elimination of resolver hardware is reducing bill-of-materials costs for two-wheeler manufacturers in cost-sensitive Asian markets.
- Yangtze River Delta concentration:Battery gigafactory clustering in Jiangsu and Zhejiang provinces pulls controller assembly inland to minimize logistics friction.
Market Restraints
- Silicon carbide wafer supply:Limited 150mm and 200mm substrate capacity constrains high-voltage inverter scaling for 800-volt platforms.
- GB/T certification barriers:China's MIIT mandates require foreign suppliers to establish local joint ventures for controller efficiency testing.
- IGBT module obsolescence risk:Legacy silicon-based switching arrays face displacement as OEMs freeze 400-volt architectures.
Strategic Opportunities
- Commercial vehicle electrification:Bus and truck duty cycles favor field-oriented control systems with dynamic torque response.
- EU Green Deal thermal integration:Refrigerant system electrification creates shared power electronics demand with thermal management modules.
- Aftermarket controller refurbishment:Independent service channels in Germany and the United States are developing remanufacturing capabilities for out-of-warranty EV fleets.
Industry Challenges
- Power electronics talent scarcity:Shortages of field-oriented control firmware engineers delay platform development cycles at tier-one suppliers.
- 800-volt safety certification:Arc containment and isolation testing protocols extend homologation timelines for premium passenger applications.
- Legacy thermal management integration:Controller packaging must accommodate refrigerant line routing without compromising IP67 sealing integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Motor Control Unit Market |
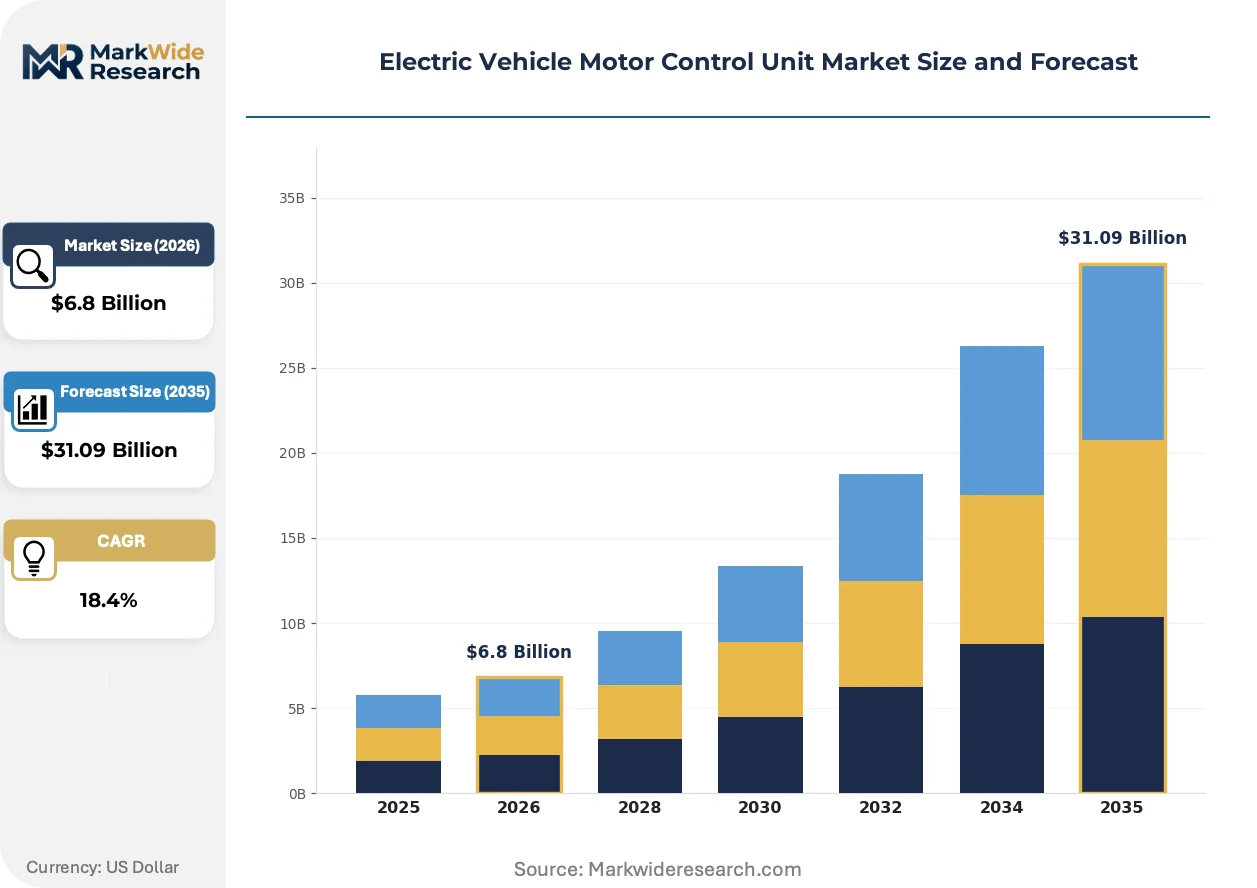
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motor Controllers, DC Motor Controllers, Brushless Motor Controllers, Hybrid Motor Controllers Technology: Field-Oriented Control, PWM Control, Direct Torque Control, Sensorless Control End User: OEMs, Aftermarket Providers, Fleet Operators, Charging Infrastructures Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Industrial Applications |
| Companies Covered | Denso, ZF, BYD, Hitachi Astemo, BorgWarner, Bosch, Tesla, Inovance, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Motor Control Unit Market Trends and Innovations
Wide-bandgap semiconductors and embedded AI torque prediction are converging to redefine motor control architectures. These advances compress switching losses while enabling predictive thermal management across variable load profiles.
Silicon carbide MOSFET arrays are digitizing inverter efficiency curves through reduced switching losses and higher thermal operating ceilings. Commercial vehicle OEMs in Europe and China are adopting 800-volt SiC modules for heavy-duty traction applications. This transition is digitizing the competitive landscape by rewarding suppliers with captive substrate sourcing agreements.
China's MIIT GB/T efficiency mandates are tightening certification thresholds for imported controller hardware. Domestic joint ventures must now demonstrate localized thermal cycling test data before platform approval. European suppliers are responding by transferring validation engineering to Suzhou and Ningbo facilities.
Fleet operators are consolidating procurement through multi-year platform contracts that bundle controller supply with battery pack sourcing. Direct OEM-fleet negotiations are displacing traditional tier-one distributor channels in North American logistics markets. This concentration is most visible in California and Texas, where drayage and last-mile operators are standardizing on single-vendor powertrain stacks.
Electric Vehicle Motor Control Unit Market Segmentation
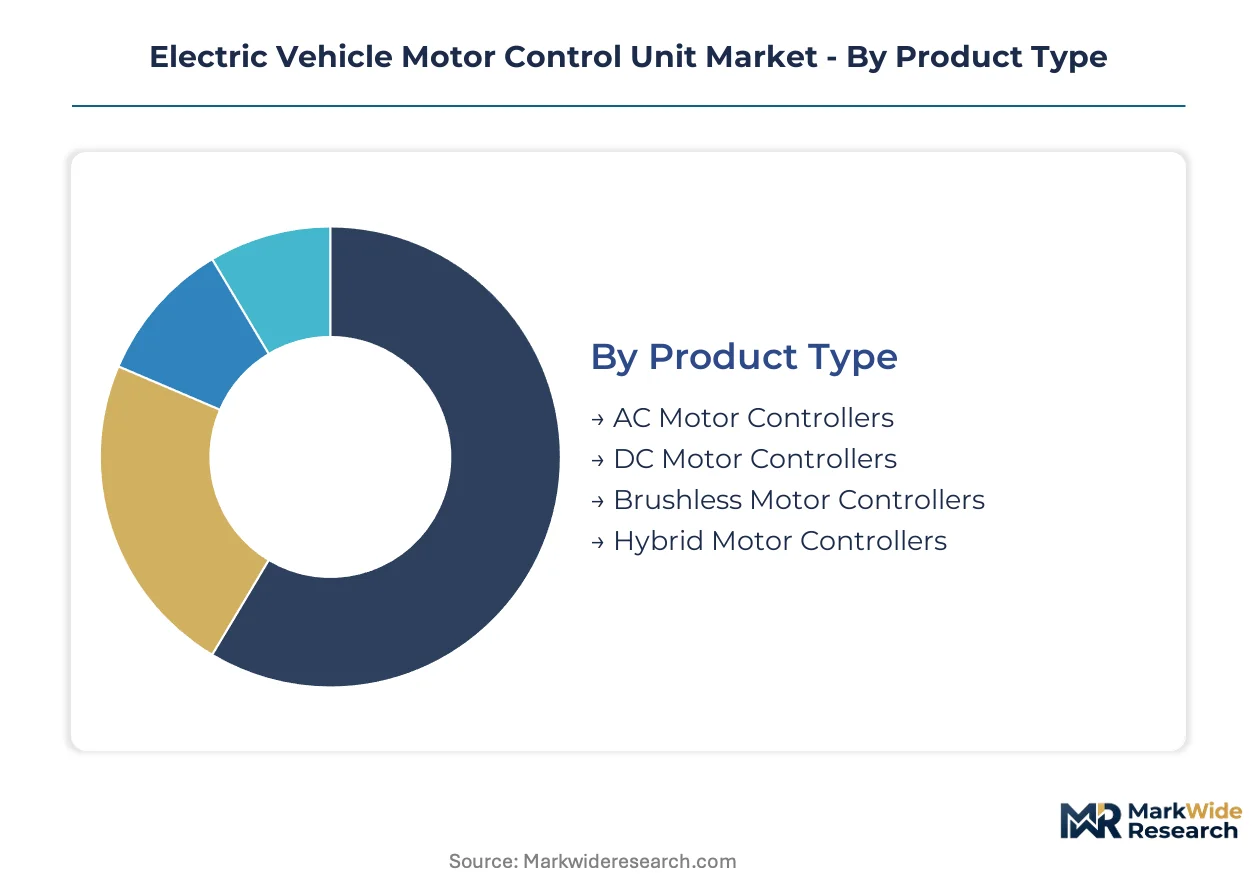
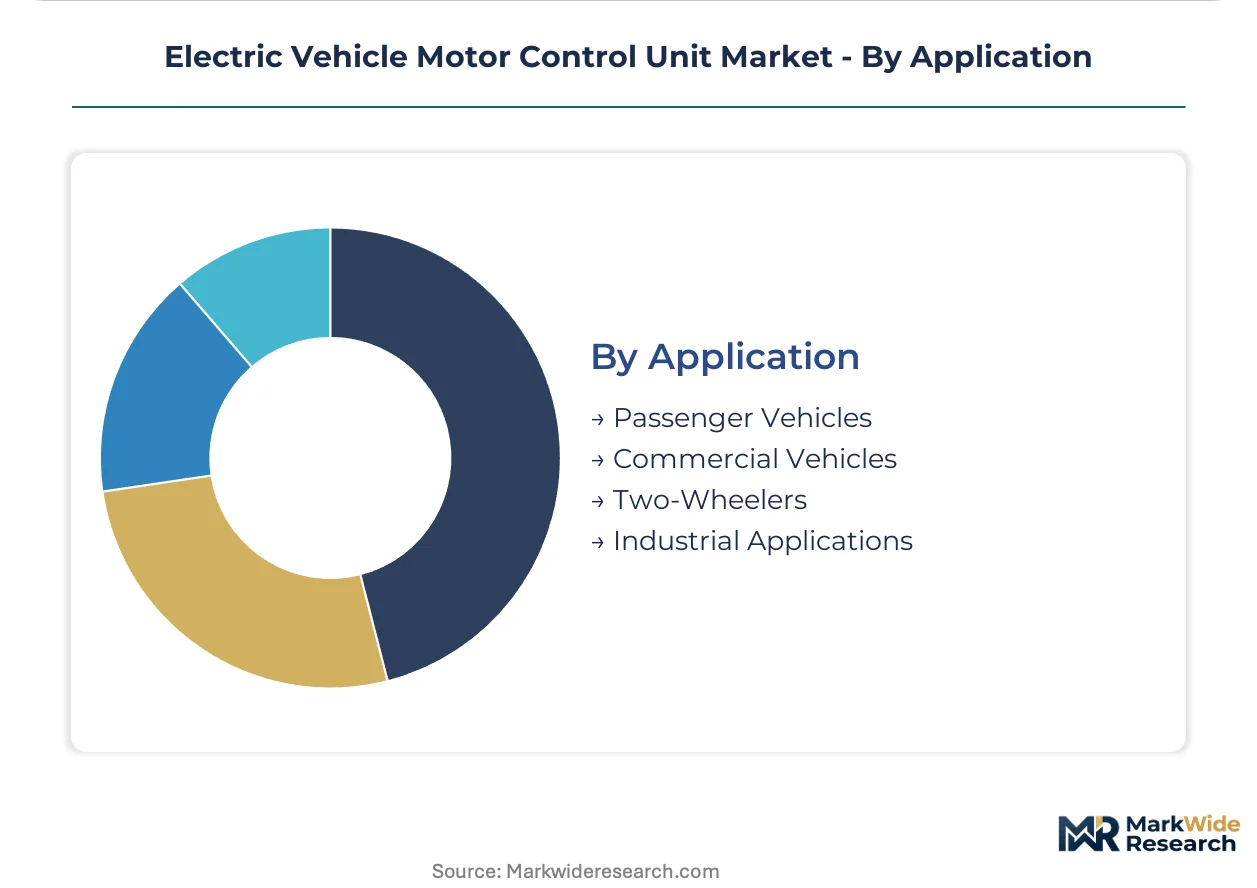
Motor control unit procurement patterns diverge sharply across powertrain architectures and customer types. Controller specifications must align with voltage platforms, thermal envelopes, and duty cycle profiles that vary by application and end user.
Product Type:
Cost tier determines switching technology, thermal management complexity, and integration depth with battery management systems.
- AC Motor Controllers:These units manage induction motor torque through variable frequency drives operating at 400-800V DC input. Demand clusters in European commercial vehicle platforms where asynchronous motors tolerate thermal stress in heavy-duty cycles. Siemens and Danfoss anchor supply for 350kW+ traction applications.
- Brushless Motor Controllers:Permanent magnet synchronous motor control dominates passenger EV installations through field-oriented commutation algorithms. China's Yangtze River Delta manufacturing corridor produces the majority of 150kW-rated units for domestic OEM platforms. The MIIT GB/T efficiency mandates favor these controllers for their superior power density.
- DC Motor Controllers:Legacy brushed motor control persists in low-voltage auxiliary systems and retrofit conversions.
- Hybrid Motor Controllers:Dual-mode units coordinate engine-generator torque blending in PHEV architectures.
Brushless controllers command the established base. The steepest expansion runs through AC motor controllers for heavy commercial electrification.
Technology:
Application requirements dictate algorithm selection, with load dynamics and sensor cost tradeoffs driving architecture decisions.
- Field-Oriented Control:This vector control method decouples torque and flux components for dynamic response in variable-load conditions. Commercial vehicle deployments in China and Germany favor FOC for bus and truck duty cycles where rapid torque adjustment prevents drivetrain stress. Bosch and Continental engineer 800V FOC firmware for European premium platforms.
- Sensorless Control:Elimination of resolver or encoder hardware reduces bill-of-materials costs through back-EMF estimation and observer algorithms. Two-wheeler manufacturers in India and Southeast Asia adopt these architectures aggressively where price sensitivity excludes position sensors. The technology expands fastest in 3-10kW peak power segments.
- PWM Control:Pulse-width modulation provides foundational voltage switching for cost-optimized entry-level controllers.
- Direct Torque Control:Hysteresis-based torque regulation offers rapid dynamic response for high-performance applications.
Field-oriented control anchors established production. Sensorless architectures are climbing the fastest on two-wheeler volume.
End User:
Customer type shapes procurement scale, specification authority, and service lifecycle expectations.
- OEMs:Original equipment manufacturers specify controller platforms during vehicle development, locking in multi-year supply agreements with tier-one inverter suppliers. Passenger vehicle OEMs in Germany, China, and the United States consolidate procurement through battery-pack bundling strategies. Platform-level integration requires ISO 26262 functional safety certification.
- Fleet Operators:Logistics and transit fleets negotiate direct controller procurement for standardized powertrain stacks across vehicle classes. California drayage operators and Texas last-mile delivery fleets drive volume through single-vendor electrification commitments. Total cost of ownership calculations favor high-efficiency silicon carbide inverters despite premium upfront pricing.
- Aftermarket Providers:Independent service channels develop remanufacturing capabilities for out-of-warranty controller replacement.
- Charging Infrastructures:Stationary power conversion systems integrate motor control derivatives for active rectification and grid stabilization.
OEMs command the established base. Fleet operators are gaining share fastest through direct procurement consolidation.
Application:
Volume scale and performance requirements create distinct controller specification bands across mobility segments.
- Passenger Vehicles:150-300kW peak power controllers with 800V silicon carbide switching dominate premium platform development. European and Chinese OEMs freeze architectures around 400V or 800V rails, with the higher voltage tier expanding for fast-charging compatibility. IP67 sealing and ASIL-D functional safety are mandatory.
- Commercial Vehicles:Bus and truck applications demand 350kW+ continuous ratings with liquid cooling and field-oriented control for gradeability. European urban transit electrification and Chinese heavy-duty logistics drive procurement concentration. Duty cycles with frequent stop-start operation prioritize thermal management robustness.
- Two-Wheelers:Cost-optimized 3-15kW controllers with sensorless control and air cooling address mass-market electrification.
- Industrial Applications:Material handling and off-highway equipment adapt automotive-derived controllers for sealed, high-vibration environments.
Passenger vehicles command the established base. Commercial vehicles show the steepest expansion trajectory on fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through GB/T efficiency mandates that foreign suppliers must satisfy via local joint ventures. Controller procurement concentrates where battery gigafactories cluster, pulling assembly inland to minimize logistics friction. The EPA and NHTSA in the United States tighten fleet-average emissions benchmarks that OEMs meet through expanded EV powertrain procurement.
China
Jiangsu and Zhejiang provinces drive controller demand through battery gigafactory clustering in the Yangtze River Delta. MIIT GB/T standards mandate domestic efficiency certifications that require localized thermal cycling test data. Suzhou and Ningbo facilities now host transferred validation engineering from European suppliers seeking platform approval.
United States
California drayage operators and Texas last-mile delivery fleets consolidate procurement through single-vendor powertrain standardization. EPA tailpipe standards and NHTSA CAFE rules tighten fleet-average emissions benchmarks across light-duty and commercial segments. Detroit engineering centers coordinate 800-volt platform development with tier-one inverter suppliers.
Germany
Stuttgart engineering bases sustain high-voltage inverter R&D for European OEM platforms. EU Green Deal and F-Gas Regulation accelerate refrigerant system electrification that shares power electronics with thermal management modules. Bavaria and Baden-Württemberg host concentrated development of silicon carbide module designs.
Japan
METI industrial policy supports wide-bandgap semiconductor adoption for next-generation traction applications. Sensorless control architectures gain traction in cost-sensitive two-wheeler segments where resolver hardware elimination reduces bill-of-materials costs. Tokyo and Nagoya engineering centers focus on embedded AI torque prediction integration.
South Korea
Seoul Capital Area OEMs procure 800-volt silicon carbide controllers for premium passenger platforms with fast-charging compatibility. Domestic battery manufacturers bundle controller supply with cell sourcing through multi-year platform contracts. Busan-Ulsan industrial corridor supports heavy-duty commercial vehicle electrification programs.
Electric Vehicle Motor Control Unit Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around tier-one automotive suppliers with captive semiconductor relationships and emerging domestic champions with backward integration into battery systems. Three archetypes dominate: integrated powertrain conglomerates, captive vertical specialists, and pure-play inverter engineering houses. Competitive moves center on wafer allocation contract renegotiation and multi-year platform bundling with fleet operators.
Among integrated powertrain conglomerates, Denso, Bosch, and Continental AG exemplify the premium-tier vector through established 800-volt silicon carbide development pipelines. BYD occupies a distinct position as a captive vertical specialist with in-house controller production aligned to its blade battery architecture. These anchors represent divergent sourcing strategies: external procurement dependency versus upstream control over critical power electronics.
| Leading Market Players |
|---|
| Denso |
| ZF |
| BYD |
| Hitachi Astemo |
| BorgWarner |
| Bosch |
| Tesla |
| Inovance |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer undercapacity across East Asian foundry networks is compressing controller production timelines and elevating pricing power for substrate holders. This utilization squeeze forces tier-one suppliers to renegotiate long-term allocation contracts while passing input cost premiums downstream to OEM procurement teams.
Pricing Analysis
Geographic price spreads widen between European premium platforms and Asian mass-market controllers as silicon carbide module costs diverge. Three-tier pricing structure across premium, standard, and economy levels separates 800V SiC inverters from 400V IGBT units and entry-level sensorless architectures. Price differentiation hinges on certification grade under China's GB/T standards and volume scale across fleet procurement bundles. Pricing pressure stems from legacy IGBT module obsolescence risk as OEMs freeze 400V architectures. Fleet operators exhibit highest price sensitivity through total cost of ownership calculations, while premium passenger OEMs absorb silicon carbide premiums for fast-charging compatibility.
Supply Chain Analysis
Contract manufacturing concentration sits with Taiwan Semiconductor Manufacturing Company, GlobalFoundries, and domestic Chinese foundries holding captive SiC substrate capacity. Geographic supply concentration centers on China, South Korea, and Germany for controller assembly, with silicon carbide wafer sourcing anchored in Japan and the United States. Raw material dependencies draw from high-purity silicon carbide substrates, copper busbar assemblies, and rare-earth permanent magnets for motor pairing. Single-source vulnerability in 150mm and 200mm SiC wafer supply constrains high-voltage inverter scaling. Distribution runs through tier-one automotive supplier channels, with fleet operators increasingly consolidating direct procurement outside traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through China's GB/T certification requirements creates substantial switching costs for foreign suppliers seeking platform approval.
For Market Incumbents: Pre-empt emerging domestic Chinese champions by transferring validation engineering to Suzhou and Ningbo facilities before GB/T barriers harden further. Lock in multi-year wafer allocation contracts with Taiwan and Japanese substrate suppliers to defend against silicon carbide supply compression. Deepen backward integration into captive semiconductor sourcing to offset foundry pricing power. For New Entrants and Emerging Players: Establish a beachhead in sensorless control architectures for two-wheeler segments where resolver hardware elimination reduces bill-of-materials costs and opens cost-sensitive Asian markets. Target aftermarket controller refurbishment channels in Germany and California where independent service capabilities for out-of-warranty EV fleets remain underdeveloped. Pursue fleet operator direct procurement relationships as traditional tier-one distributor channels face displacement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon carbide module production as 800V platform commitments require dedicated foundry capacity reservations. Long-term viability favors suppliers with captive substrate sourcing agreements and localized certification capabilities. Acquisition target archetype: pure-play inverter engineering houses with GB/T approval pathways and established tier-one OEM relationships. Watch silicon carbide substrate supply allocations as the critical inflection indicator for platform-level controller sourcing viability.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Capacity Reservation | Secures wafer allocation ahead of 800V platform launches at European and Chinese OEMs. |
| GB/T Certification Localization | Enables platform approval through Suzhou and Ningbo validation engineering transfers. |
| Fleet Procurement Bundling | Consolidates multi-year controller supply with battery pack sourcing for California and Texas operators. |
| Sensorless Control Architecture Development | Captures two-wheeler volume through resolver hardware elimination in cost-sensitive Asian markets. |
| Aftermarket Refurbishment Capability Buildout | Addresses out-of-warranty EV fleet replacement demand in Germany and United States service channels. |
Research Methodology
A standing panel of OEM platform engineers, tier-one supplier procurement leads, fleet operations directors, and thermal management specialists provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from MIIT GB/T filings, EPA tailpipe standard dockets, vehicle production databases, and IHS Markit registration data. Bottom-up unit demand modeling triangulated against top-down powertrain electrification forecasts.
Scenario-bracketing framed analytical projections across the modeling period, with low-case assumptions around silicon carbide substrate supply constraints and high-case assumptions around accelerated fleet electrification mandates. Segmentation dimensions modeled included propulsion architecture, voltage platform tier, control algorithm type, and regional production cluster. CAGRs derived from unit shipment trajectories weighted by average selling price evolution across switching technology generations. Forecast inputs incorporated OEM platform launch timelines and foundry capacity commitment disclosures.
Sensitivities concentrate around silicon carbide wafer supply allocations, GB/T certification timeline shifts, and fleet electrification mandate acceleration. Forecasts reflect documented assumptions regarding substrate capacity expansion and regulatory enforcement intensity. Quarterly review of foundry utilization rates and MIIT efficiency threshold announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
UK Solar E-Bike Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
North America Electric Motor Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
Air Motor Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
GCC Electric Motor Market