
 Casted Automotive Components Market | 2026-2036
Casted Automotive Components Market Size, Share, and Industry Trends Forecast 2026-2036
Casted Automotive Components Market Analysis
Electric vehicle OEMs is reorganizing procurement priorities away from traditional engine block castings toward lightweight structural and thermal management components. Nemak leverages its aluminum casting expertise to secure long-term supply agreements with battery-electric vehicle platforms. GF Casting Solutions anchors European production networks through specialized high-pressure die-casting operations for powertrain electrification. Ryobi Limited competes aggressively in Asian markets with integrated machining and finishing capabilities that reduce tier-one supplier complexity.
Casted automotive components are metal parts formed by pouring molten material into molds, typically achieving dimensional tolerances of CT7-CT9 for powertrain applications and requiring post-cast heat treatment to meet fatigue specifications. These components function as structural, thermal, and fluid-management elements across conventional, hybrid, and electric vehicle architectures. Aluminum alloys command the most dynamic expansion within material segments, driven by density reduction targets for electrified platforms. Engine blocks retain substantial volume within product type segments but face plateauing growth as powertrain electrification advances. OEM direct sourcing is reshaping end user segment dynamics, compressing margins for traditional tier-1 intermediaries while rewarding foundries with design-to-cast capabilities.
EPA fuel economy standards and EU F-Gas Regulation shape material selection and process emissions across major production regions, while China's MIIT enforces domestic content ratios that localize casting supply chains. NHTSA crashworthiness requirements and ECE R94/R95 homologation rules dictate wall thickness minima and alloy grade specifications for structural castings. Stakeholders must monitor regulatory divergence between jurisdictions that treat casting emissions as Scope 1 manufacturing liabilities versus embedded carbon in vehicle life-cycle assessments.
Market Dynamics
Powertrain electrification is compressing demand for traditional iron engine castings while simultaneously creating surge requirements for aluminum battery housings and thermal management plates. Foundries face simultaneous portfolio rotation and capacity reallocation pressures.
Growth Catalysts
- EPA Fuel Economy Mandates:Corporate Average Fuel Economy standards force OEMs toward aluminum-intensive designs, pulling foundry investment into high-pressure die-casting capacity for structural EV components.
- China EV Deployment:Domestic battery-electric vehicle brands source cast battery enclosures and motor housings from local supply bases, concentrating demand within MIIT-supervised production networks.
- Aluminum Alloy Substitution:Density reduction targets for electrified platforms accelerate sand-to-die process transitions, with A356 and Silafont alloys replacing gray iron in transmission and suspension applications.
Market Restraints
- Primary Aluminum Price Volatility:LME aluminum price swings and Chinese smelter capacity cuts compress foundry margins on fixed-price OEM contracts.
- Tooling Lead Times:High-pressure die-casting mold fabrication requires 16-24 week cycles, constraining foundry responsiveness to EV platform launch schedules.
- Emissions Compliance Divergence:EU F-Gas Regulation treats casting process emissions as Scope 1 liabilities, while US EPA frameworks emphasize embedded carbon in life-cycle assessments, complicating cross-border production planning.
Strategic Opportunities
- India Domestic Supply Localization:PLI scheme incentives for advanced automotive components attract foundry investment to serve Maruti Suzuki and Tata Motors electrification programs.
- Integrated Cast-Machining Cells:Converging robotics and in-process quality sensing enable near-net-shape production that bypasses tier-one machining intermediaries.
- Closed-Loop Aluminum Recycling:OEMs establish captive scrap return programs with foundries to secure low-carbon primary material under EU Green Deal carbon border adjustment mechanisms.
Industry Challenges
- Die-Casting Simulation Expertise Gap:Foundries lack computational fluid dynamics specialists capable of optimizing gating designs for large-format battery tray castings.
- Heat Treatment Bottleneck Capacity:T7 solution treatment and aging lines require significant furnace investment, creating queue delays for high-strength automotive specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casted Automotive Components Market |
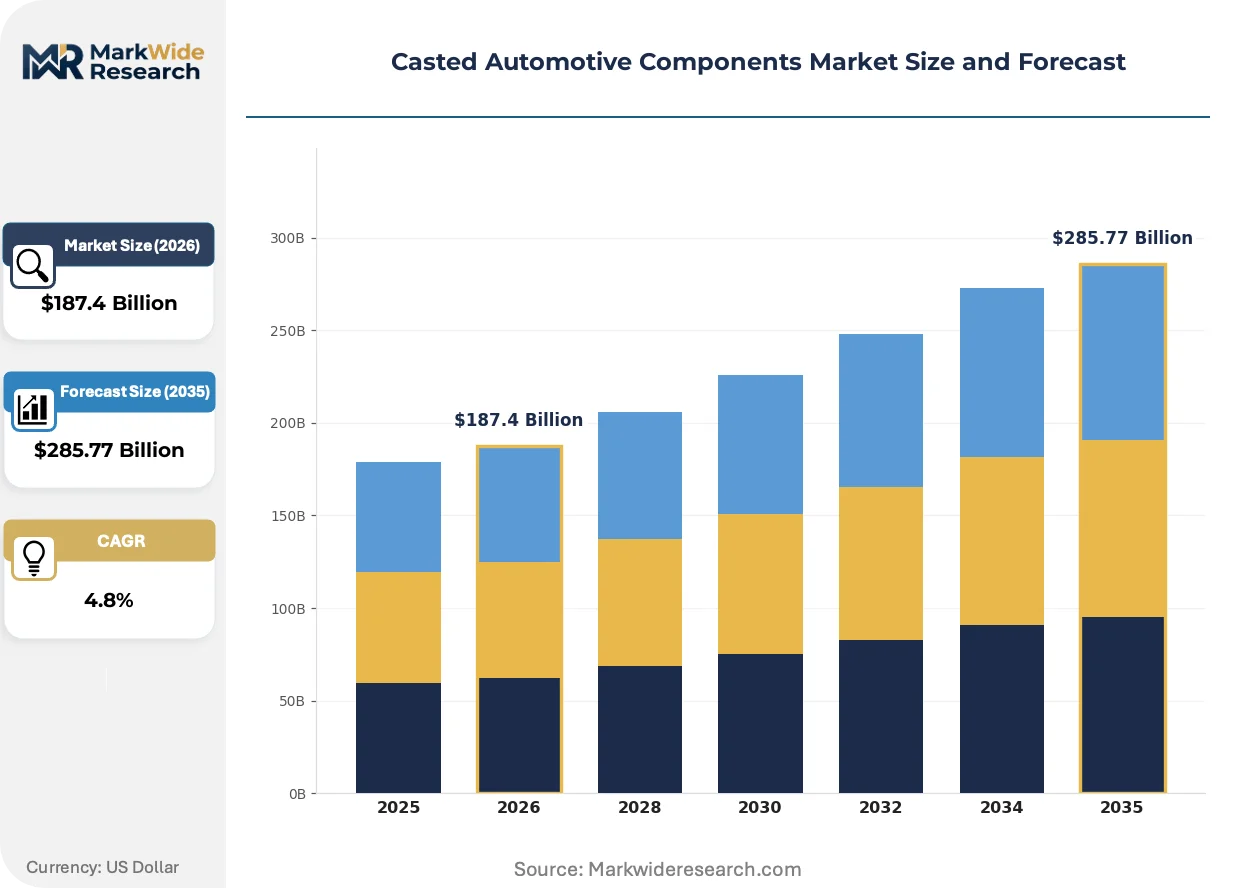
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylinder Heads, Engine Blocks, Gear Casings, Transmission Housings Material: Aluminum Alloys, Ductile Iron, Grey Iron, Magnesium Alloys Manufacturing Stage: Prototype, Production, Post-processing, Finishing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Nemak, Ryobi Limited, Dynacast International, Pace Industries, GF Casting Solutions, Linamar Corporation, Martinrea International, Endurance Technologies, Ahresty Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casted Automotive Components Market Emerging Trajectories
Process digitization and material science advances are reconfiguring casting economics, enabling geometries previously machined from wrought stock to transition directly to as-cast net shapes.
Multi-material vacuum-assisted die casting is displacing conventional high-pressure methods for battery enclosure production. Tesla and BYD specifications now demand 3.0mm wall thickness with 0.5mm tolerances across 1.2-meter spans. This process is displacing welded extrusion assemblies in premium EV architectures, compressing part count and assembly labor.
EU F-Gas Regulation phase-down schedules force foundries to abandon SF6 cover gas in magnesium casting operations by 2030. Industrial consequence includes accelerated adoption of SO2-based melt protection and fluorinated ketone alternatives. German KBA type-approval requirements now mandate process documentation for fluorinated gas alternatives, affecting powertrain casting exports from Central European supply bases.
Direct sourcing contracts are compressing traditional tier-one distributor roles. OEM engineering teams now embed foundry qualification specialists within platform development programs, bypassing intermediate procurement layers. This pattern concentrates most visibly in China, where NIO and Xpeng maintain resident engineers at key aluminum casting suppliers for concurrent design-to-cast development cycles.
Casted Automotive Components Market Segmentation
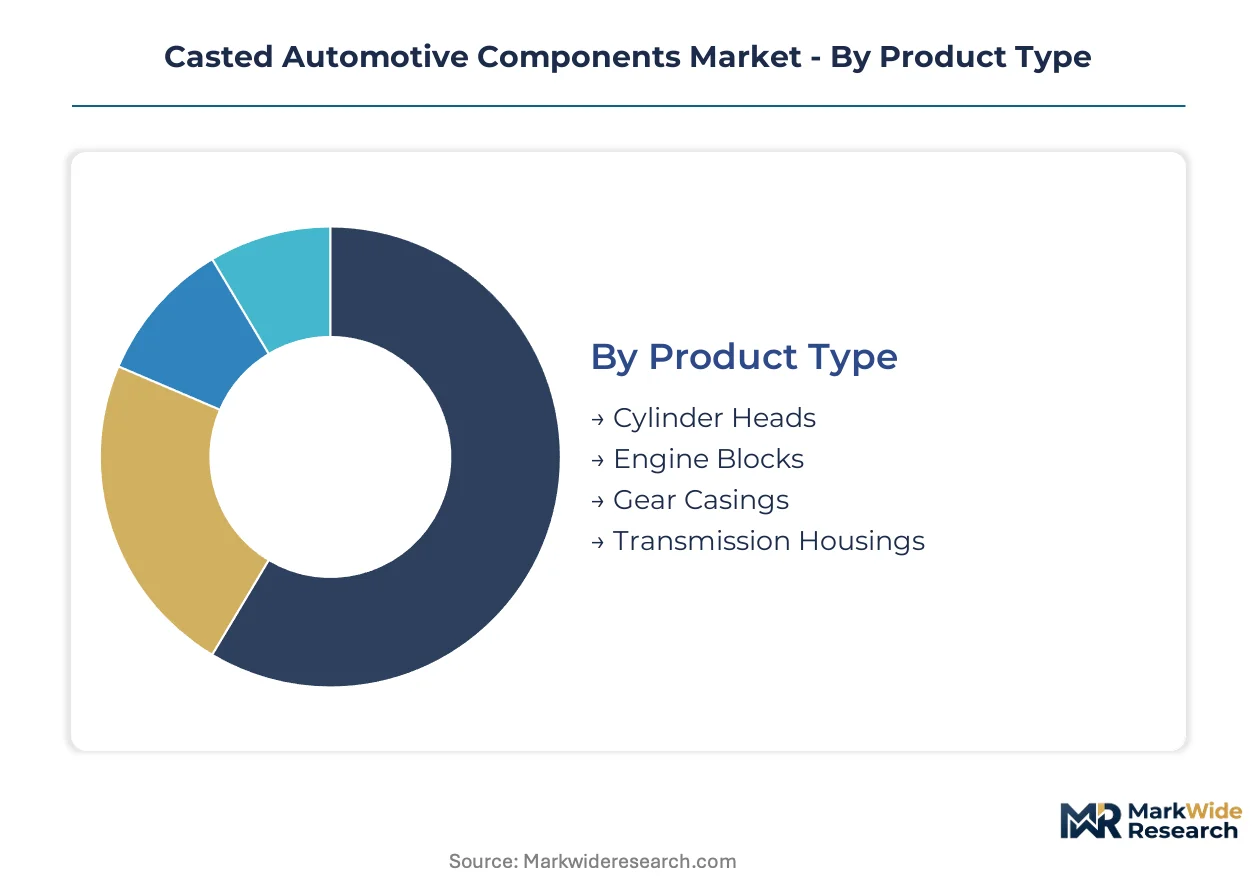
Segmentation reveals where powertrain electrification is compressing legacy demand while opening new value pools. Foundries must track substitution velocity across material and product categories to align capacity investments with platform roadmaps.
Product Type:
Engine block and cylinder head castings face the most acute substitution pressure as battery-electric platforms eliminate internal combustion architectures.
- Engine Blocks:These castings historically anchored foundry revenue through high-volume V6 and inline-4 production programs. Grey iron and aluminum alloy specifications dominate, though electrification is freezing new tooling investment for passenger car applications while commercial vehicle demand provides residual volume.
- Cylinder Heads:Complex water jacket geometries require precision sand casting or low-pressure die-casting expertise. ICE downsizing trends and hybrid range-extender programs sustain selective demand, particularly for turbocharged direct-injection architectures in premium segments.
- Gear Casings:Single-speed reduction gear housings for electric drive units favor high-pressure die-cast aluminum over traditional iron.
- Transmission Housings:Multi-speed e-axle transmissions and integrated electric drive units require cast aluminum structural enclosures with thermal management integration.
Engine blocks retain volume leadership; transmission housings hold the steepest expansion curve.
Material:
Cost tier stratification separates premium aluminum alloys from commodity iron grades, with magnesium occupying a narrow performance niche.
- Aluminum Alloys:A356, Silafont, and proprietary OEM-specific grades enable thin-wall structural castings with T7 heat treatment for strength-to-weight optimization. Tesla, BYD, and NIO specifications for battery enclosures and motor housings concentrate demand in China and Germany.
- Grey Iron:Pearlite-ferrite microstructures deliver cost-effective damping and wear resistance for remaining commercial vehicle engine applications. Chinese foundries supply domestic truck manufacturers while European production contracts.
- Ductile Iron:Nodular graphite structures provide higher tensile strength for suspension and steering knuckles in heavy-duty platforms.
- Magnesium Alloys:AZ91D and AM60B grades serve steering wheels, seat frames, and limited structural applications where mass reduction justifies raw material cost premiums and specialized corrosion protection.
Grey iron retains volume leadership; aluminum alloys hold the steepest expansion curve.
Manufacturing Stage:
Application maturity divides prototype and production volumes, with post-processing intensity determining margin capture.
- Production:High-pressure die-casting cells with automated ladling and real-time shot monitoring dominate aluminum structural component output. Chinese foundries in Ningbo and Chongqing regions scale this capacity for domestic EV platforms.
- Post-processing:T7 solution treatment, quenching, and aging lines represent the critical bottleneck for achieving automotive fatigue specifications. Furnace capacity constraints in European supply bases create queue delays for premium OEM programs.
- Prototype:Sand casting and investment casting methods enable design iteration before hard tooling commitment for new EV platforms.
- Finishing:CNC machining, leak testing, and surface treatment operations increasingly co-locate with casting cells to bypass tier-one intermediaries.
Production retains volume leadership; post-processing holds the steepest expansion curve.
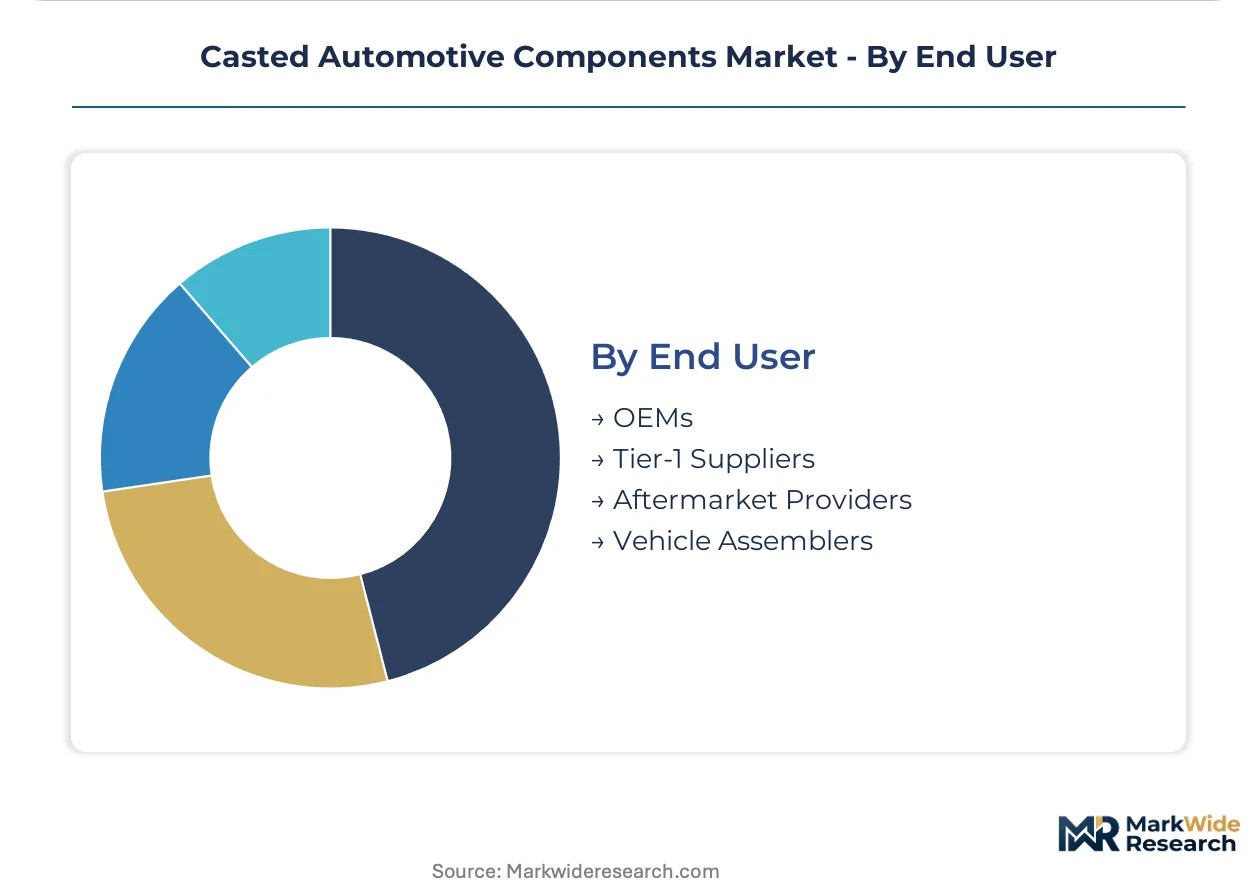
End User:
Customer type concentration is compressing traditional tier-1 supplier margins while rewarding direct foundry-OEM relationships.
- OEMs:Volkswagen, Toyota, and domestic Chinese brands now embed resident engineers at key aluminum casting suppliers for concurrent design-to-cast development. Direct sourcing contracts bypass traditional procurement layers and capture margin previously allocated to tier-1 distributors.
- Tier-1 Suppliers:Continental, ZF, and Bosch casting divisions face margin compression as OEMs internalize design authority and specify process parameters directly.
- Vehicle Assemblers:Contract manufacturers and emerging EV brands without captive foundry capacity rely on qualified supplier bases for structural castings.
- Aftermarket Providers:Remanufactured engine components and replacement housings serve aging ICE fleets, though electrification narrows this addressable market over time.
OEMs retain volume leadership; vehicle assemblers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundries export high-pressure die-cast battery housings to Swedish and Norwegian EV assemblers along a North Sea-Baltic corridor that concentrates premium aluminum casting trade flows.
China
Domestic EV brands NIO, Xpeng, and BYD source battery enclosures and motor housings from Ningbo and Chongqing foundry clusters. MIIT enforces domestic content ratios that localize casting supply chains. Yangtze River Delta facilities scale high-pressure die-casting cells for Tesla Shanghai and local OEM programs.
Germany
High-pressure die-casting operations for powertrain electrification anchor European production networks. EU F-Gas Regulation mandates SF6 phase-out in magnesium casting by 2030. Bavarian supply bases face KBA type-approval documentation requirements for fluorinated gas alternatives affecting powertrain casting exports.
United States
EPA Corporate Average Fuel Economy standards force OEMs toward aluminum-intensive designs, pulling foundry investment into structural EV component capacity. NHTSA crashworthiness requirements dictate wall thickness minima for structural castings. Midwest foundry clusters in Michigan and Ohio retool for transmission housing and battery tray programs.
India
Maruti Suzuki and Tata Motors electrification programs attract foundry investment under PLI scheme incentives for advanced automotive components. BIS certification requirements govern alloy grade specifications for structural applications. Tamil Nadu and Gujarat industrial corridors concentrate new high-pressure die-casting capacity for domestic EV platforms.
Japan
METI carbon neutrality roadmaps accelerate aluminum recycling integration in automotive supply chains. JIS standards govern dimensional tolerances for powertrain castings. Aichi Prefecture foundry clusters maintain precision sand casting expertise for hybrid range-extender cylinder heads in premium segments.
Casted Automotive Components Market Vendor Landscape
Player mix skews toward integrated aluminum specialists with captive machining capabilities. Market structure concentrates around three strategic archetypes: global tier-1 casting divisions with OEM-embedded engineering teams, regional high-volume die-casting specialists serving domestic EV platforms, and diversified metalformers leveraging casting as a vertical extension. Dominant competitive moves include capacity expansion into large-format battery tray casting and strategic partnerships for closed-loop aluminum recycling programs.
Among the integrated specialists, Nemak, Ryobi Limited, and GF Casting Solutions exemplify the archetype of foundries securing long-term supply agreements through design-to-cast capabilities. Nemak occupies a position as a representative of aluminum casting expertise anchored in platform-level partnerships. Ryobi Limited sits within the Asian market vector where integrated machining and finishing capabilities reduce procurement complexity. GF Casting Solutions anchors European production networks through specialized operations for electrification applications.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Limited |
| Dynacast International |
| Pace Industries |
| GF Casting Solutions |
| Linamar Corporation |
| Martinrea International |
| Endurance Technologies |
| Ahresty Corporation |
| Others |
Supply Flow & Price Mechanics
High-pressure die-casting cell utilization rates above 85% in Ningbo and Chongqing foundry clusters compress per-unit fixed costs and establish price floors that smaller European competitors cannot match. This scale concentration enables Chinese suppliers to absorb LME aluminum volatility through volume leverage while OEMs in Germany and the United States face margin compression from fixed-price contract structures.
Pricing Analysis
Next-generation multi-material vacuum-assisted die-casting commands 15-20% premiums over conventional high-pressure methods for battery tray specifications. Three-tier pricing structure across premium OEM-direct contracts, standard tier-one supply agreements, and economy aftermarket replacement tiers reflects design-to-cast capability stratification. Cost compression in standard-tier transmission housings is intensifying because foundries compete for fixed allocation slots on EV platform launches. Tier-one procurement officers at Continental and ZF exhibit highest price sensitivity, while OEM embedded engineering teams prioritize thermal management performance over unit cost.
Supply Chain Analysis
Just-in-time aluminum ingot delivery dominates premium OEM programs, though strategic stockpiling of A356 alloy billets is emerging among European foundries hedging against Chinese smelter capacity cuts. Supply concentrates in China, Germany, and Mexico, with raw material dependencies on primary aluminum from Chinese smelters, silicon metal from Norway and Brazil, and magnesium from Shaanxi province. Single-source vulnerability in large-format die-casting mold fabrication creates queue risks for EV platform launches. Distribution runs through direct OEM engineering relationships that bypass traditional tier-one intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM direct sourcing consolidation compresses tier-one margins while concentrating procurement power among Volkswagen, Toyota, and domestic Chinese EV brands. This buyer-power shift rewards foundries with resident engineering capabilities and penalizes distributors without design-to-cast integration.
For Market Incumbents: Shield core aluminum casting programs through captive T7 heat treatment capacity expansion in Germany and China, insulating against furnace bottlenecks that delay premium OEM qualifications. Deepen backward integration into closed-loop scrap recycling to secure low-carbon material positions under EU Green Deal carbon border adjustments. Aluminum alloy substitution mandates from EPA and EU regulators threaten grey iron legacy revenue, requiring portfolio rotation into battery enclosure and motor housing architectures. For New Entrants and Emerging Players: Differentiate on integrated cast-machining cell capabilities that eliminate tier-one intermediaries for emerging EV assemblers without captive foundry capacity. White-space targets include India's PLI-subsidized supply localization for Maruti Suzuki and Tata Motors electrification programs, plus prototype-to-production services for Chinese EV startups scaling from sand casting to hard tooling. Go-to-market positioning should emphasize concurrent engineering resident teams that mirror NIO and Xpeng supplier development models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foundries with OEM-embedded engineering contracts and long-term platform supply agreements spanning multiple vehicle generations. Long-term viability over the next decade hinges on aluminum recycling integration and large-format battery tray casting expertise rather than legacy engine block capacity. Acquisition targets should prioritize German and Chinese specialists with T7 heat treatment qualifications and SF6-free magnesium process documentation. The signal to watch is OEM qualification timelines for next-generation thermal management plate specifications.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Die-Casting Capacity Expansion | Secures allocation on Tesla, BYD, and NIO battery enclosure programs in China and Germany. |
| Closed-Loop Aluminum Recycling Partnership | Locks in low-carbon primary material supply under EU Green Deal carbon border adjustment mechanisms. |
| Resident Engineering Team Deployment | Enables concurrent design-to-cast development cycles that bypass tier-one procurement layers. |
| SF6-Free Magnesium Process Conversion | Ensures KBA type-approval compliance for EU F-Gas Regulation phase-down by 2030. |
| Integrated Cast-Machining Cell Investment | Eliminates tier-one intermediaries through near-net-shape production with in-process quality sensing. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-one procurement directors, foundry operations managers, and heat treatment specialists. Secondary validation drew from EPA fuel economy filings, EU F-Gas Regulation implementation guidance, MIIT domestic content ratio announcements, and IHS Markit vehicle production databases. Bottom-up capacity assessments across Ningbo, Chongqing, Bavarian, and Michigan foundry clusters were triangulated against top-down OEM sourcing allocation models.
Across the analysis window, forecasts incorporate segmentation by propulsion architecture, material grade tier, and regional production cluster. CAGRs were derived from platform-level content-per-vehicle trajectories for battery enclosures, motor housings, and transmission casings. Industry-specific inputs include LME aluminum price scenario modeling, die-casting mold lead time distributions, and T7 heat treatment furnace capacity utilization curves.
Material uncertainties — primary aluminum price volatility, EV platform launch delays, and regulatory divergence on casting emissions accounting — sit outside the modeled envelope. Forecasts reflect assumptions regarding OEM direct sourcing acceleration and foundry consolidation patterns. Revision becomes warranted when battery-electric vehicle penetration trajectories or carbon border adjustment implementation timelines cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Torque Vectoring Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Drive System Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market