
 Automotive Mobile Accessories Market | 2026-2036
Automotive Mobile Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Mobile Accessories Market Analytics
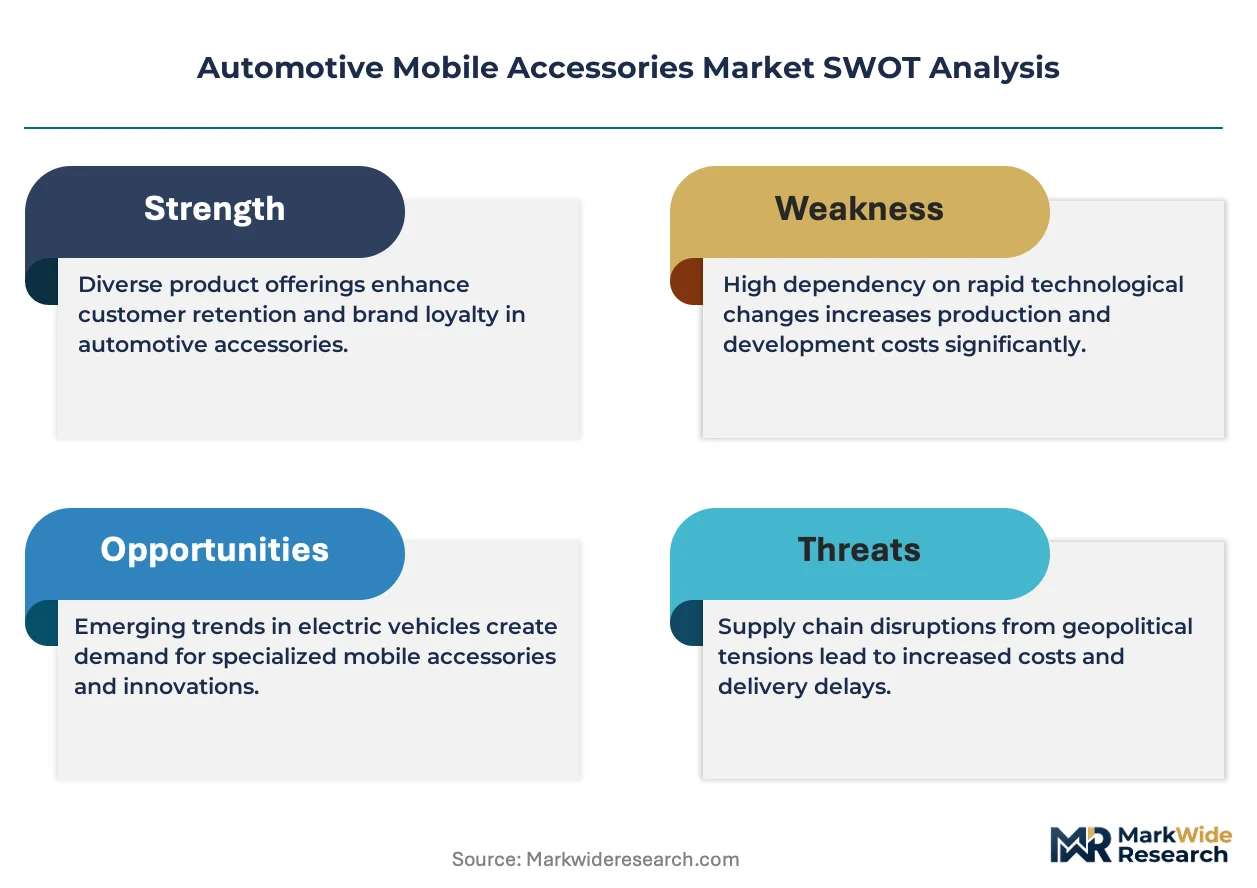
Asset-light leasing models for vehicle electronics is fragmenting competitive barriers in the Automotive Mobile Accessories Market. Belkin International leverages its retail channel control to sustain premium positioning across North American big-box distribution. Anker Innovates anchors its volume strategy through direct-to-consumer pricing and rapid product refresh cycles. Bosch competes on integrated OEM supply relationships that extend its influence into factory-installed charging systems.
Automotive mobile accessories encompass devices that interface with smartphones within vehicle environments, including Qi-compatible charging pads rated at 15W output, suction-cup or vent-clip phone mounts with vibration damping, and dual-lens dash cameras recording at 1080p minimum resolution. These products serve commercial and consumer purposes by enabling hands-free communication, navigation display, and incident documentation while reducing driver distraction. Phone mounts and charging stations lead product type revenue due to universal smartphone compatibility and repeat purchase frequency. Wireless technology within the technology segment captures the fastest expansion as automakers delete USB-A ports from new dashboards. Fleet operators within the end user segment represent the most concentrated margin pool because procurement runs through multi-year service contracts with standardized specifications.
The Federal Communications Commission governs radio frequency emissions from Bluetooth adapters and wireless chargers sold in the United States, while the EU Radio Equipment Directive mandates CE marking and interoperability testing for connected accessories distributed across Europe. China's Ministry of Industry and Information Technology enforces GB standard compliance for wireless charging devices integrated with domestic vehicle platforms. Stakeholders must monitor how regulator divergence on electromagnetic compatibility thresholds shapes product platform architectures and certification cost structures.
Market Dynamics
The deletion of USB-A ports from vehicle dashboards by automakers is compressing replacement cycles for charging accessories and forcing aftermarket suppliers to accelerate Qi 2.0 certification timelines. This single technical mandate is redrawing competitive boundaries between OEM-integrated and aftermarket product categories.
Growth Catalysts
- Fleet Telematics Mandates:Commercial vehicle operators in Germany face KBA compliance requirements for driver behavior monitoring, driving dual-lens dash camera installations across logistics networks.
- Qi 2.0 Standardization:The Wireless Power Consortium's magnetic alignment specification eliminates placement guesswork, reducing product return rates for charging pad manufacturers.
- Bluetooth Low Energy:Hands-free calling protocols embedded in vehicle infotainment systems sustain replacement demand for adapter hardware as smartphone audio architectures evolve.
Market Restraints
- Semiconductor Concentration:Power management ICs for 15W wireless charging rely on foundry capacity concentrated in Taiwan, exposing suppliers to geopolitical supply disruption.
- Electromagnetic Compatibility Testing:Divergent FCC Part 15 and EU Radio Equipment Directive thresholds force dual certification architectures, inflating fixed product development costs.
- Vehicle-Integrated Substitution:Factory-installed inductive charging surfaces in premium vehicle trims capture demand that previously flowed to aftermarket channels.
Strategic Opportunities
- India Fleet Digitization:TRAI's push for connected commercial vehicles under the PLI scheme creates unmet demand for telematics-integrated dash cameras in long-haul trucking.
- MagSafe Convergence:Apple's magnetic ecosystem alignment with Qi 2.0 enables accessory suppliers to serve both iOS and Android user bases with unified hardware platforms.
- Subscription-Attached Hardware:Cloud storage for incident footage bundled with dash camera sales generates recurring revenue streams beyond one-time equipment transactions.
Industry Challenges
- Thermal Engineering Talent:15W wireless charging in enclosed vehicle cabins demands heat dissipation expertise scarce among consumer electronics design teams.
- Multi-Protocol Certification:Simultaneous Bluetooth SIG, Qi, and automotive EMC approvals extend product launch timelines by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Mobile Accessories Market |
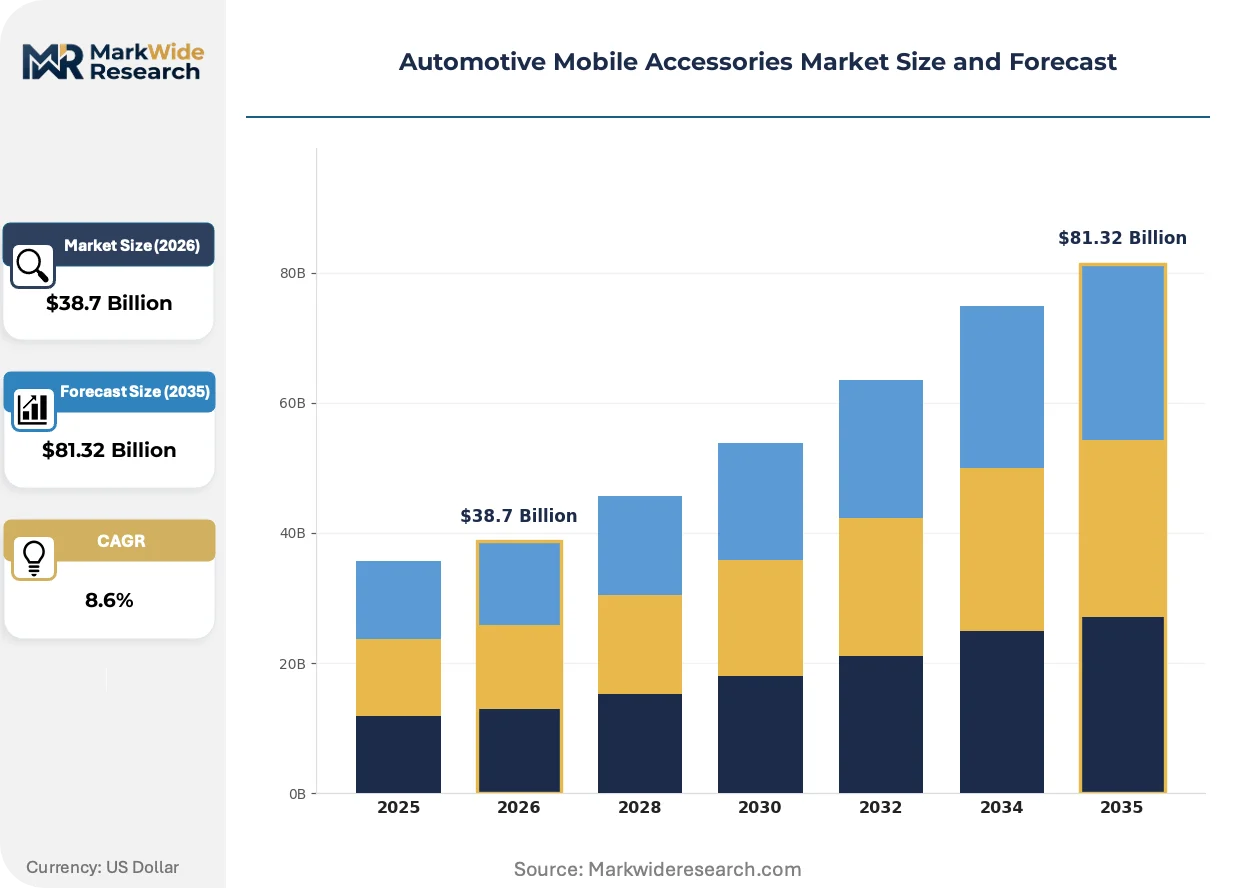
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phone Mounts, Charging Stations, Bluetooth Adapters, Dash Cameras End User: Individual Consumers, Fleet Operators, Dealerships, Aftermarket Providers Technology: Wired, Wireless, Bluetooth, NFC Installation Type: DIY, Professional, Integrated, Removable |
| Companies Covered | Belkin International, Anker Innovations, Apple Inc., Samsung Electronics, Sony Corporation, Bosch, Continental AG, Mountek, Mophie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Mobile Accessories Market Evolving Landscape
Product architectures in this market are converging around magnetic alignment and cloud connectivity, collapsing the distinction between passive mounting hardware and active networked devices. Suppliers must now embed software competencies alongside mechanical engineering.
Qi 2.0's Magnetic Power Profile is rendering obsolete the friction-based phone mounts that dominated aftermarket sales for two decades. Fleet procurement teams at logistics operators are specifying magnetic charging stations exclusively for new vehicle deployments. This transition compresses margins for suppliers lacking magnetic coil winding capabilities while rewarding vertically integrated manufacturers.
China's MIIT enforcement of GB/T 38775 wireless charging interoperability standards is forcing foreign suppliers to establish domestic testing partnerships before market entry. The regulation mandates specific frequency stability thresholds that exceed FCC Part 15 requirements. European and North American suppliers are responding by pre-certifying products at Shenzhen laboratories to avoid customs delays.
Commercial fleet managers are consolidating accessory procurement under multi-year vehicle service contracts rather than ad-hoc driver purchases. This channel shift displaces traditional retail and e-commerce volumes for dash cameras and charging hardware. The concentration is most visible in United States long-haul trucking, where ten largest carriers control a disproportionate share of annual accessory demand.
Automotive Mobile Accessories Market Segmentation
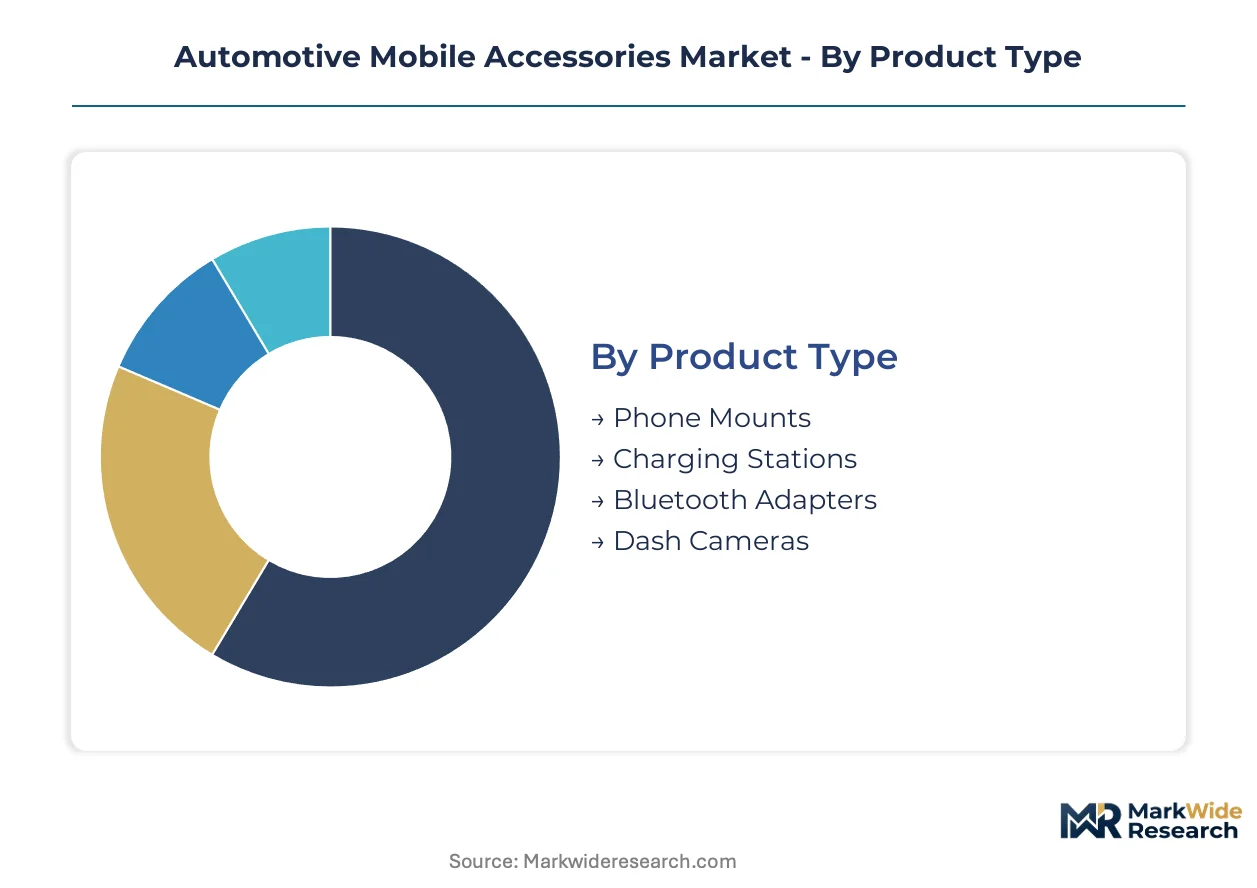
Segmentation in the Automotive Mobile Accessories Market reveals how divergent user requirements reshape product specifications across commercial and consumer channels. Fleet procurement teams prioritize standardized, telematics-integrated hardware, while individual buyers emphasize aesthetic compatibility and rapid installation.
Product Type:
Product categories span passive mounting hardware to active networked devices, each serving distinct driver workflows from navigation display to incident documentation.
- Phone Mounts:Suction-cup or vent-clip designs with vibration damping now incorporate magnetic alignment coils compatible with Qi 2.0 standards. Demand concentrates in Germany and China where connected vehicle penetration drives replacement of friction-based legacy mounts.
- Charging Stations:Qi-compatible pads rated at 15W output dominate aftermarket sales as automakers delete USB-A ports from new dashboards. Fleet operators in the United States specify these exclusively under multi-year service contracts with standardized electromagnetic compatibility certifications.
- Bluetooth Adapters:Hands-free calling hardware sustaining replacement demand as smartphone audio architectures evolve.
- Dash Cameras:Dual-lens units recording at 1080p minimum resolution serving incident documentation requirements.
Established volume favors charging stations; emerging adoption favors dash cameras with cloud-connected firmware.
End User:
Customer archetypes range from price-sensitive retail purchasers to procurement professionals managing standardized fleet deployments.
- Individual Consumers:Retail purchasers prioritizing aesthetic vehicle interior matching and rapid DIY installation. This segment exhibits highest price elasticity and shortest replacement cycles.
- Fleet Operators:Commercial vehicle procurement teams managing logistics networks across Germany face KBA compliance requirements for driver behavior monitoring. These buyers consolidate accessory procurement under multi-year vehicle service contracts with standardized Qi 2.0 and EMC specifications, representing the most concentrated margin pool.
- Dealerships:New vehicle retailers bundling factory-compatible accessories at point of sale.
- Aftermarket Providers:Independent installers serving vehicle owners outside warranty coverage.
Procurement consolidation favors fleet operators; fragmented repeat purchase favors individual consumers.
Technology:
Technical architectures determine certification burden and interoperability requirements across regulatory jurisdictions.
- Wired:USB-C and legacy USB-A connectivity facing obsolescence pressure from dashboard port deletions.
- Wireless:Qi 2.0 magnetic alignment specification eliminates placement guesswork and reduces product return rates. FCC Part 15 and EU Radio Equipment Directive thresholds force dual certification architectures for suppliers targeting multiple markets.
- Bluetooth:Low Energy protocols embedded in vehicle infotainment systems sustaining adapter hardware demand.
- NFC:Near-field pairing for seamless device authentication in premium vehicle trims.
Regulatory compliance cost favors wired legacy; steepest expansion trajectory favors wireless magnetic alignment.
Installation Type:
Installation modality shapes distribution channel economics and customer acquisition costs.
- DIY:Consumer self-installation dominating retail and e-commerce channels with lowest per-unit service overhead.
- Professional:Technician-installed systems for commercial fleet vehicles requiring hardwired power and telematics integration. China's MIIT enforcement of GB/T 38775 standards forces foreign suppliers to establish domestic testing partnerships before serving this channel.
- Integrated:Factory-installed inductive charging surfaces in premium vehicle trims capturing demand that previously flowed to aftermarket channels.
- Removable:Temporary mounting solutions for rental fleet and shared mobility applications.
Margin compression favors integrated OEM supply; channel expansion favors professional installation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for automotive mobile accessories tilt toward manufacturing concentration in East Asia against consumption gravity in Western automotive markets. Germany and the United States run persistent trade deficits in wireless charging hardware, while China maintains surplus positions across Qi-certified component categories.
United States
Fleet telematics mandates from the Federal Motor Carrier Safety Administration drive commercial vehicle accessory installations. FCC Part 15 regulations govern Bluetooth adapter and wireless charger emissions, creating certification bottlenecks for European suppliers. Detroit's automotive supplier corridor hosts integration testing facilities where OEMs validate aftermarket compatibility.
Germany
KBA compliance requirements for driver behavior monitoring compress replacement cycles for dual-lens dash cameras. The EU Radio Equipment Directive mandates CE marking and interoperability testing, adding fixed costs for Asian exporters. Stuttgart's engineering cluster concentrates OEM supply relationships for factory-integrated charging systems.
China
MIIT enforcement of GB/T 38775 wireless charging interoperability standards exceeds FCC thresholds, forcing foreign suppliers into domestic testing partnerships. The dual carbon goals accelerate deletion of USB-A ports from new vehicle dashboards. Shenzhen's electronics manufacturing hub dominates magnetic coil winding capacity for Qi 2.0 hardware.
India
TRAI's connected commercial vehicle push under the PLI scheme generates unmet demand for telematics-integrated dash cameras in long-haul trucking. BIS certification requirements for wireless charging devices create entry barriers for unbranded imports. Tamil Nadu's automotive belt hosts fleet operator procurement consolidation for standardized accessory specifications.
South Korea
MFDS-equivalent automotive EMC standards align with EU thresholds, enabling dual-market product architectures. Government incentives for connected vehicle infrastructure sustain aftermarket demand for Bluetooth Low Energy adapters. Gyeonggi Province's electronics cluster supplies power management ICs for 15W wireless charging pads.
Automotive Mobile Accessories Market Competitive Landscape
On the supply side, the industry is bifurcated between OEM-integrated specialists and aftermarket volume players. Tiered competitive positioning separates premium-brand distributors from direct-to-consumer price competitors. Three archetypes dominate: retail channel controllers, OEM supply integrators, and rapid-refresh consumer electronics specialists. M&A activity concentrates on magnetic alignment technology acquisitions, while geographic expansion targets India's fleet digitization programs.
Within the retail channel control archetype, Belkin International exemplifies premium positioning through big-box distribution relationships. Anker Innovations anchors the direct-to-consumer tier with rapid product refresh capabilities. Bosch occupies a position within the OEM-integrated supply tier, extending influence into factory-installed charging systems through automotive supplier relationships.
| Leading Market Players |
|---|
| Belkin International |
| Anker Innovations |
| Apple Inc. |
| Samsung Electronics |
| Sony Corporation |
| Bosch |
| Continental AG |
| Mountek |
| Mophie Inc. |
| Others |
Value Network & Pricing Analysis
Semiconductor foundry concentration in Taiwan determines both pricing tier spreads and supply chain shape for 15W wireless charging hardware, compressing margins for unbranded suppliers while amplifying premium capture for vertically integrated manufacturers with captive coil winding capabilities.
Pricing Analysis
Fleet operators anchor three-tier pricing structure across premium, standard, and economy levels for Qi 2.0 charging stations, with price differentiation driven by electromagnetic compatibility certification grade and volume scale under multi-year service contracts. Pricing pressure stems from OEM-integrated factory charging surfaces capturing aftermarket demand. Individual consumers exhibit highest price sensitivity through retail channels, while fleet procurement teams prioritize standardized specifications over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for magnetic coil components and power management ICs. Manufacturing concentrates in China, South Korea, and Taiwan for wireless charging hardware, drawing from neodymium magnet feedstock and copper coil raw materials. Distribution runs through big-box retail for consumer channels and direct OEM supply agreements for fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qi 2.0 magnetic alignment convergence with Apple's MagSafe ecosystem creates a platform-economics inflection, collapsing hardware differentiation toward interoperability certification and cloud-connected firmware services.
For Market Incumbents: Build regulatory certification moats through dual FCC Part 15 and EU Radio Equipment Directive pre-approval architectures. Accelerate backward integration into magnetic coil winding capabilities to defend against Shenzhen manufacturing cost advantages. Consolidate fleet procurement relationships under multi-year telematics-integrated service contracts before aftermarket channel fragmentation accelerates. For New Entrants and Emerging Players: Pursue India's TRAI-connected commercial vehicle mandate as the most penetrable geography, where BIS certification barriers filter unbranded competition. Target telematics-integrated dash cameras for long-haul trucking fleets under the PLI scheme. Deploy professional installation partnerships as the primary go-to-market angle to bypass established retail channel control. For Investors and Strategic Acquirers: The market sits at a standardization-consolidation phase that favors magnetic alignment technology specialists with Qi 2.0 certification pipelines. Long-term viability hinges on software-defined service attachment rates beyond hardware transactions. Monitor fleet operator procurement consolidation velocity as the inflection signal for aftermarket channel displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Qi 2.0 Certification Acceleration | Magnetic Power Profile compliance eliminates placement guesswork and reduces return rates for charging pad manufacturers. |
| Fleet Telematics Integration | Hardwired power and cloud connectivity bundles transform transactional hardware sales into recurring service relationships. |
| Magnetic Coil Backward Integration | In-house winding capabilities capture margin compression from Shenzhen manufacturing concentration for coil components. |
| Dual-Market Pre-Certification | Shenzhen laboratory partnerships for GB/T 38775 compliance prevent Chinese customs delays for foreign suppliers. |
| Subscription-Attached Cloud Storage | Incident footage archiving generates recurring revenue streams beyond one-time dash camera equipment transactions. |
Research Methodology
Desk research of regulatory filings, automotive production databases, and customs trade records preceded structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and fleet operator telematics directors. Primary fieldwork combined with secondary validation from FCC equipment authorization databases, EU RAPEX safety alerts, and MIIT GB standard certifications. Bottom-up volume modeling triangulated against top-down automotive accessory spend estimates.
Assumptions held Qi 2.0 adoption velocity and USB-A port deletion rates fixed across the projection horizon, while varying fleet telematics mandate enforcement timing and semiconductor foundry capacity utilization. Segmentation dimensions modeled include product type, end user archetype, wireless versus wired technology architecture, and installation modality. CAGRs derived from regression analysis against vehicle production forecasts and smartphone replacement cycle data, incorporating power management IC pricing indices and magnetic component trade flow volumes.
Sensitivities concentrate around Taiwan foundry geopolitical disruption and divergent electromagnetic compatibility threshold adjustments by FCC or EU regulators. Forecasts reflect assumptions about fleet procurement consolidation velocity and OEM-integrated charging surface penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Drive System Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automotive Metal Market
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Differential Market