
 India Automotive Airfilters Market | 2026-2036
India Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Airfilters Market Foresight
Skilled toolroom labor availability in Pune and Chennai is unwinding as apprenticeship pipelines fail to keep pace with precision-molding demand for synthetic filter housings. Mann+Hummel leverages its captive toolmaking capacity to shorten prototype-to-production cycles for domestic OEMs. Elofic Industries anchors its position through backward integration into non-woven media production near its Faridabad headquarters. Fleetguard Filters Private Limited dominates aftermarket distribution through direct dealer networks serving Ashok Leyland and Tata Motors service channels.
Automotive airfilters are engineered porous media assemblies designed to remove particulate contaminants from intake air streams, with pleated cellulose or melt-blown synthetic layers rated to capture particles down to sub-micron scale for engine protection and cabin air quality. Engine intake filters protect cylinder walls and turbocharger vanes from silica and carbon abrasion, while cabin filters incorporate activated carbon layers to adsorb NOx and hydrocarbon vapors in urban traffic conditions. Engine filters lead volume shipments due to mandatory replacement intervals tied to OEM warranty terms, though cabin filters represent the fastest-expanding margin pool as consumer awareness of PM2.5 exposure rises in Delhi-NCR and Bengaluru. Synthetic media is displacing traditional cellulose in premium applications where extended service life and higher dust-holding capacity justify material cost premiums.
BIS mandates filtration efficiency testing under IS 9478 for engine air cleaners, while the Central Pollution Control Board enforces BS-VI tailpipe standards that indirectly tighten intake air cleanliness requirements to protect aftertreatment systems. The Automotive Research Association of India certifies filter performance for OEM homologation, creating a compliance barrier for unorganized aftermarket suppliers. Stakeholders must monitor how CEA energy-efficiency norms for manufacturing and emerging state-level anti-pollution directives reshape filter replacement frequency and material specifications across India's vehicle parc.
Market Dynamics
BS-VI emission norms are forcing commercial vehicle operators to compress replacement cycles for engine intake filters, as aftertreatment system protection becomes critical to warranty compliance and fleet uptime.
Growth Catalysts
- BS-VI Aftertreatment Protection:Diesel particulate filters and selective catalytic reduction systems demand pristine intake air, mandating higher filtration efficiency standards across heavy-duty vehicle parc.
- PM2.5 Awareness in Urban Centers:Cabin filter upgrades accelerate in Delhi-NCR and Bengaluru as consumer willingness-to-pay rises for activated carbon media blocking NOx and hydrocarbon vapors.
- Synthetic Media Migration:Melt-blown polypropylene layers rated for extended service life are capturing share from traditional cellulose in premium OEM fitments and fleet replacement schedules.
Market Restraints
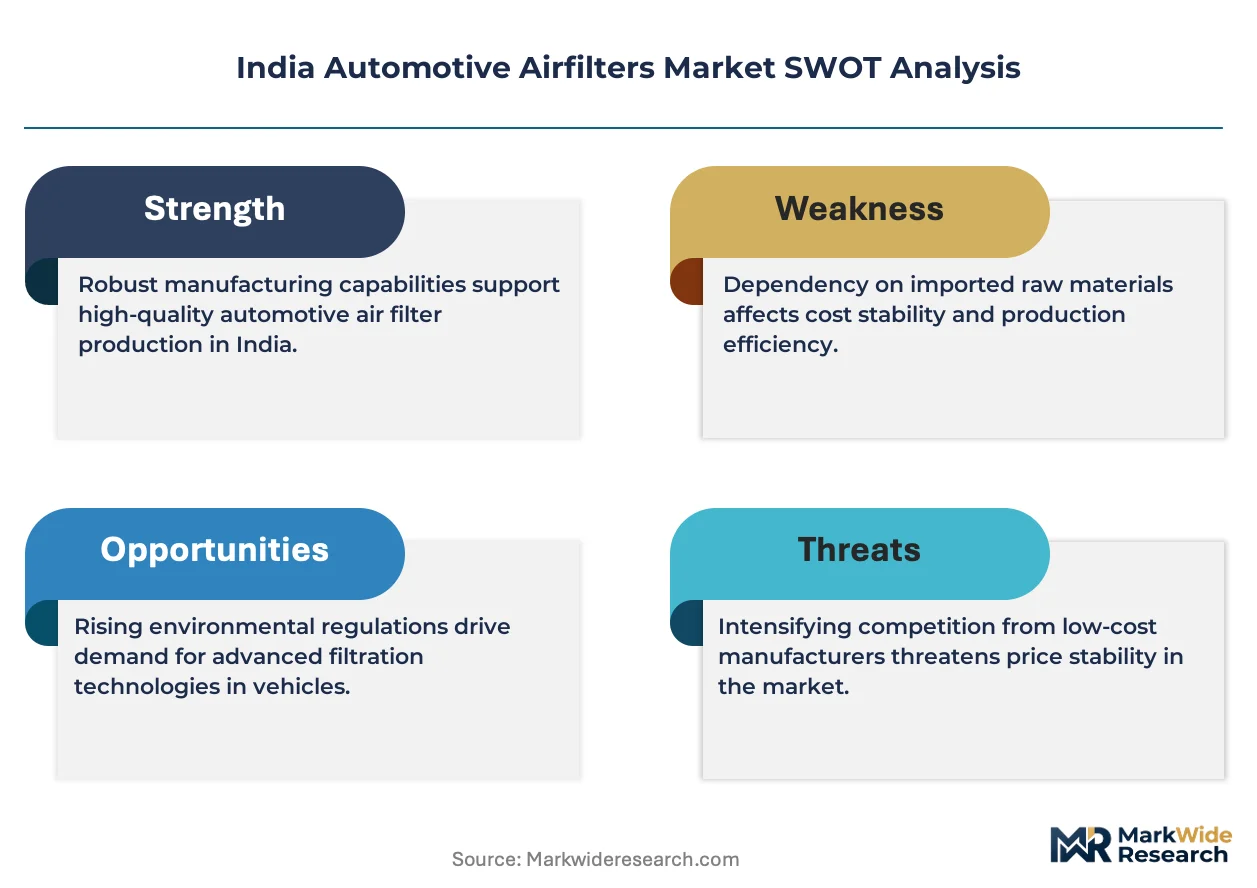
- Polypropylene Resin Volatility:Synthetic filter media production faces margin compression from petrochemical feedstock price swings, constraining domestic non-woven manufacturers' pricing flexibility.
- Toolroom Labor Scarcity:Precision mold-making capacity concentrates in Pune and Chennai, where apprenticeship pipelines fail to replenish skilled technicians for synthetic housing production.
- Unorganized Aftermarket Fragmentation:Non-certified suppliers evading BIS IS 9478 testing requirements capture price-sensitive replacement demand through unregulated distribution channels.
Strategic Opportunities
- State-Level Anti-Pollution Directives:Emerging sub-national regulations in Maharashtra and Tamil Nadu may mandate accelerated cabin filter replacement frequency for commercial fleets operating in air quality non-attainment zones.
- Direct-to-Fleet Digital Procurement:Large logistics operators are consolidating filter purchasing through integrated maintenance platforms, bypassing traditional multi-tier distribution.
- Electrification-Adapted Filtration:Battery thermal management systems and electric motor cooling circuits create demand for specialized low-pressure-drop media in emerging EV platforms.
Industry Challenges
- Homologation Timeline Compression:ARAI certification cycles for new synthetic media formulations lag OEM platform development schedules, delaying supplier qualification for model-year launches.
- Multi-Material Integration Complexity:Combining pleated synthetic layers with activated carbon and non-woven support substrates requires process reengineering at tier-1 converter facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Airfilters Market |
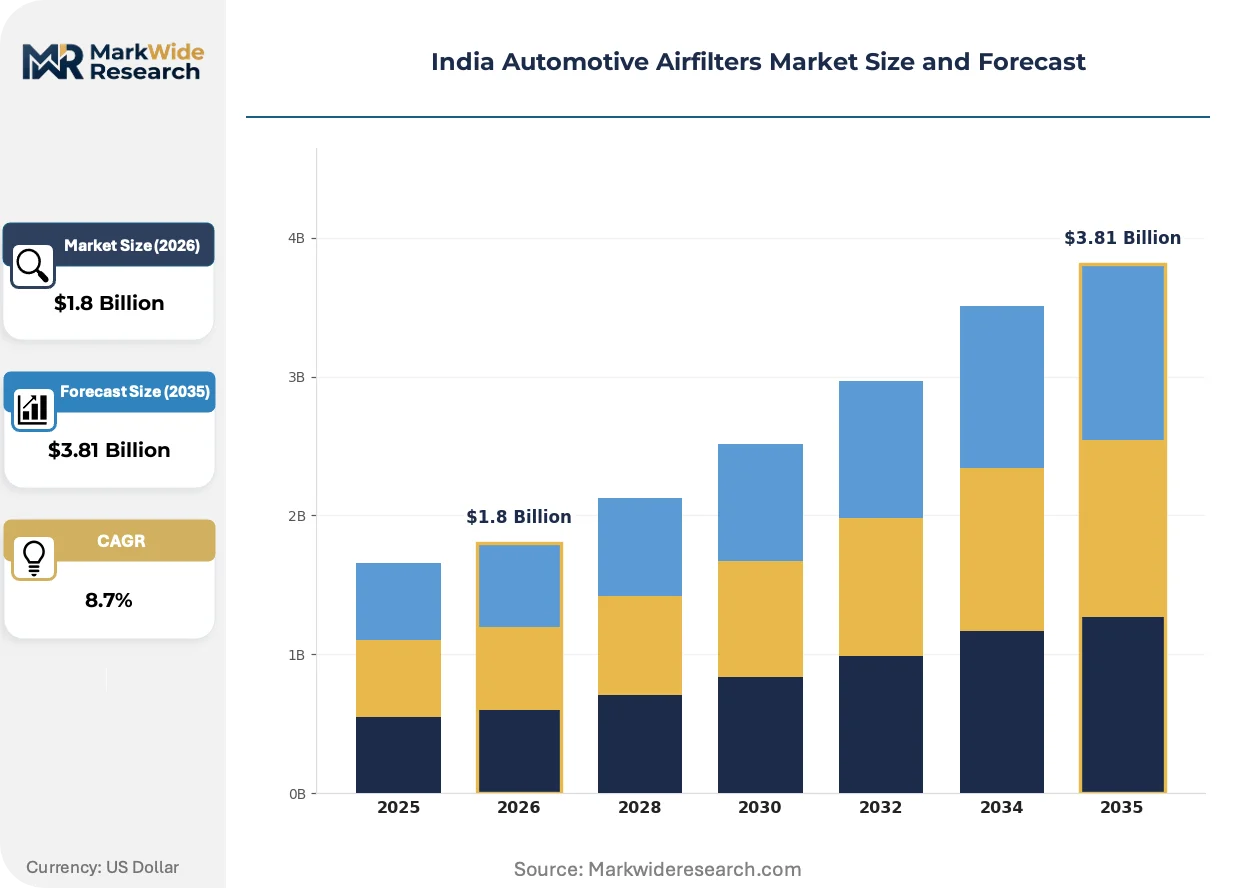
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Cabin Filters, Engine Filters, Fuel Filters, Oil Filters Material: Paper, Foam, Cotton, Synthetic End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Distribution Channel: Retailers, Wholesalers, Online Platforms, Service Centers |
| Companies Covered | Mann+Hummel, MAHLE GmbH, Elofic Industries Limited, Fleetguard Filters Private Limited, Robert Bosch GmbH, Donaldson Company, Inc., Denso Corporation, Freudenberg Filtration Technologies, Sogefi SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Airfilters Market Shifts & Advancements
Synthetic media architectures are fragmenting the competitive landscape as performance differentiation shifts from mechanical filtration efficiency to multi-functional adsorption capabilities and extended service intervals.
Filter media technology is bifurcating into two distinct performance tiers. Cellulose-based pleated paper retains volume in economy replacement segments where cost minimization dominates procurement criteria. Premium OEM channels and quality-focused fleet operators specify melt-blown synthetic composites with nanofiber surface layers, achieving sub-micron particle capture without flow restriction penalties. This technical divergence is compressing mid-tier suppliers unable to bridge both performance and cost positions simultaneously.
BIS IS 9478 efficiency testing protocols are tightening material specifications for engine air cleaner homologation. The Central Pollution Control Board's enforcement of BS-VI tailpipe standards indirectly mandates cleaner intake air to protect diesel oxidation catalysts and diesel particulate filters from silica-induced degradation. Commercial vehicle OEMs in Jamshedpur and Pune assembly corridors now specify synthetic media as standard fitment to meet warranty terms.
Fleet maintenance departments are consolidating filter procurement through integrated service contracts bundling lubricants, filters, and labor. Large road transport operators in Tamil Nadu and Gujarat bypass traditional aftermarket distributors, negotiating direct supply agreements with tier-1 filter manufacturers for scheduled replacement programs. This channel disintermediation pressures independent parts retailers dependent on walk-in replacement demand.
India Automotive Airfilters Market Segmentation
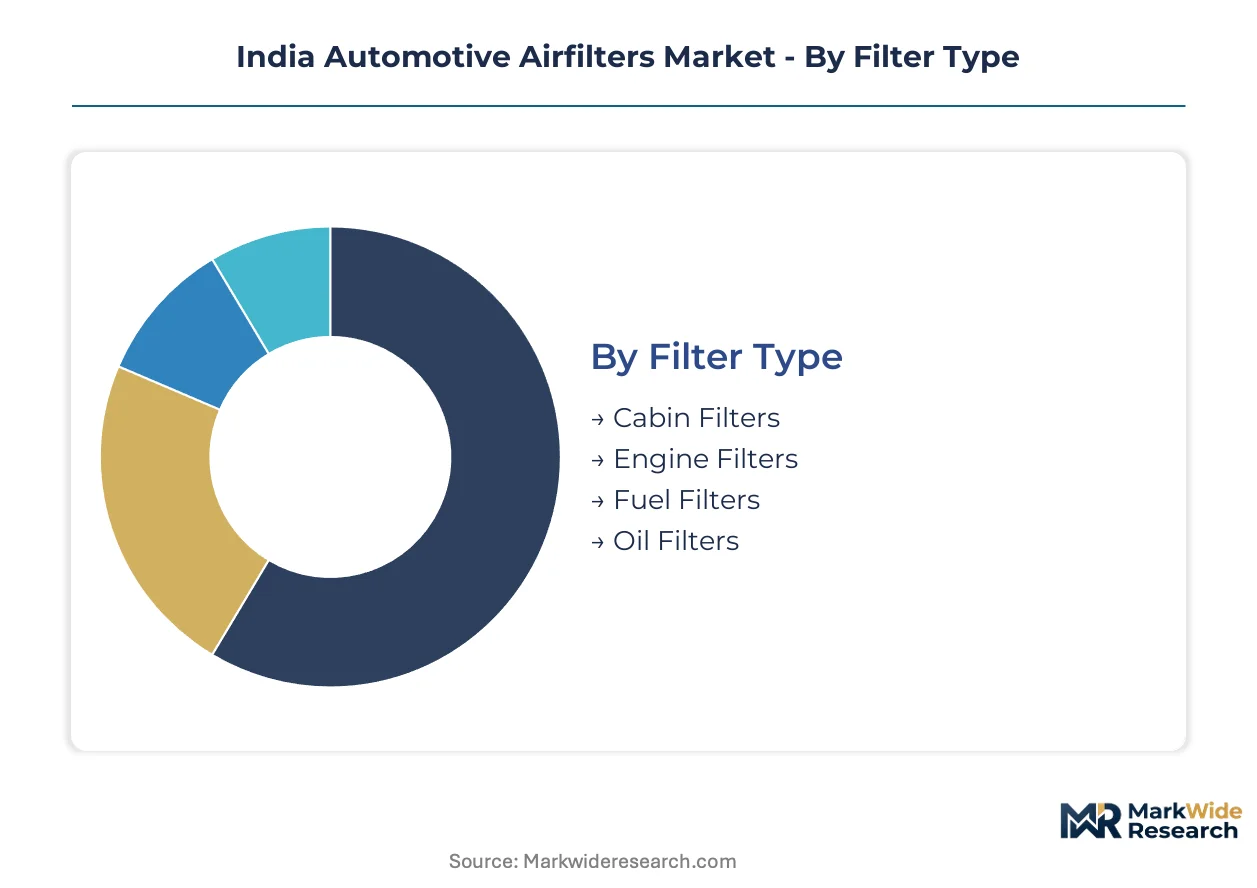
Filter procurement patterns diverge sharply across India's automotive value chain. OEM assembly corridors in Maharashtra and Tamil Nadu drive specification-heavy volume, while aftermarket channels in secondary cities respond to price elasticity and replacement urgency.
Filter Type:
Domestic OEM fitments concentrate engine filter procurement around Jamshedpur and Pune manufacturing clusters, whereas cabin filter demand accelerates in urban aftermarket channels across Delhi-NCR and Bengaluru.
- Engine Filters:Pleated cellulose or synthetic media assemblies protect cylinder walls and turbocharger components from silica abrasion. Demand clusters at Tata Motors and Ashok Leyland assembly plants in Maharashtra and Tamil Nadu, where BS-VI aftertreatment protection mandates compressed replacement cycles.
- Cabin Filters:Multi-layer constructions incorporate activated carbon adsorption layers for NOx and hydrocarbon vapor capture. Replacement frequency accelerates in Delhi-NCR and Bengaluru as PM2.5 exposure awareness reshapes consumer willingness-to-pay for premium media upgrades.
- Fuel Filters:Water-separation media protect high-pressure common-rail injection systems from particulate contamination.
- Oil Filters:Full-flow and bypass configurations extend engine service intervals in commercial fleet applications.
Engine filters hold the largest share; momentum sits with cabin filters.
Material:
Cost-to-performance positioning fragments procurement tiers, with synthetic media commanding premium fitments while cellulose retains economy replacement volumes.
- Synthetic:Melt-blown polypropylene layers with nanofiber surface coatings achieve sub-micron capture efficiency without flow restriction penalties. Mann+Hummel and Elofic Industries deploy synthetic formulations for OEM platforms requiring extended service intervals under BS-VI warranty terms.
- Paper:Traditional cellulose pleated media dominates economy aftermarket channels where price sensitivity overrides performance specifications.
- Foam:Open-cell polyurethane structures serve low-pressure-drop applications in two-wheeler intake systems.
- Cotton:Washable gauze constructions capture niche performance vehicle segments.
Paper retains volume leadership; synthetic formulations are climbing the fastest.
End User:
Fleet consolidation and consumer awareness are reshaping procurement concentration across vehicle categories.
- Commercial Vehicles:Heavy-duty parc operators specify synthetic media to protect diesel oxidation catalysts and diesel particulate filters from silica-induced degradation. Fleetguard Filters Private Limited anchors supply contracts through direct dealer networks serving scheduled replacement programs.
- Passenger Vehicles:Cabin filter upgrades accelerate as urban consumers in Delhi-NCR and Bengaluru prioritize activated carbon media for in-cabin air quality.
- Two-Wheelers:Foam and cellulose configurations dominate high-volume, cost-constrained replacement cycles.
- Heavy-Duty Vehicles:Mining and construction equipment demand high-dust-holding-capacity media for severe-service operating environments.
Commercial vehicles hold the largest share; passenger vehicles are gaining share fastest.
Distribution Channel:
Channel disintermediation is compressing traditional multi-tier distribution as fleet operators consolidate procurement through integrated platforms.
- Service Centers:Authorized outlets for Tata Motors and Ashok Leyland capture warranty-compliant replacement demand with OEM-specified synthetic media. Direct dealer networks dominate commercial vehicle aftermarket volumes through bundled maintenance contracts.
- Online Platforms:Digital procurement channels emerge as large logistics operators bypass traditional distributors for scheduled filter replacement programs.
- Retailers:Independent parts stores serve walk-in replacement demand in secondary cities.
- Wholesalers:Regional distributors aggregate volume for tier-2 and tier-3 city penetration.
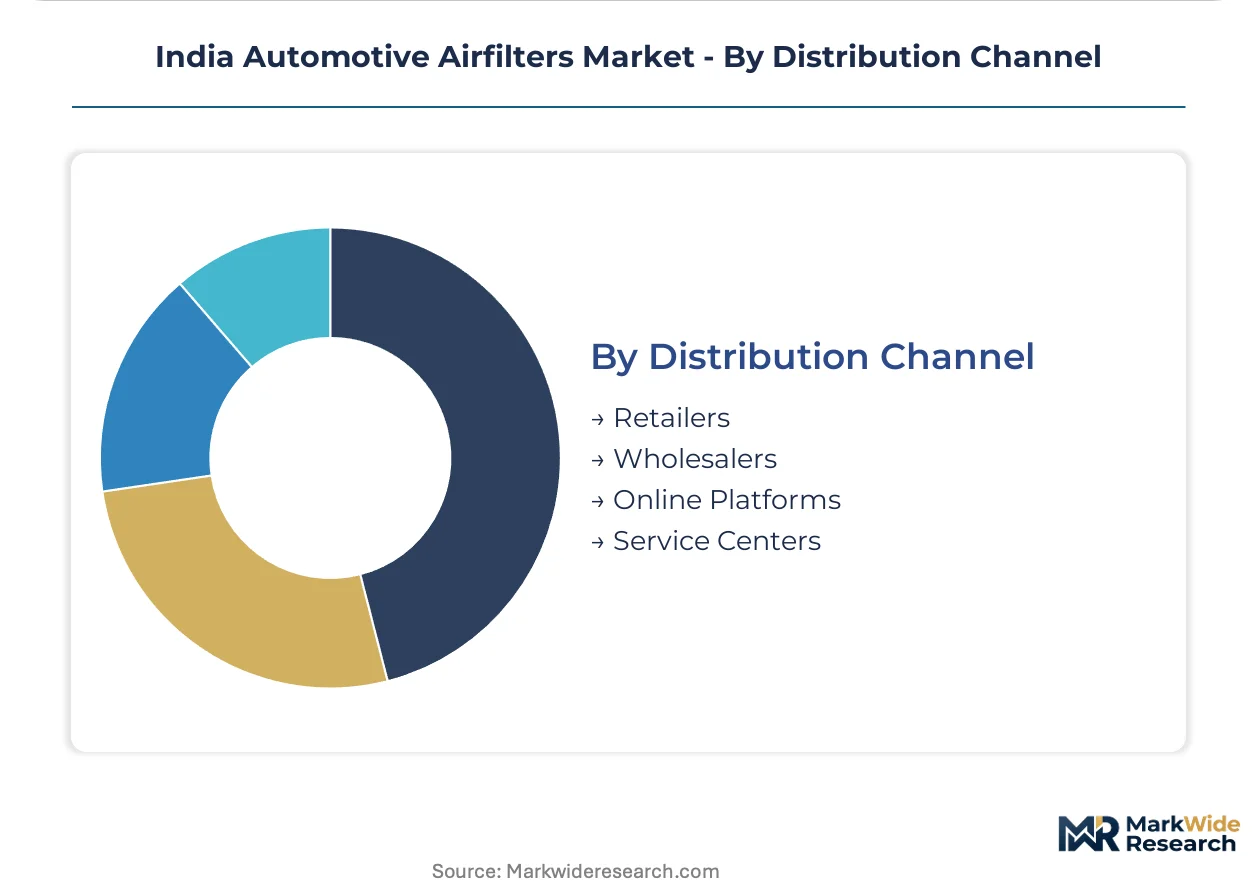
Service centers hold the largest share; online platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification under IS 9478 anchors procurement standards across Indian states, with Maharashtra and Tamil Nadu commanding the dominant share of OEM assembly corridor demand for engine and cabin filter specifications.
Maharashtra
Tata Motors and Ashok Leyland assembly plants in Pune and Jamshedpur corridor drive synthetic media procurement for BS-VI aftertreatment protection. BIS mandates filtration efficiency testing that compresses supplier qualification timelines for domestic manufacturers. Precision-molding capacity concentrates in Pune toolrooms where apprenticeship pipelines fail to replenish skilled technicians.
Tamil Nadu
Commercial vehicle OEM clusters and tier-1 supplier networks anchor engine filter volume shipments for fleet replacement programs. Central Pollution Control Board enforcement of BS-VI tailpipe standards indirectly tightens intake air cleanliness requirements for diesel oxidation catalyst protection. Chennai toolroom labor scarcity constrains prototype-to-production cycles for synthetic housing manufacturers.
Delhi-NCR
PM2.5 exposure awareness accelerates cabin filter upgrades with activated carbon media for NOx and hydrocarbon vapor capture. State-level anti-pollution directives in the National Capital Region may mandate accelerated replacement frequency for commercial fleets. Aftermarket demand concentrates in urban service centers bypassing traditional multi-tier distribution channels.
Karnataka
Bengaluru passenger vehicle parc generates premium cabin filter demand as consumer willingness-to-pay rises for multi-layer media constructions. CEA energy-efficiency norms for manufacturing reshape material specifications at tier-1 converter facilities. Fleet operators in the state consolidate procurement through integrated maintenance platforms for scheduled replacement programs.
Haryana
Elofic Industries anchors non-woven media production near Faridabad headquarters through backward integration into synthetic substrate supply. BIS certification requirements push domestic manufacturers toward material upgrades that displace traditional cellulose in premium applications. Industrial filter fabrication clusters in the National Capital Region serve aftermarket channels across North Indian secondary cities.
India Automotive Airfilters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure bifurcating between captive OEM suppliers and independent aftermarket distributors. The competitive terrain fragments across three strategic archetypes: multinational technology licensors with captive toolmaking capacity, domestic vertically integrated media producers, and fleet-focused direct distribution specialists. Capacity expansion and synthetic media formulation licensing represent the dominant competitive moves as BS-VI compliance compresses replacement cycles.
Among the integrated multinational tier, Mann+Hummel GmbH and MAHLE GmbH exemplify archetypes combining captive toolroom capacity with synthetic media expertise for OEM platform qualification. Elofic Industries Limited occupies a position within the domestic backward-integrated specialist tier, while Fleetguard Filters Private Limited anchors the fleet-direct distribution archetype through dealer network penetration. These three company types represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Mann+Hummel |
| MAHLE GmbH |
| Elofic Industries Limited |
| Fleetguard Filters Private Limited |
| Robert Bosch GmbH |
| Donaldson Company, Inc. |
| Denso Corporation |
| Freudenberg Filtration Technologies |
| Sogefi SpA |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between synthetic media manufacturers and Maharashtra-based OEM assembly plants lock in polypropylene resin supply access while stabilizing unit price visibility across multi-year replacement cycles. These arrangements insulate tier-1 suppliers from petrochemical feedstock volatility that otherwise compresses margin flexibility in spot procurement scenarios.
Pricing Analysis
Price spreads between Delhi-NCR aftermarket channels and Tamil Nadu OEM corridors reflect logistics cost differentials and certification-grade stratification. Three-tier pricing structure across premium synthetic, standard cellulose, and economy unbranded levels segments buyer willingness-to-pay. Pricing pressure stems from unorganized aftermarket suppliers evading BIS IS 9478 testing requirements. Fleet operators show lowest price sensitivity due to warranty compliance mandates, while independent retailers in secondary cities face highest elasticity.
Supply Chain Analysis
Just-in-time inventory protocols dominate OEM assembly corridors in Pune and Chennai, where toolroom labor scarcity forces strategic stockpiling of precision-molded synthetic housings. Polypropylene resin supply concentrates in Saudi Arabia, South Korea, and Singapore. Domestic non-woven media production draws from melt-blown equipment imports and petrochemical feedstock. Single-source vulnerability sits with specialized nanofiber coating technology licensors. Distribution runs through direct dealer networks serving scheduled fleet replacement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as electrification-adapted filtration for battery thermal management threatens to displace traditional engine intake filter volumes across India's vehicle parc.
For Market Incumbents: Compound captive toolmaking capacity in Pune and Chennai to compress prototype-to-production cycles for domestic OEM platform qualification. Deepen backward integration into non-woven media production to offset polypropylene resin volatility. Prioritize ARAI certification pipeline investments to outpace homologation timeline compression from unorganized competitors. For New Entrants and Emerging Players: Lead with electrification-adapted low-pressure-drop media formulations targeting emerging EV platform thermal management circuits. White-space concentrates in Karnataka and Tamil Nadu battery assembly corridors where incumbent filtration suppliers lack specialized cooling circuit expertise. Pursue direct-to-fleet digital procurement partnerships with large logistics operators consolidating scheduled replacement programs. For Investors and Strategic Acquirers: Fleet-direct distribution specialists with captive dealer network penetration represent the most defensible acquisition archetype as channel disintermediation accelerates. Long-term viability hinges on synthetic media formulation licensing revenue streams persisting through propulsion technology transitions. Watch battery electric vehicle production share inflection as signal for traditional engine filter demand trajectory revision.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Media Formulation Licensing | Mann+Hummel and Elofic Industries monetize proprietary melt-blown nanofiber expertise through tier-2 converter partnerships. |
| Backward Integration into Non-Woven Production | Elofic Industries anchors margin control through captive polypropylene substrate manufacturing near Faridabad headquarters. |
| Direct-to-Fleet Digital Platform Development | Large Tamil Nadu and Gujarat logistics operators bypass traditional distribution through integrated maintenance procurement systems. |
| Electrification-Adapted Filtration R&D | Battery thermal management and motor cooling circuits create specialized low-pressure-drop media demand in emerging EV platforms. |
| ARAI Certification Pipeline Investment | Accelerated homologation timelines compress supplier qualification windows for BS-VI-compliant synthetic media formulations. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier-1 supplier production schedules anchors the qualitative findings in this study. Primary interviews with procurement directors at Tata Motors and Ashok Leyland, aftermarket distribution heads at Fleetguard Filters, toolroom supervisors in Pune precision-molding facilities, and BIS certification auditors combined with secondary validation from ARAI homologation records, Central Pollution Control Board enforcement bulletins, and CEA energy-efficiency manufacturing disclosures. Bottom-up volume estimates from state-level vehicle parc data and top-down value projections from OEM supply contract analysis were triangulated to constrain forecast variance.
Sensitivity analysis around polypropylene resin price trajectories and BS-VI replacement cycle compression rates tested forecast robustness across the projection horizon. Segmentation dimensions modeled include filter type, material composition, end-user vehicle category, and distribution channel structure, with additional disaggregation by regional OEM assembly corridor concentration. CAGRs were derived from compound growth path calibration against historical replacement frequency trends and emerging electrification penetration assumptions. Industry-specific inputs encompassed fleet operator maintenance contract bundling patterns and state-level anti-pollution directive implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained BS-VI enforcement intensity and synthetic media cost parity achievement would require recalibration. Forecasts reflect assumptions regarding BIS certification barrier persistence and petrochemical feedstock supply continuity. Revision becomes warranted when battery electric vehicle production share crosses thresholds that materially compress internal combustion engine filter addressable market scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Off-Highway Actuators Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Global Automotive Water Separation Systems Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Glass Market
Automotive Components
Automotive Axle Market