
 ASEAN Domestic Courier Market | 2026-2036
ASEAN Domestic Courier Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Domestic Courier Market Insights
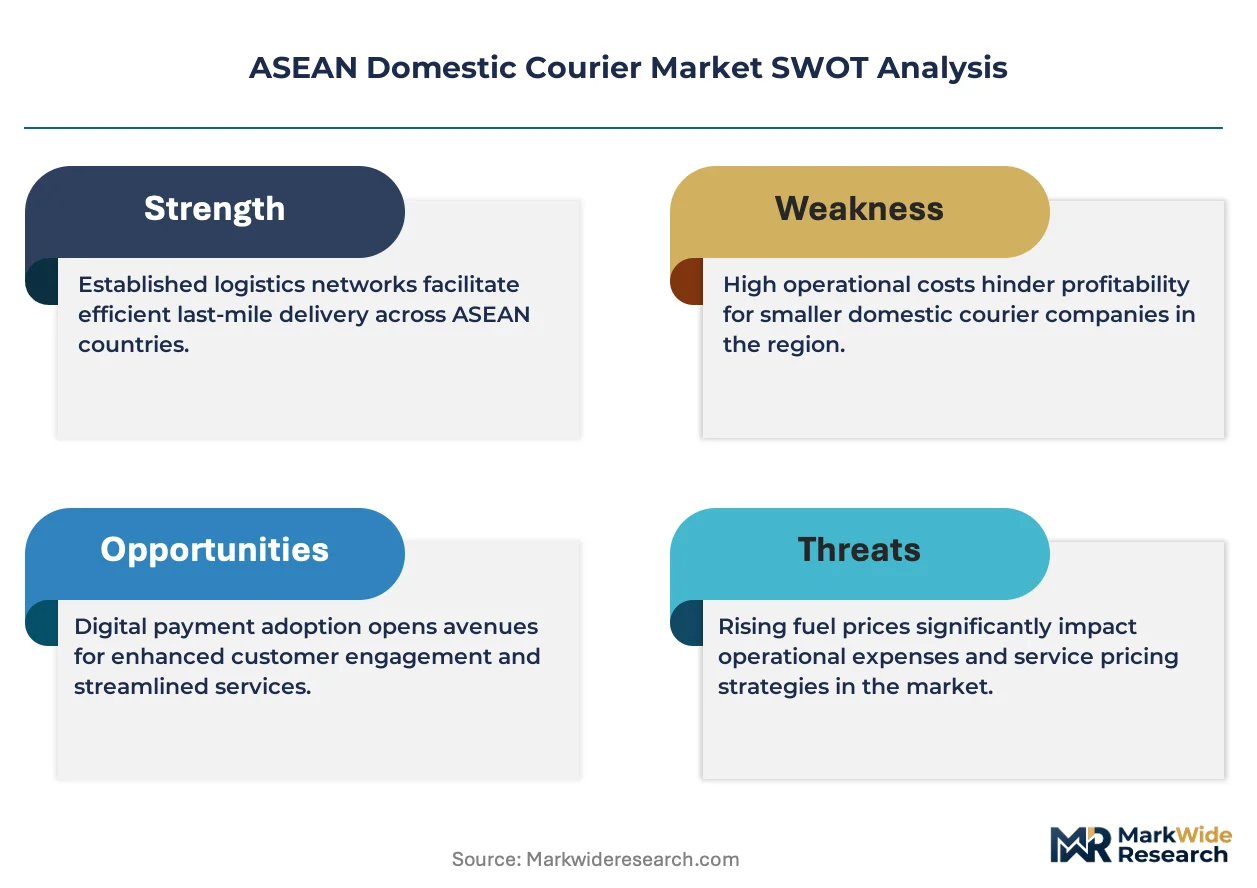
SME merchants is rotating toward platform-integrated logistics, displacing traditional wholesale distributors as the primary volume generators. J&T Express leverages its automated sorting infrastructure across Indonesian hubs. Ninja Van sustains dense last-mile networks in Vietnamese secondary cities. DHL Group anchors premium B2B contract logistics through temperature-controlled capabilities.
ASEAN domestic courier services encompass parcel collection, transit, and delivery operations within single-country boundaries, utilizing hub-and-spoke networks with real-time tracking protocols and electronic proof-of-delivery systems. These services enable inventory velocity for retailers, manufacturers, and digital platforms requiring predictable transit windows. Same-day delivery commands premium positioning in metro corridors where consumer patience compresses. Scheduled pickup services capture recurring B2B accounts with predictable volume profiles. Document shipping retains stable margins despite slower expansion relative to parcel growth.
Indonesia's Ministry of Communication and Informatics, Thailand's Electronic Transactions Development Agency, and Vietnam's Ministry of Industry and Trade shape digital commerce logistics through data localization rules and cross-border payment integration mandates. These frameworks elevate compliance costs for foreign operators while privileging domestically licensed networks. Stakeholders must monitor regulatory divergence across member states as ASEAN economic integration advances unevenly.
Market Dynamics
Platform-integrated logistics is compressing traditional wholesale distribution channels across Southeast Asian e-commerce corridors, forcing courier networks to reconfigure hub-and-spoke infrastructure around marketplace fulfillment requirements rather than conventional retail distribution patterns.
Growth Catalysts
- Indonesia's data localization mandates:Domestic licensing requirements under Ministry of Communication and Informatics rules privilege locally established networks, accelerating foreign operator partnerships with Indonesian license holders.
- Secondary city fulfillment:Vietnamese provincial hubs outside Ho Chi Minh City and Hanoi are generating parcel density that justifies dedicated sorting infrastructure and contracted fleet expansion.
- Cross-border payment integration:Thailand's Electronic Transactions Development Agency frameworks enable seamless settlement for marketplace sellers, reducing friction in domestic courier procurement.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations across ASEAN member states compress margins on long-haul trunk routes between provincial hubs and metro sorting centers.
- License concentration:Foreign operators face structural barriers entering markets with restricted postal licenses, particularly where national postal incumbents retain last-mile exclusivity.
- Address standardization gaps:Informal addressing systems in Indonesian outer islands and Vietnamese rural districts limit automated sorting accuracy and drive manual processing costs.
Strategic Opportunities
- Philippine archipelago penetration:Underdeveloped inter-island courier networks beyond Luzon present white space for hub-and-spoke investments targeting Visayas and Mindanao e-commerce growth.
- Temperature-controlled B2B:Pharmaceutical and fresh produce logistics requirements in Vietnam and Thailand exceed current specialized fleet capacity.
- Scheduled pickup automation:Recurring B2B account management through API-integrated booking systems displaces phone-based dispatch in Malaysian manufacturing corridors.
Industry Challenges
- Sortation technician scarcity:Automated hub operations require maintenance skills exceeding current vocational training output in Indonesian logistics labor markets.
- Legacy fleet electrification:Capital intensity of two-wheeler and light commercial vehicle replacement programs strains mid-tier operator balance sheets.
- Interoperability standards:Divergent electronic proof-of-delivery protocols across member states complicate cross-border network integration despite domestic operational efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Domestic Courier Market |
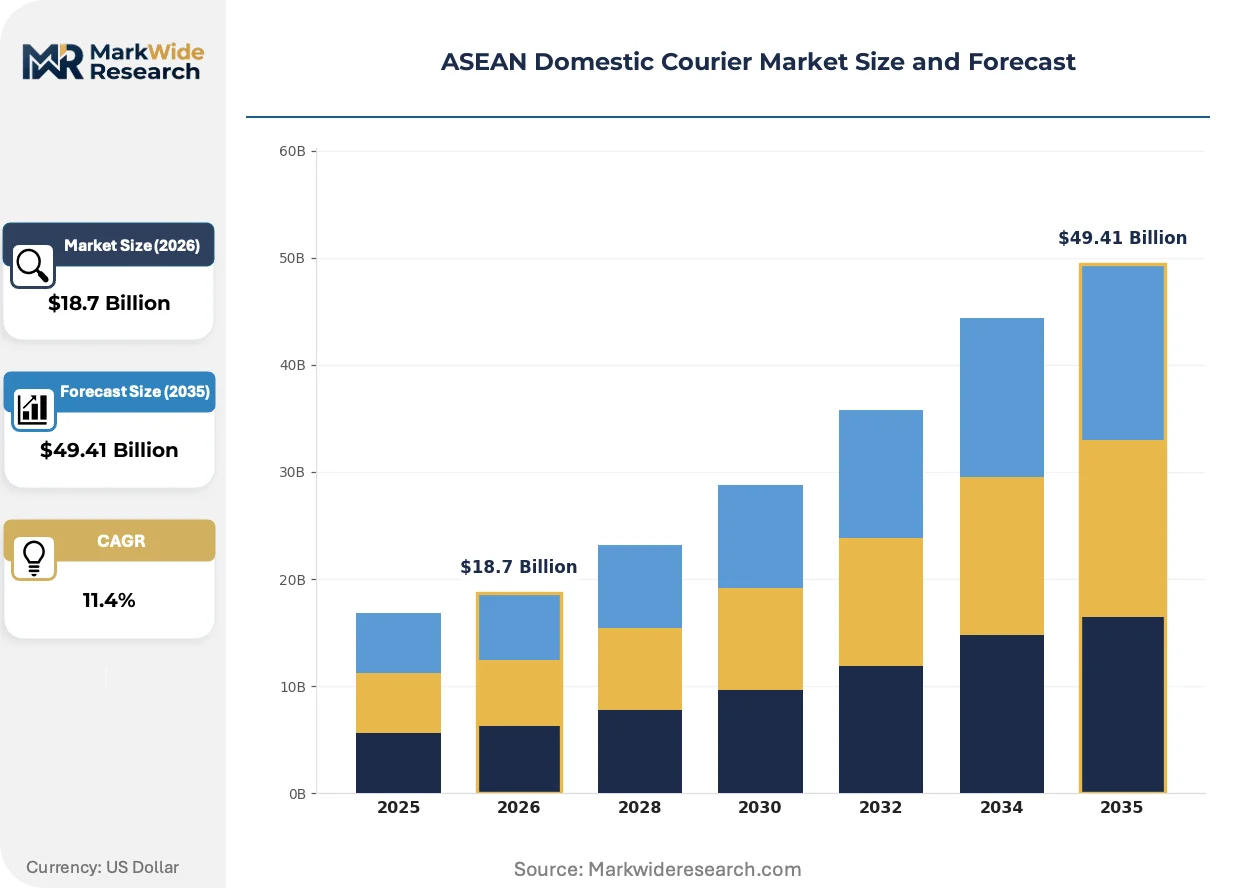
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Shipping, Scheduled Pickup Delivery Model: Door-to-Door, Drop-Off, Locker Pickup, Scheduled Delivery Customer Type: B2B, B2C, E-Commerce, Retail Package Type: Document, Parcel, Pallet, Freight |
| Companies Covered | J&T Express, Ninja Van, DHL Group, GrabExpress, PT Pos Indonesia (Persero), Pos Malaysia, Thailand Post, Kerry Express, JNE Express, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Domestic Courier Market Trends and Innovations
Real-time visibility infrastructure is reshaping competitive differentiation across ASEAN courier networks, compressing the gap between premium service tiers and economy positioning while enabling dynamic routing optimization previously reserved for express segments.
Automated parcel sorting is decomposing traditional hub labor models across Indonesian and Vietnamese facilities. E-commerce merchants with volume commitments above ten thousand daily parcels are mandating machine-readable label compatibility and automated dimensioning. This technology is decomposing the historical trade-off between processing speed and labor cost, enabling same-day service expansion into secondary cities at economy-tier pricing.
Vietnam's Ministry of Industry and Trade is tightening digital commerce logistics reporting requirements for cross-border marketplace transactions. Domestic courier operators must now integrate shipment-level data with customs pre-declaration systems, elevating compliance infrastructure costs. Temperature-sensitive B2B segments in pharmaceutical distribution are absorbing these costs fastest, passing compliance premiums through contract structures.
SME procurement patterns are fragmenting away from single-carrier annual contracts toward platform-integrated spot purchasing. Indonesian marketplace sellers now allocate volume across three to five courier options based on real-time rate comparison tools. This behavior is most visible in Jakarta and Surabaya metro corridors where delivery speed ratings directly determine seller search ranking algorithms.
ASEAN Domestic Courier Market Segmentation
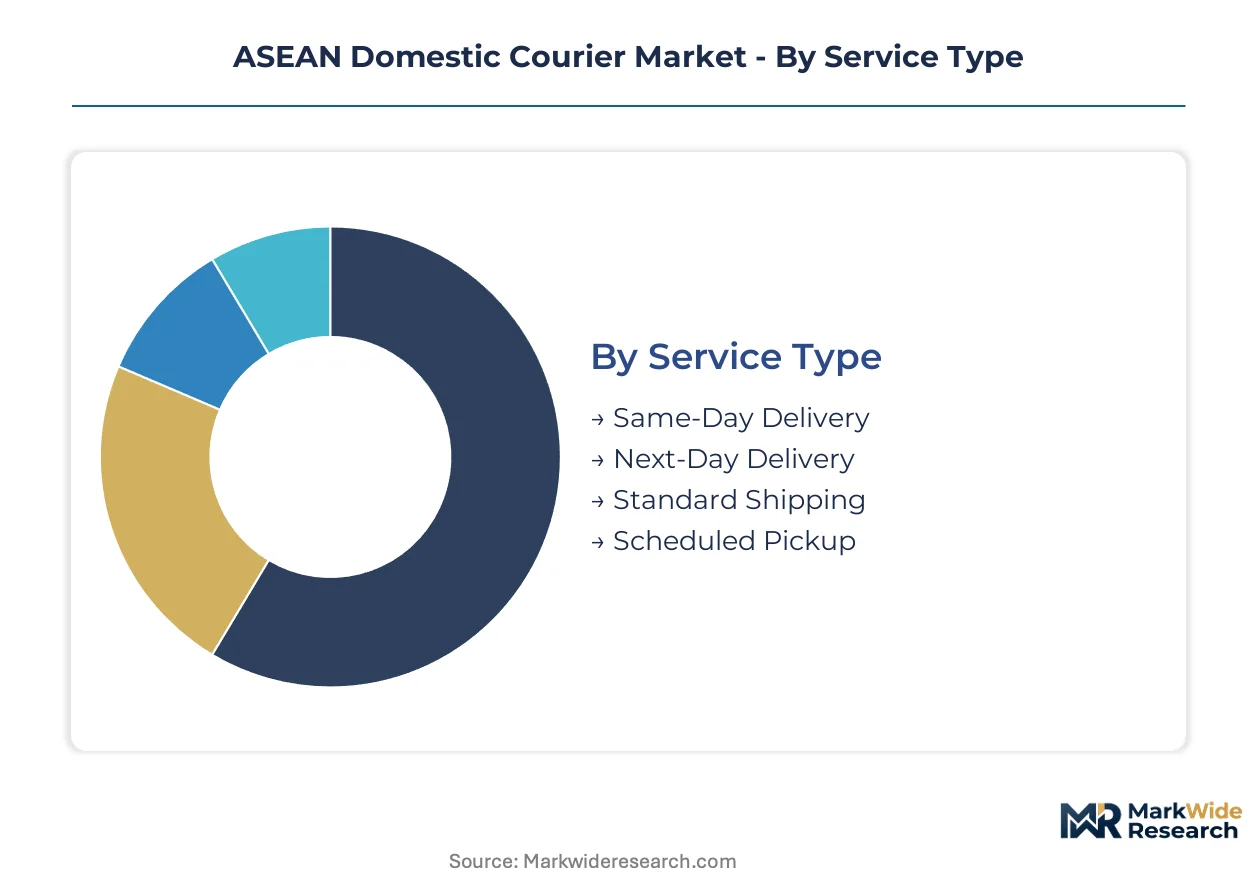
Segmentation in the ASEAN domestic courier market reveals how service tiers, delivery models, and customer profiles command distinct infrastructure investments and margin structures. Platform-integrated logistics is fragmenting traditional volume allocation, forcing operators to align capabilities with specific segment requirements rather than generic service positioning.
Service Type:
Same-day delivery segments face acute substitution pressure from instant delivery platforms and dark store networks, while scheduled services resist displacement through contractual lock-in mechanisms.
- Same-Day Delivery:Premium-tier service requiring metro-based micro-fulfillment nodes and dynamic rider dispatch algorithms. Demand concentrates in Jakarta and Ho Chi Minh City corridors where marketplace algorithms penalize slow fulfillment with search ranking demotion.
- Next-Day Delivery:Hub-and-spoke overnight operations with cutoff-time management. Vietnamese provincial hubs outside Hanoi are generating sufficient density to justify dedicated next-day sortation lanes.
- Standard Shipping:Economy positioning through consolidated trunk routes with 2-5 day windows. Indonesian outer islands absorb disproportionate standard volume due to inter-island ferry scheduling constraints.
- Scheduled Pickup:Recurring B2B account management with API-integrated booking protocols. Malaysian manufacturing corridors are displacing phone-based dispatch with automated scheduling systems.
Standard shipping retains volume leadership; same-day delivery holds the steepest expansion curve.
Delivery Model:
Cost tier differentiation separates asset-heavy door networks from capital-light locker infrastructure, with hybrid models emerging in dense urban corridors.
- Door-to-Door:Labor-intensive final leg requiring address verification and recipient availability. Indonesian informal addressing systems drive manual processing costs in outer island deployments.
- Drop-Off:Counter-based consolidation reducing last-mile dispersion. Thailand's convenience store networks provide dense drop-off coverage with extended operating hours.
- Locker Pickup:Automated collection points with 24-hour accessibility. Singapore and Kuala Lumpur metro areas justify locker density through apartment complex penetration.
- Scheduled Delivery:Appointment-based windows reducing failed delivery rates. B2B pharmaceutical shipments in Vietnam require temperature-verified handoff protocols.
Door-to-door retains volume leadership; locker pickup is gaining share fastest through urban real estate constraints.
Customer Type:
Application-driven segmentation separates inventory velocity requirements between production-linked accounts and consumption-triggered shipments.
- B2B:Contractual logistics with predictable volume profiles and specialized handling requirements. Temperature-controlled pharmaceutical distribution in Vietnam exceeds current specialized fleet capacity.
- B2C:Individual recipient deliveries with high address variability and return processing complexity. Indonesian marketplace sellers now allocate volume across multiple courier options based on real-time rate comparison.
- E-Commerce:Platform-integrated fulfillment with service level agreements tied to seller performance metrics. Vietnamese secondary cities generate parcel density justifying dedicated sorting infrastructure.
- Retail:Store replenishment and customer order fulfillment with omnichannel coordination. Malaysian retail corridors are consolidating procurement away from single-carrier annual contracts.
E-commerce retains volume leadership; B2B holds the steepest expansion curve through specialized service premiums.
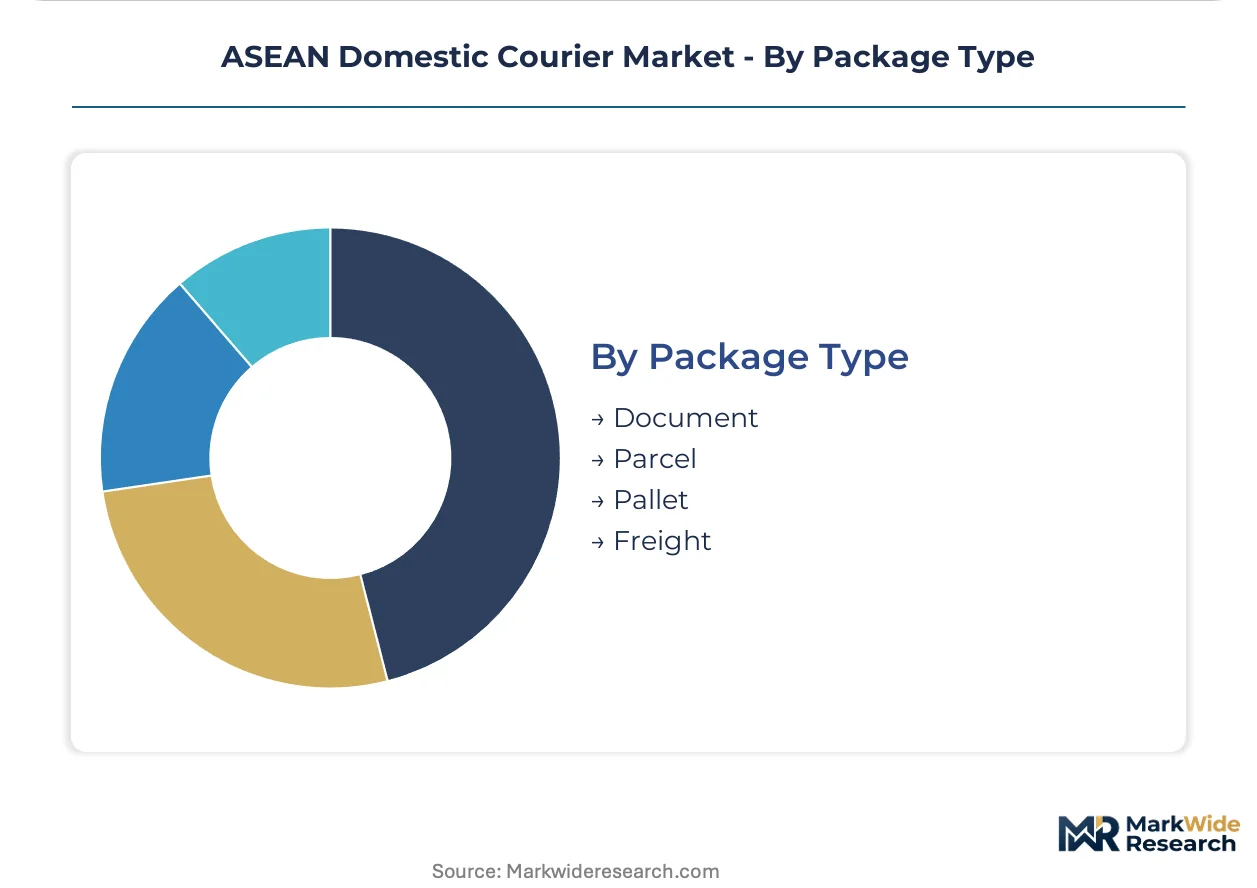
Package Type:
Supply concentration in document and parcel segments is producing divergent automation requirements, with freight demanding distinct fleet and handling infrastructure.
- Document:Lightweight shipments with stable margins despite slower expansion relative to parcel growth. Regulatory filing requirements in Vietnam mandate customs pre-declaration integration.
- Parcel:Machine-readable label compatibility and automated dimensioning are now mandatory for volume commitments above ten thousand daily units. Indonesian automated sorting facilities are decomposing historical labor cost trade-offs.
- Pallet:Unitized freight requiring fork lift-capable vehicles and dock-height loading. Manufacturing corridor demand in Thailand drives scheduled pallet pickup automation.
- Freight:Heavy cargo exceeding parcel network weight thresholds. Long-haul trunk routes between Indonesian provincial hubs and metro sorting centers absorb diesel price volatility impacts.
Parcel retains volume leadership; pallet services are expanding most quickly through manufacturing-linked contract growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia exports parcel volume to Singaporean fulfillment hubs, while Vietnam channels manufacturing-linked logistics through Thai transshipment corridors. Cross-border e-commerce flows concentrate these trade patterns around specific metro agglomerations.
Indonesia
Platform-integrated merchants in Jakarta and Surabaya generate density for automated sorting investments. Ministry of Communication and Informatics data localization rules privilege domestically licensed operators. J&T Express operates hub infrastructure across Java island corridors.
Vietnam
Provincial hubs outside Ho Chi Minh City and Hanoi now justify dedicated sortation lanes for next-day service. Ministry of Industry and Trade mandates shipment-level customs pre-declaration integration. Ninja Van maintains dense last-mile networks in Da Nang and Can Tho secondary cities.
Thailand
Manufacturing corridors around Bangkok drive scheduled B2B pickup automation. Electronic Transactions Development Agency frameworks enable seamless marketplace seller settlement. Kerry Express anchors temperature-controlled capabilities for pharmaceutical distribution.
Philippines
Visayas and Mindanao inter-island networks present white space for hub-and-spoke expansion beyond Luzon concentration. National postal regulators modernize last-mile delivery standards across archipelago jurisdictions. GrabExpress leverages convenience store drop-off density in Cebu and Davao metro areas.
Singapore
Cross-border fulfillment hub status attracts regional e-commerce platform logistics investment. Urban real estate constraints accelerate locker pickup infrastructure in high-density residential clusters. DHL Group anchors premium B2B contract logistics through specialized fleet capabilities.
ASEAN Domestic Courier Market Competitive Landscape
Player mix skews toward platform-integrated networks with automated sorting infrastructure, creating a tiered structure where asset-heavy operators compete against capital-light marketplace-integrated models. Three strategic archetypes dominate: Indonesian-origin hub-and-spoke specialists, Singapore-based premium contract logistics providers, and Vietnam-focused last-mile density builders. Competitive moves center on secondary city fulfillment expansion and API-integrated booking system deployment.
Within the Indonesian-origin tier, J&T Express and JNE Express occupy positions exemplifying automated hub-and-spoke infrastructure deployment across Java island corridors. Among Singapore-based premium operators, DHL Group anchors specialized temperature-controlled capabilities serving pharmaceutical and fresh produce segments. Ninja Van represents the Vietnam-focused archetype with dense last-mile networks in secondary cities outside Hanoi and Ho Chi Minh City.
| Leading Market Players |
|---|
| J&T Express |
| Ninja Van |
| DHL Group |
| GrabExpress |
| PT Pos Indonesia (Persero) |
| Pos Malaysia |
| Thailand Post |
| Kerry Express |
| JNE Express |
| Others |
Pricing and Supply Chain Analysis
Two-to-five-day standard shipping lead times anchor pricing power in Indonesian outer islands, where inter-island ferry scheduling constraints fragment supply concentration and force premium positioning on remote routes. This lead-time band concentrates cost absorption in diesel-exposed trunk routes while metro same-day corridors compress margins through algorithmic rate comparison tools.
Pricing Analysis
Legacy automated sorting infrastructure versus emerging AI-routed dispatch systems versus experimental drone-last-mile pilots creates a three-tier technology-generation pricing gap across ASEAN courier networks. Contract-based long-term offtake agreements dominate B2B pharmaceutical accounts, while platform-integrated spot purchasing fragments SME procurement. Price differentiation rests on volume scale commitments and temperature-controlled certification tiers. Cost compression in standard shipping intensifies as marketplace sellers allocate volume across three to five courier options. E-commerce merchants demonstrate highest price sensitivity; pharmaceutical distributors accept premium positioning for compliance-verified cold chain handoffs.
Supply Chain Analysis
Port congestion at Singapore's transshipment hub and container availability fluctuations on the Jakarta-Singapore trade lane elevate inbound logistics costs for sorting equipment and refrigerated vehicle chassis. Supply concentration centers on China for automated dimensioning hardware, South Korea for electric two-wheeler powertrains, and Japan for fleet telematics systems. Raw material dependencies include lithium-ion battery cells, aluminum alloy body panels, and machine-readable label substrates. Single-source vulnerability in automated sorting software licenses threatens operational continuity. Distribution runs through hub-and-spoke networks with provincial satellite facilities feeding metro micro-fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN domestic courier penetration sits at early-cycle expansion, with Vietnamese provincial hubs outside Hanoi and Ho Chi Minh City justifying dedicated sortation infrastructure as digital commerce deepens beyond metro corridors.
For Market Incumbents: Secure automated hub capacity in Indonesian secondary cities before license concentration tightens under Ministry of Communication and Informatics data localization enforcement. Consolidate temperature-controlled fleet positioning in Vietnamese pharmaceutical corridors where specialized capacity lags demand. Vertical integration into API-integrated booking systems displaces phone-based dispatch in Malaysian manufacturing accounts and locks recurring B2B volume. For New Entrants and Emerging Players: Differentiate on scheduled pickup automation targeting Philippine Visayas and Mindanao manufacturing corridors where inter-island courier networks remain underdeveloped. White-space penetration in Thai provincial hubs outside Bangkok offers lower competitive density than J&T Express-dominated Java corridors. Go-to-market positioning through marketplace-integrated logistics APIs captures SME merchant volume rotation away from single-carrier annual contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated sorting infrastructure as ten-thousand-daily-parcel volume thresholds mandate machine-readable label compatibility and dimensioning investments. Long-term viability favors operators with licensed Indonesian networks and Vietnamese last-mile density. Acquisition targets include Vietnam-focused last-mile specialists with Da Nang and Can Tho penetration. Watch for regulatory divergence signals as ASEAN economic integration advances unevenly across member state postal reforms.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Infrastructure Deployment | J&T Express leverages hub automation across Java to decompose labor cost trade-offs in next-day service expansion. |
| Temperature-Controlled Fleet Expansion | Kerry Express anchors pharmaceutical distribution capabilities in Bangkok corridors where specialized capacity falls short of demand. |
| API-Integrated Booking System Rollout | Malaysian manufacturing corridors displace phone-based dispatch through automated scheduling protocols locking recurring B2B accounts. |
| Secondary City Fulfillment Network Buildout | Ninja Van sustains dense last-mile coverage in Vietnamese provincial hubs generating parcel density for dedicated sortation lanes. |
| Cross-Border Payment Integration Partnership | Thailand's Electronic Transactions Development Agency frameworks enable seamless marketplace seller settlement reducing procurement friction. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with e-commerce platform logistics directors, national postal regulatory affairs leads, courier network operations managers, and manufacturing procurement officers. Secondary validation drew from Ministry of Communication and Informatics filings, Electronic Transactions Development Agency frameworks, Vietnam Ministry of Industry and Trade customs pre-declaration mandates, and ASEAN postal regulator modernization disclosures. Bottom-up volume triangulation against top-down macroeconomic anchors ensured segmentation integrity.
Across the projection horizon, the analytical framework modeled service type, delivery model, customer profile, and package category dimensions alongside platform-integration depth as a courier-specific segmentation axis. CAGRs were derived through volume trajectory analysis against infrastructure investment cycles and regulatory compliance cost absorption patterns. Forecast inputs included diesel price volatility assumptions and automated sorting penetration curves by parcel volume threshold.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce merchant expansion or accelerated data localization enforcement would require recalibration. Forecasts reflect documented assumptions regarding address standardization progress and inter-island ferry scheduling reliability. Recalibration cycles align with material shifts in national postal regulatory frameworks and cross-border payment integration mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Less-Than-Truckload Market