
 Automotive Headlight Bulb Market | 2026-2036
Automotive Headlight Bulb Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Headlight Bulb Market Analysis
Buyer concentration among fleet operators and large aftermarket chains is realigning procurement power toward volume-contracting entities. Valeo S.A. leverages its integrated lighting electronics portfolio to serve these consolidated buyers. Koito Manufacturing Co., Ltd. anchors its position through captive supply relationships with Japanese and North American OEMs. HELLA GmbH & Co. KGaA competes by specializing in adaptive front-lighting modules that command premium positioning.
An automotive headlight bulb converts electrical energy into visible light through filament incandescence, gas discharge, or solid-state electroluminescence, with LED variants achieving luminous efficacy above 100 lumens per watt and operating temperatures below 85°C at the junction. These devices provide forward illumination for vehicle operation under darkness and adverse weather conditions while meeting photometric intensity patterns mandated by national type-approval regimes. LED product type leads in value contribution as OEMs specify solid-state sources for new platforms, while halogen retains volume dominance in aftermarket replacement cycles due to compatibility breadth and price accessibility. Adaptive lighting technology captures expanding share as regulators permit matrix beam functionality and consumers prioritize safety-rated equipment.
NHTSA Federal Motor Vehicle Safety Standard 108 governs headlight photometry and durability in the United States, while ECE Regulation 48 and the EU General Safety Regulation mandate automatic leveling and cleaning systems for high-intensity discharge and LED installations across Europe. China's GB 4599 standard enforces comparable beam pattern requirements through SAMR type-approval processes, creating a tripartite compliance architecture that shapes product development budgets and market entry sequencing. Stakeholders must monitor divergence between U.S. adaptive driving beam rulemaking and European matrix-permission frameworks to anticipate platform engineering commitments and regional launch timing.
Market Dynamics
The automotive headlight bulb sector faces a structural inflection as LED solid-state technology captures OEM platform specifications while halogen aftermarket replacement cycles compress. This bifurcation between forward-fit LED adoption and backward-compatible halogen maintenance creates divergent margin pools across the value chain.
Growth Catalysts
- EU General Safety Regulation mandates:Automatic leveling and cleaning systems for high-intensity discharge and LED installations accelerate premium product penetration across European vehicle fleets.
- Matrix beam functionality:Regulatory permission for adaptive driving beam technology in Germany and select European markets enables advanced front-lighting module deployment.
- Extended vehicle age:North American aftermarket replacement demand intensifies as passenger car and light truck operational lifespans stretch beyond historical averages.
Market Restraints
- Rare earth element dependency:LED phosphor production relies on concentrated Chinese supply chains for europium and terbium, exposing cost volatility to geopolitical friction.
- NHTSA adaptive driving beam delays:Protracted U.S. rulemaking on matrix beam approval forces platform engineering teams into dual-certification strategies that inflate development budgets.
- Halogen-to-LED compatibility gaps:Legacy vehicle electrical architectures lack the voltage stability and thermal management required for direct LED retrofit without module replacement.
Strategic Opportunities
- Smart city infrastructure convergence:Vehicle-to-infrastructure communication protocols in Chinese urban pilot zones create demand for bidirectional lighting systems that signal intent to pedestrian detection networks.
- Aftermarket LED retrofit kits:Regulatory harmonization between ECE Regulation 48 and emerging ASEAN type-approval frameworks opens certification pathway expansion for solid-state conversion products.
- Subscription-based lighting performance:German premium OEMs experiment with over-the-air beam pattern upgrades, creating recurring revenue models detached from hardware replacement cycles.
Industry Challenges
- Optical engineering talent scarcity:Photometric design expertise for adaptive beam shaping concentrates among a limited pool of specialists in Stuttgart, Detroit, and Nagoya metropolitan clusters.
- Dual-homologation complexity:Engineering teams must simultaneously satisfy NHTSA Federal Motor Vehicle Safety Standard 108 photometry requirements and ECE beam pattern divergences without platform fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Headlight Bulb Market |
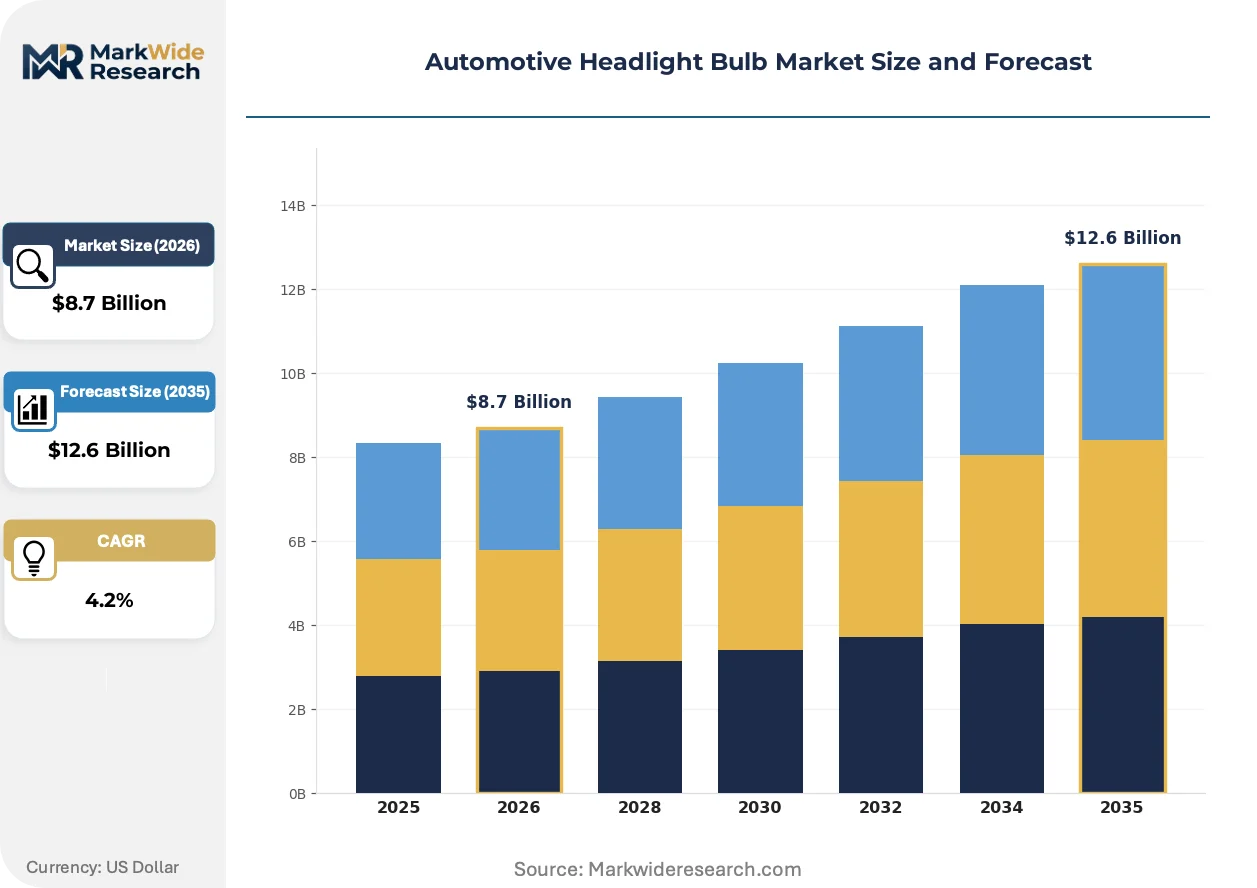
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogen, Xenon, LED, Laser End User: Original Equipment Manufacturers, Aftermarket Consumers, Auto Repair Shops, Fleet Operators Technology: Adaptive Lighting, Daytime Running Lights, Automatic Leveling, Smart Controls Distribution Channel: Online Retail, Offline Retail, Wholesalers, Direct Sales |
| Companies Covered | Philips (Signify N.V.), Valeo S.A., Osram GmbH, General Electric Company, Magneti Marelli S.p.A., Koito Manufacturing Co., Ltd., Stanley Electric Co., Ltd., Hyundai Mobis Co., Ltd., HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Headlight Bulb Market Emerging Trajectories
Active matrix LED technology is compressing incumbent headlight architectures while regulatory divergence between U.S. and European adaptive beam frameworks forces parallel development tracks. These forces reshape competitive positioning around electronics integration rather than discrete component supply.
Micro-LED pixel arrays are consolidating control over beam distribution through solid-state switching that eliminates mechanical actuators. German luxury OEMs specify these modules for flagship platforms, compressing supplier margins on legacy projector systems while elevating software-defined lighting as the value capture point. The technology is consolidating adaptive functionality into semiconductor layers that were previously discrete optical-mechanical assemblies.
NHTSA's pending adaptive driving beam rulemaking remains unresolved five years after initial petition, creating regulatory friction that delays U.S. market entry for matrix-capable systems. European manufacturers exploit this gap by deploying ECE-compliant matrix beams across domestic and export markets, forcing U.S. engineering teams into costlier dual-sku strategies. The divergence most acutely affects mid-luxury segments where platform scale economics determine profitability.
Fleet operators and large aftermarket chains now specify outcome-based lighting performance contracts rather than unit-volume procurement. These agreements transfer lumen maintenance risk to suppliers while capturing predictive replacement data. The shift is most visible in North American commercial vehicle segments where uptime guarantees override component brand preferences.
Automotive Headlight Bulb Market Segmentation
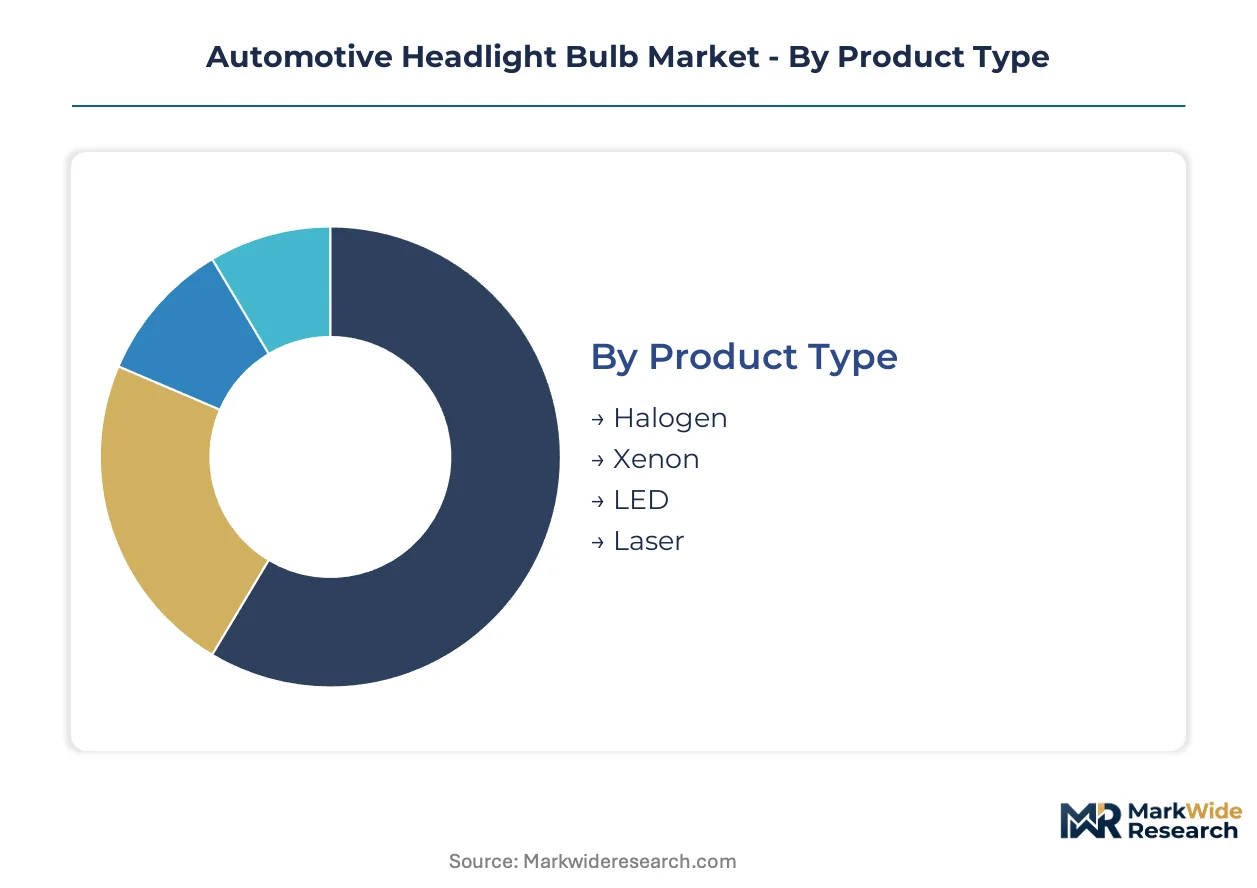
Headlight bulb procurement splits sharply between forward-fit OEM specifications and backward-compatible replacement cycles. Each segment category reflects distinct technical requirements, regulatory compliance burdens, and margin structures that shape supplier strategy.
Product Type:
Upgrade cycles diverge between new vehicle platforms specifying solid-state sources and aging fleets requiring compatible replacements.
- Halogen:Tungsten-filament bulbs operating at color temperatures around 3200K dominate aftermarket volume due to universal socket compatibility and minimal electrical system requirements. Demand concentrates in North American and Western European replacement channels where vehicle age extension sustains replenishment cycles against LED transition pressure.
- LED:Solid-state electroluminescence achieving luminous efficacy above 100 lumens per watt now anchors OEM platform specifications across German, Chinese, and US manufacturer lineups. Premium positioning reflects mandatory automatic leveling systems under EU General Safety Regulation and NHTSA durability testing protocols.
- Xenon:High-intensity discharge arc lamps retain niche presence in mid-luxury retrofit markets and specific European OEM legacy platforms.
- Laser:Coherent light amplification systems enable 600-meter throw distances on German flagship sedans with matrix beam activation.
Volume placements concentrate in Halogen; the faster expansion belongs to LED.
End User:
Procurement authority concentrates among entities with scale-advantaged contracting power or captive supply relationships.
- Original Equipment Manufacturers:Vehicle assemblers specify lighting modules through multi-year platform contracts that bundle electronics, thermal management, and optical design. German and Japanese OEMs enforce stringent supplier qualification protocols that freeze component specifications 24-36 months before production launch.
- Fleet Operators:Commercial vehicle aggregators negotiate outcome-based lighting performance agreements covering lumen maintenance and predictive replacement scheduling. North American trucking and logistics fleets prioritize uptime guarantees over unit procurement costs.
- Aftermarket Consumers:Individual vehicle owners drive replacement demand through retail channels, with purchase decisions weighted toward price accessibility and installation simplicity.
- Auto Repair Shops:Service bay operators intermediate between parts distributors and end consumers, stocking inventory based on regional vehicle age demographics.
Contract value aggregates with OEMs; margin capture is shifting fastest toward Fleet Operators.
Technology:
Feature integration determines pricing tier placement and regulatory compliance scope across regional type-approval frameworks.
- Adaptive Lighting:Matrix beam systems employing solid-state switching to mask oncoming traffic without mechanical shuttering command premium module pricing. German KBA permits full functionality under ECE Regulation 48 while NHTSA rulemaking delays force US market restriction.
- Automatic Leveling:Suspension-linked beam adjustment mechanisms satisfy EU General Safety Regulation mandates for HID and LED installations, adding sensor and actuator cost burdens.
- Daytime Running Lights:Low-power forward illumination circuits reduce pedestrian collision incidence and satisfy European homologation requirements.
- Smart Controls:Vehicle-to-infrastructure communication protocols enable bidirectional signaling in Chinese urban pilot zones.
Regulatory compliance concentrates investment in Automatic Leveling; capability expansion is climbing fastest in Smart Controls.
Distribution Channel:
Channel selection reflects buyer technical sophistication, urgency requirements, and batch size economics.
- Wholesalers:Volume distributors aggregate demand from independent repair networks and regional retailers, capturing economies in inventory pooling and logistics consolidation. North American aftermarket chains source predominantly through tier-one distributors with same-day fulfillment capabilities.
- Online Retail:E-commerce platforms displace traditional stocking for informed consumers conducting specification research, with growth concentrated in LED retrofit kit categories.
- Offline Retail:Brick-and-mortar auto parts stores serve immediate replacement needs and installation-dependent buyers.
- Direct Sales:Supplier-to-OEM relationships bypass intermediaries for platform-contracted module supply.
Transaction volume flows through Wholesalers; channel share is gaining fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive headlight bulb procurement concentrates in manufacturing clusters where OEM platform engineering and aftermarket distribution networks overlap. Germany, China, and the United States dominate forward-fit specifications and replacement channel volumes respectively.
United States
Fleet operators and commercial vehicle aggregators drive aftermarket demand through outcome-based lighting performance contracts. NHTSA Federal Motor Vehicle Safety Standard 108 governs headlight photometry and durability testing protocols. Detroit's automotive engineering corridor anchors adaptive driving beam development despite pending matrix beam rulemaking delays.
Germany
Premium OEM platform specifications for LED and laser modules sustain high-value procurement from Stuttgart and Munich-based manufacturers. KBA permits full matrix beam functionality under ECE Regulation 48, accelerating adaptive front-lighting deployment. The Stuttgart metropolitan cluster concentrates optical engineering talent for photometric design.
China
Domestic OEM platform expansion and smart city infrastructure pilots generate bidirectional lighting system demand. SAMR enforces GB 4599 beam pattern requirements through type-approval processes. Yangtze River Delta manufacturing zones supply LED phosphor materials despite concentrated rare earth element dependencies.
Japan
Captive supply relationships between lighting suppliers and domestic OEMs preserve stable contract volumes. METI oversees industrial standards coordination with international type-approval frameworks. Nagoya's automotive supplier corridor specializes in integrated lighting electronics for platform-specific modules.
South Korea
Domestic OEM global platform exports sustain LED module specification demand. MFDS and related agencies align national standards with ECE and NHTSA frameworks for export market access. Seoul Capital Area engineering centers develop solid-state switching technologies for matrix beam applications.
Automotive Headlight Bulb Market Vendor Landscape
German and Japanese producers anchor one tier; Chinese and South Korean specialists hold volume positions in LED component supply. The market structure tiers between integrated lighting electronics suppliers and discrete component manufacturers. Three archetypes dominate: captive OEM suppliers, independent module specialists, and aftermarket-focused distributors. Consolidation pressures favor multi-year platform contracts and predictive replacement service agreements.
Among European-anchored lighting specialists, Valeo S.A., HELLA GmbH & Co. KGaA, and Osram GmbH occupy positions spanning integrated electronics and adaptive module development. These entities exemplify the premium-tier archetype where software-defined beam control and regulatory compliance capabilities determine contract access. Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. represent Japanese captive-supply structures. Philips (Signify N.V.) anchors aftermarket channel presence across replacement cycles.
| Leading Market Players |
|---|
| Philips (Signify N.V.) |
| Valeo S.A. |
| Osram GmbH |
| General Electric Company |
| Magneti Marelli S.p.A. |
| Koito Manufacturing Co., Ltd. |
| Stanley Electric Co., Ltd. |
| Hyundai Mobis Co., Ltd. |
| HELLA GmbH & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Captive supply relationships between Japanese and North American OEMs anchor both procurement stability and premium pricing power for tier-one lighting module suppliers. This integration pattern insulates incumbent producers from spot-market volatility while compressing margin capture opportunities for independent aftermarket distributors competing on halogen replacement volume.
Pricing Analysis
Volume placements concentrate in halogen aftermarket replacements at commodity-equivalent price points, while margin capture clusters in LED platform specifications for German and Chinese OEMs. Pricing stratifies across adaptive matrix modules, standard LED assemblies, and economy halogen tiers based on photometric certification grade and automatic leveling system bundling. Cost compression in halogen replacement channels is intensifying because fleet operators negotiate outcome-based lumen maintenance contracts. Aftermarket consumers exhibit highest price sensitivity, while OEM platform engineering teams prioritize regulatory compliance over unit cost.
Supply Chain Analysis
Optical engineering talent scarcity in Stuttgart, Detroit, and Nagoya metropolitan clusters constrains module design capacity for adaptive beam systems. LED phosphor production draws from concentrated Chinese supply chains for europium and terbium rare earth elements, creating single-source vulnerability for solid-state source manufacturers. Distribution runs through tier-one wholesalers with same-day fulfillment capabilities to North American aftermarket chains and independent repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform contract consolidation among German and Japanese OEMs is forcing independent lighting specialists into acquisition or exit, as multi-year specification freezes eliminate spot-supply opportunities for non-integrated competitors.
For Market Incumbents: Anchor defensive positioning through backward integration into LED phosphor supply chains and captive thermal management component production. Koito Manufacturing and Stanley Electric demonstrate how Japanese OEM relationships insulate against halogen aftermarket erosion. Matrix beam software development represents the priority capability investment as hardware commoditization accelerates. For New Entrants and Emerging Players: EU General Safety Regulation mandates in Germany and France open a window for aftermarket LED retrofit kit certification under harmonized ECE Regulation 48 frameworks. ASEAN type-approval convergence creates the most penetrable geographic entry point for solid-state conversion products. Direct-to-consumer online retail channels bypass wholesaler margin extraction for specification-literate buyers. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-contracted module specialists with embedded OEM engineering relationships. Five-to-ten year viability hinges on adaptive driving beam software capabilities rather than discrete component manufacturing scale. Watch NHTSA matrix beam rulemaking resolution as the inflection signal determining U.S. market timing for premium module suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Driving Beam Software Investment | Captures value as matrix functionality displaces mechanical shuttering in ECE-regulated markets. |
| Rare Earth Supply Agreement | Secures europium and terbium access against Chinese export restriction exposure for LED phosphor production. |
| Aftermarket LED Retrofit Certification | Opens revenue streams in aging vehicle replacement cycles across North America and Western Europe. |
| Fleet Operator Outcome Contracting | Transfers lumen maintenance risk to suppliers while capturing predictive replacement data in commercial vehicle segments. |
| Dual-Homologation Engineering Capability | Enables simultaneous NHTSA and ECE compliance without platform fragmentation for export market access. |
Methodological Framework
Multi-period observation of vehicle platform specification timelines, aftermarket replacement cycle frequencies, and regulatory rulemaking progressions anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard 108 docket records, ECE Regulation 48 amendment tracking, SAMR GB 4599 type-approval databases, and vehicle production registration data. Bottom-up segmentation modeling triangulated against top-down market sizing from industry association shipments.
Input-output matrices mapped LED and halogen volume flows across OEM forward-fit and aftermarket replacement channels over the projection horizon. Segmentation dimensions included product type, end-user procurement authority, technology feature integration, and regional regulatory framework. CAGRs were derived from regression analysis of historical platform adoption curves and replacement cycle compression patterns, with explicit modeling of EU General Safety Regulation mandate timing and NHTSA adaptive driving beam rulemaking scenarios.
Caveats apply where rare earth supply disruption, accelerated NHTSA matrix beam approval, or OEM platform electrification timelines could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory harmonization progress and vehicle age extension trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Off-Highway Actuators Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Europe Automotive Electric Actuators Market