
 North America Vehicle Tolling System Market | 2026-2036
North America Vehicle Tolling System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vehicle Tolling System Market Analytics
Public-private partnership channels for toll road concessions is reconfiguring how system integrators engage state transportation agencies. TransCore leverages its long-standing relationship with the Texas Department of Transportation to anchor deployments across the southern United States. Kapsch TrafficCom AG competes through specialized expertise in multi-protocol interoperability, while Verra Mobility Corporation extends its position via dominant control of violation enforcement and revenue recovery services.
A vehicle tolling system integrates roadside detection hardware, back-office transaction processing, and vehicle identification technologies to automate fee collection from road users without requiring vehicles to stop. Core functional parameters include read accuracy above 99% for RFID transponders, sub-second transaction latency, and seamless interoperability across state and provincial boundaries. Highway tolling applications sustain the largest revenue pool given mature infrastructure across the eastern seaboard and Gulf Coast corridors, while cloud-based deployment architectures represent the fastest-expanding segment as agencies migrate from legacy mainframe systems. Video analytics technology is displacing manual tollbooth operations in urban congestion pricing pilots.
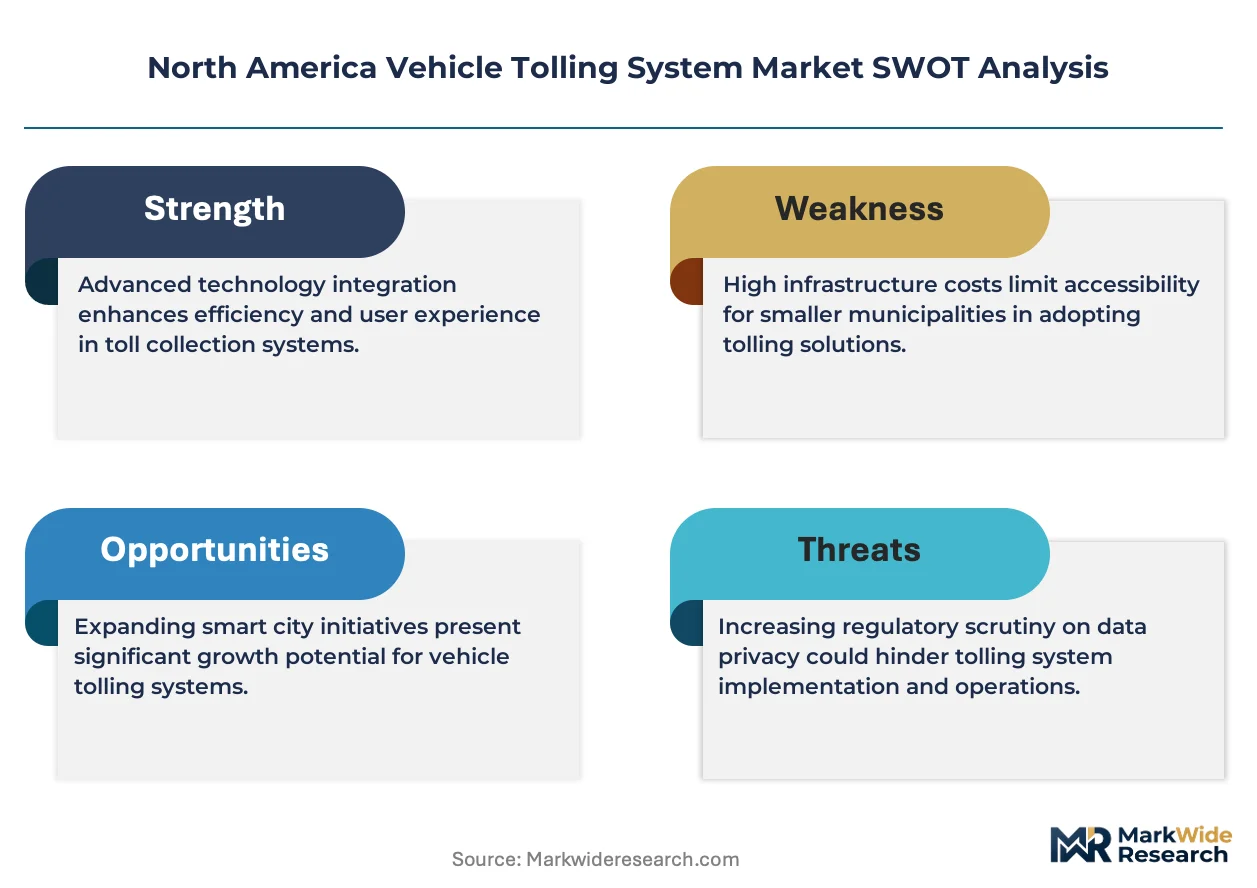
The Federal Highway Administration, state-level departments of transportation, and the International Bridge, Tunnel and Turnpike Association collectively shape equipment certification, data privacy protocols, and interoperability mandates across the United States and Canada. The National Privacy Commission in Canada and emerging state-level biometric data regulations in California and Illinois are tightening constraints on license plate recognition data retention and cross-border sharing. Stakeholders must monitor pending federal infrastructure funding reauthorization and its potential to accelerate or delay replacement cycles for aging toll collection infrastructure.
Market Dynamics
Fleet operators across the Texas Triangle corridor are accelerating replacement of legacy transponder systems with cloud-native transaction architectures, compressing procurement cycles for state transportation agencies.
Growth Catalysts
- Interoperability Mandates:The Federal Highway Administration's electronic toll collection standards are compelling state agencies to upgrade incompatible legacy systems.
- Congestion Pricing Expansion:Urban transportation authorities in New York and San Francisco are deploying dynamic pricing zones to manage peak-hour traffic flows.
- RFID Transponder Accuracy Thresholds:Equipment certification requiring 99% read reliability is driving wholesale infrastructure replacement across Gulf Coast corridors.
Market Restraints
- Semiconductor Supply Concentration:Toll system manufacturers face extended lead times for specialized RFID chipsets sourced from East Asian foundries.
- Biometric Data Regulations:California's Consumer Privacy Act and Illinois biometric laws impose strict retention limits on license plate recognition databases.
- Copper and Aluminum Volatility:Roadside antenna arrays and gantry structures face input cost pressure from base metal commodity swings.
Strategic Opportunities
- Canadian Provincial Integration:Ontario's 407 ETR and Quebec's A25 bridge represent underpenetrated corridors for unified cross-border tolling protocols.
- Video-Analytics Convergence:Machine vision algorithms combined with edge computing are enabling camera-only tolling without transponder dependency.
- Public-Private Partnership Channels:Texas and Florida are expanding concession-based procurement models that bundle construction with long-term operations contracts.
Industry Challenges
- Legacy Mainframe Integration:State agencies struggle to interface cloud-based transaction platforms with decades-old back-office billing systems.
- Specialized Technician Scarcity:Deployment and maintenance of roadside detection hardware requires certified field engineers in short supply across rural interstate corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vehicle Tolling System Market |
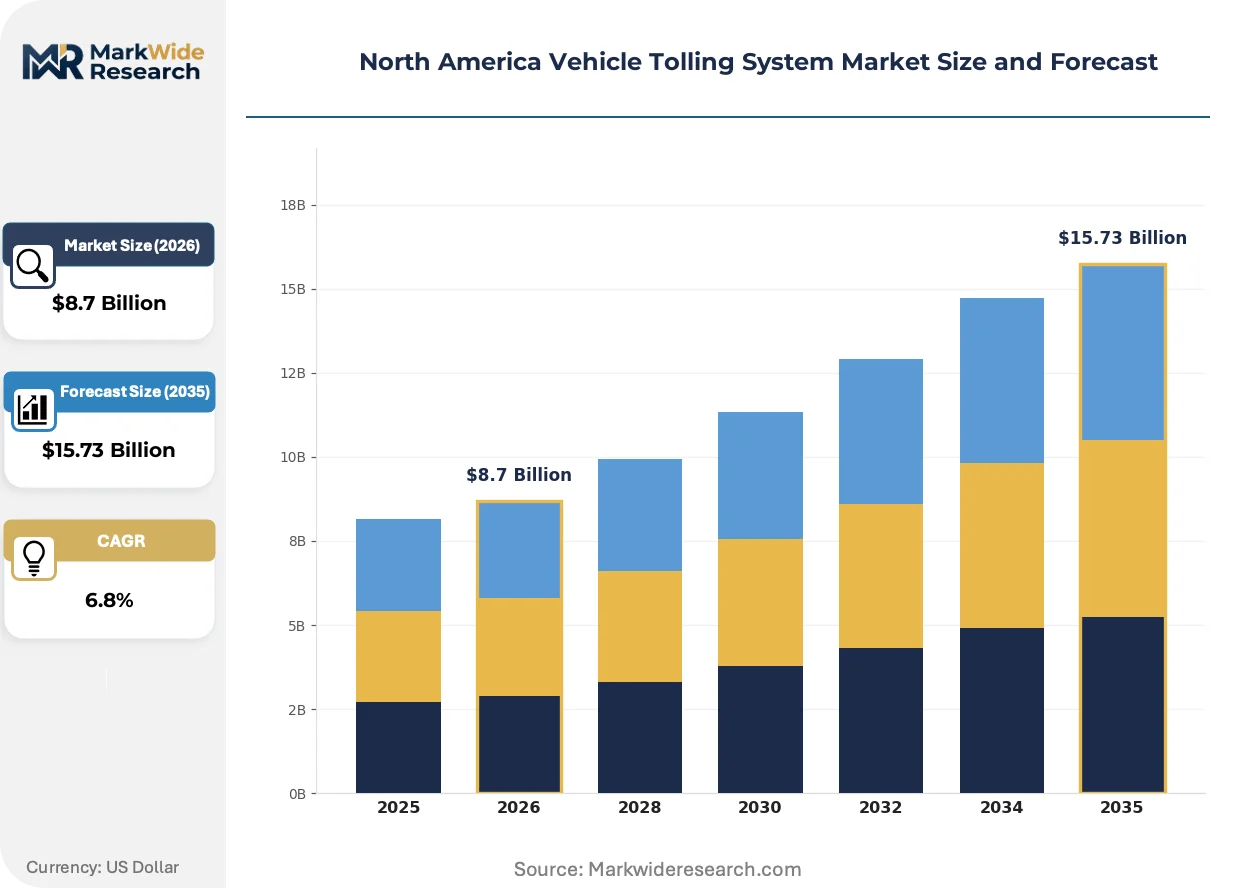
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: ETC, Manual, Video Analytics, RFID End User: Government, Toll Authorities, Fleet Operators, Transportation Agencies Application: Highway Tolling, Urban Tolling, Bridge Tolling, Parking Management Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Thales Group, Siemens AG, TransCore, Kapsch TrafficCom AG, Verra Mobility Corporation, Conduent, Magnetic Autocontrol GmbH, Emovis GmbH, International Road Dynamics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vehicle Tolling System Market Evolving Landscape
Cloud-native transaction processing is displacing mainframe-dependent architectures across state transportation departments. Three concurrent developments are compressing deployment timelines and reconfiguring vendor competitive dynamics.
Edge-based video analytics platforms are migrating from pilot deployments to production-scale urban congestion pricing systems. Municipal transportation agencies in Manhattan and Los Angeles are adopting camera-only tolling to eliminate transponder distribution costs. The technology is migrating from supplementary violation enforcement to primary transaction capture, reducing hardware footprint at tolling points.
The Federal Highway Administration's ongoing support for interoperable electronic toll collection is reshaping procurement standards nationwide. State departments of transportation must now certify equipment compatibility across multi-jurisdictional corridors before receiving federal infrastructure funding. Highway tolling applications face the steepest compliance burden as agencies retrofit aging gantries to meet unified protocol requirements.
Fleet operators are consolidating vendor relationships around integrated violation management and revenue recovery services. Large commercial trucking companies now demand bundled offerings spanning transponder provisioning, toll reconciliation, and administrative penalty resolution. This concentration is most visible across the Interstate 35 and Interstate 95 corridors where multi-state operators prioritize single-contract simplicity over point-solution optimization.
North America Vehicle Tolling System Market Segmentation
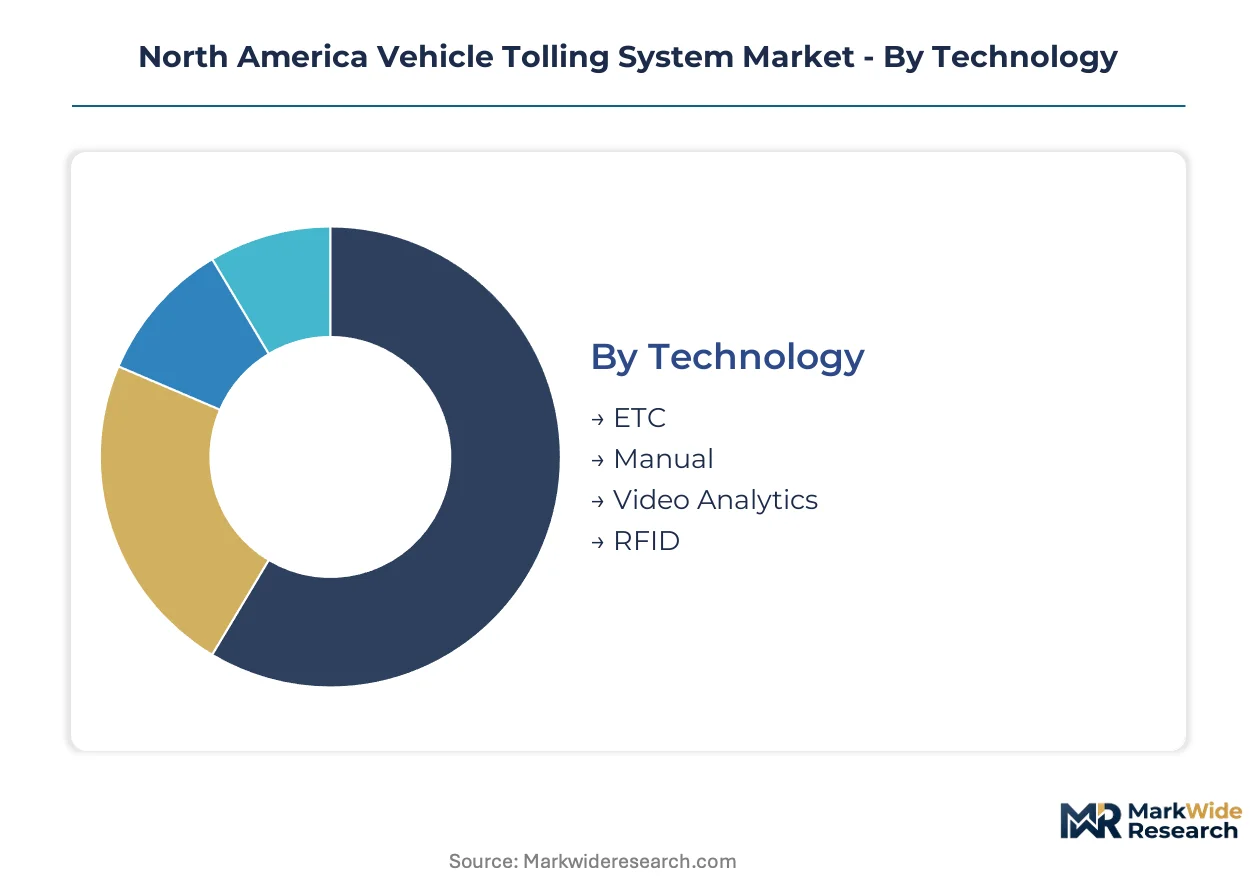
Segmentation in the North America Vehicle Tolling System Market reveals how procurement priorities diverge across technology maturity, operational scale, and infrastructure ownership models. Understanding these divisions clarifies where federal compliance mandates intersect with state-level budget cycles and fleet operator consolidation pressures.
Technology:
Cost tier differentiation separates legacy maintenance obligations from next-generation capital commitments across state transportation departments.
- ETC:Electronic toll collection systems process transactions via dedicated short-range communications at highway speeds without vehicle deceleration. The Federal Highway Administration's interoperability mandates are compelling wholesale replacement of proprietary protocols across the Gulf Coast and eastern seaboard corridors.
- Video Analytics:Machine vision platforms capture license plate data through high-resolution cameras coupled with edge-computing inference engines. New York and Los Angeles transportation authorities are deploying camera-only architectures to eliminate transponder distribution costs in urban congestion pricing zones.
- Manual:Attended tollbooth operations persist at legacy bridge crossings and cash-preference corridors where transaction volumes do not justify automation capital expenditure.
- RFID:Radio-frequency identification transponders mounted on windshields communicate with roadside readers using microwave frequencies in the 5.8 GHz band.
ETC holds installed capacity. Video Analytics is rotating up the share rankings.
End User:
Application context determines procurement complexity, from federal funding compliance to commercial fleet reconciliation requirements.
- Government:Federal and state entities prioritize interoperability certification and data sovereignty in multi-jurisdictional corridor deployments. The Texas Department of Transportation anchors the largest consolidated procurement program across the southern United States.
- Fleet Operators:Commercial trucking companies demand bundled transponder provisioning, toll reconciliation, and violation management through single-contract arrangements. Large multi-state operators along Interstate 35 and Interstate 95 corridors are consolidating vendor relationships around integrated revenue recovery services.
- Toll Authorities:Special-purpose districts manage specific facility revenue streams with focused jurisdiction over bridge, tunnel, or turnpike operations.
- Transportation Agencies:Metropolitan planning organizations coordinate congestion pricing pilots and multimodal integration across urban boundaries.
Government maintains procurement volume leadership. Fleet Operators are climbing the fastest as commercial vehicle telematics integration accelerates.
Application:
Volume concentration follows corridor density and existing infrastructure maturity rather than greenfield expansion potential.
- Highway Tolling:Long-distance interstate corridors generate sustained transaction volumes through mature gantries across the eastern seaboard and Texas Triangle. Federal infrastructure funding reauthorization cycles directly influence replacement timelines for aging roadside detection hardware.
- Urban Tolling:Dynamic congestion pricing zones in Manhattan and San Francisco deploy variable-rate structures to manage peak-hour traffic flows. Municipal transportation agencies are piloting camera-only systems to reduce physical infrastructure footprint in dense urban cores.
- Bridge Tolling:River crossings and harbor tunnels maintain specialized procurement focused on high-occupancy vehicle discrimination and commercial vehicle classification accuracy.
- Parking Management:Off-street facility operators adopt license plate recognition for frictionless entry-exit revenue capture in airport and commercial garage applications.
Highway Tolling dominates transaction throughput. Urban Tolling is expanding most quickly as metropolitan pricing authority consolidates.
Deployment:
Margin structure diverges sharply between capital-intensive on-premises infrastructure and recurring-revenue cloud service models.
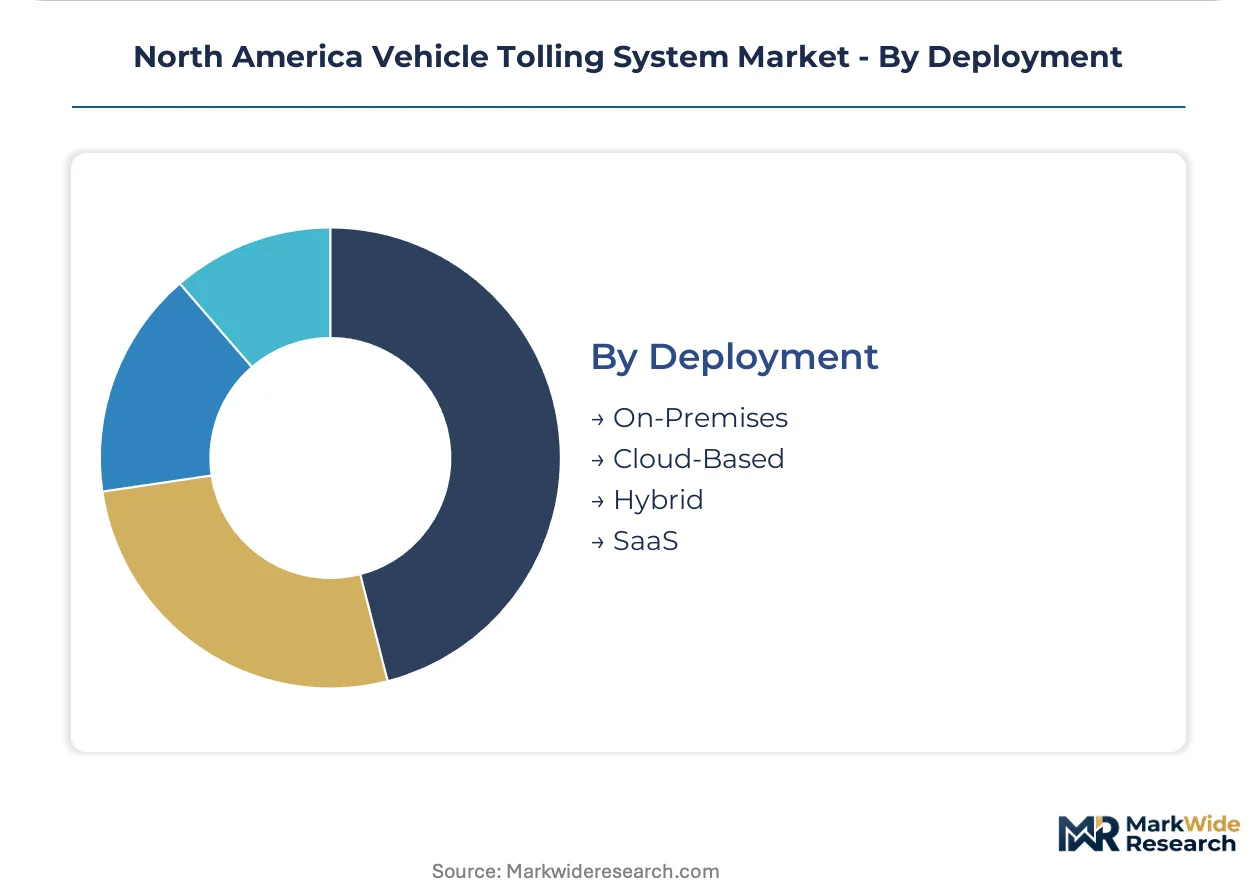
- Cloud-Based:Native cloud architectures eliminate mainframe dependency through API-driven transaction processing and elastic compute scaling. State agencies migrating from legacy systems face integration challenges with decades-old back-office billing platforms.
- Hybrid:Configurations combine on-premises roadside hardware with cloud-hosted transaction clearinghouses to balance latency requirements against operational flexibility. This architecture accommodates agencies with phased modernization budgets and mixed-vendor environments.
- On-Premises:Dedicated data center installations persist where data residency requirements or air-gapped security protocols override cloud migration incentives.
- SaaS:Software-as-a-service delivery models bundle application licensing, infrastructure management, and continuous update cycles into per-transaction or subscription fee structures.
Hybrid retains transitional dominance. Cloud-Based is gaining share fastest as federal certification standards stabilize multi-tenant security frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Texas Triangle corridor where state procurement budgets dwarf Canadian provincial programs, while Mexican infrastructure investment cycles operate on distinct federal funding calendars.
United States
The Federal Highway Administration's interoperability mandates are accelerating system replacements across Gulf Coast and eastern seaboard corridors. State transportation departments in Texas, Florida, and California anchor the largest consolidated procurement volumes. The Texas Department of Transportation maintains the most extensive deployment program connecting Dallas, Houston, and San Antonio through unified electronic toll collection infrastructure.
Canada
Ontario's 407 ETR and Quebec's A25 bridge represent underpenetrated corridors for cross-border protocol harmonization. The National Privacy Commission enforces strict license plate recognition data retention limits that constrain vendor system architectures. Provincial transportation ministries in Ontario and Quebec are piloting unified tolling standards to enable seamless travel across the Windsor-Quebec City corridor.
Mexico
Federal highway concession programs are expanding automated tolling across Interstate 35 corridor connections to US border crossings. The Secretariat of Communications and Transportation oversees equipment certification standards that increasingly reference US Federal Highway Administration protocols. Northern border states including Nuevo León and Tamaulipas are prioritizing interoperable systems to facilitate commercial freight movement.
North America Vehicle Tolling System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying detection hardware and transaction processing modules. Market structure tilts toward consolidated procurement relationships where long-standing state agency contracts create significant incumbent advantages. Three archetypes dominate: full-stack system integrators with end-to-end deployment capabilities, specialized component manufacturers focused on RFID or video analytics subsystems, and violation enforcement service providers bundling revenue recovery with toll administration. Competitive dynamics center on strategic partnerships for cloud migration services and vertical integration into roadside hardware manufacturing to secure supply chain control.
Among European-headquartered conglomerates, Thales Group and Siemens AG occupy positions spanning defense, transportation, and digital infrastructure portfolios that enable cross-subsidized market entry. TransCore exemplifies the entrenched incumbent archetype through its deep state agency relationships, while Kapsch TrafficCom AG and Verra Mobility Corporation represent specialization-focused competitors concentrating on interoperability protocols and enforcement services respectively.
| Leading Market Players |
|---|
| Thales Group |
| Siemens AG |
| TransCore |
| Kapsch TrafficCom AG |
| Verra Mobility Corporation |
| Conduent |
| Magnetic Autocontrol GmbH |
| Emovis GmbH |
| International Road Dynamics Inc. |
| Others |
Value Network & Pricing Analysis
East Asian foundry concentration for specialized RFID chipsets concentrates margin capture upstream, leaving system integrators and state transportation agencies to absorb cost volatility through multi-year procurement contracts. The downstream pricing structure reflects this dependency through configured-to-order premiums for rapid deployment timelines versus standard-tier pricing for scheduled replacement cycles.
Pricing Analysis
Configured-to-order pricing commands a substantial premium over standard procurement schedules across state transportation departments. The dominant pricing model runs through project-based contracting with SaaS-tiered back-office components, where price differentiation tracks certification tier and customization depth. Cost compression in standard-tier hardware is intensifying because semiconductor lead times have extended, while fleet operators show the greatest price sensitivity due to transponder volume scale.
Supply Chain Analysis
Supply-chain finance facilities from tier-one system integrators are extending payment terms to specialized field engineering subcontractors across rural interstate corridors. Manufacturing concentration for RFID readers and edge-computing modules rests on Taiwan, South Korea, and China, with raw material dependencies spanning copper antenna arrays, aluminum gantry structures, and silicon carbide power components. Single-source vulnerability in East Asian semiconductor packaging creates structural exposure, while distribution runs through state-procurement vehicles and concession-based public-private partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Vehicle Tolling System Market represents a high-growth disruption as cloud-native transaction architectures displace legacy mainframe systems and video analytics eliminates transponder dependency in urban deployments. Federal Highway Administration interoperability mandates are compressing replacement cycles and reshaping competitive positioning.
For Market Incumbents: Harden cloud migration capabilities through backward integration into edge-computing hardware manufacturing to secure supply chain control against East Asian foundry concentration. Deepen certification investment for multi-protocol interoperability to defend state agency relationships against specialized protocol competitors. The threat of camera-only tolling from video analytics specialists demands accelerated R&D in machine vision integration.
For New Entrants and Emerging Players: Build out violation enforcement and revenue recovery service bundles to penetrate fleet operator consolidation trends along Interstate 35 and Interstate 95 corridors. Canadian provincial integration represents the most penetrable geography, with Ontario's 407 ETR and Quebec's A25 bridge lacking unified cross-border protocols. A direct-to-toll-authority go-to-market angle targeting bridge and tunnel special-purpose districts bypasses incumbent state transportation department relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed violation enforcement service providers and regional system integrators holding long-term concession contracts. The five-to-ten-year viability window favors acquisition targets with cloud-native platform architectures and established interoperability certifications. The signal to watch is federal infrastructure funding reauthorization timing, which would accelerate replacement demand and expand procurement pool depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Eliminates mainframe dependency for state agencies through API-driven transaction processing and elastic compute scaling. |
| Video-Analytics Technology Integration | Enables camera-only tolling in Manhattan and Los Angeles congestion pricing zones without transponder infrastructure. |
| Interoperability Certification Investment | Secures Federal Highway Administration compliance for multi-jurisdictional corridor deployments across Gulf Coast states. |
| Fleet Service Bundle Expansion | Captures commercial trucking consolidation through integrated transponder provisioning and violation management. |
| Canadian Provincial Market Entry | Exploits underpenetrated Ontario 407 ETR and Quebec A25 bridge corridors for cross-border protocol harmonization. |
Research Methodology
The analysis maps electronic toll collection, video analytics, RFID, and manual tolling sub-sectors, each validated through interviews with state transportation procurement officers, toll authority operations directors, fleet operator logistics managers, and system integrator program executives. Primary fieldwork combined with secondary validation from Federal Highway Administration guidance documents, International Bridge Tunnel and Turnpike Association standards, state DOT procurement databases, and SEC filings of publicly traded tolling technology providers. Bottom-up transaction volume modeling and top-down infrastructure replacement cycle analysis were triangulated to produce segment-level outputs.
The assumption-set held federal infrastructure funding reauthorization at baseline levels while varying cloud adoption velocity and video analytics penetration rates across the projection horizon. The analytical framework modeled technology type, end-user category, application context, and deployment architecture dimensions. CAGRs were derived from infrastructure replacement cycle analysis and fleet telematics integration curves, with inputs including state procurement budget trajectories and semiconductor supply lead time assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-platform investment by European conglomerates or accelerated video-analytics deployment by municipal agencies would shift outcomes. Macroeconomic deviation in base metal commodity markets, regulatory tightening on license plate recognition data retention, or technological breakthrough in edge-computing inference efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
B2C Mobility Sharing Market