
 Automotive Bearing Market | 2026-2036
Automotive Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Bearing Market Analysis
IATF 16949 certification is reorganizing supplier tiers across the automotive bearing value chain, filtering out uncertified producers from OEM supply networks. SKF leverages its captive steel-processing assets to control raw material consistency from mine to finished race. Schaeffler AG sustains R&D intensity through dedicated e-mobility bearing centers in Germany and China. NSK Ltd. anchors its competitive position through deep specialization in electric powertrain-specific high-speed ball bearing architectures.
An automotive bearing is a precision-engineered rotational component, typically fabricated from vacuum-degassed bearing steel with hardened raceways and rolling elements separated by a cage, designed to reduce friction and support radial or axial loads in vehicle subsystems. Its primary industrial purpose is to enable reliable power transmission and motion control under cyclic thermal and mechanical stress across powertrain, chassis, and steering assemblies. Roller bearings occupy the dominant share of value in heavy-duty transmission and chassis applications where load capacity outweighs speed requirements. Ceramic material bearings represent the fastest-expanding segment as thermal management demands intensify in electrified powertrains. OEM end-user channels capture the largest margin pools due to multi-year platform contracts and integrated design-in responsibilities.
EPA tailpipe regulations in the United States, REACH chemical restrictions administered by ECHA in Europe, and China's GB standards enforced by SAMR collectively tighten material composition, recyclability, and durability requirements for bearings sold into regulated vehicle markets. These frameworks compel manufacturers to redesign lubrication systems, substitute restricted substances, and document full material lifecycle traceability. Stakeholders must monitor evolving battery-electric platform architectures to calibrate bearing portfolio exposure between declining internal-combustion applications and expanding e-axle, inverter-cooling, and thermal-management system opportunities.
Market Dynamics
Electric powertrain architectures are compressing bearing duty cycles while elevating thermal and rotational speed requirements beyond legacy internal-combustion specifications. SKF, Schaeffler AG, and NSK Ltd. are restructuring R&D allocation toward ceramic hybrid and solid-lubricated variants to capture platform design-in contracts.
Growth Catalysts
- EPA emissions mandates:Stricter tailpipe standards in the United States force engine redesigns that demand precision low-friction bearings in valvetrain and accessory drive systems.
- Silicon nitride ceramic rolling elements:These materials withstand inverter-adjacent thermal spikes above 150°C where conventional steel degrades, accelerating adoption in e-axle modules.
- China:SAMR enforcement of GB standards for vehicle durability extends bearing replacement intervals, expanding OEM specification volumes for premium sealed units.
Market Restraints
- Vacuum-degassed bearing steel supply:Concentrated primary production in China and Japan creates input cost volatility and allocation risk during alloy surcharge spikes.
- REACH substance restrictions:ECHA limitations on specific lubricant additives force reformulation cycles that extend qualification timelines by 12-18 months.
- Magnetic bearing substitution:Active magnetic levitation systems eliminate mechanical contact entirely in high-speed compressor applications above 30,000 RPM.
Strategic Opportunities
- India:PLI scheme incentives for domestic automotive component manufacturing reduce import dependency and localize bearing supply for expanding passenger vehicle exports.
- Thermal management integration:Convergence of bearing housings with inverter cooling circuits creates unified module procurement opportunities in battery-electric platforms.
- E-commerce aftermarket channels:Direct-to-workshop platforms bypass traditional distributor tiers, capturing margin compression in replacement bearing sales.
Industry Challenges
- IATF 16949 certification backlog:Third-party auditor capacity constraints delay supplier qualification, freezing uncertified producers out of OEM platform awards.
- Clean steel metallurgy expertise:Scarcity of engineers capable of specifying oxygen and titanium content thresholds for bearing-grade alloys limits R&D team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Bearing Market |
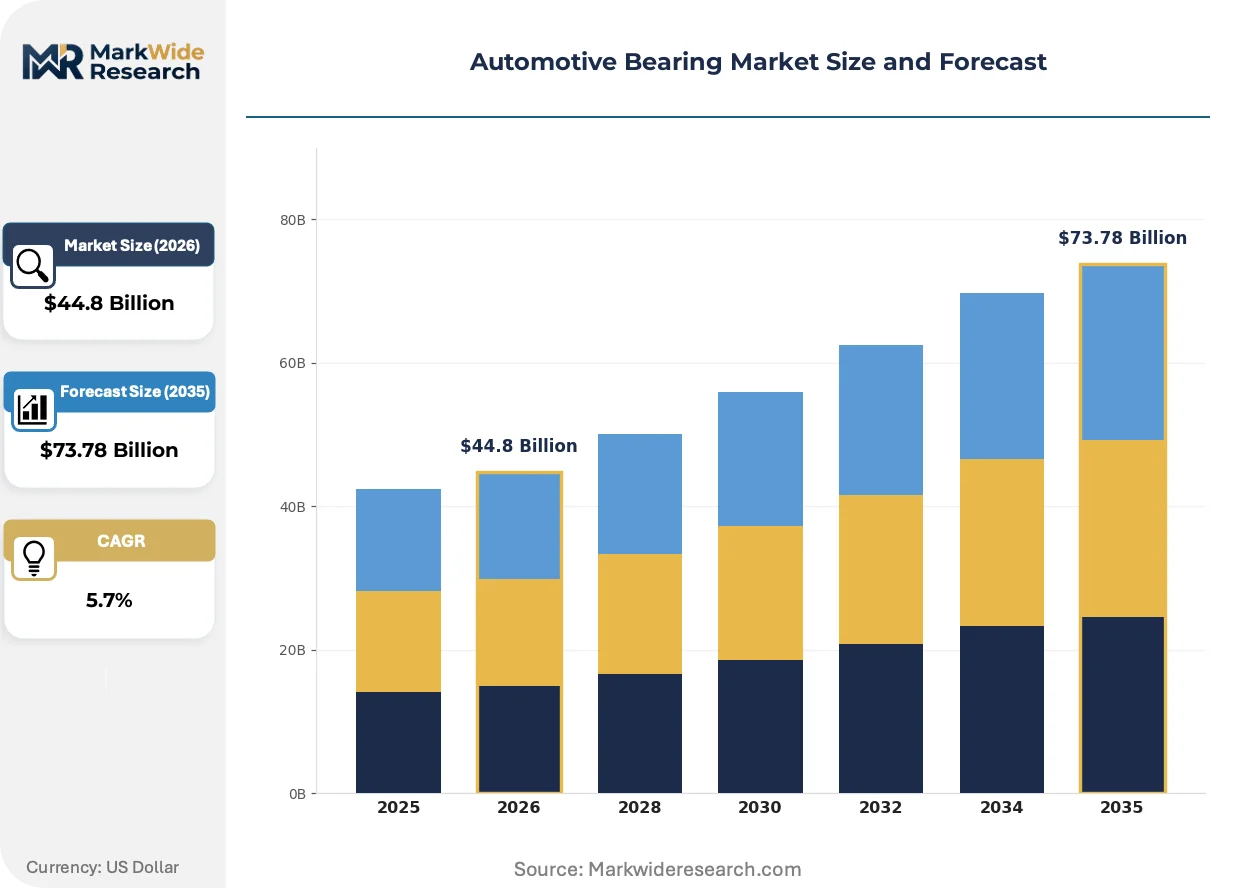
| Market Size in 2026 | $44.8 Billion |
| Market Size in 2035 | $73.78 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Tapered Bearings, Thrust Bearings End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Material: Steel, Ceramic, Plastic, Composite Application: Engine Components, Transmission Systems, Chassis Systems, Steering Mechanisms |
| Companies Covered | SKF, Schaeffler AG, NSK Ltd., NTN Corporation, JTEKT Corporation, The Timken Company, Nachi-Fujikoshi Corporation, MinebeaMitsumi Inc., RBC Bearings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Bearing Market Emerging Trajectories
Ceramic hybrid architectures and solid lubrication systems are redefining performance boundaries as electrified powertrains expose bearings to electrical pitting and thermal shock absent in conventional drivetrains.
Solid polymer lubricant bearings with PTFE-impregnated cages are supplanting grease-packed steel units in sealed-for-life e-motor support applications. Tier 1 suppliers specify these variants for 400,000-kilometer maintenance intervals. The shift is compressing aftermarket service revenue pools while elevating upfront OEM contract values.
REACH chemical restrictions administered by ECHA are prohibiting specific extreme-pressure additives and corrosion inhibitors in European-market bearings. Manufacturers substitute ionic liquid lubricants and phosphate ester alternatives. German and French OEMs now require full material disclosure documentation extending to sub-tier steel suppliers.
Platform-level procurement consolidation is displacing subsystem-specific bearing sourcing. E-axle integrators now specify complete rotating assemblies rather than discrete bearing components. This pattern concentrates specification authority with Schaeffler AG and NSK Ltd. in Germany and Japan, marginalizing independent bearing distributors from design-in phases.
Automotive Bearing Market Segmentation
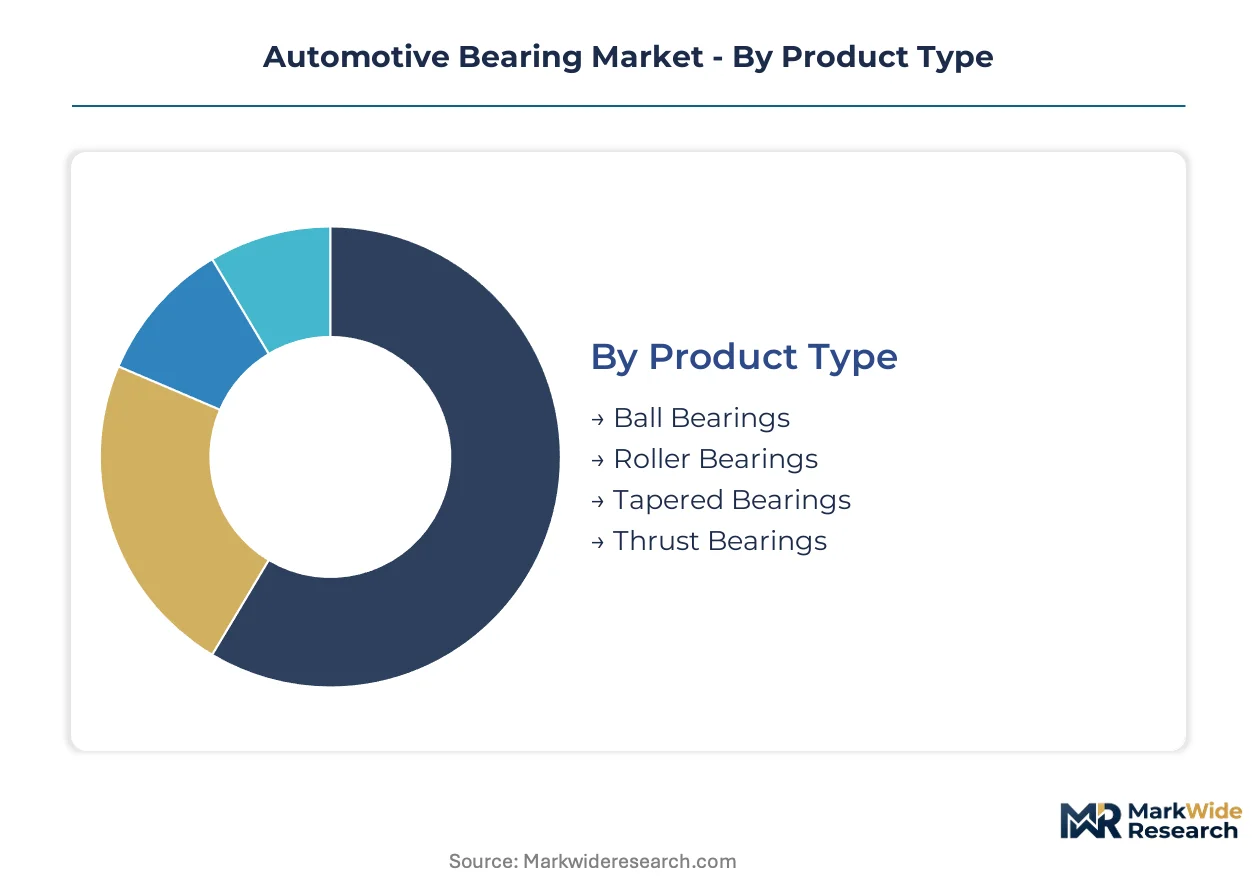
Automotive bearing segmentation reflects divergent certification requirements across product tiers and end-user channels. IATF 16949 compliance separates OEM-qualified suppliers from aftermarket-only producers, while material specifications respond to distinct thermal regimes in electrified versus combustion architectures.
Product Type:
EPA emissions mandates in the United States and ECHA REACH restrictions in Europe impose divergent friction-reduction specifications across bearing categories, with electrified powertrains demanding higher speed ratings than conventional drivetrains.
- Roller Bearings:Cylindrical and spherical configurations handle radial loads in transmission housings and wheel hubs. Demand concentrates in heavy-duty commercial vehicle production in Germany and Japan, where load capacity specifications exceed 50 kN for axle applications. EPA-driven engine downsizing has shifted some volume toward compact tapered variants in passenger valvetrains.
- Ball Bearings:Deep-groove and angular-contact designs support combined loads at rotational speeds above 15,000 RPM. NSK Ltd. and SKF anchor demand in Japanese and Swedish electric powertrain manufacturing, where e-motor support bearings must withstand inverter-induced electrical pitting. Silicon nitride hybrid variants are climbing the fastest as thermal spikes exceed 150°C in e-axle modules.
- Tapered Bearings:Conical raceway geometry manages simultaneous radial and axial thrust in differential pinions and wheel ends. Commercial vehicle production in China specifies these for extended durability under GB standards enforcement.
- Thrust Bearings:Flat-race designs absorb axial loads in automatic transmission clutch packs and steering rack gears. Japanese automatic transmission exports sustain primary demand.
Established volume favors roller bearings in chassis and transmission applications; emerging adoption favors ball bearings in electrified powertrains.
End User:
Procurement authority concentrates with entities holding platform-level design-in responsibility and multi-year contract visibility.
- OEMs:Vehicle manufacturers specify bearings during platform development, locking in suppliers for production cycles exceeding seven years. German and Japanese OEMs require full material traceability documentation under ECHA disclosure rules.
- Tier-1 Suppliers:E-axle integrators and transmission assemblers procure complete rotating assemblies rather than discrete components. Schaeffler AG and NSK Ltd. dominate specification authority in Germany and Japan through captive design centers.
- Aftermarket Providers:Independent distributors serve replacement demand outside warranty periods. REACH-compliant lubricant formulations extend qualification timelines for European-market units.
- Dealerships:Authorized service channels capture warranty-period replacements with OEM-branded sealed units. China's SAMR enforcement of extended durability intervals compresses this channel's volume.
Margin pools concentrate with OEMs and Tier-1 suppliers; aftermarket channels face compression from sealed-for-life technologies.
Material:
Thermal management requirements in electrified architectures are fragmenting material specifications across temperature thresholds.
- Steel:Vacuum-degassed bearing alloys with controlled oxygen and titanium content remain dominant for cost-sensitive chassis applications. Supply concentrates in Chinese and Japanese primary steel production, creating allocation risk during alloy surcharge volatility.
- Ceramic:Silicon nitride rolling elements in hybrid configurations withstand thermal spikes and electrical pitting in inverter-adjacent e-motor supports. Japanese and German e-axle production drives steepest expansion trajectory for this category.
- Plastic:Polymer races and cages reduce weight in auxiliary systems with moderate load requirements. HVAC blower motors and sensor housings in United States passenger vehicles specify these.
- Composite:Carbon-fiber-reinforced matrices serve niche applications requiring extreme stiffness-to-weight ratios. Racing and limited-production electric vehicles in Germany trial these for unsprung mass reduction.
Cost-driven volume remains with steel; performance-critical electrified applications are shifting fastest toward ceramic.
Application:
Duty cycle compression in electrified powertrains elevates speed and thermal specifications beyond legacy internal-combustion baselines.
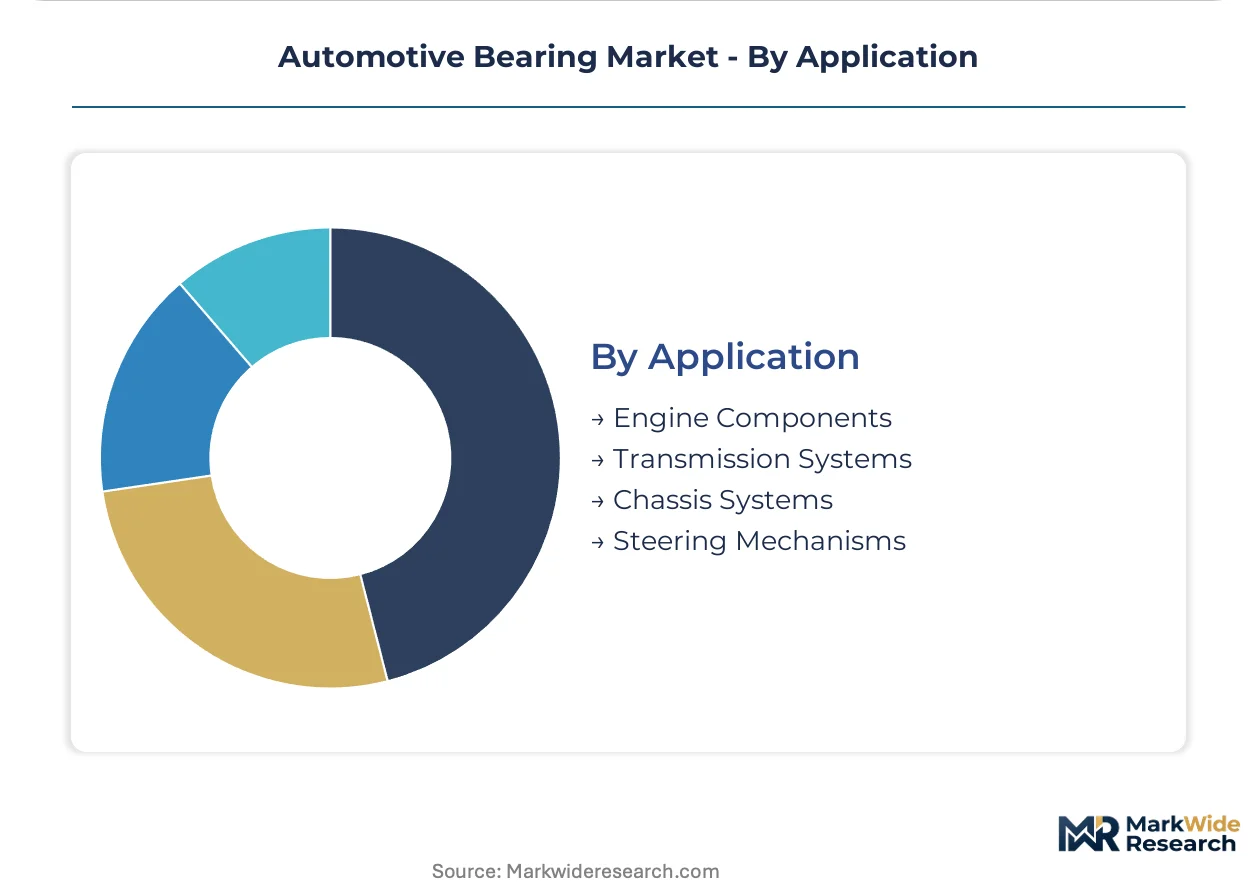
- Transmission Systems:Manual, automatic, and e-axle gearboxes require bearings handling cyclic torque loads across 8,000-20,000 RPM ranges. German dual-clutch and Japanese e-axle production sustain highest specification intensity.
- Engine Components:Valvetrain, crankshaft, and accessory drive bearings face EPA-mandated friction reduction targets. United States emissions regulations force low-viscosity lubricant compatibility redesigns.
- Chassis Systems:Wheel hubs, suspension linkages, and differential carriers prioritize load capacity over rotational speed. Chinese commercial vehicle exports specify sealed units under GB durability standards.
- Steering Mechanisms:Rack-and-pinion and electric power steering columns demand precise axial load management. Japanese compact vehicle platforms concentrate demand for compact, high-precision variants.
Traditional volume centers on transmission and engine applications; electrification is accelerating fastest in integrated e-axle and thermal management systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese OEMs dominate precision bearing procurement through captive design centers, while Chinese steel supply and Indian assembly expansion reshape upstream and downstream geography.
China
Domestic EV platform launches by BYD and NIO drive specification volumes for ceramic hybrid bearings in e-axle modules. SAMR enforces GB standards for extended vehicle durability, forcing OEMs to source premium sealed units with documented material traceability. Shanghai and Yangtze River Delta clusters concentrate bearing steel production and e-motor assembly, creating integrated supply corridors from vacuum-degassed alloy to finished powertrain components.
Germany
Dual-clutch transmission exports and e-axle integration for Mercedes-Benz and BMW sustain demand for high-speed ball bearing architectures. ECHA REACH restrictions prohibit specific extreme-pressure lubricant additives, compelling reformulation cycles that extend qualification timelines. Stuttgart and Munich engineering centers specify complete rotating assemblies rather than discrete bearings, consolidating procurement authority with Tier-1 integrators.
United States
EPA tailpipe regulations force engine downsizing and valvetrain redesigns requiring low-friction bearing solutions. The agency's emissions mandates accelerate adoption of precision bearings in accessory drive systems. Michigan and Ohio automotive corridors concentrate Tier-1 transmission assembly, while California EV startups specify ceramic variants for thermal management in inverter-adjacent applications.
Japan
Automatic transmission exports and compact EV platform development sustain demand for angular-contact ball bearings in electric power steering and e-motor support roles. METI industrial policy prioritizes domestic supply chain resilience for critical automotive components. Nagoya and Kansai manufacturing belts anchor precision bearing production, with Toyota and Honda specifying silicon nitride hybrids for 400,000-kilometer maintenance intervals.
India
PLI scheme incentives for domestic automotive component manufacturing reduce import dependency for passenger vehicle bearing supply. The program's production-linked benefits attract Tier-1 suppliers to establish local assembly capacity. Tamil Nadu and Gujarat automotive clusters expand bearing procurement for export-oriented compact vehicle platforms, with Maruti Suzuki and Hyundai sourcing sealed units under extended durability specifications.
Automotive Bearing Market Vendor Landscape
Player mix skews toward integrated steel-to-bearing manufacturers with captive metallurgy assets and specialized e-mobility R&D centers. Three structural tiers operate: multinational conglomerates controlling full value chains, mid-scale specialists focused on ceramic hybrid architectures, and regional fabricators serving aftermarket replacement demand. Competitive moves concentrate on backward integration into bearing steel supply and strategic partnerships with e-axle integrators for platform design-in access.
Among Sweden-based and Germany-based conglomerates, SKF and Schaeffler AG exemplify the integrated archetype through upstream control over raw material consistency. NSK Ltd. occupies a position within the Japanese specialist tier, anchoring demand in electric powertrain-specific high-speed architectures. These three entities represent the dominant specification authority in platform-level procurement consolidation, where e-axle integrators now source complete rotating assemblies rather than discrete components.
| Leading Market Players |
|---|
| SKF |
| Schaeffler AG |
| NSK Ltd. |
| NTN Corporation |
| JTEKT Corporation |
| The Timken Company |
| Nachi-Fujikoshi Corporation |
| MinebeaMitsumi Inc. |
| RBC Bearings, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for vacuum-degassed bearing steel translate into pricing power concentration among integrated manufacturers with captive metallurgy assets, while spot-market buyers absorb alloy surcharge volatility through quarterly contract renegotiations.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and chromium benchmarks dominate OEM procurement, with IATF 16949 certification grade and e-mobility performance tier serving as the primary price differentiation drivers. Pricing pressure stems from REACH-mandated lubricant reformulation cycles that compress Tier-1 supplier margins. Aftermarket distributors exhibit highest price sensitivity due to sealed-for-life technologies eroding replacement volumes, while OEM platform engineers prioritize thermal performance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and Japanese OEM assembly plants, while Chinese steel mills maintain strategic stockpiles of vacuum-degassed alloys to buffer alloy surcharge spikes. Supply concentrates in China, Japan, and Germany for bearing steel production, with silicon nitride ceramic powder and PTFE-impregnated cage materials as critical dependencies. Single-source vulnerability runs through Chinese primary steel production during export quota periods. Distribution runs through Tier-1 e-axle integrators rather than discrete component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where IATF 16949 certification entrenchment creates regulatory switching costs that freeze uncertified competitors from OEM platform awards.
For Market Incumbents: Compound captive steel-processing advantages through backward integration into oxygen-controlled vacuum-degassing capacity, while accelerating ceramic hybrid R&D to defend against magnetic bearing substitution in high-speed compressor applications above 30,000 RPM. For New Entrants and Emerging Players: Aftermarket e-commerce platform under-service by incumbent distributors presents white-space entry points, with direct-to-workshop channels in India's PLI-subsidized automotive clusters offering the most penetrable geography and lowest certification barrier. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized bearing divisions lacking e-mobility R&D allocation; long-term viability hinges on thermal management integration capabilities in battery-electric platforms. Watch for e-axle platform standardization announcements as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Hybrid Bearing Scale-Up | Captures design-in contracts from BYD and NIO e-axle platforms requiring 150°C thermal tolerance. |
| Captive Vacuum-Degassing Investment | Locks in raw material consistency against Chinese alloy surcharge volatility and allocation risk. |
| E-Axle Integrator Partnership | Consolidates specification authority as Schaeffler AG and NSK Ltd. dominate rotating assembly procurement. |
| Solid Lubrication Qualification | Meets Toyota and Honda 400,000-kilometer maintenance interval specifications for sealed-for-life units. |
| India PLI Localization | Reduces import dependency for Maruti Suzuki and Hyundai export-oriented compact vehicle platforms. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers; and secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from listed bearing manufacturers, and customs trade records. Bottom-up volume triangulation across product type, material, and application segments converged with top-down value estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions including propulsion architecture, content per vehicle, OEM tier positioning, and regional production cluster. CAGRs were derived from regression analysis against vehicle production forecasts and electrification penetration curves, with silicon nitride ceramic adoption rates and EPA emissions compliance timelines as critical industry-specific inputs.
Forecasts assume regulatory continuity in EPA tailpipe standards, ECHA REACH restrictions, and China's GB standards enforcement; material policy shifts would require re-modeling. Revision becomes warranted when battery-electric platform standardization or magnetic bearing cost curves cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Resonator Market
Automotive Components
Global Automotive Gears Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Automotive Fuel Injection System Market