
 Automotive MEMS Market | 2026-2036
Automotive MEMS Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive MEMS Market Analysis
Market Context
China is reconfiguring automotive MEMS supply dynamics through aggressive capacity additions in wafer fabrication and sensor packaging. Robert Bosch GmbH leverages its vertically integrated manufacturing footprint to dominate inertial and pressure sensor categories. STMicroelectronics sustains technology leadership through deep R&D investment in piezoelectric MEMS architectures. Infineon Technologies AG anchors its position in safety-critical applications with ASIL-qualified sensor portfolios.
Technical Definition and Structural Segments
Automotive MEMS (micro-electromechanical systems) are micron-scale mechanical structures fabricated on silicon substrates using photolithography, thin-film deposition, and deep reactive-ion etching, converting physical stimuli into electrical signals for real-time vehicle monitoring and control. These devices serve as the perceptual layer for engine management, occupant protection, and chassis stabilization systems. Inertial sensors and pressure sensors command the largest revenue pools, reflecting their ubiquity in electronic stability control and tire pressure monitoring mandates. Microphones represent the fastest-expanding category, driven by in-cabin voice interfaces and road-noise cancellation algorithms. End-user concentration favors OEMs and Tier-1 Suppliers, where multi-year platform contracts lock in volume commitments and technical collaboration.
Regulatory Framework and Outlook
NHTSA in the United States, ECE regulations administered by UNECE in Europe, and China's MIIT jointly enforce crashworthiness, emissions, and cybersecurity standards that dictate MEMS performance thresholds and qualification protocols. REACH and RoHS compliance in Europe, alongside EPA emissions verification in the United States, constrain material choices and accelerate design refresh cycles. Stakeholders must monitor evolving functional safety standards and cross-border data governance rules that will determine which sensor architectures qualify for next-generation vehicle platforms.
Market Dynamics
ADAS sensor node proliferation is compressing replacement cycles and concentrating procurement power among platform-scale OEMs, while Europe's F-Gas Regulation forces refrigerant sensor redesigns across thermal management systems.
Growth Catalysts
- TPMS mandates:NHTSA regulations in the United States and equivalent UNECE ECE R64 protocols in Europe enforce direct tire pressure monitoring, sustaining volume demand for absolute pressure MEMS across vehicle classes.
- Voice interface penetration:Road-noise cancellation algorithms and in-cabin assistants are expanding microphone array counts per vehicle, with premium cabins now integrating six to eight acoustic sensing nodes.
- China:MIIT vehicle safety standards and domestic EV platform scale are accelerating local sourcing requirements for inertial measurement units in chassis stabilization systems.
Market Restraints
- Foundry concentration:Automotive-grade MEMS fabrication capacity clusters in Germany, Japan, and the United States, creating geographic supply risk for second-source qualification.
- Platinum group metals:Exhaust gas sensors depend on palladium and rhodium catalyst coatings, with price volatility transmitted directly to bill-of-materials costs.
- ASIL-D certification timelines:ISO 26262 functional safety validation for safety-critical inertial sensors extends development cycles by 18-24 months versus industrial-grade equivalents.
Strategic Opportunities
- India:PLI scheme incentives for automotive component manufacturing are attracting MEMS packaging investments to serve domestic OEM assembly growth.
- Lidar-solid-state convergence:Micro-mirror arrays and optical MEMS are enabling chip-scale beam steering, collapsing mechanical complexity in autonomous perception stacks.
- EU Green Deal:Embedded emissions tracking requirements for vehicle lifecycle certification are creating demand for environmental condition sensors in battery management systems.
Industry Challenges
- Packaging engineering scarcity:Hermetic sealing and stress isolation for high-g automotive environments requires specialized MEMS process integration expertise concentrated at a handful of IDMs.
- Multi-domain integration:Combining inertial, pressure, and acoustic sensing on single substrates demands co-design with OEM electronic architecture teams, compressing Tier-1 development margins.
Report Scope
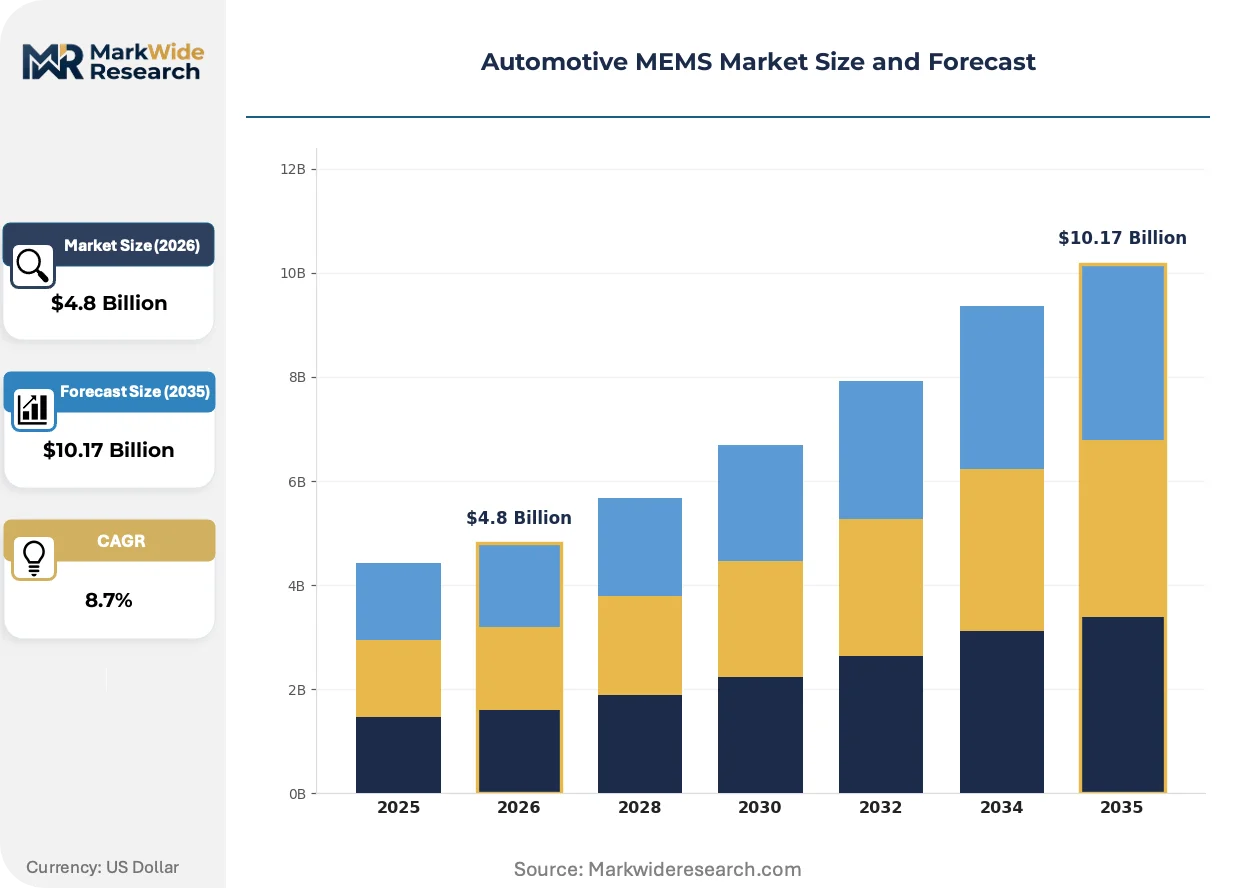
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive MEMS Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Inertial Sensors, Microphones, Optical Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Analog, Digital, Wireless, MEMS Microphones Application: Safety Systems, Engine Control, Infotainment, Chassis |
| Companies Covered | Robert Bosch GmbH, STMicroelectronics, Analog Devices, Inc., Continental AG, Denso Corporation, Infineon Technologies AG, NXP Semiconductors, Sensata Technologies, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive MEMS Market Emerging Trajectories
Piezoelectric thin-film processes are displacing capacitive architectures in next-generation sensors, while regulatory pressure on refrigerant leakage detection is forcing thermal management redesigns. OEM procurement consolidation is compressing supplier qualification timelines.
Capacitive-to-piezoelectric transition is accelerating in pressure and inertial sensing, with aluminum nitride and PZT thin films enabling higher operating temperatures and reduced drift. Robert Bosch GmbH and STMicroelectronics are scaling these processes for engine compartment applications. The technology is hybridizing signal conditioning electronics with sensing structures, collapsing module footprint and assembly cost.
F-Gas Regulation in Europe mandates refrigerant leak detection in vehicle air conditioning systems, requiring new pressure and gas concentration sensor categories. Tier-1 thermal management suppliers are redesigning compressor control loops to accommodate real-time refrigerant monitoring. Passenger vehicle HVAC platforms are absorbing the compliance cost through sensor integration at the valve block level.
Consolidated platform procurement by Volkswagen Group, Toyota, and Stellantis is compressing supplier negotiation cycles from multi-year frameworks to annual price-down schedules with volume guarantees. Tier-1 sensor suppliers are responding with captive foundry investments and long-term die bank arrangements. Germany and Japan exhibit the tightest procurement consolidation, with single-source agreements now requiring explicit second-source qualification commitments.
Automotive MEMS Market Segmentation
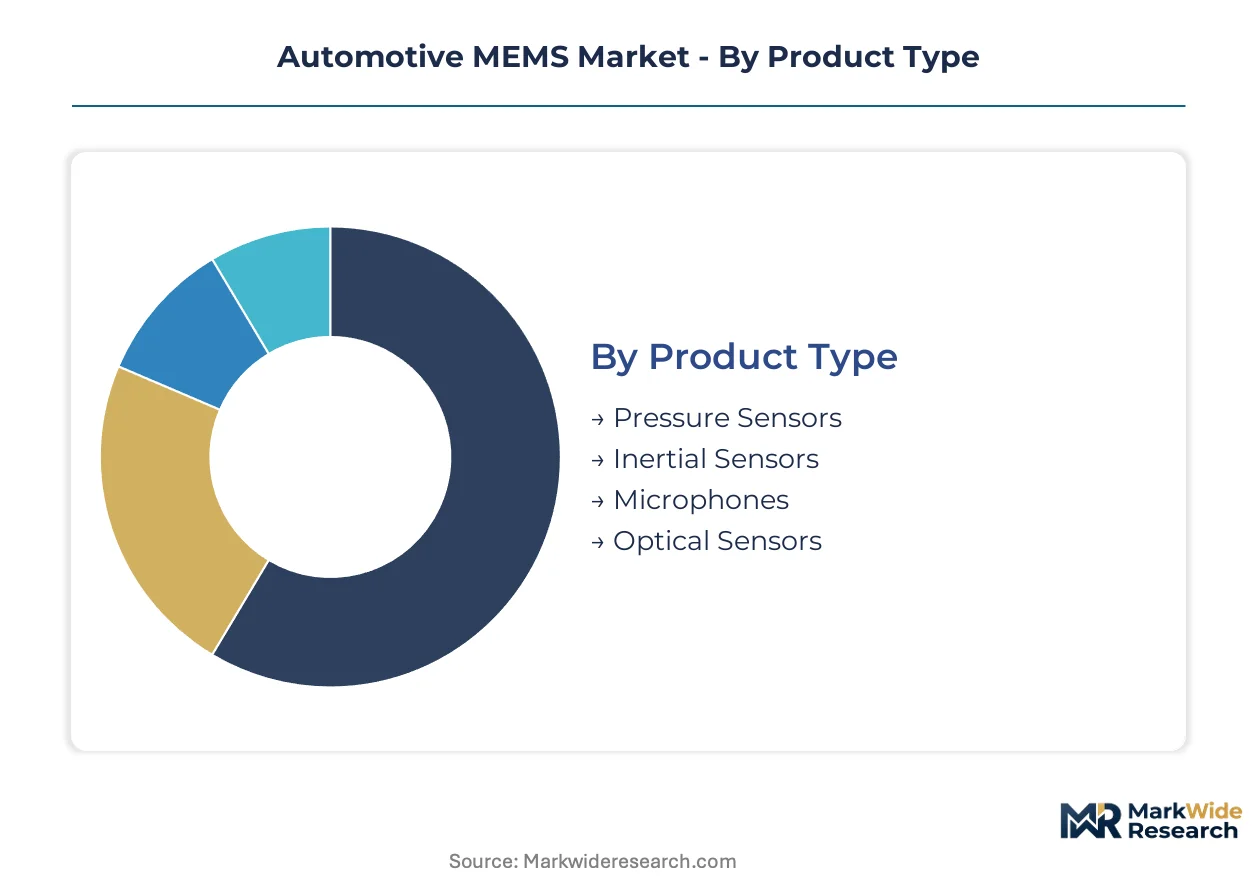
Automotive MEMS segmentation reflects divergent technical requirements across safety-critical and comfort-oriented vehicle systems. Product architecture, signal processing method, and supply chain position each create distinct competitive arenas with specialized qualification protocols.
Product Type:
Use-case spectrum spans propulsion monitoring, occupant protection, cabin experience, and autonomous perception layers.
- Pressure Sensors:Capacitive and piezoelectric MEMS measure absolute and differential pressure in tire, manifold, and HVAC applications. NHTSA TPMS mandates and ECE R64 protocols in Europe sustain volume concentration in passenger vehicle platforms.
- Inertial Sensors:Accelerometers and gyroscopes fabricated through deep reactive-ion etching detect linear acceleration and rotational velocity for electronic stability control. ASIL-D qualification requirements extend development timelines for safety-critical chassis applications.
- Microphones:Acoustic sensing nodes enable road-noise cancellation and voice interface activation. Premium cabin configurations now integrate six to eight MEMS microphones per vehicle.
- Optical Sensors:Micro-mirror arrays and photodiode structures support lidar beam steering and ambient light detection. Solid-state architectures are collapsing mechanical complexity in autonomous perception stacks.
Established volume favors Pressure Sensors; emerging adoption favors Microphones.
End User:
Procurement authority concentrates at platform-scale manufacturers with multi-year vehicle program commitments.
- OEMs:Volkswagen Group, Toyota, and Stellantis negotiate direct sensor supply agreements with annual price-down schedules. Consolidated platform procurement compresses supplier qualification timelines from multi-year frameworks to volume-guaranteed arrangements.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG integrate MEMS die into module assemblies for engine management and safety systems. These suppliers absorb ASIL certification costs and manage second-source qualification commitments.
- Aftermarket Providers:Replacement sensor distribution serves vehicle aging populations in Germany, Japan, and the United States. REACH and RoHS compliance constraints limit material choices for repair channel inventory.
- Fleet Operators:Commercial vehicle aggregators procure tire pressure and telematics sensors at fleet-scale pricing. Predictive maintenance algorithms drive sensor refresh cycles in logistics and ride-hail applications.
Platform control favors OEMs; margin capture favors Tier-1 Suppliers.
Technology:
Signal conditioning architecture determines integration complexity and electromagnetic compatibility performance.
- Analog:Continuous voltage output MEMS require external analog-to-digital conversion but offer lowest latency for engine control loops. Legacy powertrain architectures in commercial vehicles sustain analog sensor deployment.
- Digital:I2C and SPI interface protocols embed calibration coefficients and diagnostic flags within the sensor package. Digital integration is climbing the fastest in new vehicle platforms with centralized electronic architectures.
- Wireless:Battery-less passive sensors communicate via RFID or energy harvesting for tire pressure and brake wear monitoring. Elimination of wired harnesses reduces assembly weight in electric vehicle platforms.
- MEMS Microphones:Piezoelectric and capacitive acoustic transducers integrate analog-to-digital converters for digital audio bus connectivity. PDM output formats enable array synchronization for beamforming applications.
Legacy compatibility favors Analog; architecture consolidation favors Digital.
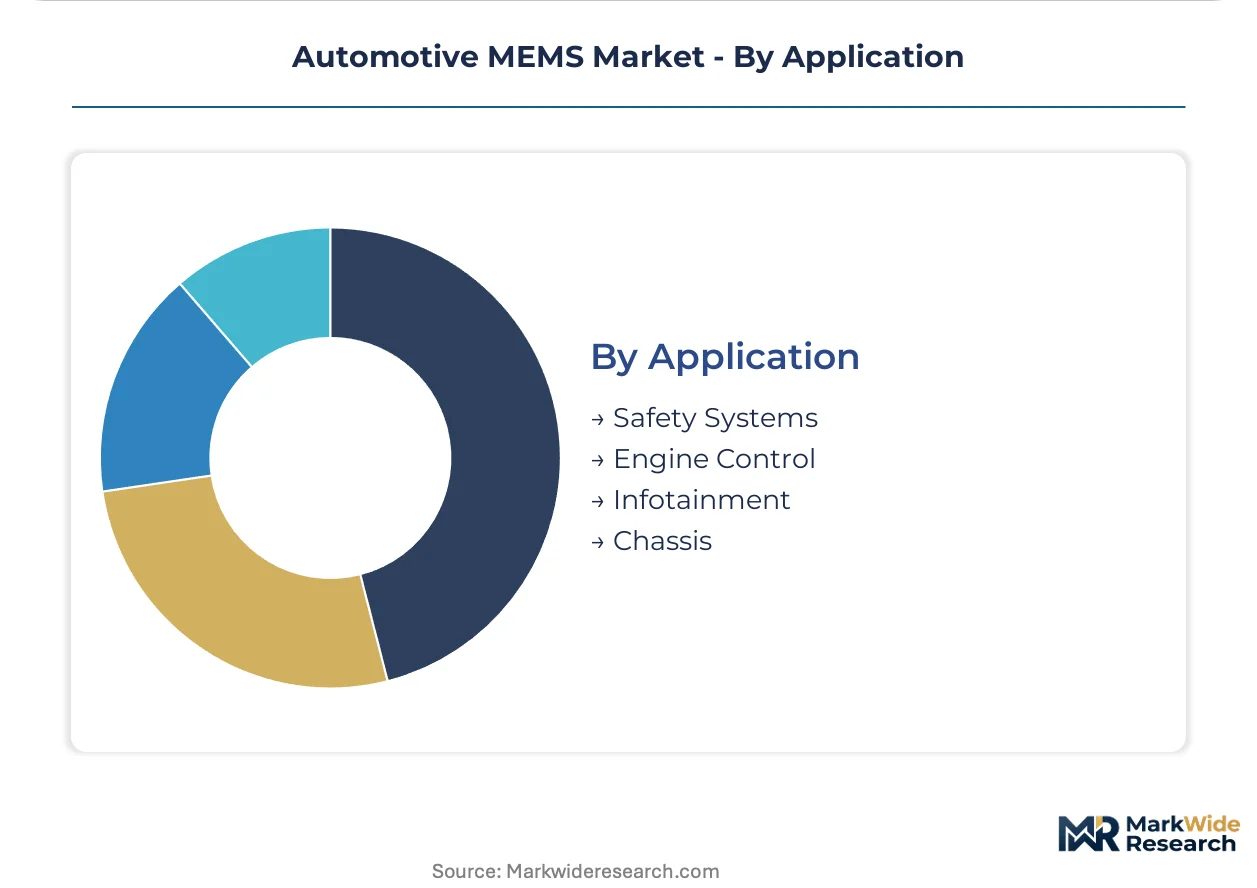
Application:
Functional domain dictates performance thresholds, environmental tolerance, and regulatory qualification intensity.
- Safety Systems:Airbag deployment sensors and electronic stability control units demand ASIL-D functional safety certification. ISO 26262 validation protocols extend development cycles substantially versus industrial-grade equivalents.
- Engine Control:Manifold absolute pressure and exhaust gas sensors operate in high-temperature combustion environments. Platinum group metal catalyst coatings expose bill-of-materials to palladium and rhodium price volatility.
- Infotainment:Microphone arrays and ambient light sensors enhance cabin experience with relaxed qualification requirements. Voice interface penetration is expanding acoustic node counts fastest in premium vehicle segments.
- Chassis:Ride height and suspension position sensors enable adaptive damping and headlamp leveling. MIIT vehicle safety standards in China are accelerating local sourcing requirements for chassis stabilization systems.
Regulatory intensity favors Safety Systems; volume expansion favors Infotainment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive-grade MEMS fabrication capacity clusters in Germany, Japan, and the United States, creating geographic concentration risk for second-source qualification. OEM procurement power concentrates at platform-scale manufacturers in these three markets, while China accelerates domestic wafer fabrication investments to reduce import dependency.
United States
NHTSA TPMS mandates and EPA emissions verification sustain volume demand for pressure and exhaust gas sensors across passenger and commercial vehicle fleets. The Inflation Reduction Act incentivizes domestic semiconductor manufacturing, accelerating foundry investments in Arizona and Texas. Detroit-area OEMs negotiate direct sensor supply agreements with annual price-down schedules and volume guarantees.
Germany
Volkswagen Group, BMW, and Mercedes-Benz consolidate platform procurement, compressing supplier qualification timelines from multi-year frameworks to annual arrangements. REACH and RoHS compliance constrain material choices for exhaust gas sensors, accelerating design refresh cycles. Baden-Württemberg and Bavaria concentrate foundry capacity and Tier-1 module assembly operations for chassis stabilization systems.
China
MIIT vehicle safety standards and domestic EV platform scale accelerate local sourcing requirements for inertial measurement units. Dual carbon goals and domestic substitution policies drive wafer fabrication investments in Shanghai and Shenzhen. Yangtze River Delta clusters host emerging MEMS packaging operations serving BYD, NIO, and XPeng platform demands.
Japan
Toyota and Honda procurement consolidation favors suppliers with captive foundry investments and long-term die bank arrangements. METI industrial policy supports piezoelectric MEMS process development for high-temperature engine applications. Nagoya and Tokyo metropolitan areas concentrate design activity for safety-critical inertial sensors with ASIL-D qualification.
South Korea
Hyundai Motor Group and Kia platform scale drives sensor node proliferation for ADAS and electronic stability control systems. MFDS automotive component standards align with global functional safety protocols, easing export qualification. Seoul Capital Area fabs supply domestic OEMs while expanding packaging capacity for microphone arrays in premium cabin configurations.
Automotive MEMS Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with die-level supply relationships. The vendor base stratifies between vertically integrated IDMs controlling wafer fabrication and fabless design houses outsourcing to automotive-qualified foundries. Three archetypes dominate: captive foundry operators, multi-product semiconductor conglomerates, and acoustic sensing specialists. Competitive moves concentrate on backward integration into wafer fabrication and long-term die bank arrangements with OEM electronic architecture teams.
Among European-based fabricators, Robert Bosch GmbH and STMicroelectronics occupy positions as archetypal vertically integrated suppliers, while Infineon Technologies AG anchors the safety-critical sensor tier with ASIL-qualified portfolios. These three represent the dominant competitive anchors in automotive-grade MEMS, each exemplifying distinct strategic positioning around manufacturing control, R&D intensity, and functional safety certification depth.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| STMicroelectronics |
| Analog Devices, Inc. |
| Continental AG |
| Denso Corporation |
| Infineon Technologies AG |
| NXP Semiconductors |
| Sensata Technologies |
| TDK Corporation |
| Others |
Supply Flow & Price Mechanics
Palladium and rhodium price volatility in exhaust gas sensor catalyst coatings compresses margin structures across OEM and aftermarket tiers while forcing dual-sourcing strategies in procurement contracts. This commodity exposure widens pricing spreads between ASIL-certified safety-critical sensors and industrial-grade equivalents, with foundry concentration in Germany and Japan amplifying geographic risk premiums.
Pricing Analysis
ISO 26262 functional safety certification dictates the pricing tier structure across automotive MEMS procurement. Three-tier pricing stratifies across ASIL-D qualified, ASIL-B compliant, and non-safety-critical economy grades. Price differentiation centers on validation timeline costs and platinum group metal content in exhaust applications. Cost compression in economy-tier pressure sensors intensifies as Chinese wafer fabrication capacity expands. Fleet operators exhibit highest price sensitivity due to volume-scale procurement, while premium OEM platform contracts absorb certification premiums through multi-year die bank arrangements.
Supply Chain Analysis
Robert Bosch GmbH, STMicroelectronics, and Infineon Technologies AG control captive foundry capacity for automotive-grade MEMS fabrication. Supply concentrates in Germany, Japan, and the United States, with emerging packaging investments in China's Yangtze River Delta. Raw material dependencies rest on silicon wafers, platinum group metals for exhaust sensors, and aluminum nitride thin films for piezoelectric architectures. Single-source vulnerability pervades ASIL-D qualified inertial sensor qualification, where second-source timelines extend 18-24 months. Distribution runs through Tier-1 module integrators to OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive MEMS sector sits at an inflection driven by solid-state lidar convergence and F-Gas refrigerant sensor mandates, creating asymmetric growth windows across acoustic and optical sensing categories.
For Market Incumbents: Insulate ASIL-D certification moats through accelerated piezoelectric process R&D in engine compartment applications. Prioritize captive foundry investments in Baden-Württemberg and Bavaria to secure wafer supply against Chinese capacity expansion. Consolidate long-term die bank arrangements with Volkswagen Group and Toyota platform teams before annual price-down schedules compress margins further. For New Entrants and Emerging Players: Pursue microphone array white space in premium cabin configurations, where six-to-eight sensor counts per vehicle outpace other categories. Target India's PLI scheme incentives for automotive component packaging to serve domestic OEM assembly growth. Lead with road-noise cancellation algorithm partnerships as the go-to-market angle rather than standalone hardware sales. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors acoustic sensing specialists with piezoelectric IP portfolios. Long-term viability hinges on content-per-vehicle expansion in EV platforms versus internal combustion engine sensor replacement cycles. Watch lidar-solid-state convergence milestones as the inflection signal for optical MEMS valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Piezoelectric Process Scale-Up | STMicroelectronics and Robert Bosch GmbH are displacing capacitive architectures in high-temperature engine applications. |
| ASIL-D Certification Acceleration | Infineon Technologies AG anchors safety-critical portfolios with ISO 26262 validation depth. |
| India Packaging Investment | PLI scheme incentives attract MEMS module assembly to serve BYD and Tata Motors platform demands. |
| Refrigerant Sensor Integration | F-Gas Regulation forces thermal management redesigns at valve block level across European HVAC platforms. |
| Die Bank Arrangement Structuring | Long-term volume guarantees with OEM electronic architecture teams lock in procurement consolidation. |
Methodological Framework
The analysis maps inertial, pressure, acoustic, and optical MEMS sub-sectors, each validated through Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and foundry operations managers. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA emissions filings, and UNECE ECE regulatory submissions anchored the evidence base. Bottom-up sensor content-per-vehicle modeling triangulated against top-down OEM platform scale estimates across the projection horizon.
Assumptions held fixed include NHTSA TPMS mandate continuity, REACH and RoHS material compliance, and MIIT vehicle safety standard enforcement. Variables tested encompass EV platform adoption curves, solid-state lidar penetration rates, and Chinese domestic substitution policy intensity. Segmentation dimensions modeled span product type, technology interface protocol, application functional domain, and end-user procurement authority. CAGRs derived from unit shipment trajectories and average selling price evolution across the analysis window, with platinum group metal cost pass-through and ASIL certification premium decay as key forecast inputs.
Sensitivities concentrate around refrigerant sensor mandate expansion, foundry geographic concentration risk, and platinum group metal price spike transmission. Forecasts reflect documented assumptions on regulatory enforcement and technology substitution timelines. Quarterly review of OEM platform procurement consolidation indicators and Chinese wafer fabrication capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
North America Sensor Market