
 IP Core Chip Market | 2026-2036
IP Core Chip Market Size, Share, and Industry Trends Forecast 2026-2036
IP Core Chip Market Foresight
Multi-source licensing of processor and interface cores is expanding as fabless designers diversify away from single-vendor dependencies. Arm Limited leverages its instruction-set architecture dominance to sustain royalty streams across mobile and automotive sockets. Synopsys Inc. anchors the physical IP layer with silicon-proven libraries that reduce time-to-tapeout for advanced nodes. Cadence Design Systems Inc. competes through integrated design-automation platforms that bundle verification tools with configurable core portfolios.
An IP core chip is a pre-designed, reusable semiconductor functional block—specified by register-transfer level code, gate-level netlists, or GDSII layout files—that system designers integrate into larger ASICs, SoCs, or FPGAs to accelerate development cycles and reduce non-recurring engineering costs. Processor cores command the largest revenue share due to their ubiquity in compute-intensive applications, while interface cores represent the fastest-expanding category as PCIe and DDR standards evolve to support higher bandwidth. SoC deployments absorb the majority of IP core volumes because consumer electronics and automotive OEMs demand tight integration of multiple functions on single die, whereas FPGA-based adoption is accelerating in industrial prototyping where reprogrammability offsets unit-cost premiums.
The FDA's software-as-medical-device framework and the EU AI Act's risk-classification system for embedded intelligence are reshaping validation requirements for IP cores deployed in healthcare and automotive systems. REACH substance restrictions and RoHS compliance mandates from ECHA constrain material choices in packaging and interconnect layers, adding qualification overhead for European-bound shipments. Stakeholders must monitor how jurisdictional fragmentation in semiconductor export controls and data-sovereignty rules affects cross-border licensing terms and foundry access for advanced-node production.
Market Dynamics
Automotive electrification and autonomous driving architectures are forcing semiconductor IP vendors to accelerate functional-safety certification cycles while compressing royalty structures for high-volume processor cores.
Growth Catalysts
- EU AI Act risk-classification mandates:Embedded intelligence in automotive and medical devices now requires traceable IP provenance, expanding demand for pre-certified core libraries that reduce compliance overhead for system integrators.
- Taiwan foundry-fabless clustering:Hsinchu Science Park's concentration of advanced-node production enables rapid core customization cycles, cutting time-to-tapeout for interface IP targeting PCIe 6.0 and DDR5 standards.
- RISC-V open-instruction-set momentum:Processor core licensing is fragmenting as fabless designers seek alternatives to proprietary architectures, particularly for edge-AI inference engines in industrial automation.
Market Restraints
- EUV lithography equipment scarcity:Advanced-node physical IP development faces capacity constraints as ASML's high-NA systems concentrate at select Taiwan and South Korea foundries, limiting second-source options.
- REACH substance restrictions:ECHA's evolving chemical bans constrain packaging material choices for European-bound IP core shipments, adding qualification cycles that extend product launch timelines.
- Functional-safety certification costs:ISO 26262 and IEC 61508 compliance for automotive and industrial cores demands specialized engineering resources that smaller IP vendors struggle to maintain.
Strategic Opportunities
- India's PLI scheme for semiconductor design:Government incentives for chip design centers in Bengaluru and Hyderabad are attracting IP core development operations seeking lower-cost engineering talent pools.
- Chiplets and 2.5D/3D integration:Disaggregated SoC architectures are creating demand for die-to-die interconnect IP and standardized interface tiles that bridge heterogeneous process nodes.
- FDA software-as-medical-device pathways:Streamlined premarket review for algorithm-driven diagnostics is expanding addressable market for neural-network accelerator cores in portable imaging and monitoring equipment.
Industry Challenges
- Verification engineering talent scarcity:Formal methods and emulation expertise for complex SoC integration are concentrating at established vendors, constraining mid-tier IP houses' ability to scale customer support.
- Cross-jurisdictional export control alignment:Fragmented semiconductor licensing restrictions between US BIS, EU dual-use regulations, and China's technology transfer rules complicate multi-site development workflows.
- Legacy node support obligations:Long-tail demand for mature-process IP in industrial and automotive sectors forces vendors to maintain obsolete tool chains that divert R&D resources from advanced-node development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IP Core Chip Market |
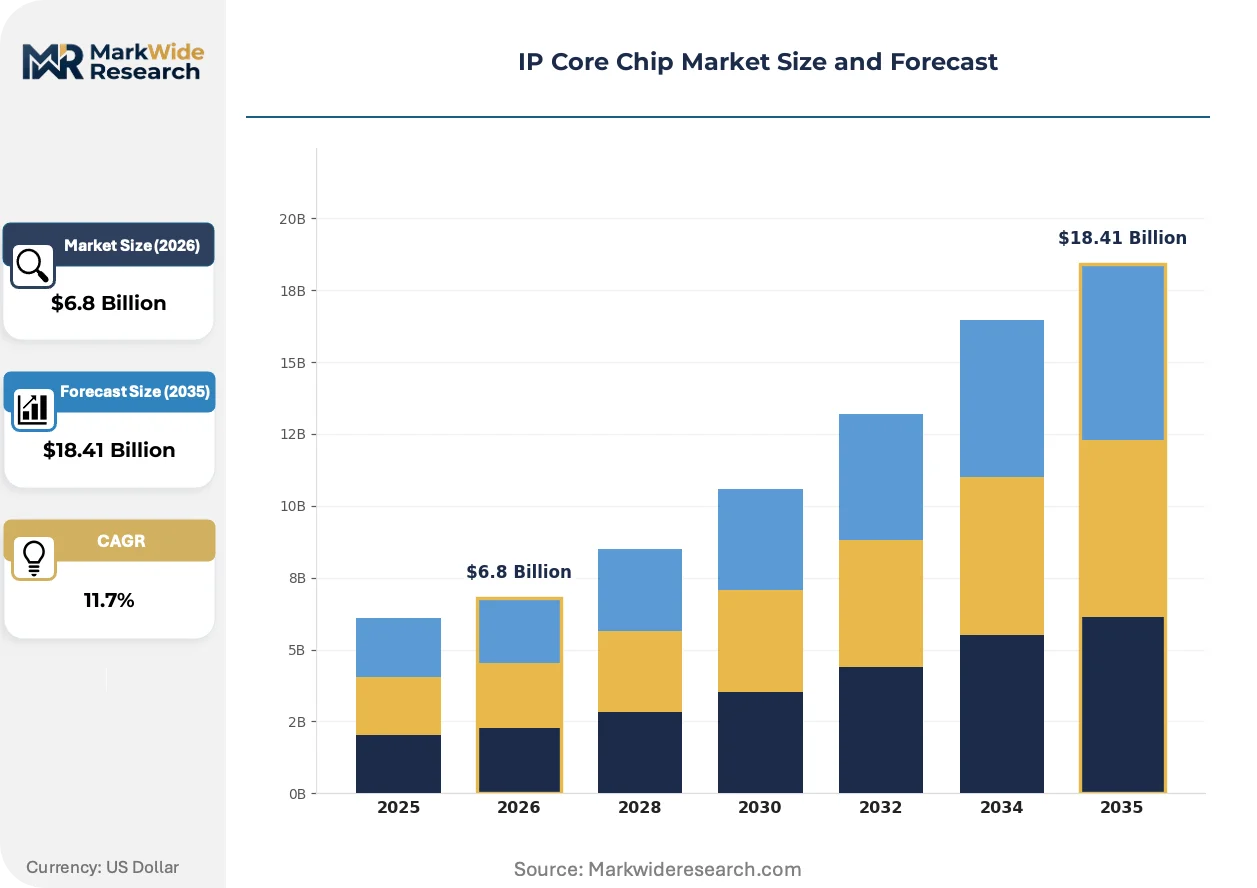
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $18.41 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processor Cores, Memory Cores, DSP Cores, Interface Cores Technology: ASIC, FPGA, SoC, CPLD End User: Telecommunications, Consumer Electronics, Automotive, Industrial Deployment: On-Premises, Cloud, Hybrid, Embedded |
| Companies Covered | Arm Limited, Synopsys Inc., Cadence Design Systems Inc., Imagination Technologies Limited, Rambus Inc., CEVA Inc., Achronix Semiconductor Corporation, ALPHAWAVE SEMI, SiFive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IP Core Chip Market Shifts & Advancements
Functional-safety requirements and disaggregated packaging architectures are reshaping how processor and interface cores are specified, verified, and monetized across automotive, medical, and industrial verticals.
Chiplets with standardized die-to-die interconnects are overtaking monolithic SoC designs for high-performance computing and AI accelerators. AMD and Intel have deployed multi-tile processors in data center sockets, establishing UCIe as the dominant physical-layer standard. This modular approach is compressing non-recurring engineering costs by allowing heterogeneous integration of logic, memory, and I/O tiles fabricated on optimal process nodes.
REACH and RoHS substance restrictions from ECHA are tightening material compliance for European-bound semiconductor IP shipments. Packaging interconnects and substrate materials face new substance scrutiny that extends qualification timelines for automotive-qualified cores. Vendors are responding by pre-certifying IP libraries against evolving chemical bans, particularly for high-reliability applications in German and French automotive supply chains.
Buyer consolidation among hyperscale cloud operators and top-tier automotive OEMs is concentrating procurement leverage for processor core licensing. Amazon Web Services, Microsoft Azure, and Google Cloud now negotiate enterprise-wide architecture licenses that displace per-unit royalty models for data center infrastructure. This shift is most pronounced in North American and Chinese cloud buildouts, where custom silicon programs demand predictable IP cost structures across multi-year deployment horizons.
IP Core Chip Market Segmentation
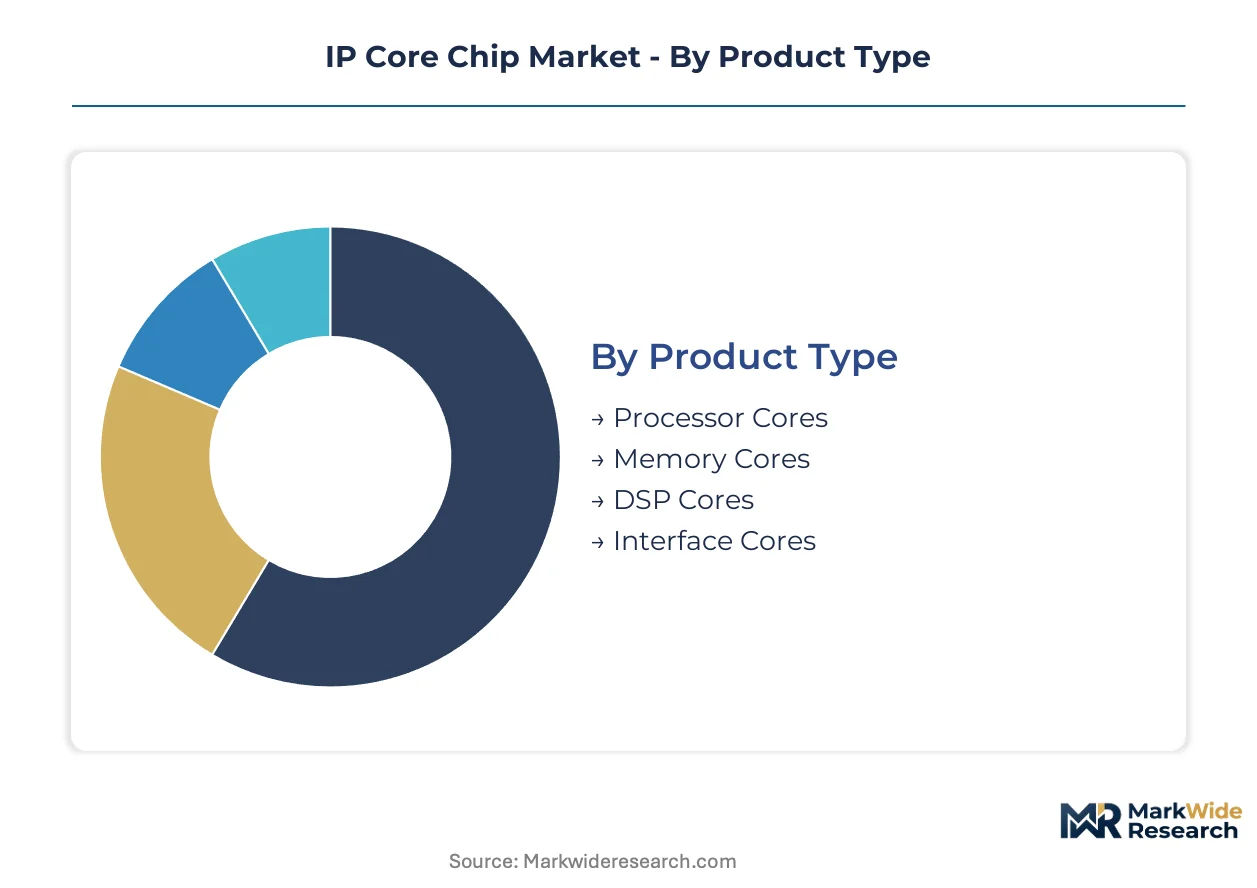
IP core chip segmentation reveals how architectural choices cascade through licensing economics and foundry partnerships. Product type determines royalty structures, while deployment mode shapes verification complexity and time-to-revenue for semiconductor vendors.
Product Type:
Processor cores attract fundamentally different buyers than memory or interface cores—compute-intensive applications demand ISA flexibility, while bandwidth-centric workloads prioritize PHY layer performance.
- Processor Cores:CPU, GPU, and NPU implementations specified by RTL or hardened layout dominate licensing revenue. Automotive OEMs in Germany and Japan are procuring Arm and RISC-V cores for ADAS compute clusters under ISO 26262 functional-safety mandates.
- Interface Cores:PCIe, DDR, and USB PHY and controller IP are expanding fastest as data center operators in the US and China upgrade to PCIe 6.0 and DDR5 standards. Taiwan's Hsinchu cluster accelerates customization cycles for these high-speed serial interfaces.
- Memory Cores:SRAM, ROM, and register file compilers target process-specific optimization. Foundry-fabless partnerships in South Korea concentrate demand for memory compiler IP at advanced nodes.
- DSP Cores:Fixed-point and floating-point signal processing engines serve audio, radar, and baseband applications. Industrial automation vendors in Japan leverage DSP cores for motor control and vibration analysis.
Processor cores lead volumes today; interface cores are climbing the fastest as bandwidth requirements escalate across cloud and automotive verticals.
Technology:
Silicon implementation technology segments buyers by non-recurring engineering tolerance and volume certainty—ASIC commitments demand million-unit confidence, while FPGA flexibility commands per-unit premiums.
- ASIC:Full-custom or semi-custom designs taped out at foundries offer optimal power-performance-area metrics. Hyperscale operators in the US and China commission ASIC implementations for AI training accelerators where unit economics justify massive NRE investments.
- SoC:System-on-chip integration of multiple IP blocks dominates consumer electronics and automotive deployments. Taiwan's foundry ecosystem enables rapid SoC iterations for smartphone and EV infotainment platforms.
- FPGA:Field-programmable gate arrays from vendors like Xilinx and Intel absorb IP cores for prototyping and low-volume production. Industrial equipment manufacturers in Germany favor FPGA-based motor control systems where reprogrammability offsets unit cost.
- CPLD:Complex programmable logic devices address glue logic and simple state machines in legacy industrial systems. Mature-node CPLD deployments persist in automotive body electronics where certification stability outweighs performance demands.
SoC implementations capture the largest volume base; ASIC deployments show the steepest expansion trajectory as cloud custom silicon programs multiply.
End User:
End-user segmentation maps IP core demand to sector-specific certification regimes—automotive requires ISO 26262 traceability, while medical devices trigger FDA software-as-medical-device pathways.
- Automotive:Electrification and autonomous driving architectures are consuming processor and interface cores for domain controllers and sensor fusion. German OEMs and their Tier-1 suppliers in Bavaria and Baden-Württemberg dominate procurement of safety-certified IP.
- Telecommunications:5G baseband and optical transport equipment demand DSP and high-speed interface cores. China's MIIT licensing timelines shape deployment schedules for domestic 5G infrastructure vendors.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs integrate application processors and multimedia subsystems. South Korean and Chinese handset manufacturers concentrate procurement leverage for mobile-optimized core libraries.
- Industrial:Factory automation, robotics, and process control systems leverage real-time processor cores and deterministic interface IP. Japanese machinery builders in the Nagoya and Osaka industrial belts specify IEC 61508-compliant cores for safety-critical applications.
Consumer electronics maintains volume leadership; automotive is expanding most quickly as software-defined vehicle architectures proliferate.
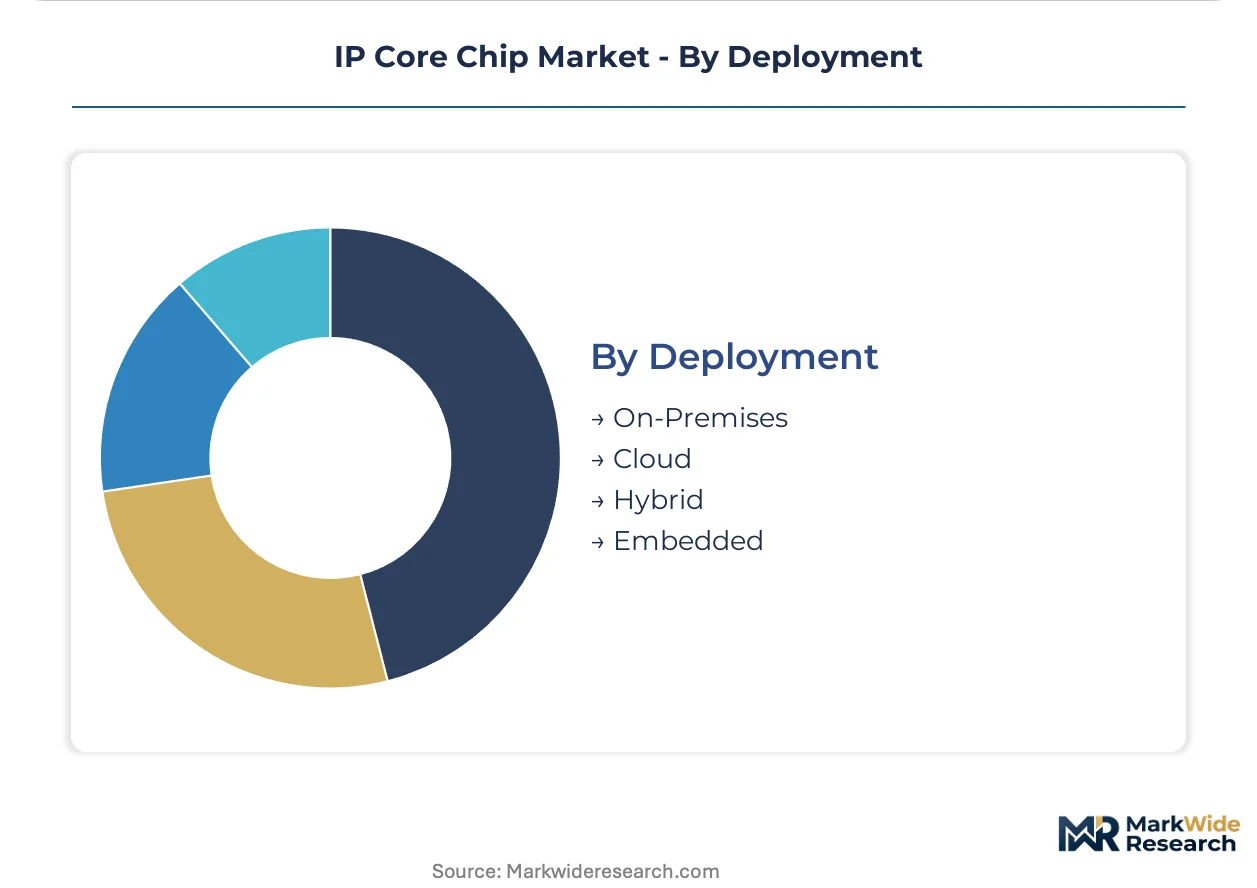
Deployment:
Deployment mode determines how IP cores are verified, integrated, and monetized—cloud-based emulation accelerates validation, while embedded deployments demand rigorous physical signoff.
- Embedded:Cores integrated directly into end-product silicon dominate automotive and industrial applications where deterministic performance is mandatory. Bosch and Continental in Germany specify embedded processor cores with lock-step redundancy for braking and steering systems.
- On-Premises:Enterprise data centers and private infrastructure deploy custom silicon with licensed IP cores for security and latency control. US financial services firms in New York and Chicago procure on-premises encryption accelerators to satisfy regulatory data-sovereignty requirements.
- Cloud:Cloud service operators commission custom ASICs with licensed cores for AI inference and networking virtualization. AWS, Microsoft Azure, and Google Cloud negotiate enterprise-wide architecture licenses displacing per-unit royalty models.
- Hybrid:Workload-specific partitioning between edge and cloud resources shapes core selection for IoT gateways and smart city infrastructure. Singapore's government technology stack deploys hybrid architectures combining local inference with cloud training.
Embedded deployment leads current volumes; cloud deployment is gaining share fastest as hyperscale infrastructure buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park concentrates the densest cluster of IP core customization activity, with foundry-fabless partnerships compressing development cycles for advanced-node interface IP.
United States
Hyperscale cloud operators in Seattle and Northern California commission custom AI accelerators with enterprise-wide architecture licenses. FDA software-as-medical-device pathways expand neural-network accelerator demand for portable diagnostics. Austin and Boston house specialized verification engineering pools supporting automotive functional-safety certification.
Taiwan
Foundry-fabless collaboration at Hsinchu Science Park accelerates PCIe 6.0 and DDR5 interface core development. The National Development Council's semiconductor initiatives reinforce advanced-node physical IP investment. Tapeout cycles for consumer SoCs now measure weeks rather than months.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg procure ISO 26262-certified processor cores for domain controllers and sensor fusion. ECHA REACH substance restrictions extend qualification timelines for packaging materials. Stuttgart and Munich anchor Tier-1 supplier engineering centers specifying lock-step redundant cores.
China
Domestic 5G infrastructure vendors under MIIT licensing timelines consume DSP and high-speed interface cores. MIIT's integrated circuit promotion policies subsidize RISC-V processor development for edge-AI applications. Shanghai and Beijing host design centers targeting heterogeneous integration for AI training accelerators.
South Korea
Memory compiler IP demand concentrates at Samsung and SK Hynix foundry partnerships for advanced-node DRAM integration. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative expands design center capacity. Seoul and Suwon house application processor teams for smartphone OEMs.
IP Core Chip Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue open-instruction-set alternatives and chiplet interconnect specialization. The vendor base stratifies across three tiers: architecture licensors commanding royalty streams, physical IP providers with silicon-proven libraries, and configurable core specialists bundling verification tools. Dominant competitive moves include strategic partnerships with foundry ecosystems and portfolio diversification into functional-safety-certified libraries.
Within the architecture-licensor tier, Arm Limited and Synopsys Inc. exemplify divergent monetization models—one leveraging ISA dominance across mobile and automotive sockets, the other anchoring physical IP layers with design-automation integration. Cadence Design Systems Inc. occupies a position bridging configurable core portfolios with emulation and verification platforms. Among emerging challengers, SiFive and ALPHAWAVE SEMI represent the open-instruction-set and high-speed-serial-interface archetypes respectively.
| Leading Market Players |
|---|
| Arm Limited |
| Synopsys Inc. |
| Cadence Design Systems Inc. |
| Imagination Technologies Limited |
| Rambus Inc. |
| CEVA Inc. |
| Achronix Semiconductor Corporation |
| ALPHAWAVE SEMI |
| SiFive |
| Others |
Supply & Pricing Matrix
ECHA REACH substance restrictions gate qualified supply for European-bound IP core shipments and premium-tier pricing access for automotive-qualified libraries. Fabless designers face extended qualification timelines that compress margins on standard-tier cores while concentrating pricing power with vendors holding pre-certified physical IP portfolios.
Pricing Analysis
Input-cost pass-through from EUV lithography equipment scarcity and specialized verification engineering talent feeds directly into licensing premiums for advanced-node processor cores. Pricing stratifies across functional-safety-certified, silicon-proven, and unverified tiers, with ISO 26262 compliance commanding substantial premiums. Cost compression in consumer electronics processor cores intensifies as hyperscale cloud operators negotiate enterprise-wide architecture licenses displacing per-unit royalty models. Automotive OEMs show least price sensitivity due to liability exposure, while industrial automation vendors exhibit highest sensitivity given mature-process volume constraints.
Supply Chain Analysis
Domestic-content mandates under China's MIIT integrated circuit promotion policies and India's PLI scheme for semiconductor design are reshaping sourcing patterns for RISC-V processor development. Supply concentrates in Taiwan's Hsinchu Science Park, South Korea's memory foundry partnerships, and US hyperscale design centers. Raw material dependencies span EUV-grade silicon wafers, advanced packaging substrates, and specialized EDA tool licenses. Single-source vulnerability at ASML's high-NA lithography systems creates chokepoint exposure. Distribution runs through direct foundry-fabless partnerships for advanced nodes and IP aggregator platforms for mature-process libraries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IP core chip market reads as a late-cycle quality story as automotive electrification shifts procurement toward ISO 26262-certified processor and interface cores with traceable provenance.
For Market Incumbents: To counter RISC-V open-instruction-set fragmentation eroding proprietary ISA royalty streams, Arm Limited and Synopsys Inc. must deepen functional-safety certification investments for automotive domain controllers while securing exclusive foundry partnerships at Taiwan's Hsinchu cluster to lock in advanced-node physical IP access.
For New Entrants and Emerging Players: Begin with India's PLI-subsidized design centers in Bengaluru and Hyderabad to access lower-cost verification engineering pools, then target industrial automation's edge-AI inference segment where RISC-V momentum outpaces proprietary architecture lock-in, leveraging chiplet interconnect specialization as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Roll-up economics work for verification-tool-integrated IP specialists because formal methods and emulation expertise concentrate at established vendors, constraining mid-tier houses' scaling capacity. Five-to-ten-year viability favors targets with FDA software-as-medical-device pathway experience and UCIe die-to-die interconnect portfolios. Monitor hyperscale cloud operator custom silicon program cancellations as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional-Safety Certification Investment | ISO 26262 pre-certification reduces automotive OEM compliance overhead and accelerates design wins at German Tier-1 suppliers. |
| Foundry-Fabless Partnership Deepening | Taiwan Hsinchu cluster collaboration compresses PCIe 6.0 and DDR5 interface core tapeout cycles to weeks. |
| RISC-V Open-ISA Platform Development | Processor licensing fragmentation creates alternatives to Arm dominance in edge-AI inference for industrial automation. |
| Chiplet Interconnect IP Specialization | UCIe-standardized die-to-die tiles enable heterogeneous integration bridging logic, memory, and I/O at optimal process nodes. |
| India Design Center Expansion | PLI scheme incentives in Bengaluru and Hyderabad attract IP core development seeking lower-cost verification engineering talent. |
Research Methodology
Multiple input streams — primary interviews with fabless design executives, foundry technology officers, and automotive Tier-1 procurement leads; secondary validation against SEC filings, MIIT policy documents, and ECHA substance restriction updates; plus customs data on semiconductor IP licensing flows — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical shipment patterns for processor, interface, memory, and DSP cores were cross-referenced against expert panel assessments of RISC-V adoption trajectories and functional-safety certification timelines. The analytical framework modeled product type, silicon implementation technology, end-user vertical, and deployment mode across the projection horizon, with CAGRs derived from elasticity analysis of foundry capacity expansion and hyperscale cloud capex cycles.
Caveats apply where EUV lithography equipment delivery delays, REACH substance restriction scope expansions, or cross-jurisdictional export control alignment failures could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Microserver Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Global AI Processor Market