
 PC Processor Market | 2026-2036
PC Processor Market Size, Share, and Industry Trends Forecast 2026-2036
PC Processor Market Intelligence
The adoption of chiplet-based architectures over monolithic die designs is fragmenting the traditional processor manufacturing model. Advanced Micro Devices (AMD) leverages this modular approach to accelerate product development cycles across its CPU and GPU lines. Intel Corporation competes by investing heavily in its advanced packaging technologies like Foveros to connect different chiplets. Meanwhile, Apple differentiates through its tight integration of custom silicon, like the M-series chips, within its closed hardware and software ecosystem.
A PC processor is a microchip, fabricated on a silicon wafer using advanced lithography, that serves as the central processing unit for personal computers. It executes fundamental instructions by performing arithmetic, logic, controlling, and input/output operations, often utilizing billions of FinFET transistors. While desktop processors remain a core revenue stream, laptop processors are seeing accelerated innovation driven by power efficiency demands. Demand for smaller process nodes, specifically 7nm and 5nm technology, is intensifying due to performance requirements in gaming and workstation applications.
Export controls managed by the US Department of Commerce and China's "dual carbon goals" are influencing semiconductor supply chains and material sourcing. Intellectual property frameworks enforced by organizations like the WTO are critical for safeguarding R&D investments in new architectures. Navigating the complex landscape of geopolitical trade restrictions and securing access to advanced manufacturing capacity will define competitive success for processor designers and manufacturers.
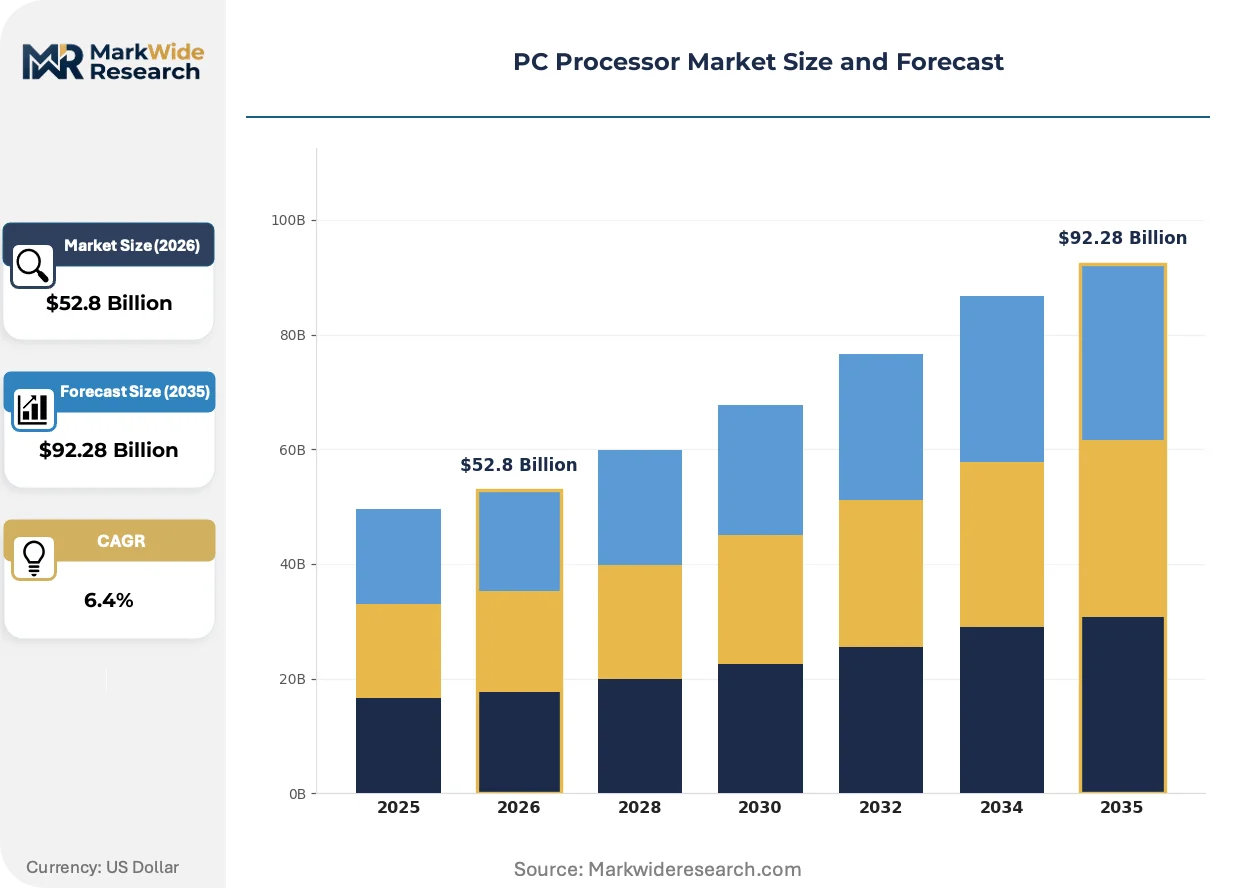
Market Dynamics
The fundamental shift from monolithic to modular, chiplet-based processor design is the central structural force shaping the market. This architectural transition redefines manufacturing processes, accelerates development cycles, and intensifies competition around advanced packaging and interconnect technologies.
Growth Catalysts
- Gaming and Workstation Demand:The performance requirements of high-fidelity gaming and professional content creation, including 3D rendering and AI model training, drive the need for processors with higher core counts and clock speeds.
- Advanced Process Nodes:The industry-wide migration to smaller lithography, including 7nm and 5nm technology, enables significant improvements in transistor density, performance, and power efficiency, which are critical for all PC segments.
- National Semiconductor Initiatives:Government-led programs, particularly in China, to foster domestic semiconductor self-sufficiency are stimulating investment in local design, manufacturing, and supply chain capabilities, creating new pockets of demand.
Market Restraints
- Extreme Ultraviolet Lithography Costs:The immense capital expenditure and operational complexity associated with EUV lithography machines, essential for manufacturing nodes below 7nm, create a significant financial barrier to entry and expansion.
- Foundry Concentration:The geographic concentration of leading-edge semiconductor foundries, primarily in Taiwan and South Korea, exposes the global supply chain to significant geopolitical risks and potential disruptions.
- Export Controls:Restrictions imposed by the US Department of Commerce on the sale of advanced semiconductor technology and manufacturing equipment to certain entities limit market access and hinder international technology collaboration.
Strategic Opportunities
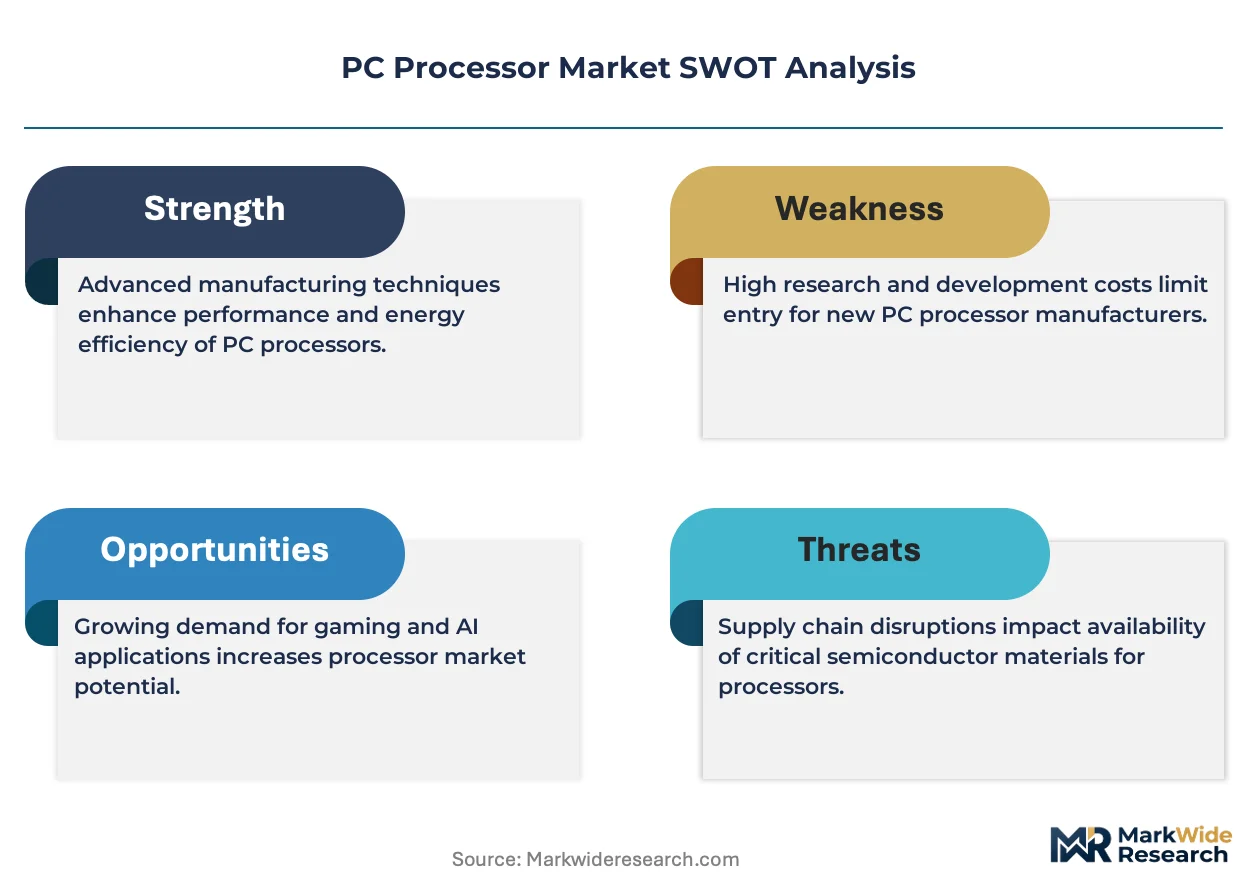
- On-Device AI Acceleration:Developing processors with integrated Neural Processing Units (NPUs) creates an opportunity to capture value from the growing demand for responsive, power-efficient AI inference in applications like real-time translation and image enhancement.
- Custom Silicon for Verticals:Designing application-specific processors optimized for niche but high-value workloads, such as financial modeling or scientific simulation, offers a path to differentiation beyond mainstream consumer CPUs.
- Emerging Market PC Penetration:Expanding the availability of affordable, energy-efficient processors for entry-level laptops and desktops can unlock substantial volume growth in developing economies across Southeast Asia and Africa.
Industry Challenges
- Advanced Packaging Talent:A persistent shortage of engineers with expertise in 3D stacking, die-to-die interconnects, and thermal management for multi-chiplet modules constrains the pace of innovation in advanced packaging.
- Intellectual Property Licensing:Navigating the intricate web of patents and cross-licensing agreements for core technologies like instruction set architectures and memory interfaces creates legal and financial overhead for new entrants.
- Fabrication Plant Lead Times:The multi-year timeline and massive capital investment required to construct and qualify a new semiconductor fabrication facility create a significant lag between investment decisions and production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PC Processor Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Processors, Laptop Processors, Server Processors, Embedded Processors Technology: 14nm, 10nm, 7nm, 5nm, 3nm Application: Gaming, Workstations, Data Centers, Virtual Reality, Edge Computing End User: Original Equipment Manufacturers, System Integrators, Cloud Service Providers, Research Labs |
| Companies Covered | Apple, Lenovo, Intel Corporation, Dell Technologies, HP Inc., Advanced Micro Devices (AMD), NVIDIA Corporation, Cerebras Systems, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PC Processor Market Strategic Shifts & Innovations
Specialization is the dominant theme in processor innovation, moving the market away from general-purpose computing toward heterogeneous architectures. Processors increasingly integrate dedicated hardware blocks to accelerate specific tasks like AI, graphics, and video processing, reshaping product differentiation.
Chiplet-based design is a modular approach that constructs a processor from multiple smaller, specialized dies. This method is gaining rapid adoption in high-performance desktop and server segments due to its improved yields and design flexibility. This architectural shift is hybridizing processor manufacturing, allowing for the combination of dies produced on different process nodes within a single, cost-effective package.
China's "dual carbon goals" are influencing semiconductor manufacturing practices within the country. The policy pressures foundries to reduce their environmental footprint, which involves adopting greener chemicals, improving water recycling, and increasing the use of renewable energy in fabrication. This sustainability push most affects high-volume manufacturers, who are now integrating energy efficiency metrics into their operational planning and equipment sourcing.
Buyer preference is shifting from evaluating CPUs on raw clock speed to assessing performance on specific, real-world applications. The traditional model of a single, monolithic CPU is being challenged by demand for processors with integrated, specialized accelerators for AI and media workloads. This trend is most visible in the laptop market, where power-efficient performance in tasks like video conferencing and content creation is a key purchasing driver.
PC Processor Market Segmentation
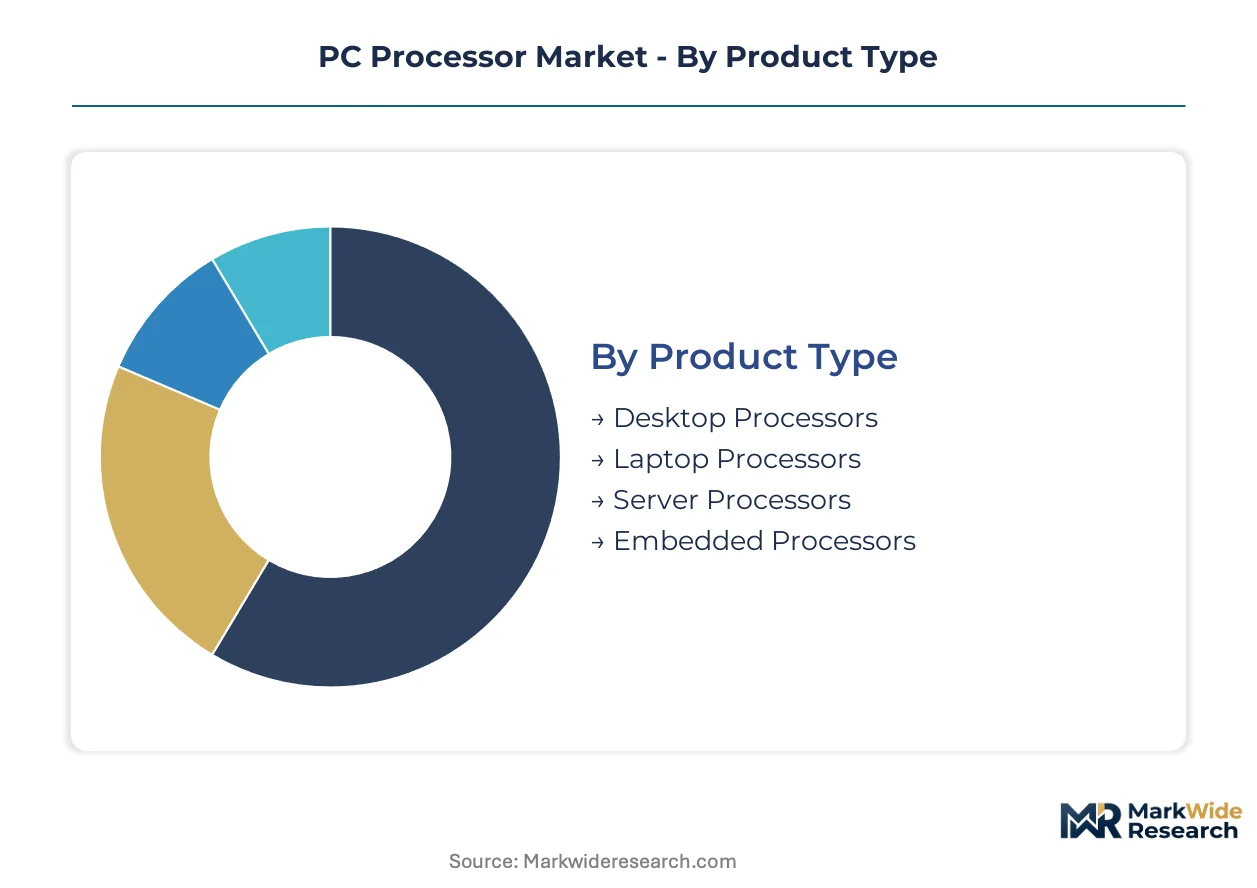
Understanding the segmentation of the PC processor market is essential for identifying distinct demand patterns and technological priorities. This analysis delineates the market across critical dimensions, revealing the nuanced forces that shape product development and competitive strategies for manufacturers.
Product Type:
Processor product types exhibit varying development cycles and market lifespans, influencing investment priorities for manufacturers.
- Laptop Processors:These microchips are optimized for power efficiency and integrated graphics, crucial for portable computing devices. Demand is accelerating in emerging markets for affordable, energy-efficient models.
- Server Processors:High-core-count, multi-threaded silicon designed for continuous operation in data centers and cloud infrastructure. Demand is concentrated in hyperscale data centers requiring robust performance for AI model training.
- Desktop Processors:General-purpose CPUs for personal computers, balancing performance and cost for diverse user needs.
- Embedded Processors:Specialized chips integrated into dedicated systems, prioritizing low power and specific functionalities.
Desktop Processors anchor the volume base while Server Processors gain share at the steepest rate.
Technology:
Processor technology nodes directly correlate with performance capabilities and manufacturing expense, driving competitive differentiation.
- 5nm:This advanced lithography node enables significantly higher transistor density and improved power efficiency compared to previous generations. Performance demands in high-end gaming and workstation applications are intensifying demand for 5nm chips.
- 3nm:Representing the bleeding edge of semiconductor manufacturing, this node offers the highest possible transistor count and performance per watt. Investment in 3nm technology is concentrated among leading-edge foundries due to extreme EUV lithography costs.
- 14nm:A mature process node still widely used for cost-effective, lower-performance processors and auxiliary chips.
- 10nm:An intermediate node offering a balance of cost and performance, often found in mainstream laptop and desktop CPUs.
- 7nm:A high-performance node widely adopted for premium CPUs and GPUs, balancing advanced capabilities with manufacturing feasibility.
Older technology nodes provide cost-effective options, while sub-7nm processes drive the leading edge of performance innovation.
Application:
Processor applications exhibit distinct performance and power requirements, dictating specialized hardware and software optimizations.
- Gaming:This segment demands high clock speeds, multiple cores, and robust graphics processing capabilities for immersive experiences. Demand for gaming processors is concentrated in regions with high disposable income and a strong esports culture.
- Data Centers:Processors for this application require high core counts, large cache sizes, and extensive I/O capabilities for parallel processing and virtualization. Cloud Service Providers are the primary drivers of innovation and volume in this segment.
- Workstations:High-performance CPUs and GPUs are essential for professional content creation, scientific simulations, and complex engineering tasks.
- Virtual Reality:Requires low-latency, high-frame-rate processing to deliver an immersive user experience without motion sickness.
- Edge Computing:Focuses on energy-efficient processors with integrated AI acceleration for localized data processing near the source.
Gaming and Workstations remain performance benchmarks, while Edge Computing represents a rapidly expanding area for specialized processor design.
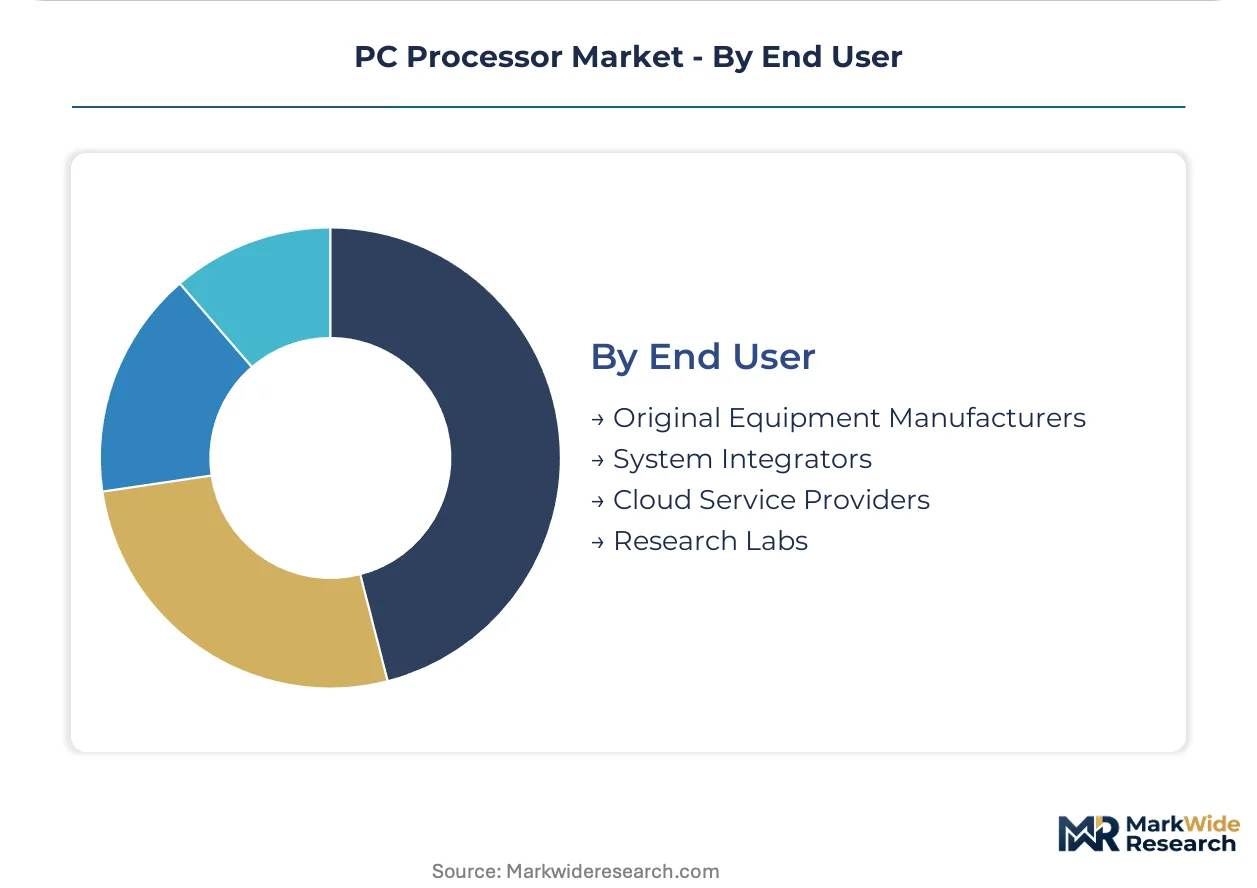
End User:
End-user segments significantly influence processor distribution channels and procurement strategies across the market.
- Original Equipment Manufacturers:These companies integrate processors into their final products, such as laptops, desktops, and embedded systems, before sale to consumers. Their procurement strategies are heavily influenced by cost, volume, and long-term supply agreements.
- Cloud Service Providers:Large-scale operators of data centers that purchase processors in vast quantities for their server infrastructure, driving demand for high-performance, power-efficient server CPUs. Demand is concentrating in regions with expanding digital infrastructure, particularly China.
- System Integrators:Assemble custom PC systems for businesses and individual clients, requiring a flexible supply of diverse processor types.
- Research Labs:Utilize high-performance processors for scientific computing, AI development, and advanced simulations, often requiring specialized architectures.
OEMs and Cloud Service Providers exert significant market power due to volume purchases, while Research Labs drive innovation in niche, high-performance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for PC processors varies significantly across key global markets, driven by differing economic development, technological adoption rates, and national strategic priorities. Performance-intensive applications in gaming and professional workstations define demand in developed economies, while emerging markets prioritize energy-efficient and cost-effective solutions. National semiconductor initiatives also redirect investment and foster localized ecosystems.
China
Demand for high-performance processors is accelerating in China due to expanding data centers and a thriving gaming market. The country's "dual carbon goals" influence manufacturing practices, pushing local foundries toward greener operations. Beijing's strategic initiatives, including the National Integrated Circuit Industry Investment Fund, actively promote domestic semiconductor design and fabrication capabilities within major tech hubs like Shanghai and Shenzhen.
United States
The United States drives innovation in high-end computing and AI acceleration, with strong demand from corporate workstations and advanced research facilities. The US Department of Commerce imposes export controls on advanced semiconductor technology, impacting global supply chains. Silicon Valley and Austin remain critical centers for processor design and intellectual property development, fostering a robust ecosystem for chip architecture innovation.
Taiwan
Taiwan is a pivotal hub for leading-edge processor manufacturing, particularly for advanced process nodes like 5nm and 3nm technology. The Taiwanese government actively supports the semiconductor industry through various incentive programs, maintaining its global leadership position. Hsinchu Science Park anchors the island's advanced manufacturing capabilities, housing major foundries and a vast network of supporting industries.
South Korea
South Korea exhibits significant demand for processors in its advanced electronics manufacturing and burgeoning AI sectors. The Ministry of Trade, Industry and Energy (MOTIE) supports domestic semiconductor R&D and production capacity expansion. The Gyeonggi Province region, including cities like Suwon and Hwaseong, forms a dense cluster of major memory and logic chip manufacturers, driving technological advancements.
Germany
Germany showcases strong demand for high-performance workstation processors, particularly in its automotive engineering and industrial design sectors. European Union initiatives, like the European Chips Act, aim to strengthen regional semiconductor manufacturing capabilities. Munich and Dresden are emerging as key centers for semiconductor research and design, attracting investments in specialized processor development.
PC Processor Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered market structure. The ecosystem features a few large, vertically integrated technology giants alongside numerous specialized design houses and foundry services. Strategic archetypes include integrated device manufacturers, fabless design innovators, and pure-play foundries. Dominant competitive moves include aggressive R&D investment in new architectures and strategic partnerships to secure manufacturing capacity.
Integrated device manufacturers, such as Intel Corporation, occupy a significant position by designing and fabricating their own processors, leveraging extensive in-house capabilities. Advanced Micro Devices (AMD) exemplifies the fabless model, focusing on innovative chip design and outsourcing manufacturing to leading foundries. Apple anchors the custom silicon segment, developing highly optimized M-series chips for its proprietary hardware and software ecosystem.
| Leading Market Players |
|---|
| Apple |
| Lenovo |
| Intel Corporation |
| Dell Technologies |
| HP Inc. |
| Advanced Micro Devices (AMD) |
| NVIDIA Corporation |
| Cerebras Systems |
| Qualcomm Technologies |
| Others |
Cost & Logistics Intelligence
The concentration of leading-edge semiconductor foundries in Taiwan dictates significant pricing power for advanced process nodes. This upstream control influences the margin structures for high-performance processors downstream.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw wafer costs and manufacturing complexity, govern pricing for advanced processor fabrication. Price differentiation stems from the performance tier of the processor and the volume scale of the order. Pricing softness intensifies across mainstream desktop and laptop segments due to intense competition among processor designers. Cloud Service Providers exhibit lower price sensitivity for server CPUs, while individual consumers for entry-level PCs are highly price-sensitive.
Supply Chain Analysis
US Department of Commerce export controls on advanced semiconductor technology significantly limit the flow of leading-edge equipment to certain regions, creating supply chain bottlenecks. Geographic supply concentration for advanced manufacturing centers on Taiwan and South Korea, with China building domestic capabilities. The industry relies heavily on specialized silicon wafers and complex Extreme Ultraviolet (EUV) lithography equipment, making geopolitical risks concerning Taiwan a critical structural vulnerability. Distribution primarily runs through direct integration with Original Equipment Manufacturers and direct sales to Cloud Service Providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PC processor market represents a high-growth disruption, driven by the fundamental shift from monolithic to modular, chiplet-based architectures. This technological inflection point redefines manufacturing and product development across the industry.
For Market Incumbents: Pre-empt emerging custom silicon players by accelerating investment in advanced packaging technologies like Foveros and hybrid bonding. Secure long-term foundry capacity through strategic partnerships with leading-edge manufacturers in Taiwan and South Korea. This defends against supply chain disruptions and strengthens competitive positioning. Focus R&D on next-generation interconnects to maximize chiplet performance gains.
For New Entrants and Emerging Players: Pursue white-space opportunities in on-device AI acceleration by developing specialized Neural Processing Units (NPUs) for Edge Computing applications. Target custom silicon designs for niche but high-value vertical markets, such as financial modeling or scientific simulation. The most penetrable segment lies in specific industrial verticals requiring tailored power-efficient solutions. Go-to-market through ecosystem partnerships with software developers and system integrators.
For Investors and Strategic Acquirers: Capital is best deployed toward fabless design innovators with strong intellectual property portfolios in AI acceleration or advanced packaging technologies. Long-term viability hinges on companies positioned for specialized computing growth over the next decade. Seek firms demonstrating proven expertise in heterogeneous architecture development. The signal to watch is increased adoption of chiplet-based designs across mainstream PC products.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Packaging R&D | Advances in 3D stacking and interconnects enhance multi-chiplet performance and power efficiency for high-end processors. |
| Secure Long-Term Foundry Agreements | Guarantees access to leading-edge process nodes like 3nm, critical for competitive product roadmaps and supply stability. |
| Develop Integrated AI Accelerators | Captures value from growing on-device AI inference demand, differentiating processors for diverse application workloads. |
| Expand Custom Silicon Offerings | Addresses niche but high-value vertical markets with application-specific processors, moving beyond general-purpose CPUs. |
| Form Ecosystem Partnerships | Accelerates market penetration for new architectures by integrating solutions with software developers and system integrators. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights came from conversations with processor architects, foundry executives, OEM procurement leads, and cloud service provider engineers. Secondary sources included corporate financial filings, patent databases, government semiconductor reports, and technology news archives. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
Forecast inputs considered technological roadmaps, economic indicators, and geopolitical developments across the analysis window. The analytical framework modeled market dynamics across product type, technology node, application, end-user, and regional demand patterns. Compound Annual Growth Rates were derived from historical trends and projected future adoption rates. Transistor density improvements and lithography advancements served as key industry-specific forecast inputs.
Sensitivities concentrate around geopolitical tensions, rapid technological shifts, and unforeseen economic downturns. Forecasts reflect assumptions regarding market stability and innovation trajectories. Material shifts in export control regimes or foundry capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Microserver Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Processor Chip Market