
 Automotive DRAM Market | 2026-2036
Automotive DRAM Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive DRAM Market Insights
The gap between consumer-grade memory reliability and automotive-grade endurance is narrowing as foundries adopt dedicated automotive process nodes and in-line testing protocols. Samsung Electronics leverages captive wafer capacity to secure long-term supply agreements with German premium OEMs. SK Hynix anchors its position through backward integration into advanced packaging for high-temperature operating environments. Micron Technology competes on the strength of its locked-step qualification programs with North American electric vehicle platforms.
Automotive DRAM comprises volatile semiconductor memory engineered for operation across temperature extremes, with AEC-Q100 qualification and fault-tolerant architectures enabling real-time data buffering for safety-critical vehicle subsystems. LPDDR5 commands the fastest expansion trajectory among product types, driven by bandwidth requirements for consolidated cockpit domain controllers. Within applications, Advanced Driver Assistance Systems absorbs the dominant share of high-density die, while Infotainment Systems generates volume demand for mid-range DDR4 configurations. OEM direct procurement is displacing Tier-1 buffer stocking for LPDDR5, reshaping contract structures and inventory liability.
FCC equipment authorization and NHTSA safety guidelines in the United States, alongside EU Green Deal embedded emissions reporting and CE marking under the F-Gas Regulation, tighten compliance obligations for memory module suppliers seeking vehicle platform integration. ISO 26262 functional safety mandates and REACH substance restrictions further constrain material selection and validation timelines. Stakeholders must weigh qualification cycle investments against the accelerating obsolescence risk of DDR4 as automakers finalize next-generation electrical architecture decisions.
Market Dynamics
LPDDR5 migration is compressing qualification timelines as automakers consolidate cockpit domain controllers and ADAS sensor fusion pipelines onto unified memory architectures, forcing foundries to accelerate automotive process node certification.
Growth Catalysts
- ISO 26262 functional safety mandates:ASIL-D certification requirements for autonomous braking and lane-keeping subsystems are mandating fault-tolerant DRAM architectures with inline ECC and row-hammer protection.
- Sensor fusion bandwidth demands:8MP camera arrays and 4D imaging radar generating multi-gigabit data streams require LPDDR5's 6400 Mbps throughput for real-time object classification.
- German premium OEM design-in activity:Stuttgart and Munich-based manufacturers are specifying AEC-Q100 Grade 0 components for engine-bay adjacent controllers, pulling supply commitments from Korean and US memory houses.
Market Restraints
- Wafer capacity allocation rigidity:Foundries prioritize consumer GPU and AI accelerator demand during supply crunches, constraining automotive-qualified wafer starts at mature nodes.
- Copper and epoxy resin input volatility:Advanced packaging substrates depend on stable commodity pricing, with laminate sheet cost swings compressing module assembler margins.
- REACH substance restriction complexity:ECHA candidate list updates for halogenated flame retardants force iterative material requalification, extending validation cycles by 8-14 months.
Strategic Opportunities
- India automotive electronics localization:PLI scheme incentives for advanced automotive component manufacturing are attracting DRAM module assembly investments to Tamil Nadu and Gujarat.
- Zonal architecture transition:Domain consolidation from distributed ECUs to centralized compute nodes creates demand for high-density LPDDR5X stacks in gateway and powertrain controllers.
- EU Green Deal embedded emissions reporting:Lifecycle carbon footprint disclosure requirements favor suppliers with renewable-powered fabrication and low-emission logistics corridors.
Industry Challenges
- Automotive reliability engineering talent scarcity:Mixed-signal verification and AEC-Q100 stress-test expertise concentrates among semiconductor veterans in Dresden, Boise, and Hsinchu, constraining foundry expansion timelines.
- Legacy DDR4 inventory stranding risk:Tier-1 suppliers holding six-quarter buffer stocks face write-down exposure as OEMs freeze DDR4 design-ins for 2027 platform cycles.
- Multi-tenant software stack integration:Hypervisor-enabled consolidation of infotainment and instrument cluster workloads onto shared memory pools introduces deterministic latency certification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive DRAM Market |
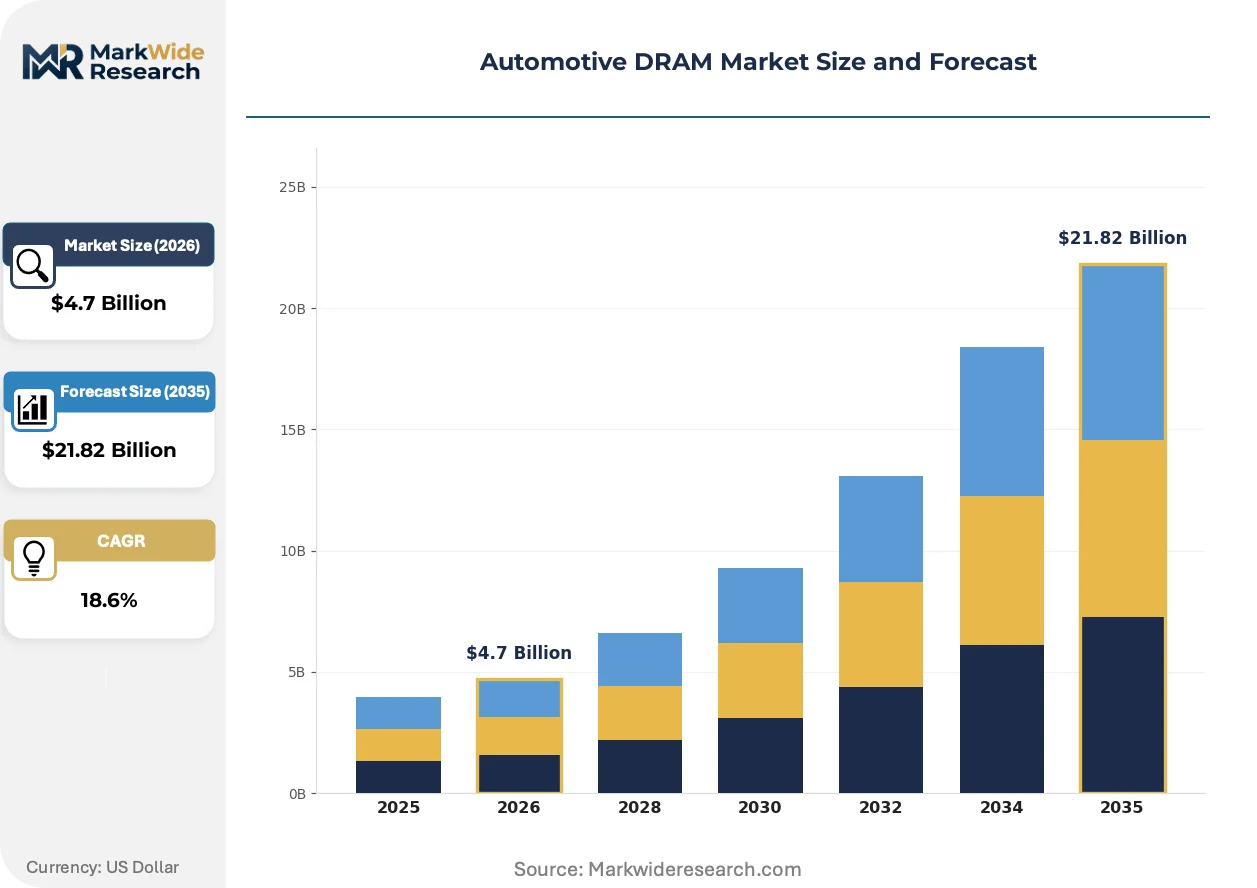
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR4, DDR5, LPDDR4, LPDDR5 Application: Advanced Driver Assistance Systems, Infotainment Systems, Automotive Control Units, Telematics Connectivity: Wired, Wireless, Ethernet, CAN End User: OEMs, Tier-1 Suppliers, Automotive Aftermarket, Technology Providers |
| Companies Covered | Samsung Electronics, SK Hynix, Micron Technology, Infineon Technologies, Nanya Technology, Winbond Electronics, Renesas Electronics, Texas Instruments, Integrated Silicon Solution Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive DRAM Market Trends and Innovations
Memory subsystem architectures are pivoting from discrete component supply toward qualified module integration, with packaging technology and functional safety certification becoming primary competitive differentiators rather than die density alone.
LPDDR5 is migrating from mobile and consumer applications into automotive-grade domain controllers, where its low-voltage operation and burst-mode efficiency support thermal-constrained engine-bay installations. German and US electric vehicle platforms are adopting LPDDR5X variants for consolidated cockpit electronics, compressing the validation window for legacy DDR4 suppliers. This technology is migrating from consumer-grade reliability benchmarks toward AEC-Q100 Grade 1 and Grade 0 qualification, enabling foundries to command premium pricing for automotive-dedicated process flows.
EU F-Gas Regulation phase-down schedules are restricting fluorinated greenhouse gas use in semiconductor etching and chamber cleaning processes, compelling memory manufacturers to retrofit fabrication lines with alternative chemistries. Industrial consequence includes extended process qualification timelines for new die shrinks as foundries validate fluorine-free plasma recipes. Automotive DRAM modules face heightened scrutiny under CE marking requirements, with module suppliers in South Korea and the United States accelerating substance declaration documentation to maintain EU vehicle platform access.
Direct OEM procurement of qualified memory modules is displacing Tier-1 distributor buffer stocking for LPDDR5 and LPDDR5X product families, compressing contract structures and reallocating inventory liability upstream. German premium manufacturers now negotiate long-term supply agreements directly with Samsung Electronics and SK Hynix, bypassing traditional automotive electronics distributors. This pattern is most visible in North American electric vehicle supply chains, where Tesla, Rivian, and Lucid Motors have established locked-step qualification programs with Micron Technology for platform-specific memory configurations.
Automotive DRAM Market Segmentation
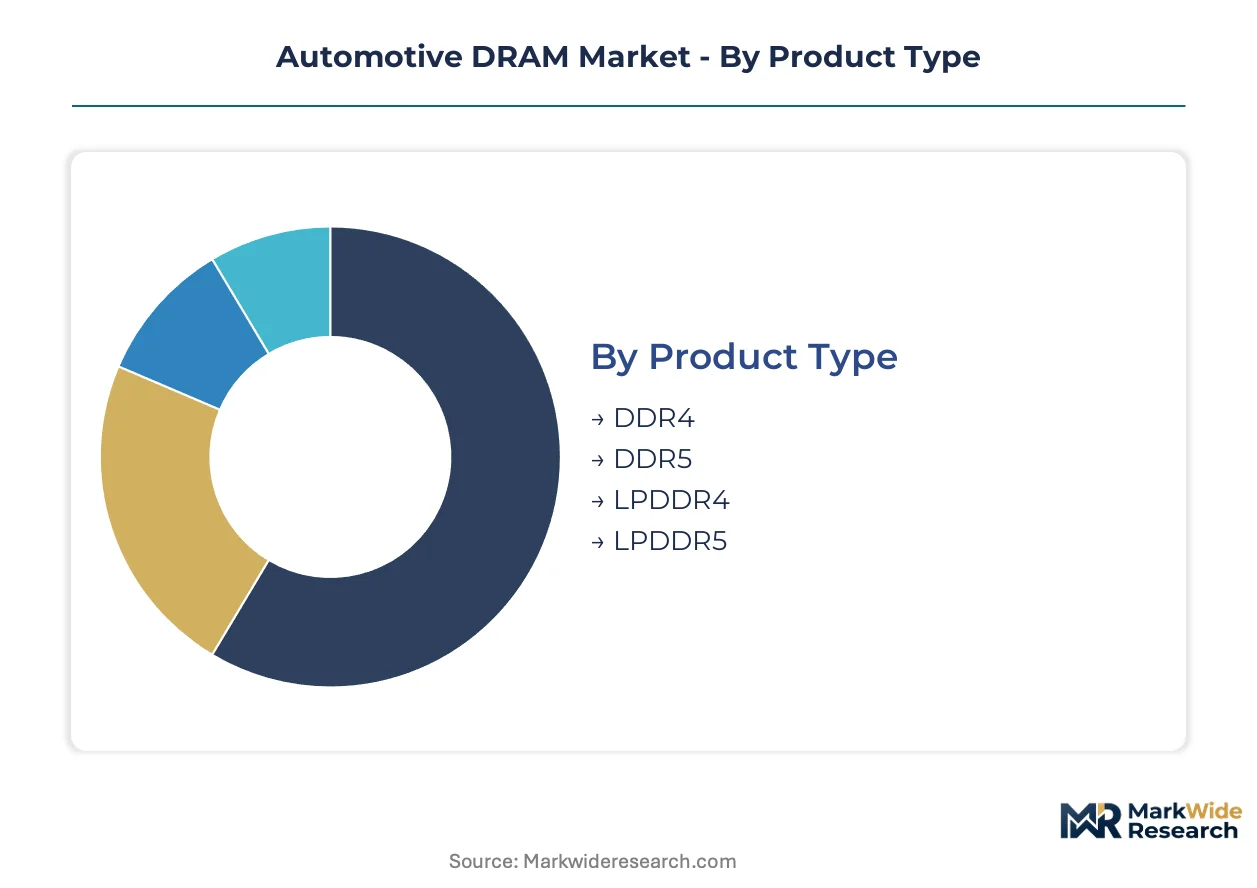
Automotive DRAM segmentation reflects the tension between legacy platform continuity and next-generation electrical architecture migration. Memory suppliers must simultaneously serve DDR4 volume commitments for current production while scaling LPDDR5 qualification for domain-consolidated designs. The resulting product mix directly shapes foundry capacity allocation and packaging technology roadmaps.
Product Type:
DDR4 commands mature-volume dominance while LPDDR5 captures design-in momentum for consolidated compute nodes.
- DDR4:Established automotive-grade variants operate at 3200 Mbps with AEC-Q100 Grade 2 qualification for body control and legacy infotainment modules. German and US automakers maintain DDR4 sourcing for 2025-2026 platform cycles, though design-freeze deadlines approach.
- LPDDR5:Low-voltage architectures at 6400 Mbps enable real-time sensor fusion for ADAS domain controllers with thermal-constrained engine-bay mounting. Stuttgart-based OEMs specify LPDDR5 for consolidated cockpit electronics, pulling supply commitments from Korean memory houses.
- DDR5:Higher-density configurations serve high-performance computing clusters in autonomous development vehicles with bandwidth headroom for neural network inference.
- LPDDR4:Mid-range smartphones and entry-level telematics units in cost-sensitive vehicle segments continue absorbing qualified die from legacy process nodes.
DDR4 handles the majority of throughput; LPDDR5 is the fastest mover on share.
Application:
Functional safety requirements stratify memory specifications across vehicle subsystems with ASIL-rated differentiation.
- Advanced Driver Assistance Systems:Multi-camera arrays and 4D imaging radar generate multi-gigabit data streams requiring LPDDR5 throughput for real-time object classification. ASIL-D certification mandates fault-tolerant architectures with inline ECC.
- Infotainment Systems:Consolidated cockpit domain controllers integrate instrument cluster and head-unit workloads onto unified memory pools. German premium OEMs specify mid-range DDR4 for current-generation platforms with hypervisor-enabled workload separation.
- Automotive Control Units:Engine management and transmission controllers operate across temperature extremes with AEC-Q100 Grade 0 qualification for powertrain-adjacent mounting.
- Telematics:Over-the-air update buffering and vehicle-to-cloud data streaming utilize lower-density configurations with extended temperature range specifications.
Advanced Driver Assistance Systems absorbs the dominant share of high-density die; Infotainment Systems generates volume demand for mid-range configurations.
Connectivity:
Physical layer protocols determine memory bandwidth allocation and deterministic latency requirements for real-time subsystems.
- Ethernet:Multi-gigabit automotive Ethernet (100BASE-T1, 1000BASE-T1) enables high-throughput sensor data aggregation for ADAS backbone networks. Zonal architecture transitions favor Ethernet-connected memory pools in gateway controllers.
- CAN:Controller Area Network persists for low-bandwidth body electronics and diagnostic interfaces with deterministic timing for safety-critical messaging.
- Wired:Dedicated point-to-point links serve high-resolution displays and camera modules with isolated bandwidth guarantees.
- Wireless:V2X communication modules buffer over-the-air firmware updates and telematics uploads with intermittent connectivity tolerance.
Ethernet captures the steepest expansion trajectory for backbone bandwidth; CAN retains installed-base dominance in body electronics.
End User:
Procurement pattern shifts reallocate inventory liability between direct OEM engagement and traditional Tier-1 distribution.
- OEMs:German premium manufacturers and North American electric vehicle platforms negotiate long-term supply agreements directly with memory foundries for LPDDR5 and LPDDR5X families. Locked-step qualification programs compress validation timelines.
- Tier-1 Suppliers:Traditional automotive electronics distributors face margin compression as buffer stocking responsibility shifts upstream. Legacy DDR4 inventory concentration creates write-down exposure.
- Automotive Aftermarket:Replacement modules for damaged infotainment and telematics units utilize commercial-grade memory with extended temperature specifications rather than full AEC-Q100 qualification.
- Technology Providers:Autonomous driving development platforms and test fleet operators procure high-density configurations with non-standard form factors for data logging and simulation workloads.
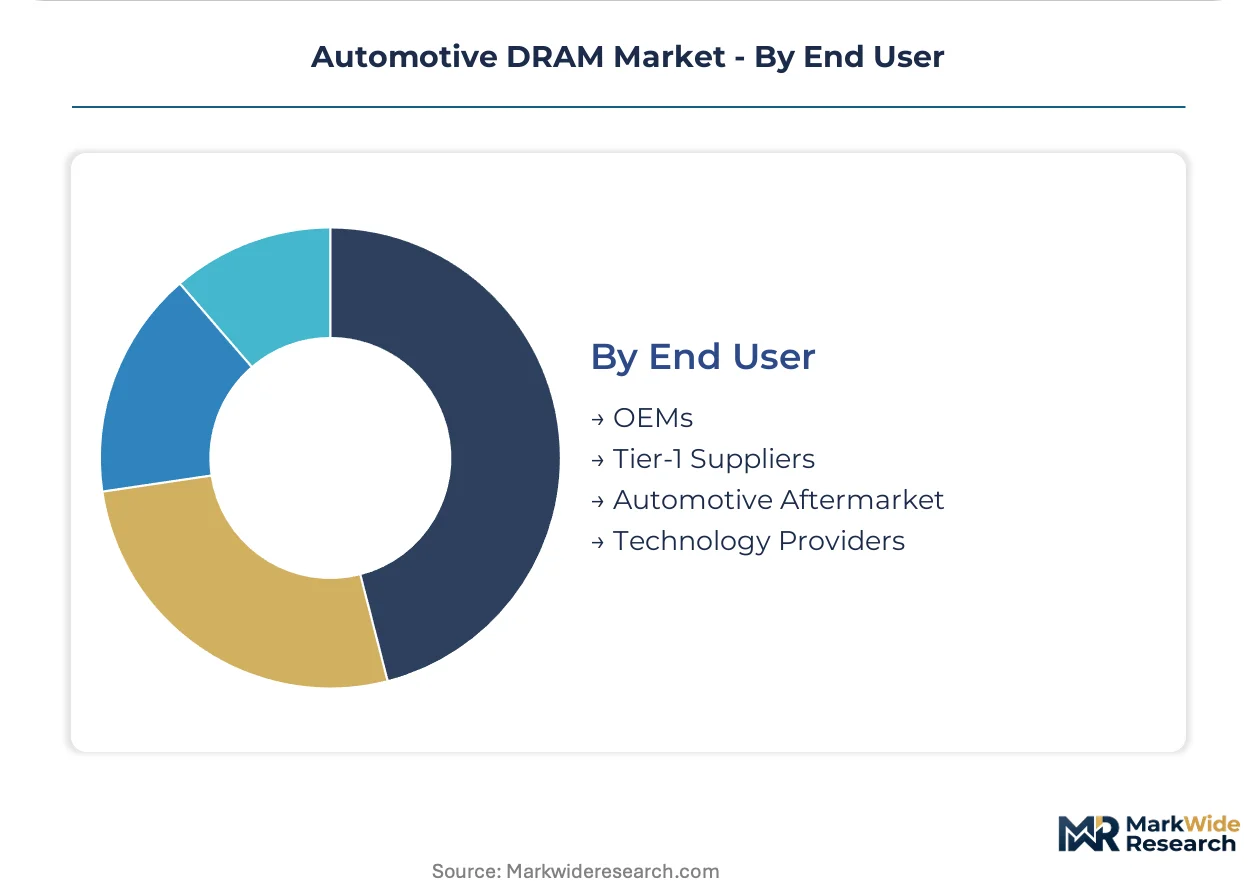
OEM direct procurement is displacing Tier-1 buffer stocking for advanced node products; the aftermarket remains anchored to legacy configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports DRAM die to German and US automotive electronics clusters, while Taiwan supplies advanced packaging substrates for temperature-qualified modules. This trade corridor shapes regional investment patterns and foundry capacity allocation.
United States
North American electric vehicle platforms drive LPDDR5 procurement for consolidated cockpit controllers. NHTSA safety guidelines and FCC equipment authorization tighten module-level compliance timelines. Austin and Detroit anchor locked-step qualification programs between memory suppliers and EV manufacturers.
Germany
Stuttgart and Munich-based premium OEMs specify AEC-Q100 Grade 0 components for engine-bay adjacent installations. EU Green Deal embedded emissions reporting and REACH substance restrictions constrain material selection. Dresden concentrates mixed-signal verification expertise for automotive process node certification.
China
Domestic EV manufacturers absorb mid-range DDR4 for cost-sensitive platform cycles while importing LPDDR5 die for ADAS domain controllers. MIIT automotive semiconductor guidelines and GB standards shape local qualification requirements. Shanghai and Shenzhen cluster module assembly investments for regional supply security.
South Korea
Captive wafer capacity supports long-term supply agreements with European and North American OEMs. MFDS substance tracking and export control alignment with WTO frameworks govern cross-border shipments. Pyeongtaek and Icheon host automotive-dedicated process flows with in-line ECC validation.
India
PLI scheme incentives attract DRAM module assembly investments for domestic automotive electronics localization. BIS certification requirements and CEA power quality standards apply to imported die integration. Tamil Nadu and Gujarat emerge as contract manufacturing hubs for temperature-qualified configurations.
Automotive DRAM Market Competitive Landscape
On the supply side, the industry is consolidating around captive fabrication capacity and automotive-specific process certification. Three strategic archetypes dominate: integrated memory foundries with captive wafer supply, advanced packaging specialists with high-temperature substrate expertise, and fabless designers with locked-step OEM qualification programs. Capacity expansion and backward integration into automotive process nodes represent the dominant competitive moves.
Within the integrated foundry tier, Samsung Electronics and SK Hynix occupy positions defined by captive wafer supply and long-term OEM agreements. Micron Technology exemplifies the North American qualification-specialist archetype, anchoring locked-step programs with electric vehicle platforms. These three entities collectively represent the supply-side concentration visible in direct procurement patterns across German and US automotive clusters.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| Micron Technology |
| Infineon Technologies |
| Nanya Technology |
| Winbond Electronics |
| Renesas Electronics |
| Texas Instruments |
| Integrated Silicon Solution Inc. |
| Others |
Pricing and Supply Chain Analysis
Pyeongtaek wafer fabrication clusters anchor global automotive DRAM supply, with Samsung Electronics and SK Hynix commanding premium pricing power through captive capacity and AEC-Q100 Grade 0 certification scarcity. Foundry allocation rigidity during consumer GPU demand surges feeds directly into contract pricing escalators for German and North American OEMs seeking locked-step qualification timelines.
Pricing Analysis
LPDDR5-to-DDR4 pricing spreads reflect the technology-generation gap most acutely, with next-generation LPDDR5X commanding substantial premiums over mature DDR4 configurations while prior-generation LPDDR4 occupies a collapsing middle tier. Three-tier pricing structure across AEC-Q100 Grade 0, Grade 1, and Grade 2 certification levels drives differentiation, with temperature qualification tier and volume scale as primary levers. Cost compression in DDR4 module assembly is intensifying because Tier-1 suppliers face inventory stranding as OEMs freeze design-ins. Aftermarket distributors demonstrate highest price sensitivity; German premium OEMs direct procurement teams show lowest.
Supply Chain Analysis
Samsung Electronics, SK Hynix, and Micron Technology concentrate contract manufacturing capacity for automotive-qualified die, with Taiwan packaging houses handling advanced substrate integration for high-temperature modules. South Korea, Taiwan, and the United States form the geographic supply backbone, with silicon wafer supply drawing from Japan and high-purity chemical inputs resting on German specialty chemical producers. Single-source vulnerability concentrates in EUV lithography equipment access, constraining capacity expansion timelines. Distribution runs through direct OEM procurement agreements displacing traditional Tier-1 buffer stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive DRAM hardware margins are compressing while qualification-as-a-service and lifetime reliability monitoring contracts expand faster than die shipments, creating a service-attach opportunity for suppliers with AEC-Q100 certification expertise.
For Market Incumbents: Pre-empt fabless designer encroachment by deepening backward integration into automotive-specific process nodes at Pyeongtaek and Icheon facilities, while locking long-term supply agreements with Stuttgart and Munich-based OEMs before qualification windows close. Threat substitution from CXL-enabled memory pooling architectures demands accelerated LPDDR5X roadmap execution. For New Entrants and Emerging Players: Build out module assembly capabilities in Tamil Nadu and Gujarat to capture PLI scheme incentives for domestic automotive electronics localization, targeting India's cost-sensitive EV platforms with extended-temperature DDR4 configurations. White-space concentrates in aftermarket replacement modules where full AEC-Q100 qualification is not mandatory. Go-to-market leverage: BIS certification partnerships with established Korean die suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a captive-capacity consolidation play because automotive process node certification scarcity and foundry allocation rigidity will persist across the analysis window. Target acquisition archetype: advanced packaging specialists with high-temperature substrate expertise and existing AEC-Q100 validation infrastructure. Signal to watch: German OEM direct procurement contract announcements bypassing traditional Tier-1 distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Process Node Certification | AEC-Q100 Grade 0 qualification at Pyeongtaek secures German OEM engine-bay placements. |
| Long-term Supply Agreement | Locked-step programs with North American EV platforms compress validation timelines. |
| Advanced Packaging Investment | High-temperature substrate expertise differentiates beyond die density alone. |
| Geographic Manufacturing Footprint | Tamil Nadu module assembly captures PLI incentives for regional supply security. |
| Software-Defined Vehicle Investment | Hypervisor-enabled memory pools require deterministic latency certification capabilities. |
Research Methodology
Cross-validation between primary fieldwork with Tier-1 supplier procurement directors and secondary validation through SEC 10-K filings anchors the qualitative findings. Semiconductor plant managers, OEM platform engineers, aftermarket distributors, and automotive electronics distributors provided demand-side perspectives. Secondary sources include vehicle production databases, IHS Markit registration data, customs/trade records, and AEC-Q100 qualification registries. Bottom-up die shipment modeling and top-down automotive electronics value chain triangulation ensure consistency.
Calibration against historical qualification cycle timelines and foundry capacity utilization patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, application, connectivity protocol, and end-user procurement pattern, with regional production cluster as an automotive-specific overlay. CAGRs derive from die density trajectories per vehicle class and propulsion architecture penetration curves. Industry-specific inputs capture zonal architecture transition speed and LPDDR5 design-in momentum.
Practitioners should monitor foundry capacity allocation shifts and REACH substance list updates for early signals of supply constraint or qualification delay. Forecasts reflect assumptions regarding automotive process node certification timelines and OEM electrical architecture consolidation decisions. Quarterly review of German premium OEM direct procurement announcements and Korean memory house automotive revenue disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
MRAM Market
Memory Chips
DDR SDRAM Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Memory Module Market
Memory Chips
In-Memory Grid Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Memory IC Market
Memory Chips
Digital RF Memory Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market