
 System on Chip (Soc) Market | 2026-2036
System on Chip (Soc) Market Size, Share, and Industry Trends Forecast 2026-2036
System on Chip (Soc) Market Intelligence
Foundry capacity expansion in Taiwan and South Korea is broadening the supply base for advanced node SoCs. Qualcomm Technologies, Inc. leverages its leadership in mobile communication chipsets to define the smartphone segment. NVIDIA Corporation competes on the strength of its GPU-centric SoCs for AI and automotive applications. MediaTek Inc. differentiates with cost-effective solutions for mid-range consumer electronics.
A System on Chip is an integrated circuit that consolidates essential electronic components, including processing units and memory, onto a single substrate. These devices, often manufactured on advanced process nodes below 10nm, serve as the computational core for a vast array of electronic products. The consumer electronics end-user segment remains the largest volume driver, particularly for mobile devices. Within technology segments, Application-Specific Integrated Circuits (ASICs) offer performance advantages for high-volume applications.
Semiconductor supply chains are influenced by national security considerations, such as export controls enforced by the United States government. In parallel, regulations like the EU's RoHS directive and China's GB standards dictate material composition and safety requirements, impacting market access. Navigating the complex interplay between geopolitical trade policies and the rapid evolution of fabrication technologies is critical for all stakeholders.
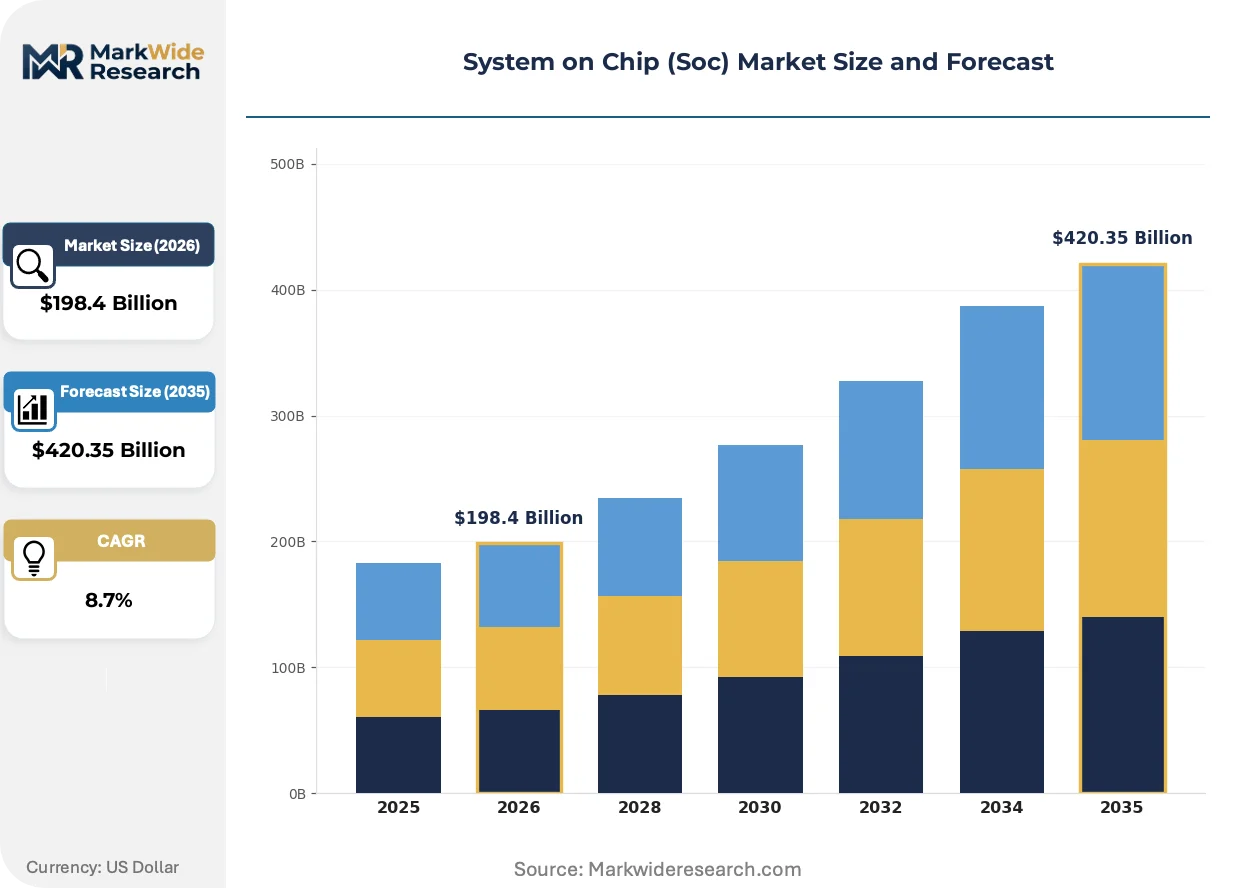
Market Dynamics
The market's central dynamic is the collision between escalating demand for functional integration in end devices and the geopolitical fragmentation of the semiconductor supply chain. This tension forces difficult tradeoffs between performance optimization and supply security for all stakeholders.
Growth Catalysts
- 5G Infrastructure Expansion:The global build-out of 5G telecommunications networks requires more powerful and integrated SoCs in base stations and user equipment to manage higher data throughput and lower latency, driving significant volume demand.
- Automotive Sector Integration:Adoption of SoCs for advanced driver-assistance systems (ADAS) and in-vehicle infotainment (IVI) is accelerating, with automakers requiring specialized chips that fuse sensor data and execute complex AI algorithms.
- Cost-Effective Solutions:The availability of differentiated, cost-effective SoCs enables high-volume production of mid-range consumer electronics, particularly within China's vast manufacturing ecosystem, broadening market access for new device categories.
Market Restraints
- Fabrication Cost Escalation:The immense capital investment required to design, test, and manufacture SoCs on advanced process nodes below 10nm creates a significant financial barrier to entry and limits competitive diversity.
- Supply Chain Concentration:Heavy reliance on foundries located in specific geographies, notably Taiwan and South Korea, for leading-edge chip production exposes the entire ecosystem to significant geopolitical and logistical disruption risks.
- Export Control Regimes:National security-driven export controls, such as those imposed by the United States government, restrict access to critical design software, manufacturing equipment, and high-performance chips, creating market uncertainty.
Strategic Opportunities
- Edge AI Proliferation:Developing specialized SoCs with integrated neural processing units (NPUs) for on-device artificial intelligence and machine learning presents a major opportunity, particularly for IoT and smart home applications.
- Custom ASIC Development:Hyperscale cloud providers and large electronics OEMs are increasingly designing custom ASICs to optimize performance for specific workloads, creating a new market for design services and IP licensing.
- Heterogeneous Integration:Advanced packaging techniques that combine multiple specialized chiplets into a single SoC package offer a pathway to bypass the physical limits of monolithic chip design, enabling new levels of performance.
Industry Challenges
- Talent Scarcity:A persistent shortage of skilled semiconductor professionals, particularly IC design and verification engineers, constrains the ability of companies to execute on complex new product roadmaps and innovate at pace.
- IP Licensing Complexity:Navigating the intricate and costly landscape of intellectual property licensing for essential components like CPU cores, GPUs, and connectivity modems is a major operational hurdle for new and existing chip designers.
- Material and Safety Compliance:Adherence to a growing web of international regulations, including the EU's RoHS directive on hazardous substances and China's GB standards, complicates global product launches and supply chain management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System on Chip (Soc) Market |
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $420.35 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded SoCs, Application SoCs, Power SoCs, RF SoCs Technology: FPGA, ASIC, DSP, Mixed Signal End User: Consumer Electronics, Automotive OEMs, Industrial Equipment, Telecommunications Application: Mobile Devices, IoT Devices, Wearable Tech, Smart Home Solutions |
| Companies Covered | Qualcomm Technologies, Inc., MediaTek Inc., Samsung Electronics Co., Ltd., Apple Inc., Broadcom Inc., Intel Corporation, NVIDIA Corporation, NXP Semiconductors N.V., Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System on Chip (Soc) Market Strategic Shifts & Innovations
Architectural innovation is reshaping the SoC landscape, moving away from monolithic, general-purpose designs toward modular, domain-specific solutions. This shift allows for greater optimization around specific workloads, from artificial intelligence in data centers to low-power sensing at the network edge.
Chiplet-based design is an emerging architectural approach for constructing complex semiconductors. These designs utilize multiple smaller, specialized dies interconnected within a single package. High-performance computing and data center applications are the primary adopters of this technology. This modular methodology is consolidating functions that previously required separate, large monolithic chips into a more efficient and customizable system.
National security policies are directly influencing technology access and supply chain strategy. Export controls enforced by the United States government restrict the flow of advanced semiconductor technology and equipment to designated entities, particularly in China. This action compels companies to re-evaluate their supply chains for resilience against geopolitical risk. The most affected segments are those reliant on leading-edge fabrication, which are now accelerating indigenous development efforts.
A shift toward in-house custom silicon design by high-volume device manufacturers is altering market dynamics. This trend sees large technology companies, especially in the cloud computing and smartphone sectors, developing bespoke ASICs to achieve performance and efficiency gains. The established model of procuring off-the-shelf components from merchant semiconductor firms is being challenged by this vertical integration strategy, most visibly in the United States and China.
System on Chip (Soc) Market Segmentation
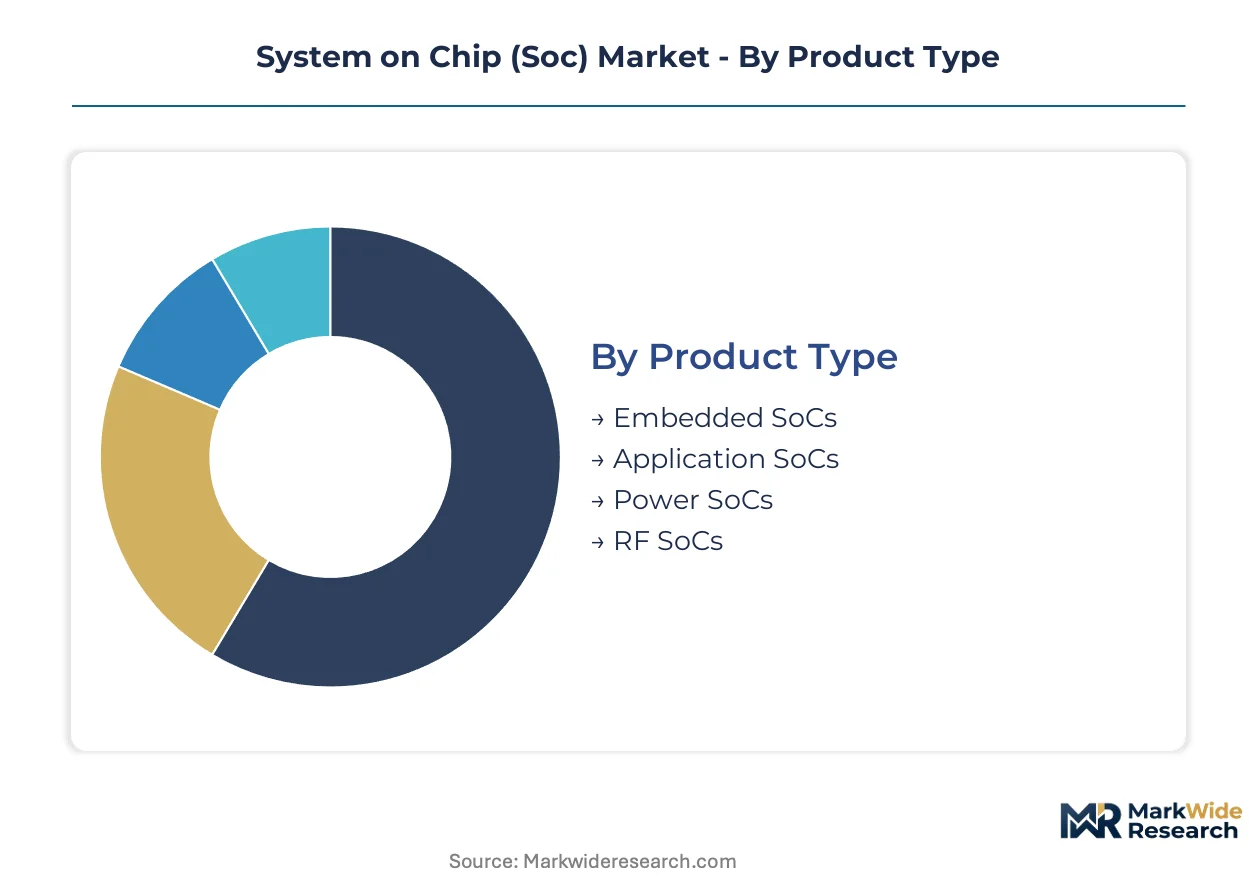
Segmentation within the System on Chip market reveals critical distinctions in design requirements, manufacturing processes, and end-user demands. Understanding these segments helps stakeholders identify specific growth vectors and allocate resources effectively across diverse technological and application landscapes.
Product Type:
The upgrade cycle for System on Chip products often dictates design complexity and integration levels, influencing how manufacturers approach component selection for new device generations.
- Application SoCs:These highly integrated circuits combine CPU, GPU, memory, and specialized accelerators for specific high-performance tasks. Demand is concentrating in mobile devices and automotive systems, driven by advanced AI processing requirements.
- Embedded SoCs:Embedded SoCs integrate core processing units with peripherals and memory for dedicated functions within larger systems. Their demand is strong in industrial equipment and IoT devices, requiring optimized power consumption and real-time capabilities.
- Power SoCs:Power SoCs manage power delivery and conversion within electronic systems, ensuring efficient energy use for various components.
- RF SoCs:RF SoCs integrate radio frequency transceivers and baseband processing for wireless communication protocols like 5G and Wi-Fi.
Volume placements concentrate in Application SoCs; the faster expansion belongs to Embedded SoCs.
Technology:
The choice of System on Chip technology hinges on critical performance optimization criteria, balancing flexibility, processing power, and energy efficiency for the target application.
- ASIC:Application-Specific Integrated Circuits are custom-designed for a particular function, offering superior performance and power efficiency for high-volume applications. Hyperscale cloud providers and large electronics OEMs increasingly leverage ASICs for specialized workloads.
- FPGA:Field-Programmable Gate Arrays provide reconfigurable logic blocks and programmable interconnects, allowing post-manufacturing customization and rapid prototyping. These are critical for telecommunications infrastructure and industrial control systems requiring adaptability.
- DSP:Digital Signal Processors are optimized for processing real-world signals, essential for audio, video, and communication applications.
- Mixed Signal:Mixed Signal SoCs combine analog and digital circuits on a single chip, facilitating interactions between the physical world and digital processing.
ASIC technology drives significant revenue due to its performance advantages, while FPGA adoption is expanding in areas demanding design flexibility.
End User:
End-user segments dictate the volume and specialization requirements for System on Chip solutions, driving distinct development priorities for chip manufacturers.
- Consumer Electronics:This segment includes smartphones, tablets, smart home devices, and wearables, demanding high-volume, cost-effective SoCs with integrated multimedia and connectivity features. Mobile devices remain the primary volume driver within this category.
- Automotive OEMs:Automotive manufacturers integrate SoCs for advanced driver-assistance systems (ADAS), in-vehicle infotainment, and autonomous driving functions, requiring stringent safety certifications and robust processing capabilities. The sector's demand for AI-enabled chips is accelerating.
- Industrial Equipment:Industrial equipment utilizes SoCs for automation, control systems, and robotics, prioritizing reliability, long lifecycles, and real-time processing.
- Telecommunications:The telecommunications sector deploys SoCs in base stations, networking equipment, and user devices to manage high data throughput and low-latency communication for 5G infrastructure.
Consumer electronics represent the largest demand base for SoCs, while the automotive sector exhibits robust expansion due to increasing vehicle intelligence.
Application:
Specific application areas define the required functionality and power profiles for System on Chip designs, influencing the integration of specialized processing units and connectivity modules.
- Mobile Devices:This application segment encompasses smartphones and tablets, demanding highly integrated SoCs with advanced CPU, GPU, AI accelerators, and 5G modems. Performance and power efficiency are paramount for user experience.
- IoT Devices:Internet of Things devices span a vast array of connected sensors, gateways, and edge computing nodes, requiring low-power, cost-optimized SoCs with diverse connectivity options. Edge AI proliferation is a significant driver in this segment.
- Wearable Tech:Wearable technology, including smartwatches and fitness trackers, relies on compact, ultra-low-power SoCs for health monitoring and notification capabilities.
- Smart Home Solutions:Smart home applications integrate SoCs for device control, security systems, and energy management, requiring robust connectivity and local processing for privacy.
Mobile devices account for the highest volume of SoC deployments, with IoT devices demonstrating the most dynamic growth in new use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast electronics manufacturing ecosystem anchors significant demand for System on Chip solutions. The country's industrial policies prioritize domestic semiconductor development, influencing global supply chain dynamics. This focus creates both opportunities and challenges for international stakeholders.
China
China's consumer electronics sector, particularly mobile devices, drives immense volume demand for integrated SoCs. The country's GB standards dictate material composition and safety requirements for market access. Manufacturing hubs in the Yangtze River Delta, like Shanghai, concentrate advanced packaging and assembly operations for domestic and international chipmakers.
United States
The United States' automotive and hyperscale cloud sectors generate substantial demand for high-performance SoCs, especially for AI applications. Export controls enforced by the United States government influence technology access and supply chain strategies. Silicon Valley in California remains a primary hub for advanced SoC design and intellectual property development.
South Korea
South Korea's leadership in memory and mobile device manufacturing fuels its demand for integrated Application SoCs. The country's industrial policies support domestic R&D in advanced semiconductor fabrication. Foundry capacity in Gyeonggi Province, including Pyeongtaek, broadens the supply base for leading-edge chip production globally.
Taiwan
Taiwan's position as a global leader in semiconductor foundry services underpins its critical role in SoC supply. The government actively promotes advanced process node development through various investment incentives. Hsinchu Science Park concentrates world-class fabrication facilities and research institutions, driving innovation in chip manufacturing.
Germany
Germany's automotive industry and industrial automation sector require robust and reliable embedded SoCs for specialized applications. EU's RoHS directive influences material composition and environmental compliance for chips sold across the continent. Dresden, known as "Silicon Saxony," is a prominent cluster for semiconductor manufacturing and design activities.
System on Chip (Soc) Market Key Industry Players
Global majors compete with regional champions across the System on Chip market's technology and application segments. The market exhibits a tiered structure, with a few integrated device manufacturers alongside numerous specialized fabless design houses. Strategic archetypes include high-performance innovators, cost-effective volume providers, and niche application specialists. Companies primarily engage in capacity expansion and strategic partnerships to secure supply and broaden market reach.
Within the high-performance innovator archetype, Qualcomm Technologies, Inc. and NVIDIA Corporation exemplify leadership in mobile communication and GPU-centric AI applications, respectively. Qualcomm's focus on mobile chipsets defines the smartphone segment, while NVIDIA's strength lies in its GPU-centric SoCs for AI and automotive. MediaTek Inc. occupies a position as a cost-effective volume provider, differentiating through solutions for mid-range consumer electronics and broad market access. These firms navigate complex IP licensing and fabrication dependencies while continually investing in next-generation architectures and advanced process nodes to maintain their competitive edge.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| MediaTek Inc. |
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Broadcom Inc. |
| Intel Corporation |
| NVIDIA Corporation |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| Others |
Cost & Logistics Intelligence
Vertical integration into custom silicon design anchors both a manufacturer's supply position and its pricing power within specific high-volume segments. This strategic choice allows large OEMs to control costs and performance for their bespoke System on Chip solutions.
Pricing Analysis
Service and IP bundling often differentiate System on Chip offerings, particularly for specialized Application-Specific Integrated Circuits. Per-unit transactional pricing dominates for high-volume consumer electronics, while licensing and royalty models apply to complex IP blocks. Price differentiation stems from performance tier and customization level, with cost compression in mid-range consumer devices intensifying due to aggressive competition. Automotive OEMs and hyperscale cloud providers exhibit lower price sensitivity compared to the highly competitive mobile device segment.
Supply Chain Analysis
Dual-sourcing requirements are becoming critical for System on Chip buyers to mitigate geopolitical risks and ensure supply continuity. Supply concentration remains high in Taiwan and South Korea for advanced process nodes, with China's ecosystem also expanding significantly. The supply chain relies heavily on specialized manufacturing equipment and critical IP blocks. Geopolitical disruption presents a structural risk, while distribution primarily occurs through direct sales to large OEMs and fabless design houses leveraging foundry services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The System on Chip market is consolidating, driven by the immense capital investment required for advanced process node development, forcing smaller players to exit or specialize. This dynamic reshapes competitive landscapes.
For Market Incumbents:Extend investment in advanced process node capabilities and heterogeneous integration to counter the custom silicon trend from large OEMs. Enhance IP portfolio licensing and design services for niche segments, mitigating margin pressure from commoditization in high-volume consumer electronics. Strategic partnerships with foundries in diverse geographies will also secure future supply.
For New Entrants and Emerging Players:Specialized design houses and IP providers can target underpenetrated segments like industrial IoT and edge AI applications. Focus on developing cost-optimized embedded SoCs for specific vertical markets, leveraging open-source IP integration for faster time-to-market. A go-to-market strategy emphasizing domain expertise and application-specific performance will differentiate offerings.
For Investors and Strategic Acquirers:Exit pathways concentrate in fabless design houses with unique intellectual property or specialized application expertise. The long-term viability of this market hinges on sustained demand for domain-specific compute solutions across diverse end-user applications. Watch for successful commercialization of chiplet-based designs as a key inflection indicator for future growth and M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Process Node Investment | Secures competitive advantage for high-performance Application SoCs. |
| IP Portfolio Expansion | Broadens licensing revenue and market reach across diverse applications. |
| Heterogeneous Integration R&D | Enables modular SoC designs, bypassing monolithic scaling limitations. |
| Geographic Supply Chain Diversification | Mitigates geopolitical risks for critical semiconductor fabrication. |
| Specialized Edge AI Development | Addresses the growing demand for on-device artificial intelligence processing. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for market sizing and trend analysis. Primary interviews with IC design engineers, automotive OEM architects, foundry executives, and consumer electronics product managers validated these insights. The research employed both bottom-up market estimation and top-down data validation for accuracy.
Market granularity was modeled across product type, technology, end-user, application, and key regional markets at a detailed level. The analysis derived compound annual growth rates from historical trends and future demand projections, incorporating industry-specific forecast inputs. Key inputs included the global 5G rollout pace and the increasing electronics content within automotive systems across the analysis window.
Caveats apply where geopolitical trade policies or unforeseen advancements in advanced process node yields could materially shift the outlook. Forecasts reflect documented assumptions regarding technological progression and market adoption rates. Deviation in regulatory frameworks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Microserver Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
Global Neural Processors Market