
 Wafer Back-Grinding Machine Market | 2026-2036
Wafer Back-Grinding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer Back-Grinding Machine Market Insights
Japanese precision equipment makers is restructuring supply chains for wafer thinning systems as foundries demand tighter thickness tolerances below 25 micrometers. DISCO Corporation dominates the dicing-grinding integrated equipment segment through captive abrasive technology development. TOKYO SEIMITSU leverages metrology integration to sustain premium positioning in thickness measurement-coupled grinding systems. Koyo Machinery anchors the double-side grinding niche for silicon carbide wafer preparation, where flatness specifications exceed legacy silicon requirements.
A wafer back-grinding machine thins semiconductor wafers through mechanical abrasion using diamond-bonded wheels, typically achieving final thicknesses between 50 and 750 micrometers depending on device packaging requirements. The equipment employs spindle speeds exceeding 3,000 RPM with in-line thickness gauges to prevent subsurface damage that would compromise die strength. Fully automatic grinding systems capture the largest installed base as 300mm wafer fabs prioritize throughput over manual loading flexibility. Laser grinding technology represents the fastest-expanding segment as gallium nitride and silicon carbide substrates crack under conventional mechanical stress, requiring thermal ablation methods that reduce kerf loss.
Japan's METI enforces JIS B 6191 precision standards for semiconductor processing equipment, mandating vibration control and thermal stability certifications that filter out lower-tier suppliers. The EU F-Gas Regulation restricts fluorinated greenhouse gases used in certain wafer cooling auxiliary systems, compelling equipment redesigns for European-bound installations. South Korea's MFDS coordinates with the central bank's technology investment incentives to qualify domestic back-grinding capacity as strategic infrastructure. Stakeholders must monitor how China's SAMR integrates GB standards for semiconductor equipment into import substitution programs affecting foreign machine acceptance.
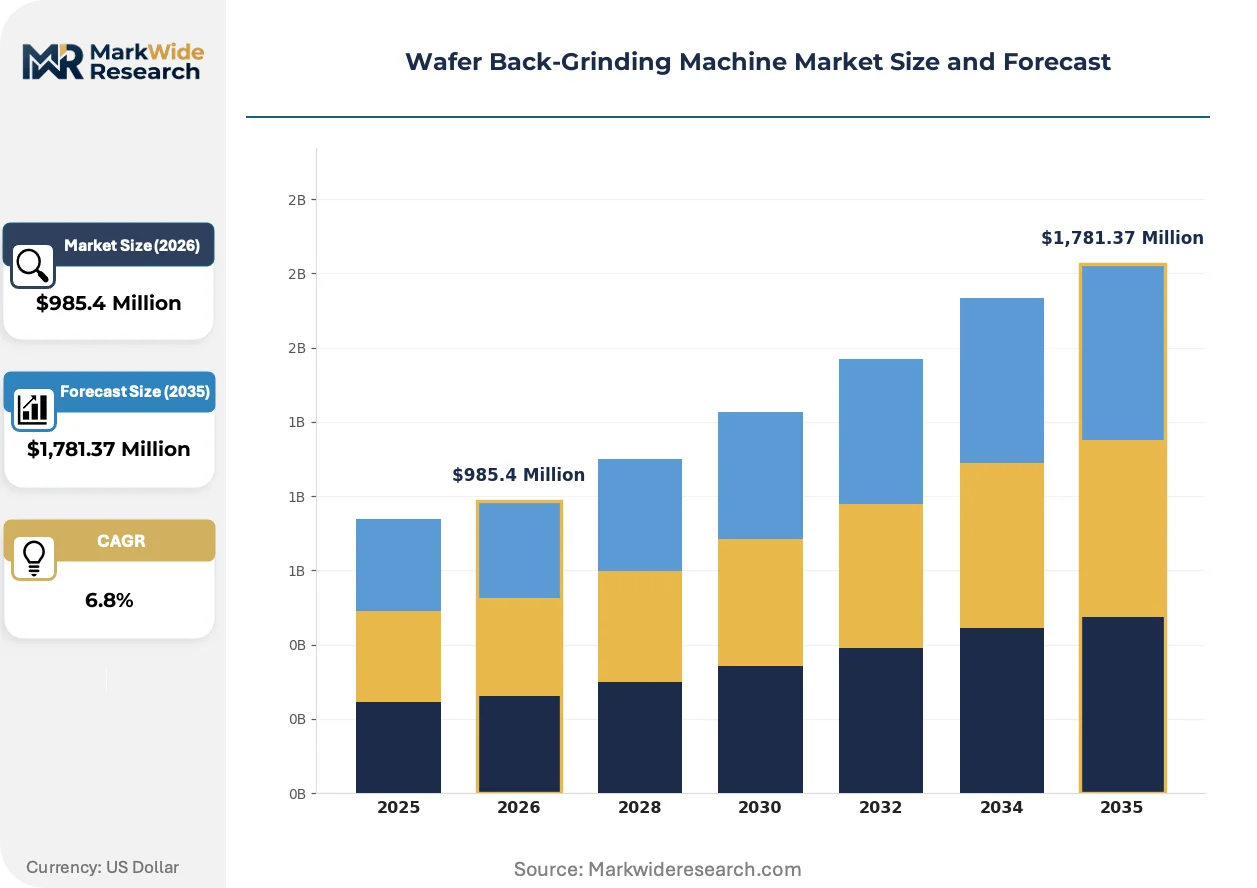
Market Dynamics
Foundry consolidation around advanced packaging nodes is compressing tolerance windows below 25 micrometers, forcing equipment architectures toward closed-loop metrology integration and thermal-stabilized spindles that eliminate vibration-induced subsurface damage.
Growth Catalysts
- Advanced Packaging Nodes:3D stacking and fan-out wafer-level packaging in Taiwan and South Korea are consuming thinned wafers at volumes that justify dedicated back-grinding lines rather than shared equipment pools.
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases in cooling auxiliary systems is accelerating equipment replacement cycles for European-bound installations as legacy systems face compliance deadlines.
- Silicon Carbide Substrates:Power electronics manufacturers are qualifying double-side grinding systems for SiC wafer preparation, where flatness specifications exceed legacy silicon requirements and command premium equipment configurations.
Market Restraints
- Diamond Abrasive Supply Concentration:Synthetic diamond wheel production concentrates among Japanese suppliers, creating input cost volatility when yen fluctuations compress equipment margins.
- REACH Chemical Compliance:EU restrictions on abrasive slurry formulations are forcing closed-loop coolant system retrofits that add 15-20% to installed base upgrade costs.
- Mechanical Stress Limitations:Gallium nitride and silicon carbide substrates crack under conventional diamond grinding parameters, restricting addressable substrate types without laser ablation capital expenditure.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic fab construction are creating first-mover advantage for equipment vendors establishing local service infrastructure before capacity ramps.
- Metrology-Converged Systems:Integration of in-line thickness gauges with real-time spindle feedback is enabling predictive maintenance contracts that capture recurring revenue streams from foundry operators.
- Laser Grinding Adoption:Thermal ablation methods for brittle compound semiconductors represent unpenetrated white space as device architectures migrate toward GaN-on-SiC power modules.
Industry Challenges
- Precision Metrology Talent Scarcity:Vibration control engineering and thermal stability certification expertise concentrates among aging specialists in Japan and Germany, constraining equipment maker expansion.
- JIS B 6191 Compliance Timelines:METI-mandated precision standards require 18-24 month certification cycles that delay product launches for non-captive suppliers.
- Legacy Spindle Integration:Retrofitting closed-loop coolant systems into installed mechanical grinding lines creates downtime conflicts with foundry production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer Back-Grinding Machine Market |
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,781.37 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Side, Double-Side, Fully Automatic, Manual Technology: Mechanical Grinding, Chemical Etching, Laser Grinding, Plasma Polishing End User: Semiconductor Manufacturers, Electronics Companies, Research Institutions, Material Suppliers Application: Thin Wafer Production, Specialty Wafer Processing, Device Packaging, Feedback Mechanism |
| Companies Covered | G&N, Koyo Machinery, DISCO Corporation, WAIDA MFG, Komatsu NTC, TOKYO SEIMITSU, Revasum, Daitron, Okamoto Machine Tool Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer Back-Grinding Machine Market Trends and Innovations
Equipment architectures are bifurcating between mechanical precision grinding for silicon and thermal ablation systems for compound semiconductors, with metrology integration becoming the common competitive battleground across both technology branches.
Closed-loop thickness gauge feedback is integrating with spindle control systems to enable real-time parameter adjustment during grind cycles. Taiwan foundries are deploying these configurations for 300mm wafer throughput optimization. The technology is integrating predictive maintenance algorithms that compress unplanned downtime intervals and shift vendor revenue toward service contracting.
The EU F-Gas Regulation is restricting fluorinated greenhouse gases in wafer cooling auxiliary systems. Equipment makers are redesigning thermal management architectures to qualify for European installations. South Korean manufacturers face the steepest compliance timeline pressure as their European export exposure exceeds regional peers.
After-sales service unbundling is accelerating as foundry operators separate equipment procurement from maintenance contracting. Independent service providers are capturing calibration and spindle refurbishment work that OEMs previously bundled. This pattern concentrates in the Hsinchu Science Park corridor where equipment density supports third-party specialization.
Wafer Back-Grinding Machine Market Segmentation
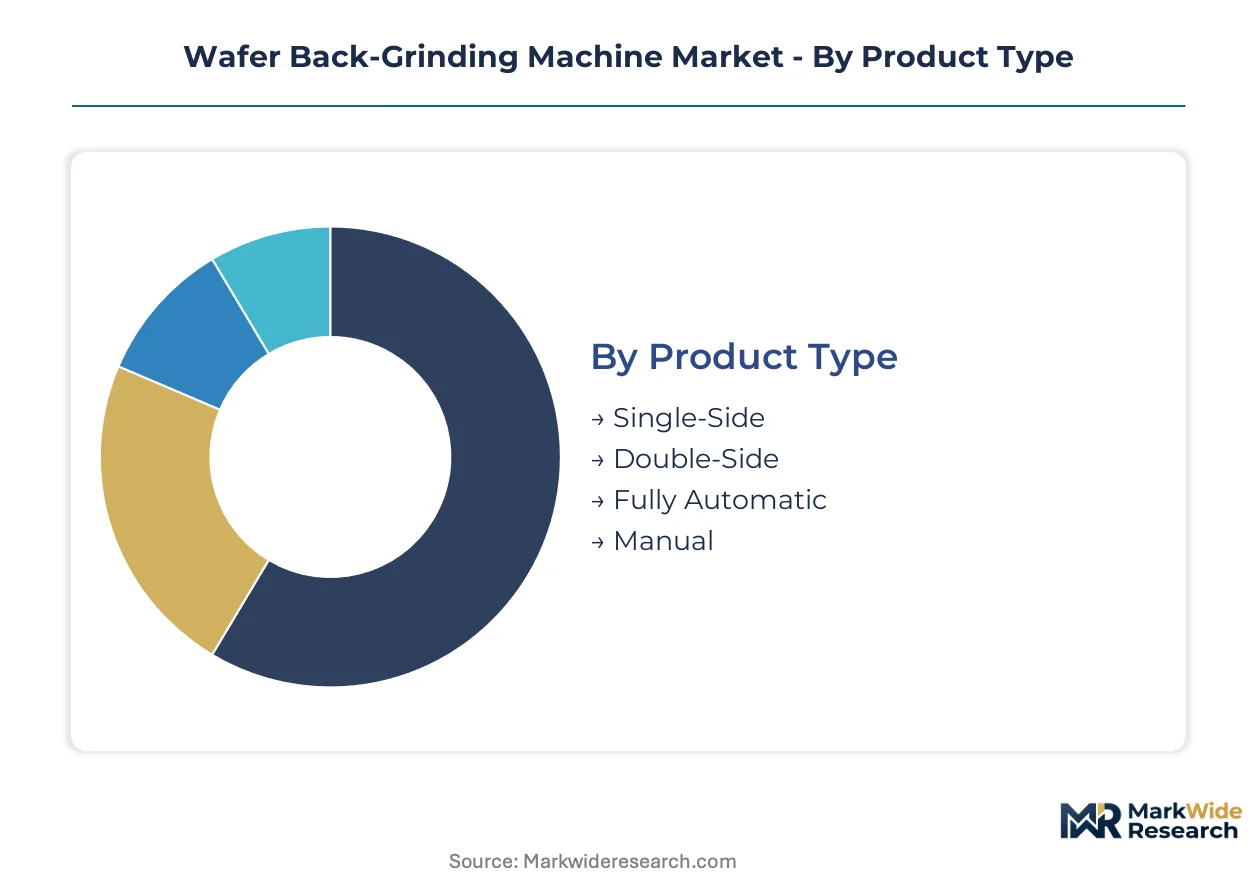
Wafer back-grinding equipment segments diverge sharply between high-volume silicon production and brittle compound semiconductor processing. Technology choices determine capital intensity, while automation levels separate foundry-scale deployments from R&D or specialty material operations.
Product Type:
Single-side systems dominate standalone installations for 300mm silicon wafer thinning, while double-side configurations embed into silicon carbide preparation lines where flatness tolerances exceed legacy requirements.
- Fully Automatic:These systems integrate cassette-to-cassette wafer handling with in-line metrology for uninterrupted 300mm production flows. Taiwan foundries deploy dedicated automatic lines for advanced packaging nodes rather than shared equipment pools, prioritizing throughput over loading flexibility.
- Double-Side:Simultaneous grinding of both wafer surfaces achieves the flatness specifications required for silicon carbide power electronics substrates. Koyo Machinery anchors this niche where specifications exceed legacy silicon requirements and command premium equipment configurations.
- Single-Side:Sequential thinning of one surface at a time suits cost-sensitive silicon operations with established tolerance windows.
- Manual:Operator-loaded systems persist in research settings and low-volume specialty material processing where flexibility outweighs throughput economics.
Fully automatic systems lead volumes today; double-side configurations are gaining share fastest.
Technology:
Cost tiers separate mature mechanical grinding from emerging thermal and chemical methods, with laser systems commanding capital premiums for compound semiconductor compatibility.
- Mechanical Grinding:Diamond-bonded wheels rotating above 3,000 RPM remain the cost baseline for silicon wafer thinning. The technology captures the largest installed base as 300mm fabs prioritize proven throughput over unproven alternatives.
- Laser Grinding:Thermal ablation removes material without mechanical stress that cracks gallium nitride and silicon carbide substrates. This method reduces kerf loss for compound semiconductors where conventional parameters fail, representing unpenetrated white space as power electronics migrate toward GaN-on-SiC architectures.
- Chemical Etching:Wet chemistry approaches thin wafers without subsurface damage for MEMS and sensor applications requiring preserved crystal structure.
- Plasma Polishing:Ionized gas processes achieve atomic-level surface finishes for photonics and high-frequency device substrates where roughness controls performance.
Mechanical grinding leads volumes today; laser grinding is climbing the fastest.
End User:
Customer type determines specification stringency, with semiconductor manufacturers demanding metrology-integrated systems while research buyers prioritize parameter flexibility over throughput guarantees.
- Semiconductor Manufacturers:Integrated device foundries and memory producers specify closed-loop thickness gauge integration with real-time spindle feedback. These buyers compress tolerance windows below 25 micrometers for 3D stacking applications, forcing equipment architectures toward thermal-stabilized spindles that eliminate vibration-induced subsurface damage.
- Electronics Companies:OSATs and packaging houses purchase grinding capacity for fan-out wafer-level packaging lines where thinned wafers enable higher I/O density.
- Research Institutions:Universities and national laboratories acquire manual or semi-automatic systems for process development and material characterization studies.
- Material Suppliers:Wafer vendors invest in grinding capability to deliver pre-thinned substrates to device manufacturers lacking in-house thinning operations.
Semiconductor manufacturers lead volumes today; electronics companies are expanding capacity fastest.
Application:
Maturity gradients separate established thin wafer production from emerging feedback mechanism integration, where real-time control systems enable predictive maintenance revenue models.
- Thin Wafer Production:Standardized thinning to 50-750 micrometer final thickness supports wire bond and flip-chip packaging across memory, logic, and power devices. This application commands the largest equipment base as foundry consolidation around advanced packaging nodes consumes thinned wafers at dedicated-line volumes.
- Device Packaging:Back-grinding enables 3D stacking and fan-out architectures where vertical integration of multiple die demands precise thickness control for through-silicon via alignment.
- Specialty Wafer Processing:Silicon carbide and gallium nitride substrates require modified grinding parameters or alternative technologies to prevent fracture.
- Feedback Mechanism:In-line thickness gauges integrated with spindle control systems enable real-time parameter adjustment during grind cycles, shifting vendor revenue toward service contracting models.
Thin wafer production leads volumes today; feedback mechanism integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan commands denser back-grinding equipment concentration than South Korea despite comparable foundry output, reflecting Taiwan's earlier commitment to dedicated thinning lines for advanced packaging. Equipment procurement patterns diverge sharply across manufacturing clusters. Regulatory compliance timelines reshape investment calendars differently in each jurisdiction.
Taiwan
Foundries in the Hsinchu Science Park corridor are expanding dedicated back-grinding capacity for 3D stacking applications rather than sharing equipment across packaging nodes. The National Science and Technology Council coordinates fab infrastructure incentives with central bank technology lending programs. Taichung's precision machinery suppliers cluster around OEM service contracts for spindle refurbishment and calibration work.
South Korea
Memory producers and system foundries are qualifying double-side grinding systems for silicon carbide substrate preparation as power electronics capacity expands. The MFDS coordinates with technology investment incentives to classify domestic back-grinding capacity as strategic infrastructure. Pyeongtaek and Yongin manufacturing zones concentrate equipment installations serving HBM packaging requirements.
Japan
Precision equipment makers are restructuring supply chains for wafer thinning systems as foundries demand thickness tolerances below 25 micrometers. METI enforces JIS B 6191 precision standards mandating vibration control and thermal stability certifications that filter lower-tier suppliers. Tokyo and Nagoya industrial corridors host captive abrasive technology development and metrology integration specialists.
China
Domestic fab construction is accelerating import substitution programs affecting foreign machine acceptance protocols. The SAMR integrates GB standards for semiconductor equipment into qualification requirements for domestic procurement. Shanghai and Beijing semiconductor manufacturing clusters are deploying closed-loop coolant systems to preempt future chemical compliance restrictions.
United States
Compound semiconductor foundries are piloting laser grinding technology for gallium nitride substrates that fracture under conventional mechanical parameters. The EPA monitors abrasive slurry disposal practices though REACH-equivalent federal restrictions remain less stringent than European counterparts. Arizona and Texas fab corridors concentrate equipment procurement for advanced packaging pilot lines.
Wafer Back-Grinding Machine Market Competitive Landscape
Japanese producers anchor the premium tier through precision certification dominance; German and American specialists hold positions in compound semiconductor processing niches. The vendor base separates into integrated dicing-grinding system architects, metrology-coupled grinding specialists, and double-side configuration experts for brittle substrates. Three strategic archetypes define competitive positioning: captive technology developers, metrology integrators, and service-contracting enablers. Equipment makers are pursuing predictive maintenance revenue models and geographic service infrastructure expansion as primary competitive moves.
Among Japanese precision fabricators, DISCO Corporation, TOKYO SEIMITSU, and Koyo Machinery exemplify distinct strategic positions within the equipment hierarchy. DISCO occupies a position representing integrated dicing-grinding system architecture. TOKYO SEIMITSU exemplifies the metrology-coupled grinding specialist archetype. Koyo Machinery anchors the double-side grinding niche for silicon carbide preparation requirements. These three entities collectively represent how Japanese vendors have structured competitive differentiation around technology integration depth rather than scale economics.
| Leading Market Players |
|---|
| G&N |
| Koyo Machinery |
| DISCO Corporation |
| WAIDA MFG |
| Komatsu NTC |
| TOKYO SEIMITSU |
| Revasum |
| Daitron |
| Okamoto Machine Tool Works |
| Others |
Pricing and Supply Chain Analysis
Vibration control engineering expertise concentrates in Japan's Nagoya and Tokyo industrial corridors, where labor-cost differentials between METI-certified precision specialists and regional technicians drive pricing-tier spreads across equipment categories.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for mid-tier mechanical grinding systems as domestic foundries scale HBM packaging lines. Three-tier pricing structure across premium metrology-integrated, standard automatic, and economy manual configurations separates buyers by certification requirements and after-sales bundling. Cost compression in standard-tier equipment is intensifying because Japanese yen volatility squeezes diamond abrasive input margins. OSATs and packaging houses exhibit highest price sensitivity, while integrated device foundries prioritize thermal-stabilized spindle specifications over unit economics.
Supply Chain Analysis
Spindle refurbishment and metrology calibration flows from Taiwan's Hsinchu Science Park corridor back to Tokyo and Nagoya service centers, creating reverse-logistics networks that extend equipment lifecycle value. Synthetic diamond wheel production concentrates in Japan, with coolant system components sourcing from Germany and South Korea. Supply chain risk centers on single-source vulnerability for JIS B 6191-certified vibration control subassemblies. Distribution runs through OEM-direct contracts for foundry-scale deployments and specialized distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a regulatory compounder, accelerating equipment replacement cycles as European-bound installations face compliance deadlines for fluorinated greenhouse gas phase-down.
For Market Incumbents: Deploy predictive maintenance contracting to capture recurring revenue streams from foundry operators as after-sales service unbundling accelerates. Deepen captive abrasive technology development to defend against laser grinding substitution for compound semiconductor applications. Invest in Taichung service infrastructure before India's PLI scheme incentives trigger domestic fab construction capacity ramps. For New Entrants and Emerging Players: Independent calibration specialists represent the most accessible channel partner type for wedge-free market entry. Target laser grinding white space for gallium nitride and silicon carbide substrates where conventional mechanical parameters fail. Pursue metrology-converged system architectures as the fastest-penetrating technology branch for compound semiconductor foundries. For Investors and Strategic Acquirers: Precision metrology talent holders are the most active acquirer category in this space, consolidating vibration control engineering expertise that constrains equipment maker expansion. Long-term viability hinges on service-contracting revenue mix and geographic service infrastructure depth. Monitor JIS B 6191 certification timeline extensions as inflection indicators for non-captive supplier competitive pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Coolant System Retrofit | EU REACH compliance positions vendors for European-bound installation qualification ahead of deadlines. |
| Metrology Integration Partnership | Real-time thickness gauge coupling with spindle control enables predictive maintenance revenue capture from Taiwan foundries. |
| Laser Grinding Technology Licensing | Thermal ablation methods unlock gallium nitride and silicon carbide substrate processing for power electronics migration. |
| India Service Infrastructure Pre-positioning | Domestic fab construction under PLI scheme incentives creates first-mover advantage before capacity ramps. |
| Double-Side Grinding Capacity Expansion | Silicon carbide flatness specifications exceed legacy silicon requirements and command premium equipment configurations. |
Research Methodology
Coverage spans East Asian semiconductor manufacturing clusters, European regulatory jurisdictions, and North American compound semiconductor corridors, with primary inputs from each. The analysis combines interviews with equipment engineering directors, foundry procurement managers, metrology integration specialists, and aftermarket service heads with secondary validation from METI certification records, EU F-Gas Regulation compliance filings, and SEMI equipment shipment databases. Bottom-up equipment unit estimates and top-down foundry capital expenditure triangulation anchor market sizing.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions span automation level, grinding technology, end-user category, and substrate material compatibility. CAGRs derive from equipment shipment run-rates, foundry capacity buildout schedules, and technology substitution curves for laser versus mechanical grinding methods. Forecast inputs incorporate JIS B 6191 certification cycle durations and EU REACH chemical restriction implementation timelines.
Revisions become necessary when regulatory compliance deadlines shift, diamond abrasive supply disruptions materialize, or compound semiconductor substrate adoption accelerates beyond mechanical grinding stress thresholds. Forecasts reflect documented assumptions about foundry consolidation patterns and packaging node evolution. Practitioners should monitor METI precision standard updates, EU F-Gas phase-down enforcement intensity, and India PLI scheme disbursement schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
United States Chip Mounter Market