
 Data Center Chip Market | 2026-2036
Data Center Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Chip Market Intelligence
Project finance for hyperscale buildouts is tilting competitive dynamics toward capital-rich cloud operators. NVIDIA leverages its CUDA software ecosystem to sustain pricing power in AI training silicon. Intel anchors its position through in-house fabrication and foundry services for government clients. AMD competes aggressively on datacenter CPU core density and energy efficiency metrics.
Data center chips are semiconductor devices engineered for continuous high-throughput computation in controlled environments, typically fabricated on process nodes of 5nm or below with thermal design power ratings exceeding 200 watts for AI accelerators. Their primary purpose is to execute parallel workloads for machine learning inference, cloud virtualization, and enterprise database operations. GPU segments command the dominant share of AI-specific revenue pools, while ASIC architectures are gaining traction among cloud providers seeking workload-optimized efficiency. CPU demand from enterprise virtualization remains mature with stable replacement cycles, whereas FPGA adoption concentrates in telecom edge deployments requiring field-reprogrammable logic.
The US CHIPS and Science Act directs NHTSA and Department of Commerce funding toward domestic advanced packaging facilities, tightening market access for non-compliant suppliers. The EU AI Act through EMA coordination imposes risk-classification requirements on chips deployed in high-stakes inference systems, reshaping product certification pathways. China's MIIT dual carbon goals and GB standards enforce power-efficiency thresholds that filter import eligibility for foreign silicon. Stakeholders must monitor how export control alignment across these jurisdictions reshapes foundry allocation and design tool licensing before committing to multi-billion dollar fab investments.
Market Dynamics
Capital allocation for AI training clusters is compressing procurement cycles and forcing foundry capacity commitments three years ahead of silicon tape-out. Cloud operators now dominate wafer allocation negotiations, displacing traditional enterprise server vendors from leading-edge node access.
Growth Catalysts
- EU AI Act risk-classification framework:High-stakes inference deployments must deploy certified silicon, creating compliant product premiums and dedicated revenue pools for verified suppliers.
- Cloud virtualization density requirements:Enterprise database consolidation onto fewer physical hosts drives CPU core count expansion and memory bandwidth upgrades in controlled environment facilities.
- GB standards enforcement:China's MIIT power-efficiency thresholds filter import eligibility, redirecting domestic demand toward locally compliant foundry output and advanced packaging capacity.
Market Restraints
- Leading-edge node concentration:Taiwan and South Korea control 5nm and below fabrication, exposing supply continuity to single-point geopolitical disruption.
- EUV lithography equipment scarcity:ASML's annual system output caps foundry expansion regardless of capital availability, stretching delivery timelines for new capacity.
- Thermal design power escalation:AI accelerators exceeding 700 watts strain conventional air-cooled infrastructure, forcing liquid cooling retrofits that compress facility-level returns.
Strategic Opportunities
- US CHIPS Act advanced packaging incentives:NHTSA and Department of Commerce funding redirects supply chains toward domestic substrate and interposer capacity, creating captive supply advantages for compliant designers.
- Telecom edge FPGA deployments:Field-reprogrammable logic addresses latency-sensitive inference at base station density, opening volume pools outside hyperscale concentration.
- Convergence of silicon photonics and CPO:Co-packaged optical I/O reduces electrical trace lengths, enabling rack-scale bandwidth density that electrical signaling cannot match.
Industry Challenges
- Advanced packaging process engineering talent:Through-silicon via yield optimization and hybrid bonding expertise concentrates at a handful of Asian subcontractors, constraining geographic diversification.
- Multi-billion dollar fab construction timelines:Cleanroom qualification and tool installation extend five to seven years, misaligning capacity arrival with demand cycle peaks.
- Export control alignment complexity:Divergent US, EU, and Chinese licensing regimes fragment design tool access and IP core availability across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Chip Market |
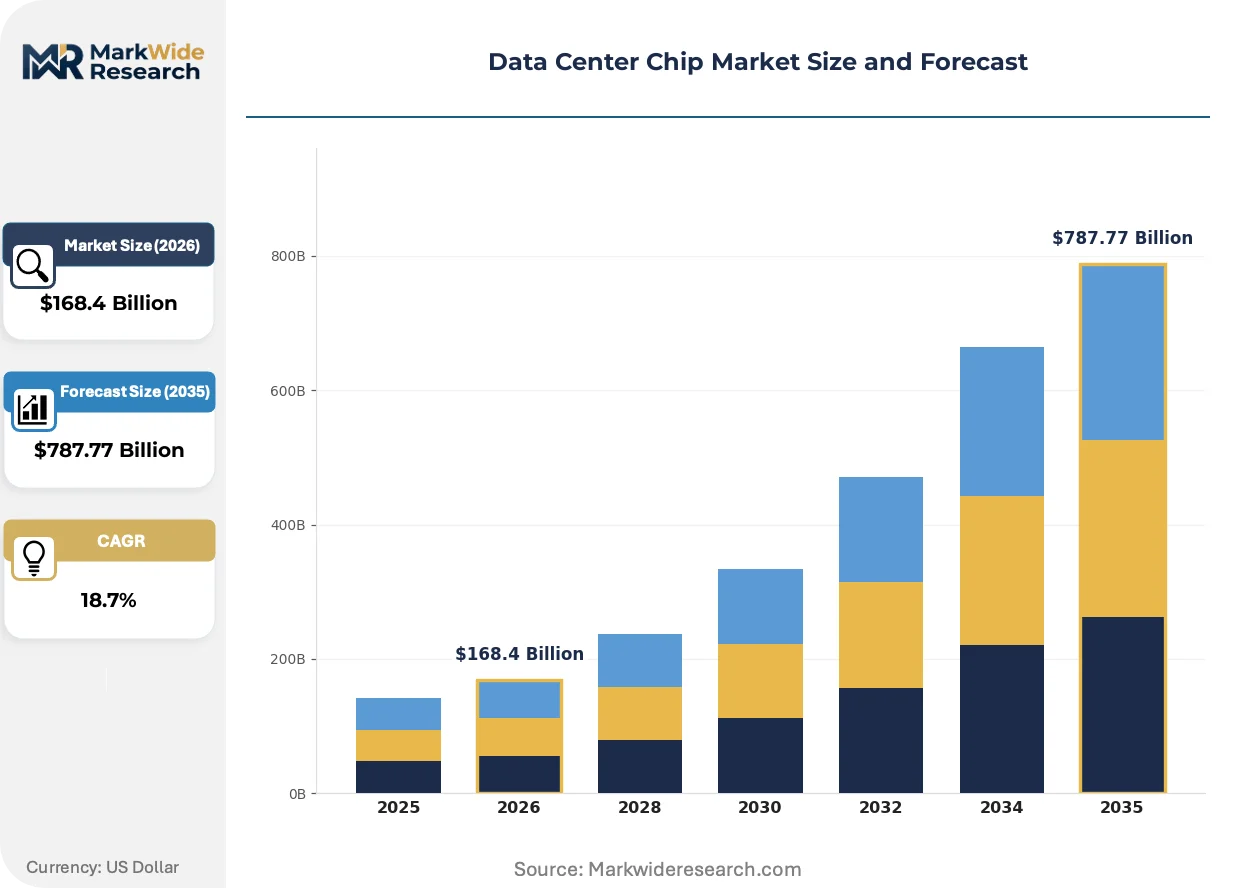
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $787.77 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPU, GPU, FPGA, ASIC Technology: Silicon, Gallium Nitride, CMOS, BiCMOS End User: Cloud Providers, Telecom Operators, Enterprises, Government Agencies Form Factor: Modular, Integrated, Discrete, System-on-Chip |
| Companies Covered | Broadcom, Cerebras Systems, NVIDIA, Microsoft, Amazon (AWS), Intel, Qualcomm, Google (Alphabet), AMD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Chip Market Strategic Shifts & Innovations
Workload-specific silicon architectures are fragmenting the general-purpose processor monopoly that dominated prior decades. Custom accelerators now command dedicated foundry tape-outs, reshaping competitive positioning around software-hardware co-design capabilities rather than transistor density alone.
Chiplet-based disaggregation is migrating from experimental prototypes to volume production roadmaps. AMD and Intel now ship multi-die CPUs as standard configurations, while cloud providers commission custom accelerators built from reusable die libraries. This modularity compresses time-to-market for specialized silicon and enables performance tiering without full reticles, though it concentrates advanced packaging capacity at TSMC and Intel Foundry Services.
The EU AI Act through EMA coordination imposes pre-deployment conformity assessment on chips destined for high-stakes inference systems. Product certification pathways now require documented training data provenance and failure-mode analysis, extending time-to-revenue by six to twelve months for affected SKUs. Medical imaging and autonomous system silicon suppliers are restructuring quality management systems to capture this compliant premium.
Hyperscale procurement patterns now favor direct foundry relationships over merchant silicon intermediaries. Amazon, Google, and Microsoft negotiate wafer starts directly with TSMC and Samsung Foundry, commissioning custom ASICs that displace merchant GPU volumes in internal workloads. This concentration is most visible in the United States, where cloud operators account for the majority of leading-edge node allocation outside smartphone applications.
Data Center Chip Market Segmentation
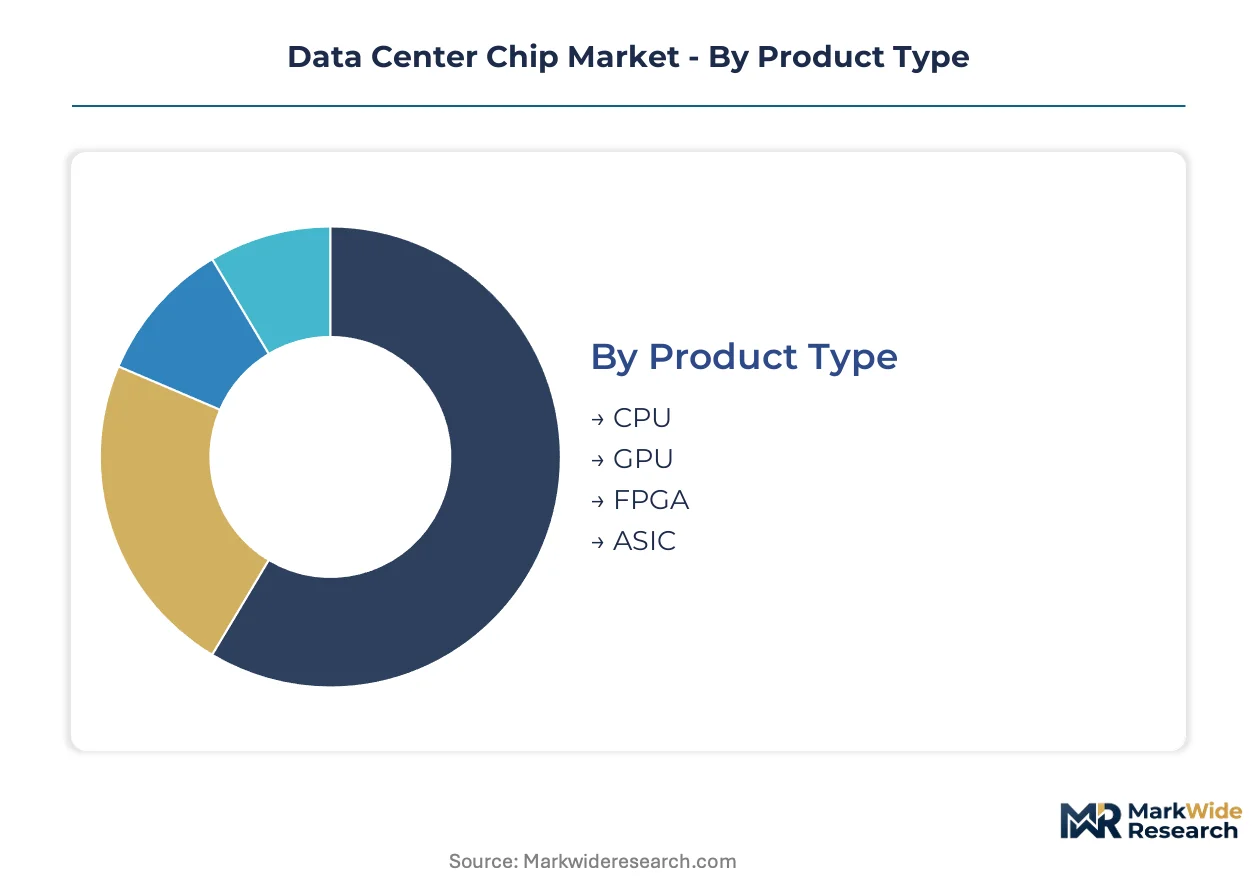
Segmentation in data center silicon reveals divergent procurement rhythms and margin profiles across product architectures. Cloud operators now segment their procurement portfolios between high-volume training accelerators and latency-sensitive inference engines. Understanding these cycle-time differentials enables suppliers to align capacity commitments with actual demand velocity rather than aggregate market forecasts.
Product Type:
GPU accelerators turn over fastest at 18-24 month cadences as training clusters scale, while enterprise CPUs cycle through 4-5 year replacement windows. FPGA and ASIC procurement sits between these extremes depending on workload specificity.
- GPU:Parallel processing architectures dominate AI training workloads with thermal design power ratings exceeding 700 watts. Demand concentrates in United States hyperscale facilities where cloud providers negotiate direct foundry allocations for custom configurations. NVIDIA's CUDA ecosystem sustains pricing power despite emerging competitive silicon.
- CPU:General-purpose processors execute virtualization and database workloads with mature instruction set architectures. Enterprise consolidation in Germany and Japan drives core-count expansion as physical server counts compress. Intel and AMD compete on energy efficiency metrics and socket compatibility.
- FPGA:Field-reprogrammable logic enables telecom edge deployments requiring post-deployment reconfiguration. Japan's NTT and Germany's Deutsche Telekom deploy these for base station density.
- ASIC:Application-specific designs optimize inference efficiency for fixed workloads. Google and Amazon commission custom tape-outs displacing merchant volumes.
CPU anchors the volume base while ASIC gains share at the steepest rate as cloud providers internalize accelerator design.
Technology:
Process node economics stratify this category between leading-edge silicon commanding premium pricing and mature-node alternatives serving cost-sensitive volumes.
- Silicon:Dominant substrate material fabricated at 5nm and below for AI accelerators with EUV lithography. Taiwan and South Korea foundries control supply concentration.
- Gallium Nitride:Wide bandgap compound enables power conversion efficiency in high-density rack infrastructure. United States defense applications and telecom rectifier deployments in South Korea drive qualification cycles.
- CMOS:Complementary metal-oxide-semiconductor process underpins mainstream logic production with mature yield curves. Enterprise storage controllers and networking silicon in Japan leverage these nodes.
- BiCMOS:Bipolar-CMOS integration serves mixed-signal applications requiring analog precision with digital density. Precision timing and SerDes interfaces in German automotive-grade data centers specify these processes.
Silicon maintains absolute volume leadership while Gallium Nitride expands most quickly from power electronics penetration into thermal management subsystems.
End User:
Procurement authority concentrates differently across this dimension, with cloud operators wielding direct foundry negotiation leverage while government buyers impose compliance premiums.
- Cloud Providers:Hyperscale operators commission custom silicon through direct TSMC and Samsung Foundry relationships. United States facilities account for dominant leading-edge allocation outside smartphone applications. Amazon, Google, and Microsoft displace merchant GPU volumes with internal ASIC programs.
- Telecom Operators:5G infrastructure and edge computing deployments require latency-optimized inference at base station density. Japan's METI and South Korea's MSIT subsidize domestic silicon adoption.
- Enterprises:Traditional IT procurement cycles favor merchant CPU and GPU solutions with established software ecosystems. German automotive and Japanese financial services sectors drive replacement demand.
- Government Agencies:National security applications mandate domestic foundry sourcing under US CHIPS Act and EU chip sovereignty programs. NHTSA and Department of Commerce funding tightens market access for non-compliant suppliers.
Cloud Providers command the steepest expansion trajectory while Enterprises retain the broadest installed base requiring refresh cycles.
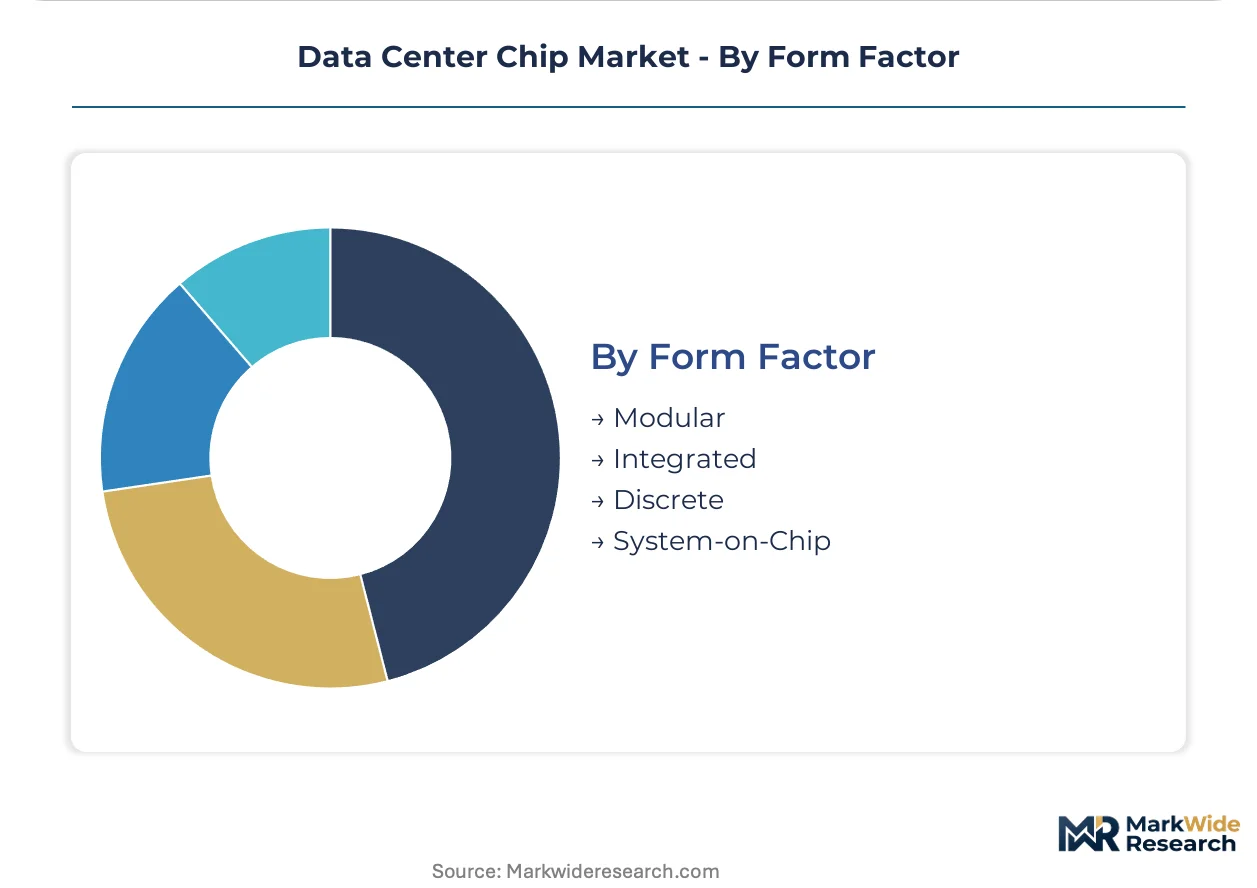
Form Factor:
Integration density determines thermal and electrical performance ceilings, with modular designs enabling disaggregation against system-on-chip consolidation.
- Modular:Chiplets and multi-die packages enable mix-and-match performance tiering without full reticle costs. AMD and Intel ship standard multi-die CPUs while cloud providers commission reusable die libraries.
- Integrated:Co-packaged optical and electrical I/O reduces trace lengths for rack-scale bandwidth density. Silicon photonics convergence targets United States hyperscale facilities.
- Discrete:Standalone components serve legacy infrastructure and specialized acceleration cards. European enterprise refresh cycles sustain this segment.
- System-on-Chip:Maximum integration for power-constrained edge deployments and mobile-influenced designs. China's MIIT efficiency thresholds filter import eligibility toward compliant domestic output.
Modular configurations anchor volume production roadmaps while Integrated form factors climb fastest from co-packaged optical adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US CHIPS Act and EU AI Act are redirecting foundry investment toward compliant jurisdictions, while China's MIIT efficiency standards filter import eligibility. Taiwan and South Korea retain leading-edge node concentration, but geographic diversification is accelerating through subsidized domestic capacity.
United States
Hyperscale cloud operators commission custom ASICs through direct TSMC and Samsung Foundry negotiations. The Department of Commerce and NHTSA direct funding toward advanced packaging facilities under CHIPS Act implementation. Arizona and Texas host the primary fab construction clusters where Intel Foundry Services and TSMC are expanding 3nm-class capacity.
Taiwan
TSMC controls the dominant share of 5nm and below EUV fabrication for AI accelerators and high-performance CPUs. The National Development Council coordinates supply continuity protocols amid geopolitical exposure concerns. Hsinchu Science Park anchors the densest concentration of leading-edge process engineering talent and tool installation.
South Korea
Samsung Foundry and SK Hynix supply HBM memory and logic fabrication for training clusters. MSIT subsidizes domestic silicon adoption for telecom edge and AI inference deployments. Pyeongtaek and Yongin host the primary memory and logic fabrication complexes where 3nm GAA processes are ramping.
China
MIIT dual carbon goals and GB standards enforce power-efficiency thresholds that constrain foreign silicon import eligibility. Domestic foundries redirect capacity toward locally compliant advanced packaging and mature-node logic. Shanghai and Beijing-Tianjin-Hebei clusters concentrate government-funded design houses and SMIC expansion.
Germany
Automotive-grade data centers drive demand for precision timing and mixed-signal silicon under stringent reliability specifications. The EU AI Act through EMA coordination imposes risk-classification requirements on chips for high-stakes inference systems. Dresden and Bavaria host the primary semiconductor manufacturing regions where Intel and TSMC are negotiating subsidized fab investments.
Data Center Chip Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Cloud operators with direct foundry relationships now displace merchant silicon intermediaries, compressing margins for traditional server vendors. Three archetypes dominate: vertically integrated IDMs with captive fabrication, fabless designers dependent on external foundry access, and hyperscale cloud providers commissioning custom silicon. Competitive moves concentrate on securing multi-year wafer allocation commitments and acquiring advanced packaging engineering talent.
Within the fabless accelerator tier, NVIDIA and AMD exemplify divergent ecosystem strategies, while Intel occupies a distinct position as an IDM with foundry service ambitions. Among cloud-commissioned silicon, Amazon, Google, and Microsoft represent the vertical integration archetype through internal ASIC programs. Cerebras Systems and Broadcom occupy specialized positions in wafer-scale and connectivity silicon respectively. These players collectively illustrate the market's bifurcation between software-anchored ecosystem control and workload-optimized hardware efficiency.
| Leading Market Players |
|---|
| Broadcom |
| Cerebras Systems |
| NVIDIA |
| Microsoft |
| Amazon (AWS) |
| Intel |
| Qualcomm |
| Google (Alphabet) |
| AMD |
| Others |
Cost & Logistics Intelligence
The Kaohsiung-to-Los Angeles transpacific freight corridor transmits cost volatility from Asian foundry clusters directly into landed silicon pricing, amplifying spreads between certified EU AI Act-compliant inventory and standard-grade alternatives while hyperscale buyers leverage volume commitments to compress procurement premiums.
Pricing Analysis
Certification level under EU AI Act risk-classification frameworks creates the primary spread between premium and standard tiers, with EMA-coordinated conformity assessments adding six-to-twelve month qualification delays that suppliers monetize through compliant-product premiums. NVIDIA's CUDA-anchored ecosystem sustains value-based licensing against transactional per-unit alternatives, while AMD competes on core-density metrics that appeal to price-sensitive enterprise virtualization buyers. Pricing pressure stems from cloud providers negotiating direct foundry allocations that displace merchant silicon intermediaries, compressing margins for traditional server vendors. Government agencies under US CHIPS Act mandates exhibit lowest price sensitivity due to domestic-sourcing requirements, whereas telecom operators in Japan and Germany face METI and KBA efficiency thresholds that filter toward cost-optimized FPGA deployments.
Supply Chain Analysis
High-purity silicon wafers, EUV lithography equipment, and HBM memory stacks constitute the critical upstream feedstocks that constrain output elasticity regardless of capital availability. Taiwan and South Korea control leading-edge 5nm-and-below fabrication, with the United States expanding 3nm-class capacity in Arizona and Texas under CHIPS Act incentives. Single-source vulnerability concentrates at ASML's annual EUV system output caps, which stretch delivery timelines for new foundry capacity regardless of funding commitments. Distribution runs through direct hyperscale procurement relationships that displace traditional OEM and distributor channels, with Amazon, Google, and Microsoft negotiating wafer starts directly with TSMC and Samsung Foundry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center silicon sits in early-cycle expansion as AI training cluster buildouts accelerate procurement velocity and cloud providers internalize accelerator design, creating white-space opportunities for specialized packaging and photonics integration before market consolidation hardens.
For Market Incumbents: Build software-hardware co-design moats through CUDA-equivalent ecosystem lock-in and chiplet-based reusable die libraries that compress competitor time-to-market. Intel must accelerate Intel Foundry Services qualification for government CHIPS Act contracts before TSMC's Arizona ramp captures captive US demand. NVIDIA should defend against emerging ASIC displacement by embedding inference optimization deeper into cloud provider workflows, while AMD expands energy efficiency leadership in enterprise CPU sockets threatened by ARM-based alternatives. For New Entrants and Emerging Players: Pursue advanced packaging engineering talent scarcity as the primary white-space vector, with through-silicon via yield optimization and hybrid bonding expertise concentrating at Asian subcontractors that geographic diversification incentives now destabilize. Telecom edge FPGA deployments in Japan's NTT and Germany's Deutsche Telekom base stations offer the most penetrable volume pool outside hyperscale concentration, with latency-sensitive inference requirements that favor field-reprogrammable logic over fixed ASICs. A go-to-market angle anchored to silicon photonics and co-packaged optical I/O addresses rack-scale bandwidth density limits that electrical signaling cannot match. For Investors and Strategic Acquirers: Fabless designers with advanced packaging process engineering capabilities and established foundry allocation commitments represent the highest-conviction acquisition archetype for five-to-ten year holding periods. Long-term viability hinges on securing multi-year wafer starts before cloud provider internalization of accelerator design commoditizes merchant silicon volumes. The signal to monitor is hyperscale ASIC program cancellation rates, which would indicate reversion toward merchant GPU and FPGA procurement that benefits ecosystem-anchored incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Buildout | Domestic substrate and interposer facilities under CHIPS Act funding create captive supply advantages for compliant designers. |
| Direct Foundry Relationship Formation | Hyperscale cloud operators negotiating wafer starts with TSMC and Samsung Foundry displace merchant silicon intermediaries. |
| EU AI Act Certification Investment | EMA-coordinated conformity assessments extend time-to-revenue but unlock premium pricing in medical imaging and autonomous systems. |
| Silicon Photonics Integration | Co-packaged optical I/O reduces electrical trace lengths for rack-scale bandwidth density in United States hyperscale facilities. |
| Chiplet-Based Design Library Development | Reusable die architectures compress time-to-market for specialized silicon and enable performance tiering without full reticle costs. |
Research Approach
Cross-validation between hyperscaler capex disclosures and foundry utilization reports anchors the qualitative findings, with primary interviews involving cloud procurement officers, semiconductor process engineers, and regulatory affairs specialists at EU notified bodies combined against secondary validation through SEC 10-K filings, EMA submission databases, and MIIT GB standard updates. Bottom-up triangulation aggregates individual product-line revenue disclosures while top-down calibration benchmarks against aggregate wafer start data from TSMC and Samsung Foundry.
Calibration against historical hyperscale infrastructure deployment cycles and foundry capacity ramp timelines informs the projection framework across the analysis window. Segmentation dimensions span product architecture, process node technology, end-user procurement authority, and form factor integration density, with CAGRs derived from elasticity modeling of cloud provider AI training spend against EUV equipment delivery constraints. Industry-specific forecast inputs include ASML system output schedules and CHIPS Act funding disbursement trajectories.
Sensitivities concentrate around export control alignment shifts, foundry construction timeline extensions, and thermal design power escalation beyond air-cooled infrastructure limits. Forecasts reflect documented assumptions regarding cloud provider ASIC program momentum and EU AI Act enforcement consistency. Cross-checking against hyperscaler earnings call commentary on infrastructure deployment cadence is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Microserver Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
System on Chip (Soc) Market