
 Global Automotive MCU Market | 2026-2036
Global Automotive MCU Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive MCU Market Foresight
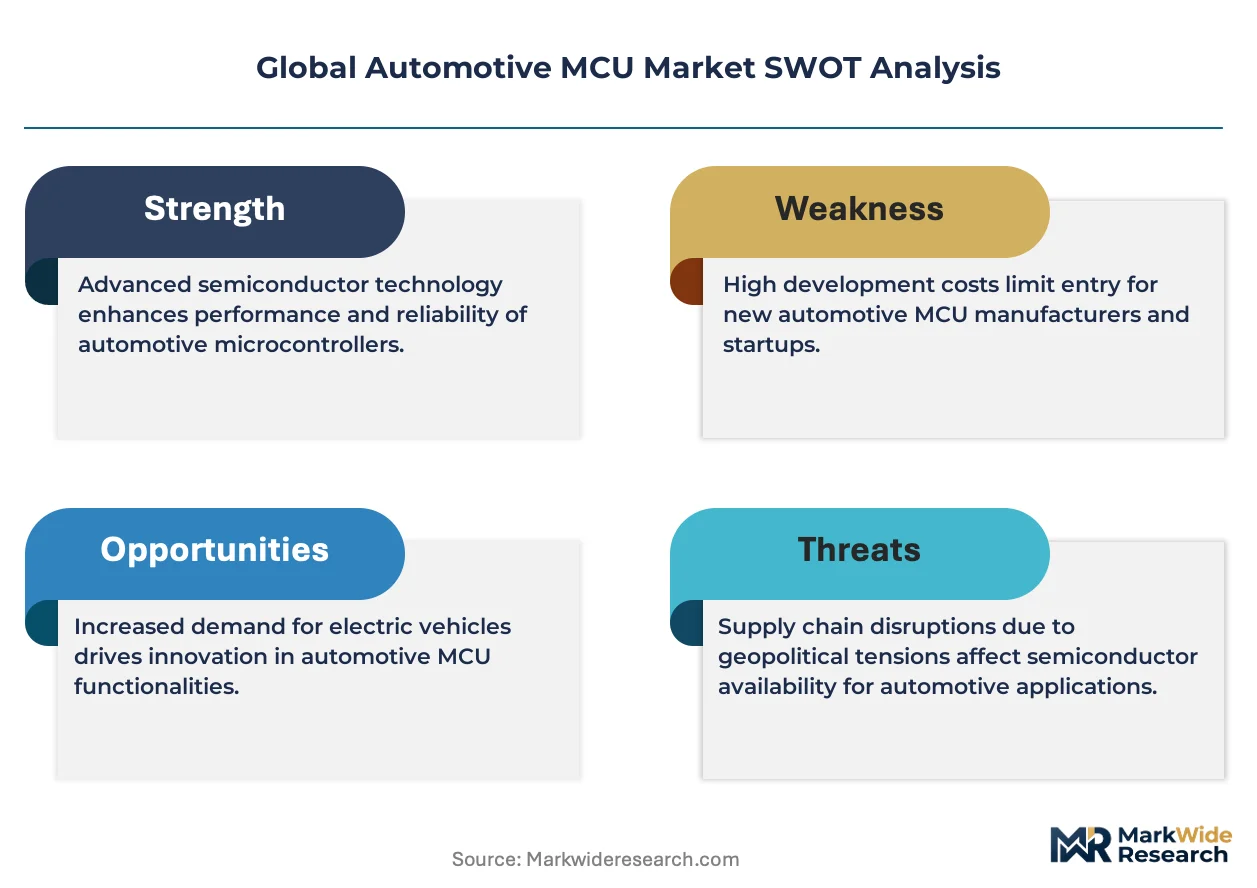
Platform licensing revenue is tilting toward embedded software stacks and functional safety certification services rather than discrete silicon sales. Infineon Technologies AG leverages its captive fab capacity in Dresden to sustain supply commitments to German OEMs. NXP Semiconductors N.V. anchors its automotive franchise through domain-architecture MCUs that consolidate body and powertrain control. Renesas Electronics Corporation specializes in RISC-V roadmap extensions for software-defined vehicle platforms.
An automotive microcontroller unit integrates a processor core, volatile and non-volatile memory, and multiple analog and digital peripherals onto a single die, typically manufactured on 40nm to 28nm process nodes with operating temperatures spanning minus forty to one hundred fifty degrees Celsius. These devices execute real-time control functions across engine management, chassis systems, and cabin electronics where deterministic latency is mandatory. Thirty-two-bit MCUs now capture the dominant margin pool as electrified powertrains and ADAS domains demand higher compute throughput and ASIL-D safety ratings. Application-specific MCUs for battery management systems represent the fastest-expanding category within the product-type dimension. ARM Cortex cores retain technology leadership while RISC-V adoption accelerates among Asian chip designers seeking instruction-set independence.
The EPA tailpipe emissions framework and NHTSA safety mandates in the United States, alongside the EU Green Deal and REACH substance restrictions in Europe, compel MCU vendors to certify silicon for extended temperature ranges and hazardous-substance compliance. Japan's METI directs domestic semiconductor investment toward automotive-grade capacity expansion. Stakeholders must monitor foundry allocation decisions between consumer and automotive process nodes as capacity constraints force qualification trade-offs.
Market Dynamics
The automotive MCU landscape is compressing around domain-centralized architectures where zonal controllers replace distributed ECUs, forcing silicon vendors to recertify products for ASIL-D safety ratings under tighter thermal budgets.
Growth Catalysts
- ISO 26262 functional safety mandates:ASIL-D certification requirements for autonomous braking and steer-by-wire systems are pulling 32-bit MCUs into chassis domains previously served by simpler 8-bit devices.
- China's dual carbon goals:Domestic OEM procurement quotas for locally-designed battery management systems are accelerating RISC-V MCU adoption by fabless designers in Shenzhen and Shanghai.
- Silicon carbide powertrains:Wide-bandgap inverter switching frequencies above 100kHz demand real-time gate control that legacy analog solutions cannot deliver.
Market Restraints
- Automotive-grade foundry concentration:Taiwan-based pure-play foundries control over 80% of 40nm-28nm capacity qualified for AEC-Q100 Grade 0, creating single-source vulnerability for European and Japanese MCU vendors.
- Copper and gold bond wire volatility:Packaging material costs swing 15-30% quarterly, compressing gross margins on sub-dollar 8-bit units where die size cannot shrink further.
- Legacy 8-bit code bases:Decades of proprietary assembly firmware in powertrain controllers block migration paths to 32-bit architectures without complete software rewrites.
Strategic Opportunities
- Software-defined vehicle platforms:Over-the-air update capabilities are creating attach-rate opportunities for secure-element MCUs with hardware root-of-trust in gateway modules.
- India's PLI scheme for automotive electronics:Tier-1 suppliers establishing Chennai and Pune facilities require localized MCU sourcing partnerships to meet domestic value-add thresholds.
- EU battery passport mandates:Cell-level monitoring ICs with embedded MCUs must log state-of-health data across 15-year vehicle lifecycles, opening aftermarket firmware service revenue streams.
Industry Challenges
- Functional safety engineer scarcity:ASIL-D certification expertise concentrates in Munich, Stuttgart, and Nagoya, forcing vendors to bid against German OEM captive engineering centers for talent.
- Multi-year qualification timelines:AEC-Q100 Grade 0 testing across temperature cycling and electromigration consumes 18-24 months, locking product roadmaps before volume demand materializes.
- Legacy LIN bus integration:Door modules and seat controllers still communicate at 20kbps, forcing 32-bit MCUs to maintain costly legacy peripheral support alongside high-speed Ethernet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive MCU Market |
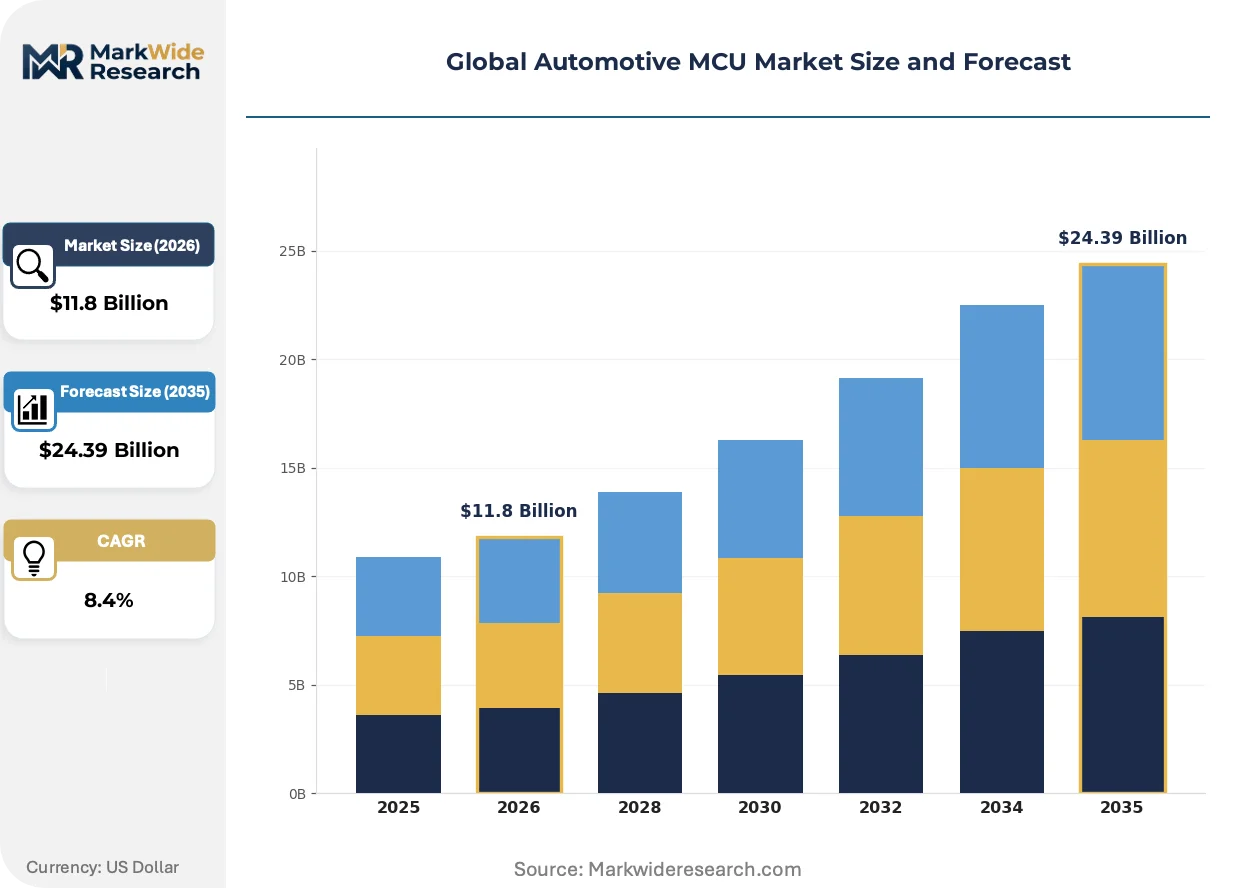
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 32-bit MCUs, 16-bit MCUs, 8-bit MCUs, Application-Specific MCUs Technology: Flash Memory, EEPROM, RAM Embedded, ARM Cortex, RISC-V Application: Powertrain Control, Infotainment Systems, Advanced Driver Assistance, Body Electronics End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Producers, Vehicle Assemblers |
| Companies Covered | STMicroelectronics N.V., Microchip Technology Inc., Infineon Technologies AG, ON Semiconductor Corp., Analog Devices Inc., NXP Semiconductors N.V., Texas Instruments Incorporated, Broadcom Inc., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive MCU Market Shifts & Advancements
Electrification and software-defined architectures are collapsing the traditional boundary between powertrain and body electronics, forcing MCU vendors to consolidate heterogeneous compute onto single dies while maintaining deterministic real-time guarantees.
Virtual machine hypervisors for mixed-criticality workloads are virtualizing the hardware abstraction layer that once separated infotainment from safety-critical domains. German OEMs now specify dual-core lockstep configurations where one virtual partition runs POSIX-compliant middleware while the second maintains sub-millisecond interrupt response for motor control. This consolidation is virtualizing the discrete MCU supplier base by disqualifying vendors lacking functional safety software stacks.
REACH substance restrictions on lead finishes and halogenated flame retardants are forcing packaging redesigns across Dresden, Toulouse, and Kyoto assembly sites. The industrial consequence extends beyond materials compliance to supply chain requalification, as every solder joint and mold compound change triggers AEC-Q100 retesting. Battery management system MCUs face the tightest scrutiny, with EU importers now requiring full material disclosure down to the smelter level for conflict minerals.
Long-term service contracts with foundry partners are displacing spot-market wafer purchases as procurement behavior shifts toward captive capacity reservation. Tier-1 module makers in Michigan and Baden-Württemberg now negotiate three-year supply agreements with pre-paid capacity deposits, transferring inventory risk upstream to semiconductor vendors. This pattern is most visible in 28nm automotive node allocations, where consumer electronics demand volatility would otherwise crowd out vehicle program ramps.
Global Automotive MCU Market Segmentation
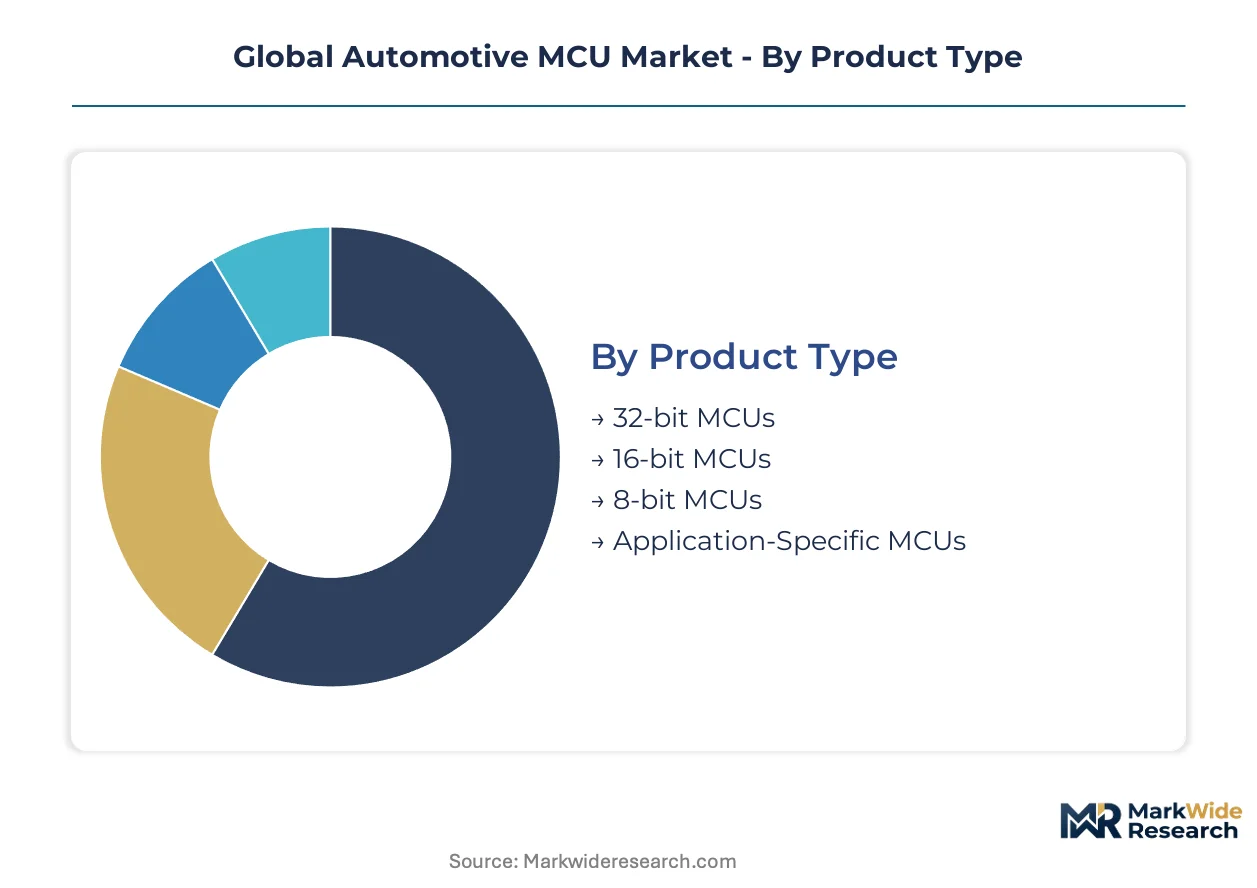
Automotive MCU segmentation reveals how silicon vendors allocate R&D across divergent performance requirements. Each dimension—bit-width, memory technology, vehicle domain, and customer tier—carries distinct qualification burdens and margin structures that reshape competitive positioning.
Product Type:
Mature 8-bit architectures coexist with emerging 32-bit dominance as electrification rewrites compute requirements across vehicle platforms.
- 32-bit MCUs:These devices integrate dual-core lockstep configurations with hardware security modules for ASIL-D functional safety. Demand concentrates in German OEM powertrain programs where silicon carbide inverters require sub-millisecond gate control loops.
- Application-Specific MCUs:Battery management system ICs embed precision analog front-ends with cell-balancing FET drivers on single die. Shenzhen-based fabless designers are capturing procurement quotas under China's dual carbon goals for localized BMS sourcing.
- 16-bit MCUs:Transitional architectures persist in Japanese chassis controllers where legacy code bases resist full 32-bit migration.
- 8-bit MCUs:Minimalist cores serve door modules and seat controllers communicating over 20kbps LIN bus segments.
32-bit MCUs handle the majority of throughput; application-specific MCUs are climbing the fastest on share.
Technology:
Cost tiers separate established proprietary architectures from open-instruction-set alternatives seeking supply chain independence.
- ARM Cortex:Licensed cores dominate through ecosystem maturity and pre-certified safety libraries. Stuttgart-based Tier-1 suppliers specify Cortex-M7 derivatives for domain-centralized zonal controllers consolidating body and powertrain functions.
- RISC-V:Open-source instruction sets enable custom extensions for software-defined vehicle hypervisors. Shanghai design houses leverage METI-funded Japanese foundry capacity to qualify automotive-grade RISC-V cores for domestic OEM programs.
- Flash Memory:Floating-gate cells store firmware across temperature cycling from minus forty to one hundred fifty degrees Celsius.
- EEPROM:Byte-addressable non-volatile memory retains calibration data through powertrain controller power cycles.
- RAM Embedded:SRAM macros provide deterministic access for real-time interrupt service routines.
ARM Cortex commands the revenue base; RISC-V is gaining share fastest among new design starts.
Application:
Volume concentration follows electrification intensity, with powertrain and ADAS domains displacing traditional body electronics in wafer allocation priority.
- Powertrain Control:Motor control algorithms execute on MCUs with hardware trig units and PWM synchronization. Michigan-based EV startups are qualifying 28nm MCUs for 800V silicon carbide traction inverters.
- Advanced Driver Assistance:Sensor fusion nodes require deterministic latency for camera-radar integration. Baden-Württemberg suppliers specify ASIL-D MCUs for autonomous emergency braking actuation paths.
- Infotainment Systems:Guest operating systems run on POSIX-compliant partitions virtualized alongside safety-critical domains.
- Body Electronics:Distributed door and lighting modules persist with legacy peripheral support requirements.
Powertrain control absorbs the dominant wafer volume; advanced driver assistance shows the steepest expansion trajectory.
End User Industry:
Customer type determines procurement leverage, with captive OEM engineering centers extracting qualification concessions unavailable to fragmented aftermarket channels.
- OEMs:Volkswagen Group and Toyota Motor Corporation negotiate three-year foundry capacity reservations with pre-paid deposits. Direct silicon procurement is displacing Tier-1 module sourcing for domain controller MCUs.
- Tier-1 Suppliers:Bosch and Continental AG aggregate demand across multiple OEM programs to secure 28nm automotive node allocation. These vendors maintain captive functional safety certification teams in Munich and Nagoya.
- Vehicle Assemblers:Contract manufacturers in Chennai and Pune require localized MCU sourcing to satisfy India's PLI domestic value-add thresholds.
- Aftermarket Producers:Diagnostic tool and telematics module vendors source through distribution with limited influence over road map prioritization.
OEMs command the qualification timeline; Tier-1 suppliers are expanding most quickly through domain-architecture consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry partnerships for automotive-grade silicon cluster in three distinct manufacturing corridors. Taiwan-based pure-play foundries control over 80% of 40nm-28nm capacity qualified for AEC-Q100 Grade 0. Procurement decisions by German, Chinese, and United States-based OEMs determine allocation priority across these constrained nodes.
China
Domestic OEM procurement quotas for locally-designed battery management systems are accelerating RISC-V MCU adoption by fabless designers in Shenzhen and Shanghai. The country's dual carbon goals under MEE directives mandate localized BMS sourcing for new energy vehicle programs. Yangtze River Delta fabrication clusters are qualifying automotive-grade RISC-V cores through METI-funded Japanese foundry partnerships.
Germany
Volkswagen Group and BMW AG negotiate three-year foundry capacity reservations with pre-paid deposits for domain controller silicon. EU Green Deal emissions frameworks and KBA safety mandates compel ASIL-D certification for autonomous braking systems. Baden-Württemberg engineering centers in Stuttgart anchor functional safety expertise for chassis and powertrain MCU development.
United States
Michigan-based EV startups are qualifying 28nm MCUs for 800V silicon carbide traction inverters under EPA tailpipe emissions frameworks. NHTSA safety mandates pull 32-bit MCUs into steer-by-wire chassis domains. Detroit-Warren corridor Tier-1 suppliers aggregate demand across multiple OEM programs to secure automotive node allocation.
Japan
Toyota Motor Corporation and Honda Motor Co. maintain captive functional safety certification teams in Nagoya and Tokyo. METI directs domestic semiconductor investment toward automotive-grade capacity expansion for 32-bit powertrain controllers. Chubu region engineering clusters specialize in RISC-V roadmap extensions for software-defined vehicle platforms.
India
Tier-1 suppliers establishing Chennai and Pune facilities require localized MCU sourcing to satisfy PLI scheme domestic value-add thresholds. BIS certification requirements for automotive electronics are forcing silicon vendors to recertify products for extended temperature ranges. Maharashtra and Tamil Nadu manufacturing corridors are capturing assembly-stage value from imported die.
Global Automotive MCU Market Competitive Landscape
Integrated device manufacturers and fabless specialists split the market through divergent capacity strategies. Captive fabrication assets in Dresden and proprietary process libraries create supply security advantages for vertically integrated players. Three archetypes dominate: foundry-dependent fabless designers, captive-fab integrated manufacturers, and domain-specialist architecture vendors. Competitive intensity concentrates on long-term supply agreements with pre-paid capacity deposits and functional safety software stack certification.
Within the integrated-manufacturer tier, Infineon Technologies AG and Renesas Electronics Corporation exemplify captive-fab strategies that insulate German and Japanese OEM programs from foundry allocation volatility. NXP Semiconductors N.V. occupies a position bridging fabless flexibility with domain-architecture consolidation expertise. These three anchors represent divergent responses to ASIL-D qualification timelines and zonal controller integration demands.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Microchip Technology Inc. |
| Infineon Technologies AG |
| ON Semiconductor Corp. |
| Analog Devices Inc. |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| Broadcom Inc. |
| Renesas Electronics Corporation |
| Others |
Supply & Pricing Matrix
Taiwan-based foundry concentration for AEC-Q100 Grade 0 capacity determines both the premium commanded by ASIL-D certified MCUs and the three-year contract structures displacing spot-market procurement. This single-source dependency forces German and Japanese OEMs to pre-pay capacity deposits while compressing margins on legacy 8-bit units unable to absorb packaging material volatility.
Pricing Analysis
ISO 26262 functional safety mandates dictate the pricing tier structure across automotive MCU procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D dual-core lockstep configurations from single-core ASIL-B derivatives and undifferentiated 8-bit door controllers. Price differentiation hinges on certification grade and volume scale, with million-unit powertrain programs extracting 15-20% discounts unavailable to aftermarket diagnostic vendors. Cost compression in sub-dollar 8-bit segments is intensifying because copper and gold bond wire costs swing quarterly without die-shrink offsets. Aftermarket producers exhibit the highest price sensitivity, while Volkswagen Group and Toyota Motor Corporation prioritize supply security over unit economics.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation anchor global automotive-grade foundry capacity alongside Samsung Foundry in South Korea. Raw material dependencies span silicon wafers from Shin-Etsu, specialty gases from Linde and Air Liquide, and epoxy mold compounds from Sumitomo Bakelite. Single-source vulnerability concentrates in 28nm automotive node qualification, where TSMC's process libraries are prerequisites for German OEM platform approval. Distribution runs through Tier-1 module makers in Baden-Württemberg and Michigan who aggregate demand across multiple OEM programs before foundry submission.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIL-D certification expertise scarcity concentrates in Munich, Stuttgart, and Nagoya engineering clusters, forcing vendors to bid against captive OEM centers for functional safety talent. This capability gap determines competitive survival as domain-centralized architectures collapse heterogeneous compute onto single dies.
For Market Incumbents: Insulate German and Japanese OEM supply commitments through captive fab capacity in Dresden and Tokyo while accelerating RISC-V roadmap extensions to counter Shenzhen fabless designers. Pre-pay foundry deposits for 28nm automotive node allocation defend against consumer electronics demand crowding. Domain-architecture MCU consolidation disqualifies competitors lacking functional safety software stacks. For New Entrants and Emerging Players: Pursue India's PLI scheme domestic value-add thresholds by establishing Chennai and Pune assembly partnerships for BMS MCUs with localized die sourcing. Battery management systems for new energy vehicle programs represent the most penetrable segment under China's dual carbon goals. Lead with RISC-V instruction-set independence as the go-to-market angle against ARM Cortex licensing dominance. For Investors and Strategic Acquirers: EU battery passport mandates reshape the acquisition landscape by mandating 15-year cell-level data logging infrastructure. Long-term viability centers on vendors combining secure-element MCUs with aftermarket firmware service revenue streams. Target fabless designers with automotive-grade RISC-V qualification through METI-funded Japanese foundry partnerships. Monitor foundry allocation decisions between consumer and automotive process nodes as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Functional Safety Certification | ISO 26262 compliance unlocks German OEM powertrain procurement at premium tier pricing. |
| RISC-V Architecture Roadmap Extension | Open-source instruction sets enable Shenzhen designers to bypass ARM licensing for domestic NEV quotas. |
| Captive Foundry Capacity Reservation | Three-year supply agreements with pre-paid deposits transfer inventory risk from Tier-1 module makers to semiconductor vendors. |
| Battery Management System MCU Localization | China's MEE dual carbon directives mandate localized BMS sourcing, opening procurement quotas for qualified domestic designers. |
| Software-Defined Vehicle Platform Integration | Hardware root-of-trust MCUs in gateway modules capture over-the-air update attach-rate opportunities. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, foundry capacity planners, and aftermarket distributors converged on the working assumptions underlying demand projections. Primary fieldwork across Stuttgart, Nagoya, and Detroit-Warren corridors combined with secondary validation against vehicle production databases, IHS Markit registration data, SEC semiconductor filings, and customs wafer import records. Bottom-up unit demand from powertrain and ADAS domain controllers triangulated against top-down foundry capacity allocation estimates.
Demand-supply balance modeling across the analysis window segmented by bit-width architecture, vehicle propulsion type, functional safety rating, and regional production cluster. CAGRs derived from regression against historical automotive electronics content per vehicle trajectories, with electrification intensity and software-defined vehicle penetration as primary forecast inputs. Zonal controller consolidation rates and silicon carbide inverter adoption curves shaped powertrain MCU volume assumptions.
Sensitivities concentrate around foundry node allocation shifts between consumer and automotive qualifications, copper and gold bond wire commodity volatility, and legacy 8-bit firmware migration timelines. Forecasts reflect documented assumptions on electrification penetration and functional safety mandate enforcement. Quarterly review of AEC-Q100 Grade 0 qualification backlogs and RISC-V design win announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Indonesia Data Center Processor Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Microserver Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
Micro Server IC Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
Processor for Smartphones Market