
 Edge Artificial Intelligence Chips Market | 2026-2036
Edge Artificial Intelligence Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Artificial Intelligence Chips Market Intelligence
On-device neural network inference is reconfiguring how intelligent systems process sensor data without cloud dependency. NVIDIA leverages its CUDA software ecosystem to sustain developer loyalty across autonomous machine platforms. Qualcomm anchors premium smartphone AI acceleration with its Hexagon DSP architecture. NXP Semiconductors specializes in automotive-grade edge processors that meet ASIL-D functional safety requirements.
Edge artificial intelligence chips are semiconductor devices designed to execute machine learning inference workloads locally, typically operating within power envelopes from milliwatts to tens of watts and integrating dedicated matrix multiply accelerators alongside general-purpose cores. Their primary purpose is to reduce latency, preserve data privacy, and minimize bandwidth costs for real-time decision-making in distributed environments. ASIC architectures dominate inference throughput per watt in production deployments, while FPGA platforms serve prototyping and low-volume customization where algorithm flexibility outweighs unit economics. GPU segments retain strength in training-to-edge transfer scenarios and high-performance edge servers. The fastest structural expansion sits at the intersection of embedded deployment and robotics applications, where deterministic response requirements favor dedicated neural processing units over general-purpose alternatives.
The EU AI Act, FDA software-as-medical-device guidance, and China's GB standards for intelligent vehicle data security collectively shape product certification pathways and geographic market access conditions for chip vendors. REACH substance restrictions and RoHS compliance add material composition constraints to foundry selection and packaging decisions. Stakeholders must monitor how divergent national AI governance frameworks fragment qualification requirements and force region-specific silicon variants.
Market Dynamics
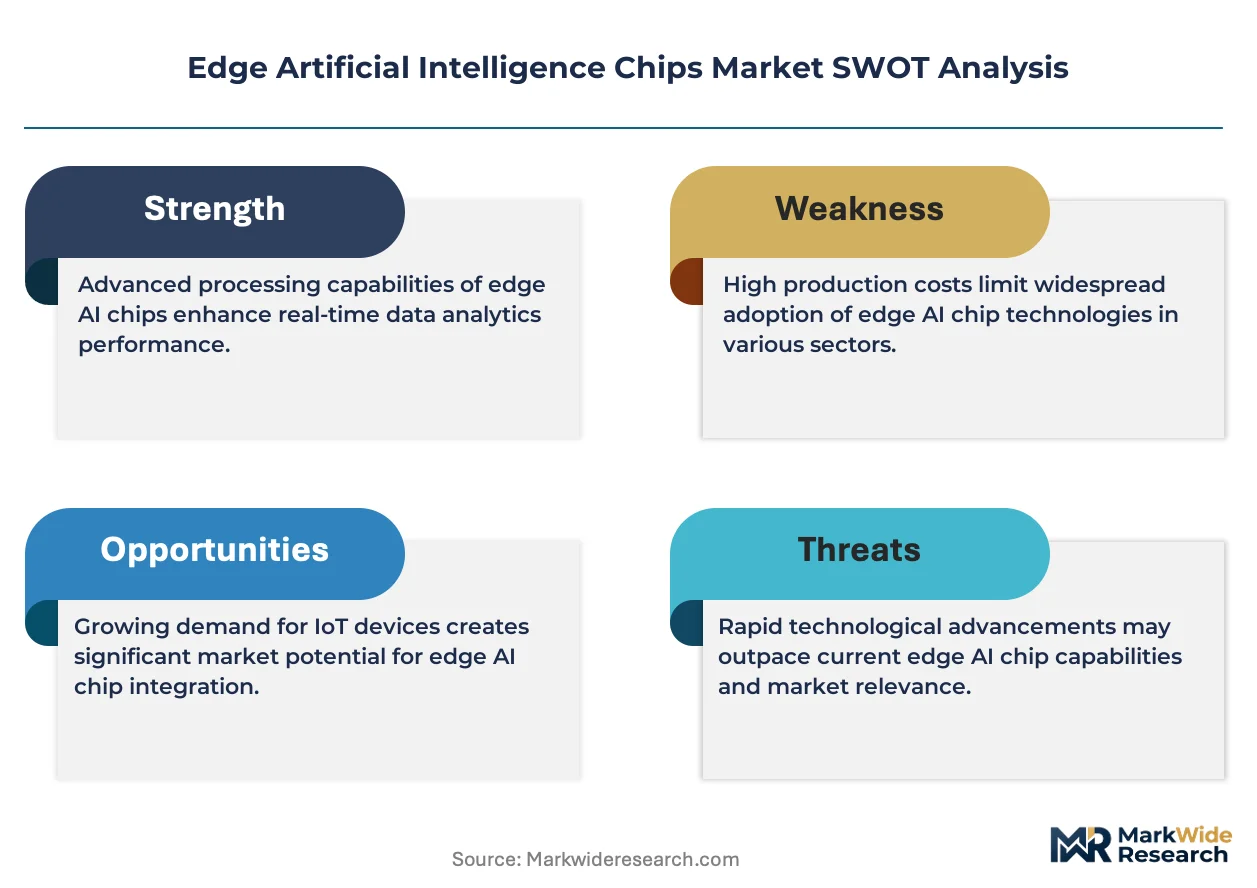
On-device inference is compressing cloud dependency for real-time sensor processing, forcing chip architectures toward dedicated neural accelerators with deterministic latency envelopes. This structural shift reconfigures power-performance tradeoffs across automotive, industrial, and consumer deployments.
Growth Catalysts
- EU AI Act risk classification:Embedded system deployers face mandatory conformity assessments for high-risk applications, accelerating demand for pre-certified silicon platforms that streamline product approval timelines.
- Automotive functional safety mandates:ASIL-D requirements for autonomous navigation systems are pulling automotive-grade edge processors into volume production with fault-tolerant architectures.
- China's dual carbon infrastructure:MIIT localization directives are concentrating demand for domestically manufactured edge computing nodes in smart grid and industrial automation deployments.
Market Restraints
- Advanced node foundry concentration:Sub-7nm production for high-performance AI accelerators depends on TSMC and Samsung capacity allocation, creating supply vulnerability for fabless chip vendors.
- REACH substance restrictions:ECHA limitations on lead-free solder alternatives and flame retardants constrain packaging material selection, elevating qualification costs for European-bound shipments.
- Algorithm-hardware coupling:Transformer architecture evolution outpaces fixed-function ASIC design cycles, creating obsolescence risk for inference engines optimized to prior-generation neural networks.
Strategic Opportunities
- India PLI scheme for electronics:Domestic manufacturing incentives for semiconductor assembly and testing are attracting edge chip packaging investments to serve South Asian IoT demand.
- Industrial robotics sensor fusion:Multi-modal perception requirements in warehouse automation and precision agriculture are opening volume markets for sub-5W heterogeneous compute platforms.
- FDA software-as-medical-device pathway:Streamlined premarket review for AI-enabled diagnostic edge devices is reducing regulatory friction for healthcare chip deployers targeting clinical settings.
Industry Challenges
- Neural compiler toolchain fragmentation:Proprietary SDKs from silicon vendors force developers to maintain parallel optimization pipelines, inflating firmware engineering headcount.
- Functional safety certification timelines:ASIL-D and SIL-3 qualification cycles for automotive and industrial processors extend 18-24 months, compressing product revenue windows against algorithm obsolescence.
- Heterogeneous integration yield:Chiplets combining logic, memory, and analog interfaces in 2.5D packages face thermal-mechanical stress failures, elevating test and burn-in costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Artificial Intelligence Chips Market |
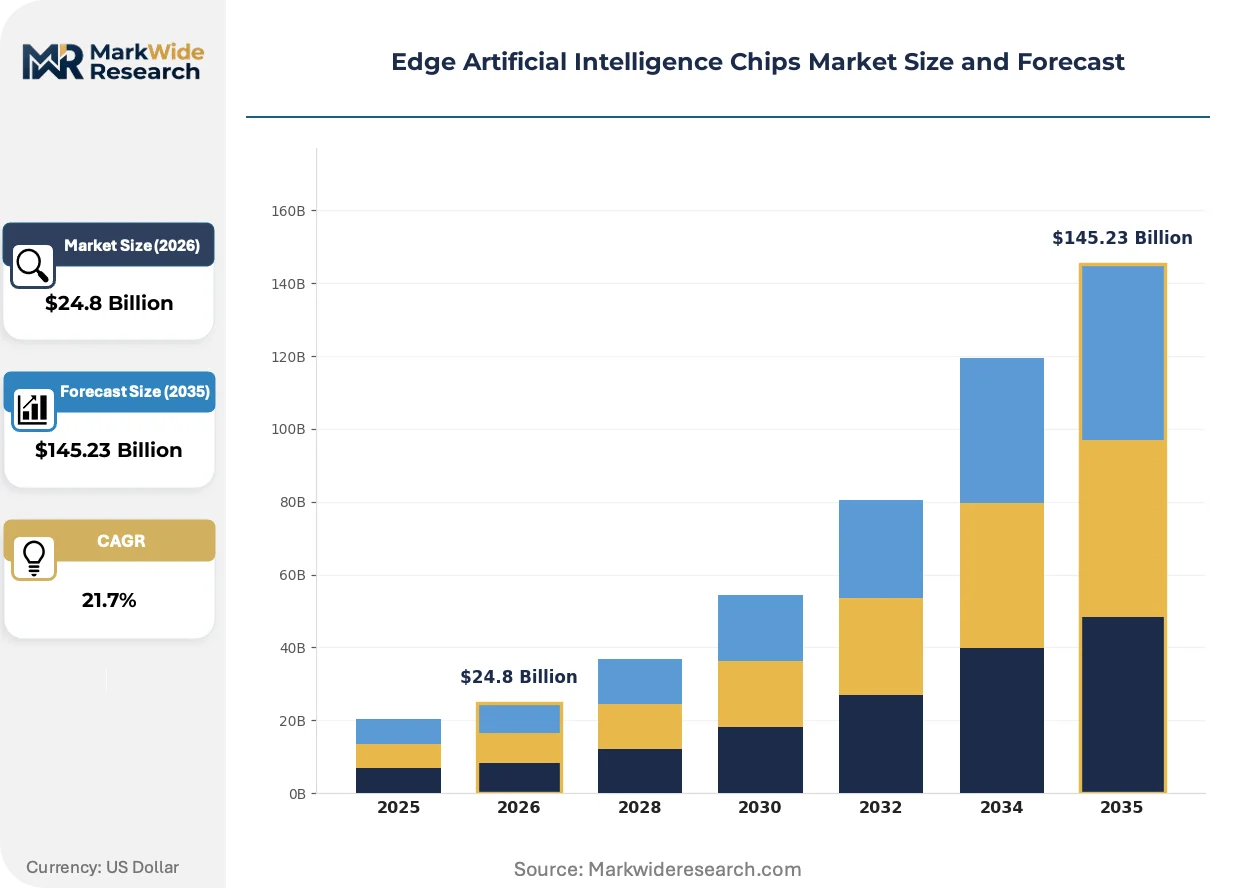
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $145.23 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ASIC, FPGA, CPU, GPU Application: Smart Cameras, Robotics, IoT Devices, Edge Servers End User: Healthcare, Automotive, Retail, Manufacturing Deployment: On-Premises, Cloud, Hybrid, Embedded |
| Companies Covered | MediaTek, NXP Semiconductors, NVIDIA, Lattice Semiconductor, STMicroelectronics, Arm Holdings, Ambarella, Synaptics, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Artificial Intelligence Chips Market Strategic Shifts & Innovations
Neural network quantization and in-memory computing architectures are restructuring how edge devices execute inference workloads within milliwatt power envelopes. These advances are compressing the latency gap between cloud and on-device processing.
Compute-in-memory arrays using analog MAC operations are digitizing sensor data processing at the array periphery, eliminating von Neumann bottlenecks for voice and vibration classification. Automotive tier-1 suppliers are sampling these architectures for cabin monitoring and predictive maintenance. The technology is digitizing edge inference economics by collapsing external DRAM requirements and reducing board-level component counts.
EU AI Act conformity assessment procedures are mandating technical documentation and risk management systems for embedded AI deployers. Chip vendors must now supply traceability data for training dataset provenance and model performance metrics. Automotive and medical device segments are responding by pre-integrating certification documentation into SDKs to accelerate customer product approvals.
Industrial buyers are consolidating vendor relationships around platforms offering decade-long supply assurance and binary-compatible upgrade paths. Distributors are displacing spot-market procurement with long-term allocation agreements and bonded inventory programs. This concentration is most visible in German and Japanese automation markets, where facility certification cycles create switching costs that favor incumbent silicon relationships.
Edge Artificial Intelligence Chips Market Segmentation
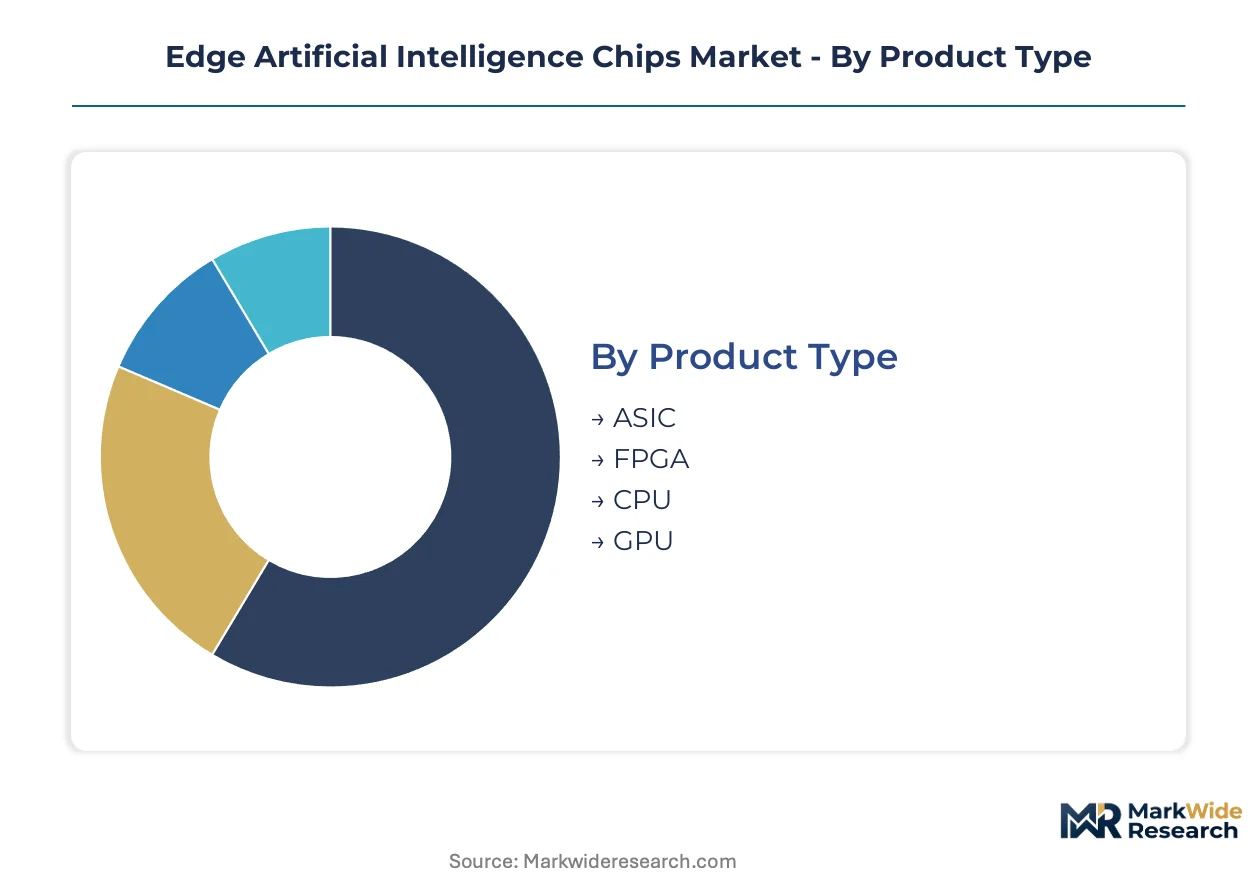
Edge AI chip architectures fragment across power envelopes, latency requirements, and certification burdens that reshape procurement criteria. Understanding these divisions reveals where margin pools concentrate and which technology transitions command engineering investment.
Product Type:
After-sales support intensity varies sharply by product type, with ASIC and FPGA deployments demanding sustained firmware optimization services while CPU and GPU segments rely more heavily on standardized SDK maintenance.
- ASIC:Application-specific integrated circuits integrate fixed-function matrix multiply accelerators with sub-watt to 50W power envelopes. German automotive tier-1 suppliers source ASIC-based cabin monitoring processors to meet KBA functional safety timelines. Demand concentrates in autonomous navigation systems where deterministic latency and ASIL-D certification requirements favor custom silicon over programmable alternatives.
- FPGA:Field-programmable gate arrays enable post-deployment algorithm reconfiguration through reconfigurable logic blocks and DSP slices. Japanese industrial automation vendors deploy FPGA-based sensor fusion platforms for warehouse robotics where neural network architectures evolve faster than ASIC design cycles permit.
- CPU:General-purpose processors with integrated AI acceleration extensions serve low-complexity inference workloads in smart home and consumer electronics.
- GPU:Parallel processing architectures retain deployment in edge server clusters requiring training-to-inference pipeline continuity.
ASIC holds the largest share; momentum sits with FPGA as algorithm volatility outpaces fixed-function design cycles.
Application:
Cost tier differentiation separates premium robotics deployments from mass-volume IoT endpoints, with smart cameras and edge servers occupying intermediate price-performance positions.
- Smart Cameras:Vision processors with integrated neural accelerators execute real-time object detection and facial recognition at 1080p to 4K resolutions. China's GB standards for intelligent vehicle data security are accelerating domestic procurement of smart camera modules for traffic monitoring and public safety infrastructure.
- Robotics:Heterogeneous compute platforms combine dedicated NPU, DSP, and real-time cores for multi-modal sensor fusion. FDA software-as-medical-device guidance is streamlining premarket pathways for surgical robotics edge processors in US hospital systems.
- IoT Devices:Milliwatt-class inference engines enable voice activation and anomaly detection in battery-constrained endpoints.
- Edge Servers:High-throughput accelerators serve 10-100W thermal envelopes for localized model serving and federated learning aggregation.
Smart Cameras holds the largest share; Robotics is gaining share fastest as warehouse automation and precision agriculture expand deployment volumes.
End User:
Customer type fragmentation reflects divergent certification timelines, with automotive and healthcare segments imposing 18-24 month qualification cycles that contrast with retail's rapid procurement velocity.
- Healthcare:Clinical-grade edge processors must satisfy FDA premarket notification requirements and IEC 62304 software lifecycle standards. Diagnostic imaging equipment manufacturers source ASIC-based inference engines for pathology slide analysis and radiological screening workflows.
- Automotive:ASIL-D functional safety mandates from ISO 26262 drive fault-tolerant architectures with lockstep cores and ECC memory. NHTSA autonomous vehicle guidance and EU AI Act risk classifications are tightening documentation requirements for training dataset provenance.
- Retail:Inventory management and checkout automation systems prioritize cost-optimized inference over extended temperature ranges.
- Manufacturing:Predictive maintenance and quality inspection platforms demand deterministic response times in noisy electromagnetic environments.
Automotive holds the largest share; Healthcare is expanding most quickly as FDA pathway streamlining reduces regulatory friction for diagnostic edge devices.
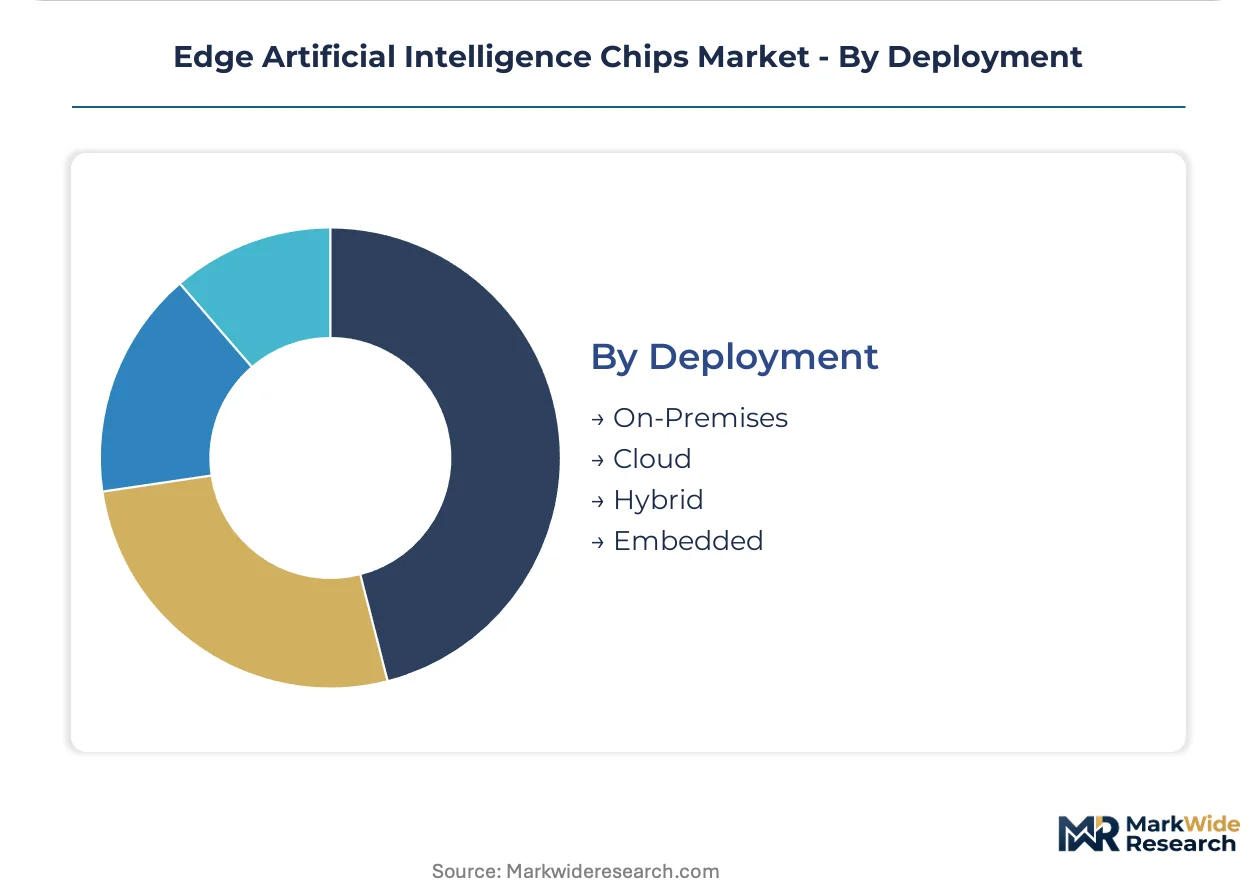
Deployment:
Supply concentration varies by deployment mode, with embedded and hybrid configurations requiring heterogeneous integration capabilities that concentrate qualified vendor relationships.
- On-Premises:Enterprise edge clusters deploy within facility data centers to preserve data sovereignty and minimize cloud egress costs. Financial services institutions in Frankfurt and Singapore source on-premises inference servers to satisfy national data localization requirements.
- Embedded:Deeply integrated silicon operates without host processor dependency in resource-constrained devices. REACH substance restrictions and RoHS compliance are constraining packaging material selection for European-bound embedded shipments.
- Cloud:Edge-cloud orchestration extends centralized model management to distributed inference endpoints.
- Hybrid:Split computation architectures distribute workloads between local preprocessing and cloud aggregation based on latency sensitivity.
Embedded holds the largest share; Hybrid is climbing the fastest as workload orchestration tools mature and latency optimization becomes programmable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and industrial automation buyers cluster demand in jurisdictions with functional safety mandates and localized manufacturing incentives. Procurement patterns track regulatory enforcement intensity across certification-heavy end-use segments.
China
MIIT dual carbon directives concentrate edge computing infrastructure investment in smart grid and industrial automation. GB standards for intelligent vehicle data security mandate localized processing architectures for automotive deployments. Yangtze River Delta fabrication clusters supply domestically manufactured inference accelerators to BYD and NIO autonomous navigation programs.
United States
FDA software-as-medical-device guidance streamlines premarket pathways for diagnostic imaging edge processors. NHTSA autonomous vehicle oversight tightens documentation requirements for training dataset provenance. Austin and San Diego design centers develop ASIL-D certified silicon for Tesla and Waymo production volumes.
Germany
KBA functional safety timelines accelerate procurement of pre-certified automotive-grade edge processors. EU AI Act risk classifications mandate conformity assessments for embedded systems in high-risk applications. Stuttgart and Munich automotive clusters source fault-tolerant inference engines from NXP and Infineon for Mercedes-Benz and BMW production lines.
Japan
METI industrial digitization programs fund warehouse robotics sensor fusion platforms requiring deterministic latency envelopes. JIS standards govern quality inspection system certification for manufacturing edge deployments. Nagoya and Osaka automation clusters deploy heterogeneous compute platforms for Fanuc and Yaskawa precision robotics.
India
PLI scheme incentives for electronics manufacturing attract edge chip packaging investments to serve South Asian IoT demand. BIS certification requirements constrain material selection for European-bound embedded shipments. Bangalore and Hyderabad design centers develop sub-5W inference engines for domestic smart camera and agricultural drone programs.
Edge Artificial Intelligence Chips Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent certification timelines and power envelope requirements. The vendor base stratifies between scale-driven platform vendors and safety-critical specialists serving automotive and medical segments. Two archetypes dominate: CUDA-ecosystem anchors sustaining developer loyalty, and ASIL-D certified suppliers capturing automotive qualification cycles. Competitive moves concentrate on strategic partnerships for heterogeneous integration and geographic expansion into India PLI-subsidized packaging facilities.
Within the automotive-grade specialist tier, NXP Semiconductors and STMicroelectronics exemplify functional safety-focused suppliers. NVIDIA anchors the developer-ecosystem platform archetype. Qualcomm occupies a position bridging premium smartphone acceleration with automotive extension strategies.
| Leading Market Players |
|---|
| MediaTek |
| NXP Semiconductors |
| NVIDIA |
| Lattice Semiconductor |
| STMicroelectronics |
| Arm Holdings |
| Ambarella |
| Synaptics |
| Qualcomm |
| Others |
Cost & Logistics Intelligence
TSMC's sub-7nm foundry undercapacity drives automotive-grade edge AI chip vendors toward long-term wafer supply agreements, compressing margin flexibility while elevating spot-market premiums for fabless designers without captive capacity allocation.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate high-volume automotive procurement, with ASIL-D certified processors commanding premium-mid-economy pricing differentiation based on fault-tolerant architecture complexity and decade-long supply assurance terms. Price differentiation centers on functional safety certification tier and heterogeneous integration yield, with industrial robotics buyers exhibiting highest sensitivity to unit economics and medical device OEMs least sensitive due to reimbursement-insulated procurement. Cost compression in consumer IoT tiers is intensifying as MediaTek and Qualcomm extend smartphone-derived silicon into adjacent edge applications.
Supply Chain Analysis
Contract manufacturing concentration rests with TSMC and Samsung Foundry for advanced logic, with ASE Technology and Amkor handling automotive-grade packaging and test. Raw material dependencies draw from Taiwan for silicon wafers, Japan for specialty chemicals and photoresists, and South Korea for HBM memory stacks. Single-source vulnerability in EUV lithography equipment creates supply chain risk for sub-5nm AI accelerator tape-outs. Distribution runs through Arrow Electronics and Avnet for design-in support, with direct OEM relationships displacing distributor dependency in volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and Japanese automotive OEMs consolidating vendor relationships around pre-certified silicon platforms, fragmenting pricing leverage for second-tier chip vendors without ASIL-D qualification heritage.
For Market Incumbents: Insulate automotive revenue streams by deepening backward integration into heterogeneous packaging capabilities and accelerating FDA software-as-medical-device pathway investments before algorithm-hardware coupling obsolescence threatens fixed-function ASIC margins. Lockstep core architectures and ECC memory subsystems represent defensible moats against FPGA-based reconfigurable alternatives in safety-critical deployments. For New Entrants and Emerging Players: India's PLI-subsidized assembly and test capacity offers white-space entry for sub-5W inference engines targeting agricultural drone and smart camera programs with BIS certification as the regulatory gateway. Warehouse robotics sensor fusion platforms present the most penetrable segment, with deterministic latency requirements favoring heterogeneous compute newcomers over established CPU-GPU incumbents. Go-to-market positioning through Bangalore design centers with domestic manufacturing narratives captures MIIT-influenced procurement preferences. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ASIL-D certified suppliers with decade-long supply agreements and binary-compatible upgrade paths, positioning functional safety specialists for durable cash flow quality across the analysis window. Target acquisition archetypes include industrial automation-focused FPGA platforms with JIS certification heritage and FDA pathway experience in surgical robotics edge processors. Monitor EU AI Act conformity assessment timeline acceleration as inflection signal for pre-certified silicon premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Heterogeneous Integration Partnership | Combines logic, memory, and analog chiplets to collapse board-level component counts for robotics OEMs. |
| ASIL-D Certification Pre-Integration | Embeds ISO 26262 documentation into SDKs to compress KBA customer approval timelines for German automotive. |
| India PLI Packaging Investment | Captures bonded inventory programs serving South Asian IoT demand with BIS-compliant material selection. |
| FDA SaMD Pathway Acceleration | Streamlines premarket review for diagnostic imaging edge processors in US hospital procurement cycles. |
| Compute-in-Memory Architecture Sampling | Eliminates external DRAM requirements for voice and vibration classification in cabin monitoring applications. |
Research Approach
Desk research of SEC semiconductor filings, foundry capacity disclosure reports, and EU AI Act technical documentation preceded structured interviews with automotive platform engineering directors, industrial automation procurement leads, and edge AI chip product managers. Primary fieldwork combined with secondary validation against TSMC and Samsung Foundry capex announcements, MIIT dual carbon policy releases, and FDA software-as-medical-device guidance updates. Bottom-up unit shipment estimates across smart camera, robotics, and IoT device segments were triangulated with top-down semiconductor revenue aggregation.
Assumptions held fixed include EU AI Act enforcement timelines and REACH substance restriction scope, while variables encompassed TSMC advanced node allocation priority shifts and transformer architecture evolution velocity. The analytical framework modeled product type, application, end user, and deployment mode segmentation across the projection horizon, with CAGRs derived from regression against historical smartphone AI accelerator penetration curves and automotive ADAS content-per-vehicle trajectories. Neural compiler toolchain maturity and heterogeneous integration yield rates served as industry-specific forecast sensitivity inputs.
Practitioners should monitor TSMC CoWoS capacity expansion announcements and EU AI Act delegated act publication schedules for early signals of supply constraint easing or compliance burden escalation. Forecasts reflect these assumptions with acknowledged sensitivity to foundry geopolitical risk and algorithm-hardware obsolescence acceleration. Quarterly review of automotive OEM vendor consolidation announcements and FDA SaMD premarket submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Thailand Data Center Processor Market