
 United Arab Emirates Data Center Processor Market | 2026-2036
United Arab Emirates Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Data Center Processor Market Insights
Silicon photonics is decoupling data center processor performance from traditional copper interconnect limits. NVIDIA Corporation leverages its CUDA ecosystem to anchor AI training deployments across UAE hyperscale facilities. AMD competes on core density and power efficiency for cloud virtualization workloads. Intel Corporation sustains manufacturing scale through its foundry relationships with regional system integrators.
Data center processors are integrated circuits engineered to execute compute workloads within centralized server environments, typically fabricated on advanced nodes with thermal design power ratings exceeding 200 watts for high-performance variants. These devices orchestrate virtualization, inference, and analytics tasks across rack-scale infrastructure. GPU segments command premium positioning as generative AI training expands across UAE cloud regions. CPU deployments retain volume leadership in enterprise colocation and legacy workload migration. ASIC adoption is accelerating among telecommunications operators building 5G core networks.
MOHAP and the UAE's Telecommunications and Digital Government Regulatory Authority shape processor certification requirements for healthcare and critical infrastructure deployments. BIS-equivalent conformity assessments and the country's data localization mandates restrict uncertified hardware from government cloud procurement. Stakeholders must weigh sovereign compute requirements against supply chain lead times for advanced node silicon.
Market Dynamics
Silicon photonics is decoupling processor performance from copper interconnect thermal limits across UAE hyperscale clusters. This shift compresses rack-scale latency while amplifying power density requirements for AI training infrastructure.
Growth Catalysts
- UAE National AI Strategy 2031:Government-backed sovereign compute mandates require localized AI training clusters, directly expanding GPU procurement from hyperscale operators.
- Data Localization Frameworks:MOHAP and TDRA certification requirements for healthcare and critical infrastructure cloud deployments restrict uncertified hardware, favoring compliant domestic procurement.
- Silicon Photonics Integration:Optical I/O architectures are replacing electrical interconnects in Dubai and Abu Dhabi facilities, enabling higher-bandwidth processor clustering without thermal penalties.
Market Restraints
- Advanced Node Supply Concentration:Sub-5nm fabrication capacity concentrates among three global foundries, exposing UAE deployments to 18-24 month lead time volatility.
- Thermal Design Power Escalation:AI training GPUs now exceed 700W TDP, requiring liquid cooling retrofits that add 40-60% infrastructure capex to existing air-cooled facilities.
- BIS-Equivalent Export Controls:Dual-use technology classification for high-performance AI accelerators creates licensing friction for certain processor categories entering UAE cloud regions.
Strategic Opportunities
- Abu Dhabi Industrial City Expansion:Greenfield data center zones offer captive renewable power for high-density AI clusters, attracting processor vendors seeking carbon-neutral deployment credentials.
- 5G Core Network ASIC Demand:Telecommunications operators are replacing general-purpose CPUs with custom silicon for packet processing, opening specialized procurement channels.
- MOHAP Healthcare Cloud Mandate:Patient data sovereignty requirements are forcing hospital systems to migrate from offshore clouds to certified domestic facilities, expanding enterprise CPU volumes.
Industry Challenges
- Liquid Cooling Infrastructure Gap:Regional mechanical contractors lack experience with direct-to-chip cooling loops, delaying high-TDP processor deployments in legacy facilities.
- Multi-Vendor Orchestration Complexity:Hyperscalers integrating NVIDIA, AMD, and Intel silicon within unified clusters face CUDA-ROCm-oneAPI software fragmentation that increases operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Data Center Processor Market |
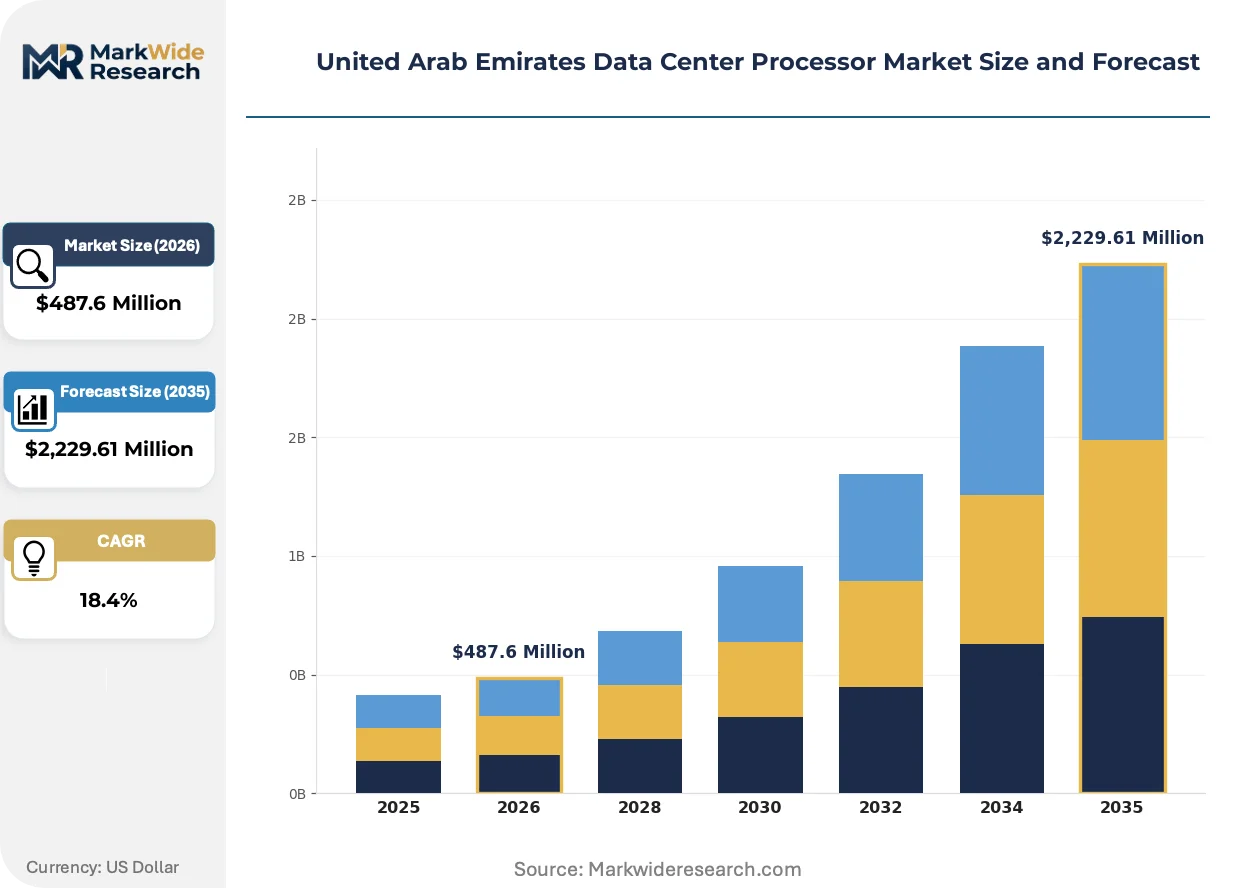
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPU, GPU, FPGA, ASIC Application: Cloud Computing, AI/ML, Big Data Analytics, Virtualization End User: Telecommunications, BFSI, Healthcare, Government Deployment Model: On-Premises, Hybrid, Multi-Cloud, Colocation |
| Companies Covered | Advanced Micro Devices Inc, NVIDIA Corporation, Intel Corporation, Broadcom Inc, IBM, Huawei Technologies, ARM Holdings, Qualcomm, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Data Center Processor Market Trends and Innovations
Compute architectures are fragmenting along workload-specific lines as AI training demands diverge from traditional virtualization. This specialization is reshaping vendor competitive dynamics and procurement evaluation criteria across UAE facilities.
Silicon photonics is absorbing electrical interconnect bandwidth constraints in high-density AI clusters. Hyperscale operators in Dubai are deploying co-packaged optical I/O modules to extend processor-to-processor reach beyond copper distance limits. This convergence of photonics and advanced packaging is absorbing legacy retimer and redriver component markets while enabling disaggregated rack architectures.
MOHAP processor certification requirements for healthcare cloud deployments are hardening hardware security criteria. The framework mandates trusted execution environments and supply chain attestation that disqualify uncertified silicon from government procurement. Medical imaging and electronic health record workloads are most affected, with hospital IT departments extending hardware refresh cycles to await compliant processor availability.
Hyperscale procurement is consolidating around direct-foundry relationships that bypass traditional distributor channels. Etisalat and du are negotiating wafer-level commitments with advanced node manufacturers, compressing margin capture for regional system integrators. This disintermediation is most visible in Abu Dhabi, where sovereign wealth-backed cloud ventures are building captive silicon supply agreements.
United Arab Emirates Data Center Processor Market Segmentation
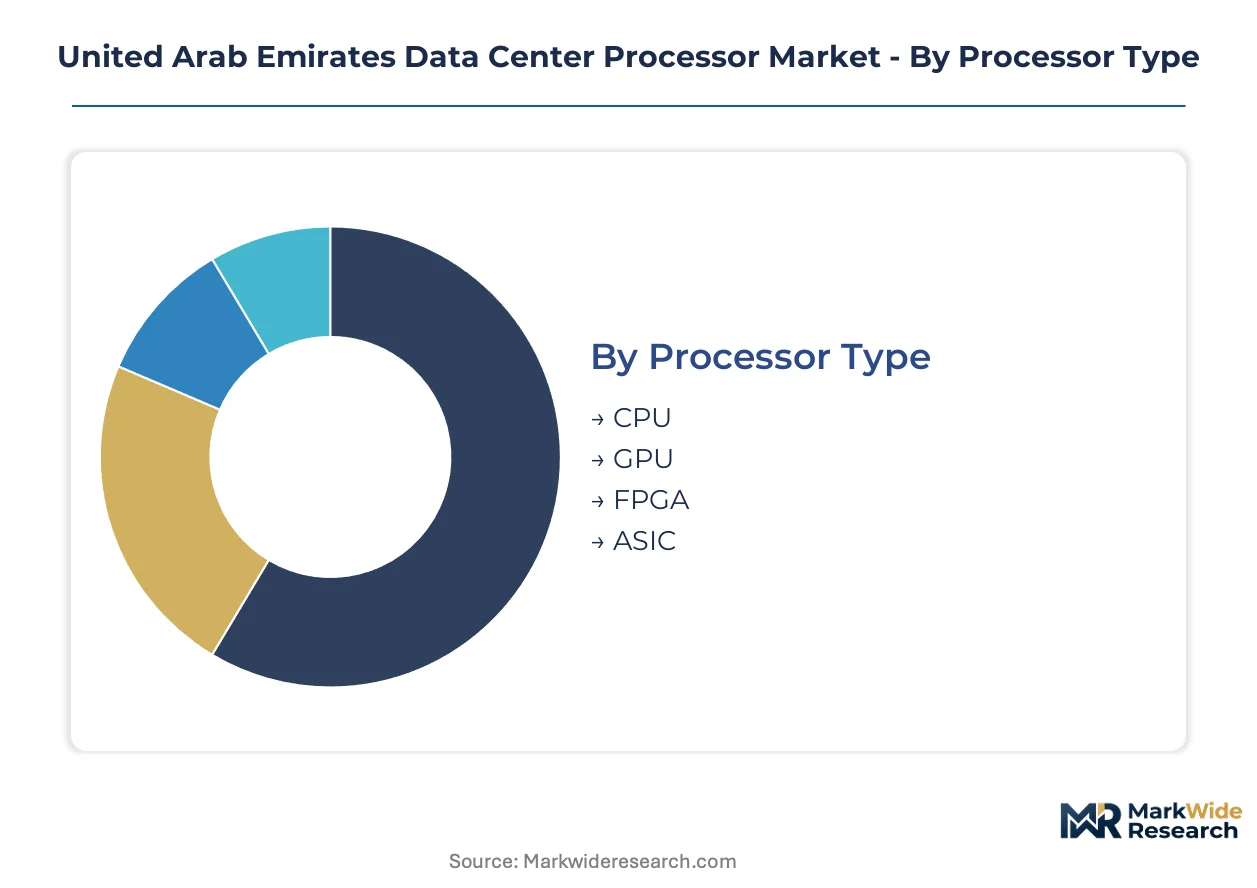
Processor segmentation in the UAE reflects divergent compute requirements across sovereign AI mandates, healthcare data localization, and hyperscale cloud expansion. Procurement patterns differ sharply between government-backed training clusters and enterprise virtualization workloads.
Processor Type:
Buyers differentiate primarily by thermal design power tolerance and software ecosystem lock-in rather than raw compute metrics alone.
- CPU:General-purpose processors fabricated on 5nm-7nm nodes handle virtualization and legacy enterprise workloads. Abu Dhabi government cloud facilities favor x86 architectures for their extensive software compatibility and established supply chain relationships with regional system integrators.
- GPU:Massively parallel architectures with HBM memory stacks now exceed 700W thermal envelopes. Dubai-based hyperscalers deploy these for sovereign AI training clusters mandated under the UAE National AI Strategy, driving concentrated procurement from cloud service providers with direct foundry relationships.
- FPGA:Reconfigurable logic devices offer deterministic latency for financial trading and 5G baseband processing. Etisalat utilizes these for packet acceleration in core network infrastructure where workload flexibility outweighs unit economics.
- ASIC:Application-specific silicon delivers optimal power efficiency for fixed-function workloads. du and other telecommunications operators commission custom designs for 5G core user plane functions, displacing general-purpose processors in high-throughput network segments.
CPU leads volumes today; GPU is gaining share fastest.
Application:
Workload characteristics dictate cooling infrastructure investment and procurement channel selection across UAE facilities.
- Cloud Computing:Multi-tenant virtualization platforms require processors with robust memory bandwidth and hardware-assisted isolation. Colocation providers in Dubai Internet City prioritize SKUs certified for MOHAP and TDRA compliance frameworks.
- AI/ML:Training and inference pipelines demand tensor-optimized architectures with high-bandwidth interconnects. Abu Dhabi sovereign wealth-backed ventures anchor procurement here, building captive clusters for Arabic large language model development.
- Big Data Analytics:Scale-out database and streaming platforms favor high core-count processors with balanced compute-to-memory ratios. BFSI institutions deploy these for real-time risk modeling under central bank data residency requirements.
- Virtualization:Server consolidation and legacy workload migration sustain steady CPU demand. Healthcare providers migrating from offshore clouds to MOHAP-certified domestic facilities drive refresh cycles in this segment.
Cloud Computing anchors procurement volumes; AI/ML shows steepest expansion trajectory.
End User:
Regulatory compliance thresholds and data sovereignty requirements fragment procurement authority across buyer categories.
- Telecommunications:Etisalat and du operate under TDRA network equipment certification regimes. These operators blend FPGA acceleration with ASIC offload for 5G core infrastructure, prioritizing supply chain security over cost optimization.
- BFSI:Banks and insurers face UAE Central Bank data localization mandates. Their processor procurement emphasizes hardware security modules and trusted execution environments for payment processing workloads.
- Healthcare:MOHAP cloud certification requirements restrict eligible silicon to attested supply chains. Hospital systems extending hardware refresh cycles await compliant processor availability for medical imaging and electronic health record platforms.
- Government:Federal and emirate-level entities drive sovereign compute initiatives. Abu Dhabi and Dubai government clouds specify processors meeting national security criteria for AI training and classified workload processing.
Government procurement commands premium positioning; Healthcare is expanding most quickly as offshore migration accelerates.
Deployment Model:
Infrastructure ownership structure determines processor lifecycle management and thermal design investment horizons.
- On-Premises:Captive facilities owned by large enterprises and government entities. BFSI headquarters in Dubai maintain these for core banking systems requiring direct hardware control.
- Hybrid:Workload portability between private infrastructure and public cloud. Healthcare groups utilize this model during phased migration to MOHAP-certified domestic facilities.
- Multi-Cloud:Distributing workloads across independent cloud service providers. Government entities adopt this for resilience, though data sovereignty requirements constrain provider selection to UAE-based operators.
- Colocation:Leased space in carrier-neutral facilities with shared power and cooling. Smaller BFSI and healthcare providers favor this for reduced capital exposure while meeting certification requirements.
Colocation dominates volume today; Hybrid deployments are climbing the fastest as regulated industries navigate cloud transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Internet City anchors processor procurement volumes across the Emirates, with hyperscale clusters driving concentrated GPU demand. Abu Dhabi sovereign wealth vehicles are commissioning dedicated AI training infrastructure. Sharjah and Northern Emirates facilities follow enterprise virtualization patterns.
Dubai
Dubai Internet City and Dubai Silicon Oasis host the Emirates' densest processor deployments. TDRA cloud certification requirements mandate hardware attestation for multi-tenant facilities. Colocation providers here are retrofitting liquid cooling infrastructure to accommodate 700W-class AI training accelerators.
Abu Dhabi
Abu Dhabi Industrial City greenfield zones attract carbon-neutral AI cluster investments backed by sovereign capital. The UAE National AI Strategy 2031 mandates localized training infrastructure for Arabic large language models. Masdar City adjacent facilities leverage captive solar generation to power high-density GPU deployments.
Sharjah
Sharjah Research Technology and Innovation Park supports mid-scale enterprise virtualization workloads. MOHAP healthcare cloud mandates are driving hospital system migrations from offshore providers to certified domestic facilities. Local system integrators here specialize in x86 server refreshes for regulated industries.
Northern Emirates
Ras Al Khaimah and Fujairah data center zones serve disaster recovery and latency-sensitive edge applications. Federal data sovereignty requirements restrict certain processor categories from government procurement. These facilities emphasize air-cooled CPU infrastructure over liquid-cooled AI training deployments.
United Arab Emirates Data Center Processor Market Competitive Landscape
Global majors compete with regional champions across certification compliance and direct-foundry access. The vendor base stratifies between CUDA-anchored AI accelerators, x86 virtualization stalwarts, and emerging ARM-based alternatives. Three archetypes dominate: ecosystem-locked incumbents, core-density challengers, and custom-silicon specialists. Competitive moves center on wafer-level supply agreements and sovereign cloud certification pre-qualification.
Within the ecosystem-locked tier, NVIDIA Corporation anchors AI training procurement through its CUDA software moat. Advanced Micro Devices Inc occupies a challenger position on core density and power efficiency metrics. Intel Corporation represents the manufacturing-scale archetype through foundry relationships with regional system integrators.
| Leading Market Players |
|---|
| Advanced Micro Devices Inc |
| NVIDIA Corporation |
| Intel Corporation |
| Broadcom Inc |
| IBM |
| Huawei Technologies |
| ARM Holdings |
| Qualcomm |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics integration across UAE hyperscale facilities is simultaneously compressing interconnect costs and concentrating procurement leverage among operators with direct-foundry relationships. This dual effect reshapes margin distribution between advanced packaging specialists and legacy copper-component suppliers while elevating liquid-cooled infrastructure premiums.
Pricing Analysis
Wafer-level foundry pricing pass-through dominates procurement economics for sub-5nm AI accelerators, with hyperscalers absorbing 40-60% infrastructure premiums for liquid cooling retrofits. Price differentiation separates TDRA-certified silicon from uncertified alternatives, with MOHAP healthcare mandates further stratifying tiers by supply chain attestation requirements. Cost compression in air-cooled CPU segments intensifies as regional system integrators compete for enterprise virtualization volumes. Government-backed sovereign compute clusters exhibit least price sensitivity; colocation providers serving regulated mid-market healthcare groups face acute margin pressure.
Supply Chain Analysis
Advanced node fabrication expertise concentrates in Taiwan, South Korea, and the United States, with workforce availability constraints in each geography limiting capacity expansion velocity. UAE processor procurement draws from HBM memory stacks, co-packaged optical I/O modules, and specialized substrate materials. Single-source vulnerability pervades sub-5nm logic and high-bandwidth memory segments. Distribution runs through direct-foundry agreements that disintermediate traditional regional system integrators, compressing their margin capture on advanced silicon categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
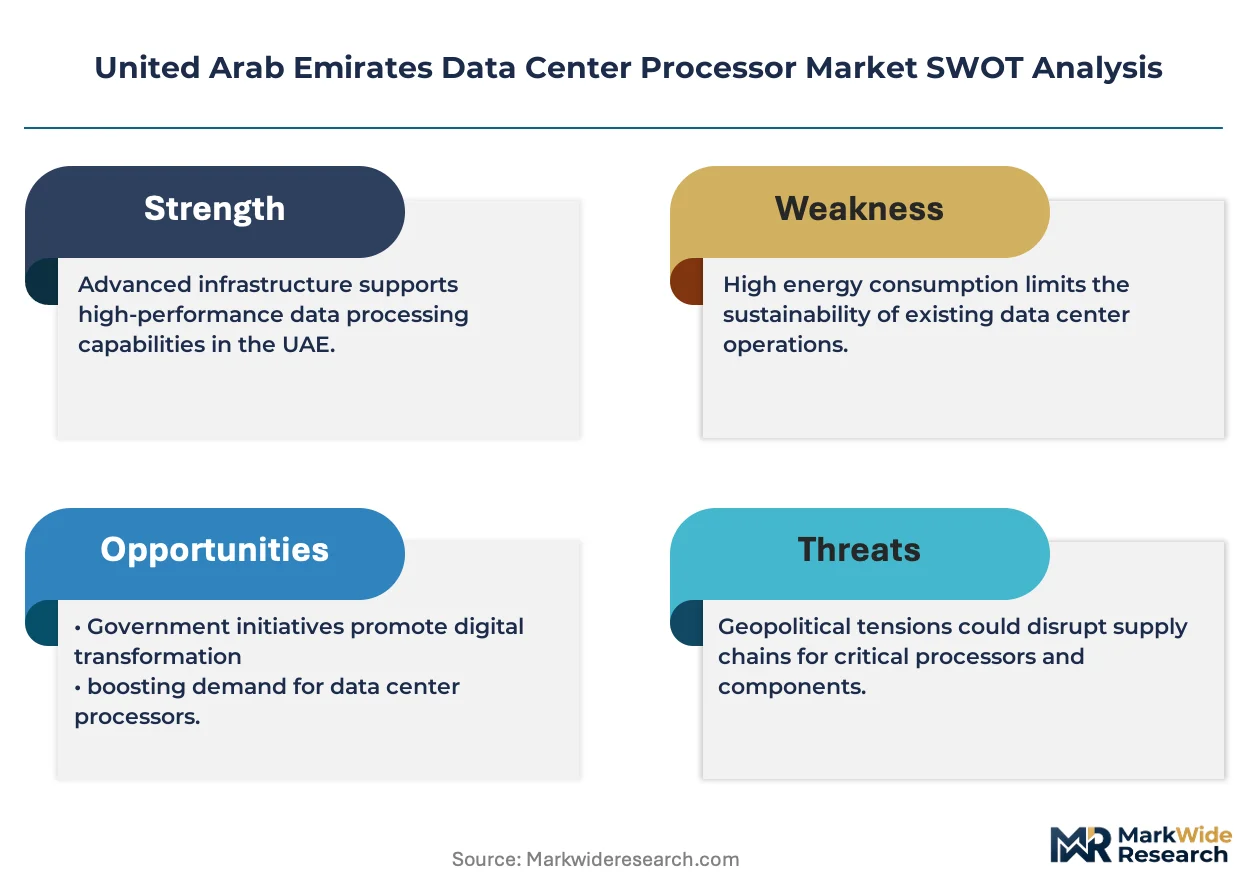
The UAE data center processor market functions as a regulatory compounder where MOHAP certification mandates and TDRA cloud frameworks continuously harden compliance thresholds, expanding addressable demand for attested silicon.
For Market Incumbents: Cement ecosystem lock-in through CUDA-ROCm cross-compatibility layers that reduce hyperscaler orchestration friction. Deepen captive supply agreements with advanced node foundries to defend against lead time volatility threatening sovereign AI deployment schedules. Prioritize liquid-cooling certification partnerships with Abu Dhabi Industrial City contractors to accelerate high-TDP cluster commissioning. For New Entrants and Emerging Players: Regional system integrators represent the most accessible channel partner type for penetrating MOHAP-certified healthcare cloud migrations. Target Sharjah and Northern Emirates colocation facilities serving hospital systems awaiting compliant processor availability. Position ARM-based alternatives against x86 virtualization stalwarts in enterprise refresh cycles where software compatibility requirements are less stringent than government cloud mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized liquid-cooling infrastructure providers lacking hyperscaler scale but holding regional mechanical contractor relationships. Long-term viability centers on carbon-neutral deployment credentials aligning with Abu Dhabi sovereign wealth sustainability criteria. Watch for BIS-equivalent export control expansion signals as inflection indicators for licensing friction in high-performance AI accelerator categories.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Foundry Supply Agreement | Etisalat and du are bypassing distributors to secure wafer-level commitments, compressing regional integrator margins. |
| MOHAP Certification Pre-Qualification | Hardware vendors attesting supply chains capture procurement preference in healthcare cloud migrations from offshore providers. |
| Liquid Cooling Infrastructure Partnership | Abu Dhabi Industrial City contractors with direct-to-chip experience are winning retrofit contracts for 700W-class GPU deployments. |
| Silicon Photonics Integration | Co-packaged optical I/O modules enable disaggregated rack architectures that absorb legacy retimer component markets. |
| Sovereign AI Cluster Development | Government-backed ventures in Dubai and Abu Dhabi are building captive training infrastructure for Arabic large language models. |
Research Methodology
Direct dialogue with hyperscale facility operators, regional system integrators, TDRA certification specialists, and MOHAP healthcare IT procurement managers grounded qualitative findings. Secondary validation drew from hyperscaler capex disclosures, foundry capacity announcements, UAE regulatory filings, and customs data on semiconductor imports. Bottom-up demand modeling across processor categories triangulated against top-down market sizing from supply-side fabrication capacity assessments.
Segmented outputs across processor type, application workload, end-user regulatory tier, and deployment ownership structure populated the analytical framework throughout the projection horizon. CAGRs derived from deployment velocity assumptions tied to sovereign AI mandate timelines and healthcare cloud migration schedules. Industry-specific inputs included liquid cooling infrastructure buildout rates and MOHAP certification queue processing times.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to advanced node capacity allocation shifts and BIS-equivalent control expansion. Forecasts reflect documented assumptions regarding sovereign compute procurement timelines and foundry yield trajectories. Material deviation in export licensing friction or regional liquid-cooling contractor capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Data Center Chip Market