
 Automotive Clutch Actuator Market | 2026-2036
Automotive Clutch Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Clutch Actuator Market Insights
Aftermarket service revenue is rewriting profit allocation across the clutch actuator value chain. ZF Friedrichshafen AG leverages its integrated transmission portfolio to capture recurring replacement demand. Schaeffler AG anchors its position through bearing and actuation system bundling. Robert Bosch GmbH competes on electromechanical module scale across multiple OEM platforms.
An automotive clutch actuator is an electromechanical or hydraulic device that engages and disengages the clutch plate through precise force transmission, typically operating at response times below 100 milliseconds and force outputs ranging from 500N to 2500N depending on vehicle class. Electric actuators now lead product type adoption as OEMs eliminate hydraulic fluid circuits to reduce maintenance and leak risk. Electromechanical systems within the technology dimension carry the fastest growth trajectory due to their compatibility with 48V mild-hybrid architectures. OEM end users command the dominant volume share, though aftermarket suppliers capture disproportionate margin pools in regions with aging vehicle fleets.
The EPA enforces Corporate Average Fuel Economy standards that push manufacturers toward clutch actuators enabling engine-off coasting and stop-start optimization. NHTSA safety protocols govern actuator failure-mode behavior to prevent unintended clutch engagement. China's MIIT administers dual carbon goals that accelerate electric actuator adoption in domestic transmission production. Stakeholders must monitor how software-defined vehicle architectures integrate clutch actuation into centralized drivetrain control domains.
Market Dynamics
Electric clutch actuation systems are displacing hydraulic architectures as OEMs eliminate fluid circuits to meet tightening EPA tailpipe standards and EU F-Gas Regulation requirements for transmission efficiency.
Growth Catalysts
- 48V Mild-Hybrid Compatibility:Electromechanical actuators integrate seamlessly with 48V architectures, enabling engine-off coasting and stop-start optimization that satisfies Corporate Average Fuel Economy mandates.
- China MIIT Dual Carbon Goals:Domestic transmission producers accelerate electric actuator adoption to align with national carbon neutrality targets and reduce manufacturing emissions intensity.
- Automated Manual Transmission Expansion:Passenger car OEMs in Germany and the United States densify production lines for AMT and dual-clutch systems, concentrating demand for precision actuation components.
Market Restraints
- Rare Earth Magnet Dependency:Electric actuator motors require neodymium and dysprosium supplies concentrated in Chinese processing facilities, exposing procurement to geopolitical volatility and export quota fluctuations.
- Hydraulic Legacy Infrastructure:Established service networks and technician training for hydraulic clutch systems create switching friction in aftermarket channels, delaying electromechanical penetration in aging vehicle fleets.
- NHTSA Failure-Mode Certification:Safety protocols governing unintended clutch engagement demand extensive validation cycles, extending time-to-market for new actuator designs and compressing development budgets.
Strategic Opportunities
- India PLI Scheme Alignment:Component suppliers can access production-linked incentives by establishing electromechanical actuator manufacturing for domestic OEMs and export markets.
- Software-Defined Vehicle Integration:Clutch actuation convergence with centralized drivetrain control domains creates white space for firmware-capable tier suppliers to capture value from hardware-software bundling.
- Aftermarket Service Unbundling:Independent repair chains in the United States and Germany seek direct sourcing relationships for replacement actuators, bypassing traditional OEM captive distribution.
Industry Challenges
- Embedded Systems Talent Scarcity:Actuator manufacturers compete for control software engineers capable of integrating real-time force feedback algorithms with vehicle network architectures.
- Legacy Powertrain Integration Complexity:Electromechanical systems must interface with existing transmission control modules designed for hydraulic pressure signals, requiring protocol translation layers that introduce latency.
- ISO 26262 Functional Safety Certification:ASIL-D compliance for clutch actuation demands fault-tolerant hardware designs and exhaustive failure mode analysis, stretching engineering resources across multiple OEM programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Clutch Actuator Market |
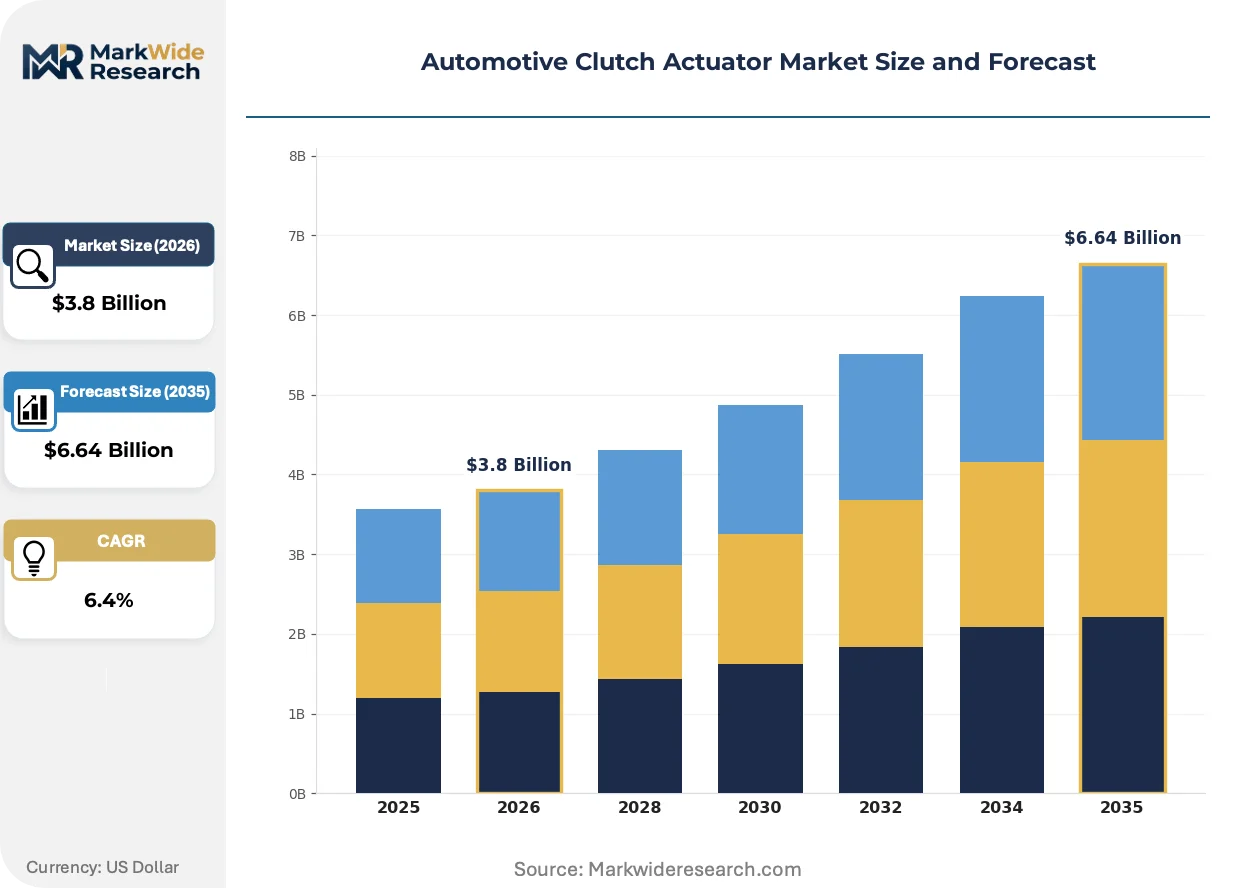
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Actuators, Electric Actuators, Pneumatic Actuators, Mechanical Actuators Technology: Sensor-Based Systems, Motor-Driven Solutions, Electromechanical Systems, Intelligent Control Modules End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Suppliers Size: Compact Systems, Standard Systems, Heavy-Duty Systems, Modular Systems |
| Companies Covered | ZF Friedrichshafen AG, Schaeffler AG, Robert Bosch GmbH, Continental AG, DENSO Corporation, Valeo SA, FTE Automotive Group, Magneti Marelli, WABCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Clutch Actuator Market Trends and Innovations
Actuator architectures are converging with broader drivetrain electrification, compressing development cycles and forcing suppliers to restructure around software competencies and systems integration capabilities.
Brushless DC motor technology with integrated position sensing is hybridizing clutch actuator designs, replacing separate sensor modules with magnetoresistive elements embedded in the motor housing. Tier-1 suppliers in Germany and Japan are adopting these consolidated packages for 2026 platform launches. The integration is hybridizing cost structures by eliminating wiring harness complexity while enabling closed-loop force control algorithms that were previously impractical.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in manufacturing processes, compelling actuator producers to retool sealing and lubrication systems for compatibility with fluorine-free alternatives. This transition compresses margin structures for mid-tier suppliers lacking capital for process revalidation. Dual-clutch transmission production lines in Germany and the Czech Republic are experiencing the most acute compliance pressure, with OEMs demanding material certifications that extend upstream to bearing and seal vendors.
Fleet operators and large leasing companies are consolidating actuator procurement through long-term service agreements that bundle replacement scheduling with predictive maintenance analytics. This channel compression displaces traditional aftermarket distributors in the United States and Western Europe. The shift is most visible among commercial vehicle fleets operating automated manual transmissions, where unplanned downtime costs exceed component price premiums by an order of magnitude.
Automotive Clutch Actuator Market Segmentation
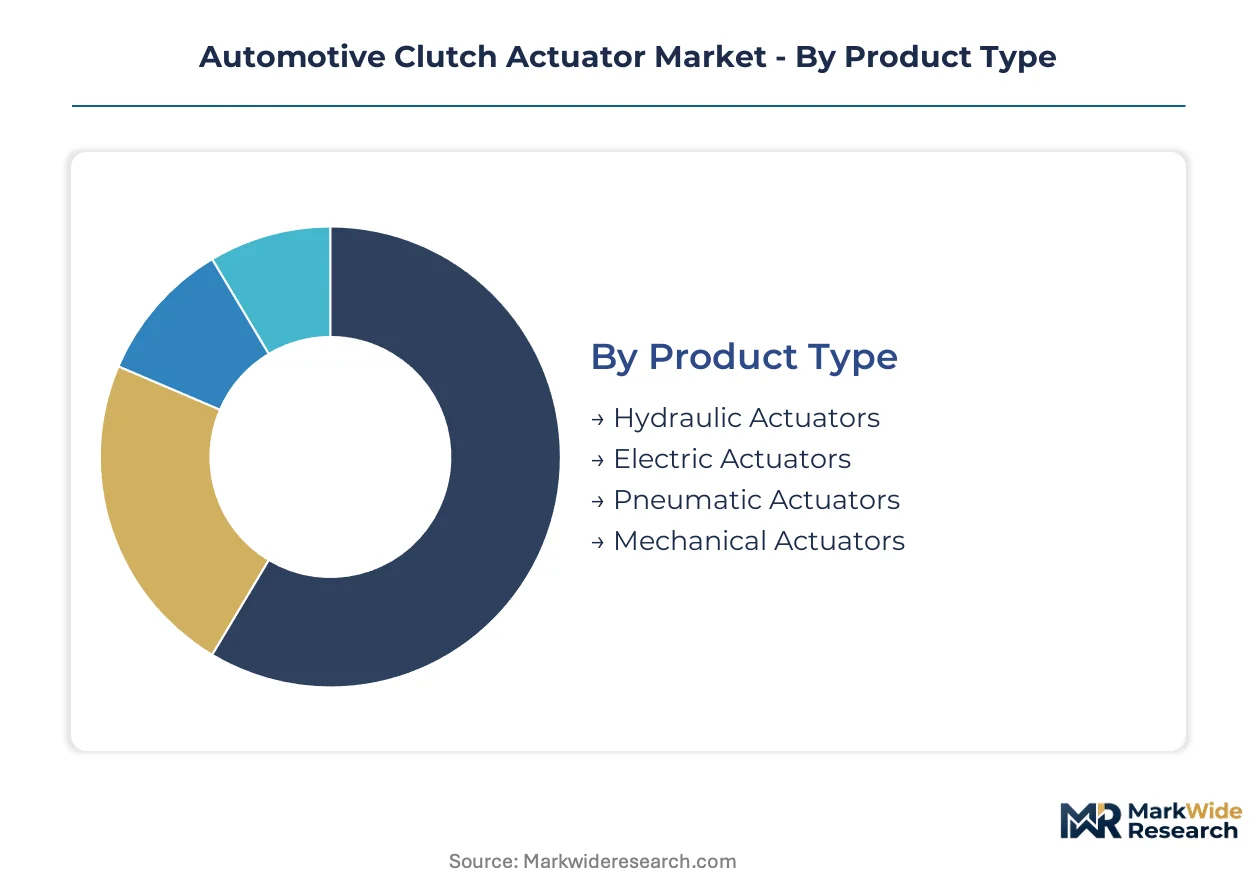
Segmentation in the automotive clutch actuator market reveals distinct service intensity profiles across product architectures. Aftermarket revenue concentration varies sharply by actuator type, with electromechanical systems generating replacement cycles three to five times shorter than hydraulic alternatives due to electronic component degradation.
Product Type:
After-sales service intensity diverges fundamentally across actuator architectures, with electric systems demanding specialized diagnostic capabilities while hydraulic units rely on established fluid service networks.
- Hydraulic Actuators:These systems transmit clutch force through pressurized fluid circuits, typically operating at pressures between 40 and 80 bar with response latencies of 150-200 milliseconds. Demand concentrates in commercial vehicle fleets across Germany and the United States, where technician familiarity and existing service infrastructure delay electromechanical conversion despite higher maintenance burden.
- Electric Actuators:Brushless DC motors generate precise force outputs through ball-screw or worm-gear mechanisms, achieving sub-100 millisecond response times with position feedback resolution below 0.1 millimeters. Passenger car OEMs in China and Germany densify procurement for these systems as MIIT dual carbon goals and EU F-Gas Regulation compliance eliminate hydraulic fluid handling from assembly plants.
- Pneumatic Actuators:Compressed air systems serve niche applications in heavy-duty commercial segments where onboard air supply already exists.
- Mechanical Actuators:Cable and linkage mechanisms persist in emerging market vehicle platforms with minimal electronic content.
Electric actuators hold the largest share; momentum sits with electromechanical architectures displacing hydraulic circuits in automated manual transmission applications.
Technology:
Technology segmentation maps directly to value capture potential, with integrated control modules commanding premium positioning against discrete component assemblies.
- Electromechanical Systems:These architectures merge motor, gearbox, and position sensing into sealed units compatible with 48V mild-hybrid electrical grids. Germany's KBA certification requirements and China's GB standards for electromagnetic compatibility drive convergence toward these consolidated packages.
- Intelligent Control Modules:Embedded firmware enables adaptive force curves and predictive wear algorithms through CAN-FD vehicle network integration. Tier-1 suppliers in Japan and Germany capture disproportionate margins by bundling hardware with proprietary calibration software.
- Sensor-Based Systems:Discrete Hall-effect or inductive position sensors provide feedback for external control units.
- Motor-Driven Solutions:Basic brushed DC configurations serve cost-sensitive applications with limited precision requirements.
Electromechanical systems hold the largest share; momentum sits with intelligent control modules as software-defined vehicle architectures consolidate drivetrain domain control.
End User:
End user segmentation determines margin structure, with captive OEM channels facing pressure from independent aftermarket consolidation.
- OEMs:Original equipment manufacturers specify actuators at platform design stage, locking in multi-year supply agreements with technical collaboration requirements. German and Chinese passenger car producers dominate procurement volume for dual-clutch and automated manual transmission integration.
- Aftermarket Suppliers:Independent distributors and remanufacturers capture replacement demand in aging vehicle fleets across the United States, where average vehicle age exceeds twelve years and actuator failure rates accelerate.
- Vehicle Assemblers:Contract manufacturers and kit assemblers procure actuators for regional vehicle production.
- Tier-1 Suppliers:Integrated transmission system providers bundle actuators with complete gearbox assemblies.
OEMs hold the largest share; momentum sits with aftermarket suppliers as fleet operators consolidate procurement through predictive maintenance service agreements.
Size:
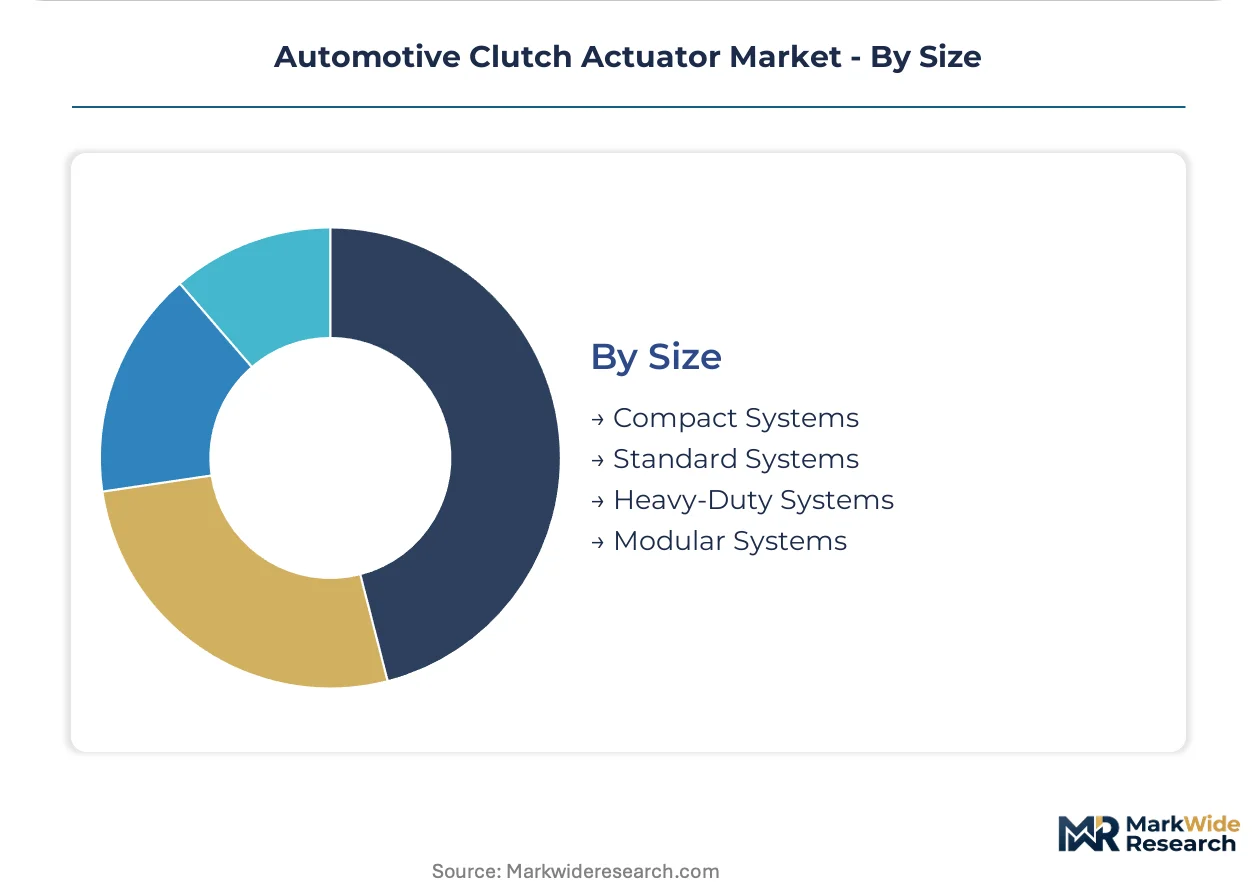
Size segmentation correlates with torque capacity requirements and packaging constraints across vehicle classes.
- Compact Systems:These units deliver 500-800N force outputs within envelope dimensions below 120 millimeters, serving A-segment and B-segment passenger cars where engine bay space constraints are acute. Chinese domestic brands and European city car specialists drive procurement concentration.
- Heavy-Duty Systems:Force outputs exceeding 2000N serve commercial vehicle applications with dry clutch diameters above 400 millimeters. North American long-haul trucking fleets and German construction vehicle producers specify these units for automated manual transmission durability.
- Standard Systems:Mid-range force outputs of 1000-1500N cover C-segment and D-segment passenger vehicles.
- Modular Systems:Scalable architectures adapt common motor and gearbox components across multiple force ratings.
Standard systems hold the largest share; momentum sits with compact systems as urban vehicle electrification densifies powertrain packaging requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Germany absorb electromechanical actuator premiums without volume elasticity, while fleet operators in the United States demand price-competitive hydraulic alternatives for aging commercial vehicle pools.
Germany
Dual-clutch transmission production lines in Stuttgart and Munich drive precision actuator procurement. KBA certification requirements for electromagnetic compatibility force suppliers toward consolidated electromechanical packages. The Baden-Württemberg cluster hosts ZF Friedrichshafen AG's integrated transmission development, anchoring tier-1 supplier concentration for 48V mild-hybrid platforms.
China
Domestic OEMs in Shanghai and Beijing densify automated manual transmission output for passenger car electrification. MIIT dual carbon goals accelerate electric actuator adoption to reduce manufacturing emissions intensity. The Yangtze River Delta transmission corridor concentrates procurement for export-oriented vehicle assemblers serving Southeast Asian markets.
United States
Long-haul trucking fleets in Michigan and Ohio prioritize hydraulic actuator durability over electromechanical conversion to minimize technician retraining costs. EPA Corporate Average Fuel Economy standards push passenger car OEMs toward engine-off coasting enabled by electric clutch actuation. The Detroit automotive cluster integrates actuator specification into centralized drivetrain control domain architectures.
Japan
Precision motor manufacturers in Nagoya and Osaka supply brushless DC architectures for clutch actuator integration. METI industrial standards govern electromagnetic compatibility for 48V mild-hybrid vehicle networks. The Aichi Prefecture automotive belt converges actuator development with hybrid powertrain control system suppliers.
India
Domestic OEMs in Pune and Chennai expand automated manual transmission production for cost-sensitive passenger segments. The PLI scheme for automotive components attracts electromechanical actuator manufacturing investment from multinational tier-1 suppliers. The Tamil Nadu automotive corridor develops export capacity for Southeast Asian and African transmission markets.
Automotive Clutch Actuator Market Competitive Landscape
Integrated transmission specialists and electromechanical component fabricators split the market along systems-integration versus discrete-component fault lines. Consolidation pressure concentrates procurement leverage among German and Japanese OEMs with captive transmission divisions. Three archetypes dominate: full-system integrators bundling actuators with complete gearbox assemblies; electromechanical module suppliers scaling across multiple OEM platforms; and bearing-specialist incumbents leveraging friction-component expertise into actuation systems. Competitive moves center on strategic partnerships for software-defined vehicle integration and capacity expansion for 48V mild-hybrid actuator lines.
Among German-based integrated suppliers, ZF Friedrichshafen AG and Schaeffler AG exemplify divergent strategic positions within the clutch actuator value chain. ZF Friedrichshafen AG occupies a position as a full-system integrator leveraging transmission portfolio breadth, while Schaeffler AG anchors the bearing-specialist archetype through friction-component expertise. Robert Bosch GmbH represents the electromechanical module scale archetype, with positioning across multiple OEM platform specifications. These three entities collectively illustrate how supplier archetypes map to distinct margin capture mechanisms in evolving drivetrain electrification.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Schaeffler AG |
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Valeo SA |
| FTE Automotive Group |
| Magneti Marelli |
| WABCO |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's container rate volatility compresses margin structures for electromechanical actuator shipments from Chinese manufacturing hubs to German transmission plants. This logistics cost pressure amplifies price differentiation between consolidated electromechanical packages and discrete component assemblies, while EU F-Gas Regulation compliance costs further stratify procurement economics across supplier tiers.
Pricing Analysis
Aftermarket service contracts drive lifetime value capture in clutch actuator economics. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 ASIL-D certification grades and bundled diagnostic software capabilities. Cost compression in mid-tier electromechanical modules intensifies as Chinese domestic brands scale 48V-compatible production. Fleet operators in the United States exhibit highest price sensitivity, prioritizing hydraulic actuator durability over electromechanical premiums, while German OEMs absorb technology premiums without volume elasticity.
Supply Chain Analysis
Extended payment terms from German OEMs to tier-1 suppliers now stretch 90-120 days, forcing working capital financing through supply-chain facilities. Manufacturing concentration centers on Germany, China, and Japan for precision motor and gearbox components. Rare earth magnet supply draws from Chinese processing facilities for neodymium and dysprosium. Single-source vulnerability in magnet procurement exposes actuator producers to export quota fluctuations. Distribution runs through captive OEM channels for original equipment, with independent aftermarket distributors serving aging fleet replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clutch actuator incumbents face substitution pressure from integrated e-axle architectures that eliminate mechanical clutches entirely in battery-electric vehicle platforms. Defense of position requires strategic repositioning around software-defined drivetrain control domains.
For Market Incumbents: Build firmware integration moats by embedding predictive wear algorithms and adaptive force curves into intelligent control modules. Anchor position through backward integration into brushless DC motor manufacturing to secure magnet supply chain leverage against Chinese export volatility. Prioritize ISO 26262 ASIL-D certification investment to lock out mid-tier competitors from German OEM platform specifications.
For New Entrants and Emerging Players: Independent aftermarket service chains in the United States and Germany represent the most penetrable entry point, bypassing traditional OEM captive distribution through direct sourcing relationships for replacement electromechanical actuators. Target fleet operator predictive maintenance agreements as anchor customers. Pursue white-label manufacturing partnerships with established bearing suppliers to shortcut transmission system integration barriers.
For Investors and Strategic Acquirers: Electromechanical module specialists with embedded software competencies and 48V mild-hybrid platform validation offer the strongest acquisition target archetype for consolidation plays. Long-term viability hinges on differentiation from commodity motor suppliers as drivetrain electrification compresses hardware margins. Monitor NHTSA failure-mode certification timelines as inflection indicator for competitive clearance rates among tier-2 suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Firmware-capable tier suppliers capture value from hardware-software bundling in centralized drivetrain architectures. |
| 48V Mild-Hybrid Platform Standardization | Electromechanical actuator compatibility with 48V grids satisfies EPA Corporate Average Fuel Economy mandates. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors mitigate geopolitical exposure in electric actuator motor production. |
| Aftermarket Service Channel Expansion | Direct relationships with fleet operators displace traditional distributors in predictive maintenance procurement consolidation. |
| ISO 26262 ASIL-D Certification Program | Functional safety compliance creates technical barriers protecting premium positioning against unvalidated competitors. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier-1 supplier procurement data anchors the qualitative findings in this study. Primary interviews with transmission system architects, actuator manufacturing executives, and aftermarket distribution managers combined with secondary validation from vehicle production databases, IHS Markit registration data, and EPA fuel economy certification filings. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across the analysis window.
Calibration against historical adoption curves for automated manual transmission and dual-clutch systems shapes the projection framework. Segmentation dimensions include vehicle class, propulsion architecture, actuator technology type, and regional production cluster. CAGRs derive from elasticity modeling against regulatory compliance deadlines and OEM platform launch schedules. Forecast inputs incorporate MIIT dual carbon goal implementation timelines and EU F-Gas Regulation phase-down trajectories.
Practitioners should monitor rare earth export quota announcements, NHTSA safety protocol amendments, and software-defined vehicle architecture standardization for early signals of forecast deviation. Macroeconomic contraction in automotive production, regulatory delay in emissions enforcement, or breakthrough in e-axle cost parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Engine Support Bar Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
CNG Powertrain Market
Powertrain
Global Automotive Clutch Market
Powertrain
Automotive Crankshaft Sensor Market
Powertrain
Automotive Drivetrain Market
Powertrain
Internal Combustion Engine Market
Powertrain
LNG Engine Market