
 Global Automotive GD Injector Market | 2026-2036
Global Automotive GD Injector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive GD Injector Market Intelligence
Asset-light leasing arrangements for fuel-system testing equipment is reconfiguring competitive entry barriers across the injector supply base. Robert Bosch GmbH leverages captive manufacturing of piezoelectric actuators to sustain margin control across premium Common Rail Injector lines. Denso Corporation anchors its position through backward integration into ceramic substrate production for solenoid valve assemblies. Continental AG competes by operating dedicated electromagnetic injector foundries in lower-cost European manufacturing zones.
Automotive GD injectors are precision fuel-delivery devices that atomize diesel or gasoline at pressures exceeding 2,000 bar into combustion chambers, utilizing solenoid, piezoelectric, or hydraulic actuation mechanisms to control injection timing within millisecond tolerances. Their primary commercial purpose is optimizing fuel-air mixing for thermal efficiency gains and particulate matter reduction in internal combustion engines. Multi Hole Injector configurations currently lead volume shipments due to OEM adoption for Euro VI and EPA Tier 4 compliance, while Piezo Injector segments capture disproportionate value pools from premium passenger car direct injection platforms. Electromagnetic technology dominates aftermarket replacement demand given simpler diagnostic protocols, whereas Piezoelectric systems concentrate in first-fit OEM supply chains where nanosecond response precision commands pricing premiums.
EPA emission thresholds for heavy-duty diesel engines and the EU F-Gas Regulation on fluorinated greenhouse gases are tightening material specifications for injector seals and cooling circuits, forcing redesign cycles among Tier 1 suppliers. Japan's METI fuel-efficiency benchmarks and China's GB standards on diesel exhaust pollutants are converging toward comparable injection pressure requirements, compressing product differentiation across export markets. Stakeholders must monitor how REACH chemical restrictions on nickel alloys reshape actuator material sourcing decisions before committing to capacity expansion plans.
Market Dynamics
Piezoelectric actuator manufacturing concentration in Germany and Japan is compressing margin structures for second-tier injector assemblers, forcing asset-light strategies and captive sourcing alliances.
Growth Catalysts
- Euro VI-equivalent emission standards:Indonesia, Thailand, and Vietnam are tightening diesel exhaust thresholds, extending replacement cycles for commercial fleet injectors and expanding aftermarket service revenue pools.
- Multi-hole injector architectures:OEMs in Germany and Japan are specifying higher-pressure combustion precision for direct injection platforms, accelerating specification upgrades across premium passenger car lines.
- Electromagnetic aftermarket preference:Simpler diagnostic protocols for solenoid-based systems are sustaining replacement demand from independent repair networks in North America and Eastern Europe.
Market Restraints
- Nickel alloy sourcing constraints:REACH chemical restrictions on nickel-based actuator materials are forcing redesign cycles before Tier 1 suppliers commit to capacity expansion.
- Piezoelectric ceramic supply concentration:Backward-integrated Japanese and German manufacturers control ceramic substrate production for solenoid valve assemblies, limiting second-source options.
- High-pressure seal material specifications:EPA emission thresholds and EU F-Gas Regulation are tightening fluorinated polymer requirements for injector cooling circuits, elevating qualification costs.
Strategic Opportunities
- Asset-light testing equipment leasing:Fuel-system validation infrastructure is reconfiguring competitive entry barriers, enabling mid-scale suppliers to access OEM qualification protocols without capital-intensive foundry investment.
- Convergence of electromagnetic and piezoelectric actuation:Hybrid injector designs blending solenoid reliability with piezo response precision are opening specification windows for dual-technology suppliers.
- China GB standard alignment:Converging diesel exhaust pollutant benchmarks with EU and Japanese requirements is compressing product differentiation and enabling single-SKU export strategies.
Industry Challenges
- Millisecond-precision calibration expertise:Nanosecond response tuning for piezoelectric systems requires specialized technician training that outpaces vocational program output in lower-cost manufacturing zones.
- Cross-regulatory certification timelines:Simultaneous EPA, REACH, and METI qualification processes for new injector architectures extend product launch windows and strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive GD Injector Market |
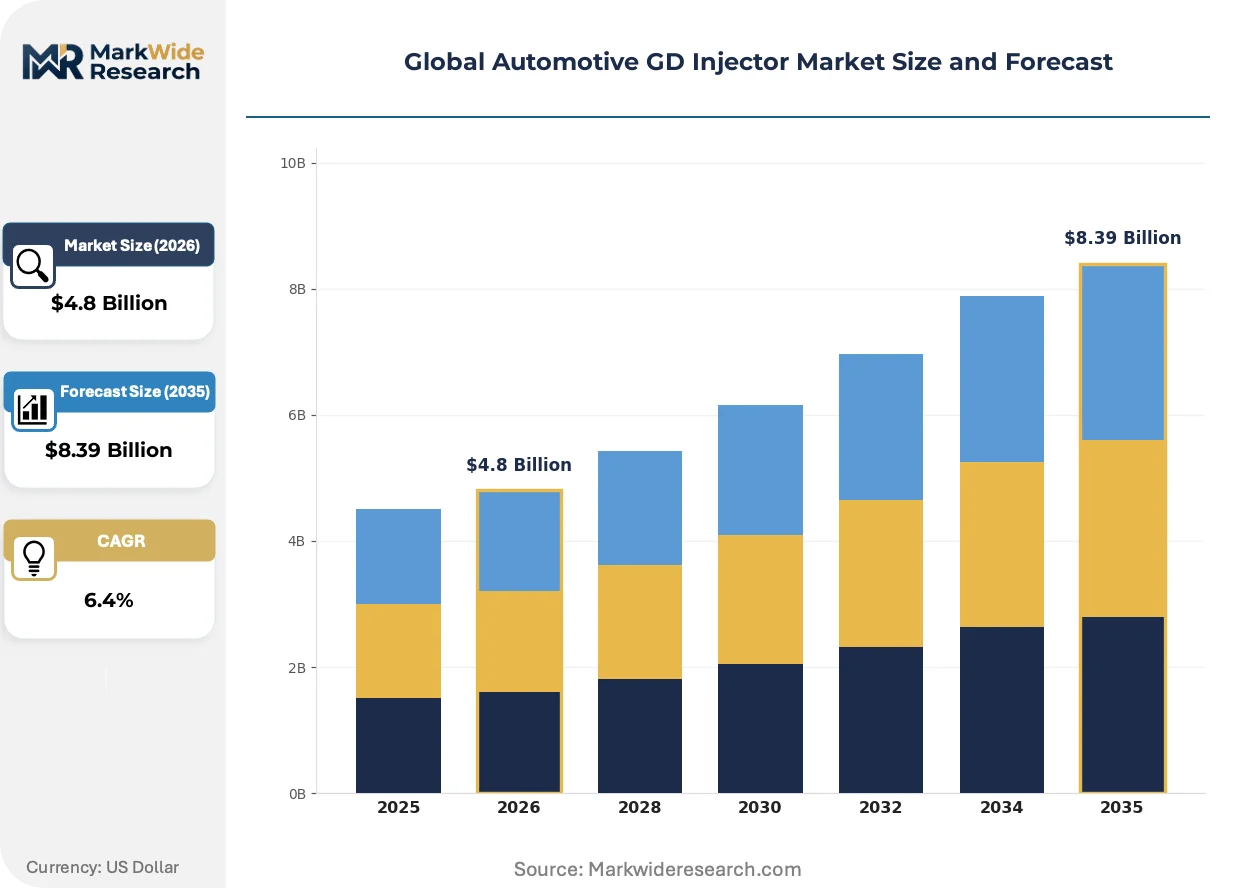
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Hole Injector, Multi Hole Injector, Solenoid Injector, Piezo Injector, Common Rail Injector, Direct Injection Injector Technology: Electromagnetic, Piezoelectric, Hydraulic, Mechanical, Magnetostrictive, Digital Application: Passenger Cars, Commercial Vehicles, Heavy-Duty Trucks, Construction Equipment, Agricultural Machines, Recreational Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Retrofitting Firms, Fleet Operators, Spare Parts Dealers, Maintenance Providers |
| Companies Covered | Delphi Technologies, Magneti Marelli S.p.A., Robert Bosch GmbH, Keihin Corporation, Stanadyne LLC, Continental AG, Hitachi Automotive Systems, Woodward, Inc., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive GD Injector Market Strategic Shifts & Innovations
Injector architecture evolution is fragmenting along actuation mechanism lines, with virtualization of testing and validation protocols compressing traditional hardware-centric development cycles.
Digital twin environments for fuel spray atomization modeling are virtualizing injector performance validation before physical prototyping. Tier 1 suppliers in Stuttgart and Nagoya are deploying computational fluid dynamics platforms to simulate 2,000-bar injection events. This capability is virtualizing the traditional foundry-test-iterate loop, collapsing development timelines from months to weeks.
Japan's METI fuel-efficiency benchmarks are converging with China's GB diesel exhaust standards, harmonizing injection pressure requirements across export markets. This regulatory alignment is eliminating regional product variants and forcing single-platform engineering strategies. OEM supply chains in Japan and South Korea are consolidating injector specifications to serve both domestic and Chinese export volumes.
Commercial fleet operators in Southeast Asia are compressing injector replacement cycles ahead of regulatory deadlines, shifting procurement from reactive breakdown service to predictive maintenance contracts. Independent service networks in Bangkok and Jakarta are unbundling after-sales support from OEM captive channels. This behavioral shift is most visible in Indonesia's logistics corridor, where third-party injector remanufacturing is capturing share from authorized dealer networks.
Global Automotive GD Injector Market Segmentation
Injector architecture fragmentation across actuation mechanisms and pressure regimes demands granular segmentation to map technology-to-application fit. Product type and technology categories reveal competing design philosophies, while application and end-user splits expose divergent procurement logics between first-fit OEM supply chains and aftermarket service networks.
Product Type:
Mature multi-hole architectures dominate commercial volumes, while emerging piezoelectric configurations capture premium specification upgrades.
- Multi Hole Injector:Precision-machined orifice plates deliver atomized spray patterns across 6-12 discrete holes, enabling optimized fuel-air mixing for Euro VI and EPA Tier 4 compliance. Demand concentrates in German and Japanese OEM passenger car platforms where combustion efficiency targets exceed 45% thermal efficiency. Fleet operators in Indonesia and Thailand specify these units for commercial vehicle retrofits ahead of emission enforcement deadlines.
- Piezo Injector:Lead zirconate titanate actuators achieve nanosecond response times for multiple injection events per combustion cycle, supporting 2,500-bar operating pressures. Japanese and German premium passenger car manufacturers specify these for direct injection gasoline platforms where millisecond-precision timing commands pricing premiums. REACH nickel alloy restrictions are forcing material redesigns before capacity expansion commitments.
- Single Hole Injector:Legacy throttle-body designs persist in cost-sensitive agricultural and recreational vehicle applications across India and Brazil.
- Solenoid Injector:Electromagnetic coil actuation dominates aftermarket replacement channels in North America and Eastern Europe due to simpler diagnostic protocols.
- Common Rail Injector:High-pressure accumulator systems anchor heavy-duty diesel platforms across Southeast Asian logistics corridors.
- Direct Injection Injector:Stratified charge capability supports downsized gasoline engines in South Korean and Chinese domestic market vehicles.
Multi Hole Injector configurations retain volume leadership; Piezo Injector architectures hold the steepest expansion curve.
Technology:
Cost tier stratification separates electromagnetic workhorses from piezoelectric precision instruments, with hydraulic and mechanical alternatives filling durability-focused niches.
- Electromagnetic:Solenoid coil and armature assemblies generate magnetic force for needle lift, operating reliably across 1,600-2,000 bar with established diagnostic protocols. Independent repair networks in Poland and Mexico prefer these systems for aftermarket service given minimal specialized tooling requirements. Simpler calibration procedures compress technician training cycles relative to piezoelectric alternatives.
- Piezoelectric:Ceramic actuator stacks expand and contract under voltage application, achieving sub-millisecond response for up to five injection events per cycle. Stuttgart and Nagoya-based Tier 1 suppliers deploy these for premium OEM first-fit supply where nanosecond precision justifies material cost premiums. Backward-integrated ceramic substrate production in Japan and Germany limits second-source availability.
- Hydraulic:Pressure-amplified needle actuation serves mining and construction equipment in Australia and Chile where contamination tolerance exceeds electronic system reliability.
- Mechanical:Cam-driven unit injectors persist in legacy agricultural machinery across Argentina and Ukraine.
- Magnetostrictive:Terfenol-D alloy actuation emerges in prototype military and aerospace fuel systems requiring extreme temperature stability.
- Digital:Electronically controlled valve timing integrates with engine management architectures for hybrid powertrain optimization in California and Shanghai regulatory environments.
Electromagnetic technology commands the broadest installed base; Piezoelectric systems are climbing the fastest on value per unit metrics.
Application:
Volume concentration in passenger cars contrasts with margin intensity in heavy-duty and off-highway segments where durability specifications extend replacement cycles.
- Passenger Cars:Downsized direct injection gasoline and diesel platforms specify multi-hole and piezoelectric injectors for 2025-2030 emission compliance horizons. German and Japanese OEMs consolidate specifications to serve both domestic and Chinese export volumes under converging METI and GB standards.
- Heavy-Duty Trucks:Long-haul diesel platforms in the US Interstate corridor and European TEN-T network demand 2,000-bar common rail systems with 800,000-kilometer durability ratings. Fleet operators compress replacement cycles ahead of EPA and Euro VI enforcement phases.
- Commercial Vehicles:Light and medium-duty distribution trucks across Indonesia and Vietnam extend service intervals through predictive maintenance contracts.
- Construction Equipment:Hydraulic excavators and wheel loaders in South Africa and Turkey specify contamination-resistant injector architectures.
- Agricultural Machines:Tractor and combine harvester applications in Brazil and India prioritize field-serviceable electromagnetic units.
- Recreational Vehicles:Marine and power-sport injectors in Florida and Queensland markets balance emission compliance with cost constraints.
Passenger Cars retain volume leadership; Heavy-Duty Trucks hold the steepest expansion curve on aftermarket service contract growth.
End User:
Procurement patterns diverge between OEM captive channels specifying first-fit precision and aftermarket networks optimizing for diagnostic simplicity and parts availability.
- OEMs:Vehicle manufacturers in Germany, Japan, and South Korea specify piezoelectric and multi-hole injectors through qualified Tier 1 supply chains with nanosecond calibration tolerances. Single-platform engineering strategies emerge as METI, EPA, and GB standards converge on injection pressure requirements.
- Aftermarket Suppliers:Independent distributors in Poland, Mexico, and Thailand stock electromagnetic solenoid injectors for repair networks prioritizing diagnostic accessibility over response precision. Inventory depth and cross-reference compatibility drive supplier selection.
- Fleet Operators:Logistics companies in Indonesia and Vietnam shift from reactive breakdown service to predictive maintenance contracts, unbundling after-sales support from authorized dealer networks.
- Vehicle Retrofitting Firms:Emission upgrade specialists in Delhi and São Paulo install certified injector replacements for pre-Euro VI commercial vehicle compliance.
- Spare Parts Dealers:Independent retailers in Istanbul and Bangkok source remanufactured units from third-party reconditioners capturing share from OEM captive channels.
- Maintenance Providers:Authorized service networks in California and Bavaria deploy proprietary calibration equipment for piezoelectric system warranty coverage.
OEMs retain volume leadership; Fleet Operators hold the steepest expansion curve on predictive maintenance contract adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission thresholds for heavy-duty diesel engines and converging fuel-efficiency benchmarks across Japan's METI and China's GB standards are compressing product differentiation and enabling single-SKU export strategies for injector manufacturers.
Germany
Premium passenger car OEMs in Stuttgart specify piezoelectric multi-hole injectors for direct injection platforms requiring nanosecond-precision timing. REACH chemical restrictions on nickel-based actuator materials force redesign cycles before capacity expansion commitments. The Baden-Württemberg automotive cluster concentrates Tier 1 supplier engineering centers and piezoelectric actuator manufacturing.
Japan
METI fuel-efficiency benchmarks drive specification upgrades across domestic and Chinese export volumes. Backward-integrated ceramic substrate production for solenoid valve assemblies limits second-source availability for competing assemblers. The Nagoya-Tokyo industrial corridor anchors captive manufacturing of piezoelectric actuators and precision injector assembly operations.
United States
Long-haul diesel platforms across the Interstate corridor demand 2,000-bar common rail systems with extended durability ratings. EPA Tier 4 and emerging heavy-duty emission enforcement compress fleet replacement cycles ahead of regulatory deadlines. Michigan-based engineering centers develop electromagnetic injector architectures for aftermarket service networks prioritizing diagnostic simplicity.
China
GB standards on diesel exhaust pollutants converge toward EU and Japanese injection pressure requirements, eliminating regional product variants. Domestic OEM supply chains consolidate specifications to serve both local and export volumes. The Yangtze River Delta manufacturing zone concentrates injector assembly operations serving South Korean and Japanese transplant production.
Indonesia
Commercial fleet operators extend injector replacement cycles ahead of Euro VI-equivalent emission enforcement across logistics corridors. Independent service networks in Jakarta unbundle after-sales support from OEM captive channels through predictive maintenance contracts. Third-party injector remanufacturing captures share from authorized dealer networks in the Java-based distribution hub.
Global Automotive GD Injector Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around three strategic archetypes: backward-integrated actuator manufacturers, electromagnetic aftermarket specialists, and asset-light testing service providers. Consolidation pressures concentrate among piezoelectric ceramic suppliers while fragmentation persists in electromagnetic aftermarket channels. Dominant competitive moves include captive sourcing alliances and geographic expansion into Southeast Asian fleet service markets.
Within the integrated manufacturing tier, Robert Bosch GmbH and Denso Corporation represent archetypes of captive supply chain control. Stuttgart-based Robert Bosch GmbH exemplifies channel-controlling positioning through in-house production of piezoelectric actuators. Denso Corporation anchors the Japanese manufacturing cluster with upstream control over ceramic substrate production. Continental AG occupies a position among European electromagnetic injector fabricators operating dedicated foundries in lower-cost manufacturing zones.
| Leading Market Players |
|---|
| Delphi Technologies |
| Magneti Marelli S.p.A. |
| Robert Bosch GmbH |
| Keihin Corporation |
| Stanadyne LLC |
| Continental AG |
| Hitachi Automotive Systems |
| Woodward, Inc. |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
German and Japanese ceramic substrate production concentrates upstream control over piezoelectric actuator supply, anchoring margin pools in first-fit OEM channels while compressing second-tier assembler pricing power across aftermarket segments.
Pricing Analysis
Certification grade creates the primary spread across injector tiers, with EPA Tier 4 and Euro VI compliance qualification separating premium first-fit supply from economy aftermarket units. Three-tier pricing structure across premium, standard, and economy levels reflects differential calibration precision, material specification, and warranty bundling. Cost compression in electromagnetic aftermarket channels is intensifying because independent repair networks prioritize diagnostic simplicity over response precision. Fleet operators in Southeast Asia exhibit highest price sensitivity through predictive maintenance contract negotiations, while German premium passenger car OEMs remain least sensitive to unit cost given nanosecond-precision requirements.
Supply Chain Analysis
Export-control restrictions on high-pressure ceramic manufacturing equipment limit technology transfer outside Germany and Japan, constraining second-source development for piezoelectric stacks. Supply concentrates in Germany, Japan, and China for finished injector assembly, with ceramic substrates and nickel alloy actuators drawing from captive upstream operations. Lead zirconate titanate ceramics, fluorinated polymer seals, and precision-machined orifice plates represent critical input dependencies. Single-source vulnerability for ceramic actuator supply creates structural risk for non-integrated assemblers. Distribution runs through OEM captive channels for first-fit volume, with independent aftermarket networks in Poland, Mexico, and Thailand handling replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts in Southeast Asian commercial fleets expand faster than hardware shipments, creating attach-rate opportunities that outpace standalone injector revenue growth.
For Market Incumbents: Harden supply chain control through captive ceramic substrate production or exclusive sourcing alliances with Baden-Württemberg and Nagoya-based actuator manufacturers. Expand electromagnetic aftermarket certification programs to defend against independent remanufacturers capturing share from authorized dealer networks in Jakarta and Bangkok. REACH nickel alloy restrictions threaten material cost structures; accelerate alternative alloy qualification before capacity commitment deadlines. For New Entrants and Emerging Players: Mid-scale fleet service providers in Vietnam and Indonesia represent the most penetrable entry point, where predictive maintenance contract unbundling from OEM channels creates procurement openness. Asset-light testing equipment leasing bypasses capital-intensive foundry investment while qualifying for OEM specification protocols. Target electromagnetic aftermarket segments in Eastern Europe and North America where simpler diagnostic protocols lower technician training barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electromagnetic aftermarket specialists holding distribution depth in Poland and Mexico but lacking piezoelectric capability. Long-term viability over a five-to-ten-year window favors platforms with hybrid actuation expertise bridging solenoid reliability and piezo precision. Watch for convergence signals between METI, EPA, and GB standards as inflection indicators for single-SKU export scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Denso Corporation and Robert Bosch GmbH anchor margin control through captive piezoelectric actuator supply. |
| Asset-Light Testing Equipment Leasing | Mid-scale suppliers access OEM qualification protocols without capital-intensive foundry investment in Stuttgart. |
| Hybrid Actuator Architecture Development | Dual-technology designs blend electromagnetic reliability with piezoelectric precision for specification flexibility. |
| Predictive Maintenance Service Contracts | Indonesian logistics operators unbundle aftermarket support from authorized dealer networks in Jakarta. |
| Single-SKU Export Platform Consolidation | Converging METI, EPA, and GB standards eliminate regional product variants for Japanese and South Korean OEMs. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet maintenance operators; and secondary validation through vehicle production databases, IHS Markit registration data, EPA emission certification filings, and REACH chemical restriction notices. Bottom-up triangulation across injector shipment volumes by technology and application combined with top-down market sizing through automotive OEM procurement spend analysis.
Forecast inputs considered actuation technology substitution rates, regulatory enforcement timelines across Indonesia, Thailand, and Vietnam, and convergence patterns between METI, EPA, and GB injection pressure standards. Segmentation dimensions modeled include injector architecture, actuation mechanism, vehicle class, content per engine, OEM tier, and regional production cluster. CAGRs derived from weighted scenario analysis across emission compliance deadlines and fleet replacement cycle compression.
Macroeconomic conditions sit as an overlay; deviation in commercial fleet utilization rates, diesel fuel price volatility, or regional trade tariff structures would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and technology substitution elasticity. Material shifts in REACH chemical restriction scope or piezoelectric ceramic export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Power Assisted Steering Market
Powertrain
Global Powertrain Market
Powertrain
Reciprocating Engine Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
Automatic Transmission Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Global Driveline Market
Powertrain
Dual Clutch Transmission (DCT) Market
Powertrain
Automotive Turbo-Compounding System Market
Powertrain
Clutch Friction Plate Market
Powertrain
Automotive TCU Market
Powertrain
Gas Engine Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Global Industrial Brakes and Clutches Market