
 North America Fleet Management Solutions Market | 2026-2036
North America Fleet Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fleet Management Solutions Market Analytics
The U.S. EPA Phase 3 greenhouse gas standards for heavy-duty vehicles is expanding compliance-driven investment in connected fleet infrastructure across North America. Geotab, Inc. leverages its open-platform architecture to anchor large-scale deployments across Canadian provincial fleets. Samsara Inc. competes through vertically integrated hardware-software stacks purpose-built for real-time vehicle diagnostics. Verizon Connect sustains market presence through extensive cellular network partnerships that dominate U.S. last-mile logistics corridors.
Fleet management solutions encompass integrated telematics platforms, route optimization engines, fuel monitoring systems, and predictive maintenance modules that combine GPS tracking, onboard diagnostics, and cloud analytics to optimize vehicle utilization, driver safety, and regulatory compliance for commercial operators. Telematics remains the dominant product category, though artificial intelligence capabilities within technology stacks represent the fastest-expanding margin pool as carriers demand predictive failure detection. Cloud-based deployment models now lead new implementations, while on-premise systems retain footholds among public sector fleets with stringent data sovereignty requirements.
The U.S. EPA, Transport Canada's Motor Vehicle Safety Directorate, and the Federal Motor Carrier Safety Administration collectively shape product standards through emissions mandates, hours-of-service logging requirements, and electronic logging device certification protocols that determine market access for solution vendors. State-level California Air Resources Board regulations extend these compliance obligations beyond federal baselines, creating fragmented certification demands across North American jurisdictions. Stakeholders must monitor evolving interoperability standards between telematics platforms and emerging vehicle-to-grid infrastructure to preserve platform relevance.
Market Dynamics
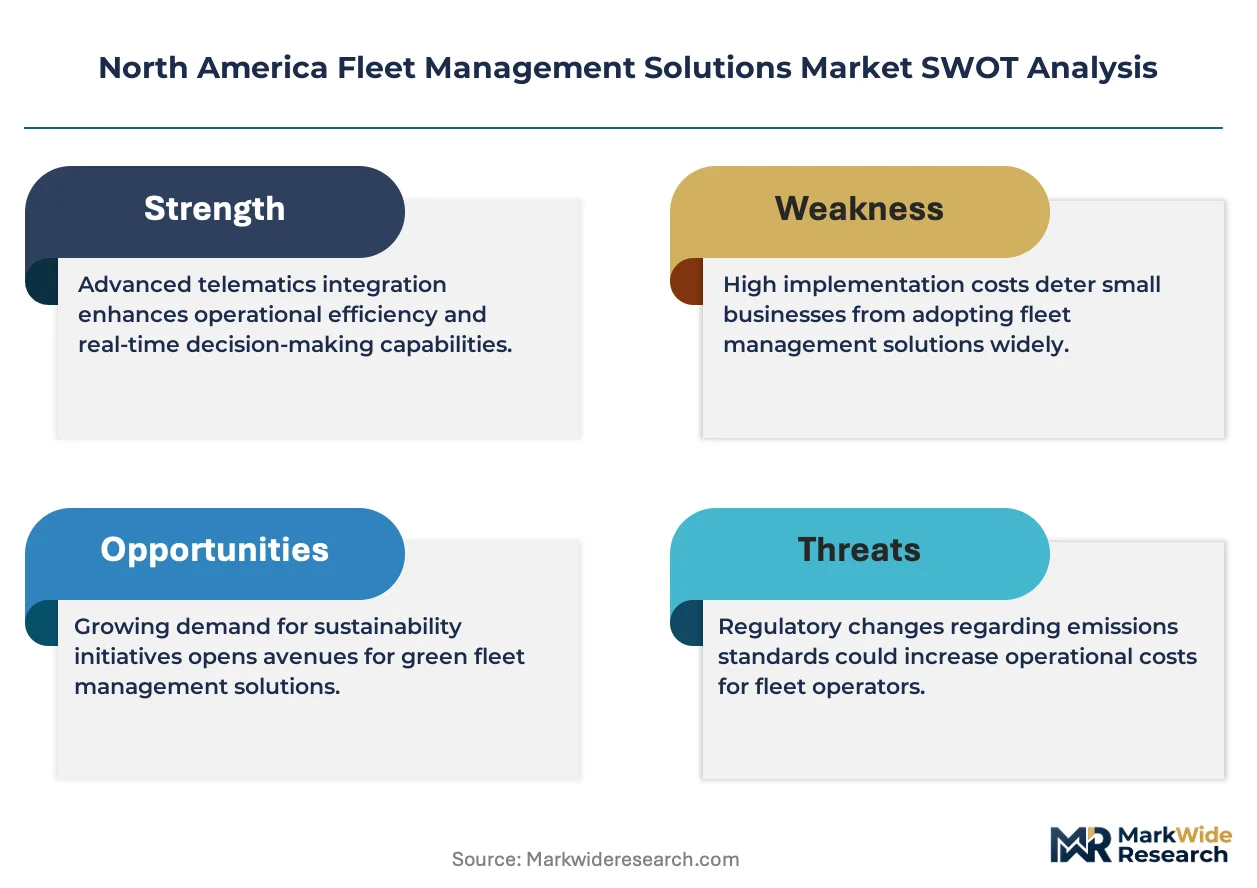
The U.S. EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles is forcing fleet operators to retrofit existing assets with real-time emissions monitoring infrastructure, compressing deployment timelines and elevating platform interoperability requirements across the United States and Canada.
Growth Catalysts
- Emissions compliance mandates:The U.S. EPA Phase 3 standards require connected telematics for continuous emissions verification, compelling private fleet operators in the U.S. Midwest to accelerate platform procurement.
- Ontario manufacturing corridor:Dense logistics networks around Toronto and Hamilton are generating concentrated demand for integrated route optimization and predictive maintenance modules among automotive parts distributors.
- Electronic Logging Device mandates:Transport Canada's Motor Vehicle Safety Directorate and the U.S. FMCSA have synchronized certification protocols, reducing vendor fragmentation and lowering adoption barriers for cross-border operators.
Market Restraints
- Cellular connectivity dependency:Rural coverage gaps across the Canadian Prairies and U.S. Mountain West create operational blind spots that degrade real-time fleet visibility and limit platform value proposition.
- Data sovereignty requirements:Public sector fleets in Canada must maintain on-premise deployments to satisfy provincial data residency laws, constraining cloud-native vendor market access.
- Sensor hardware costs:Onboard diagnostic unit installation for legacy diesel fleets carries capital intensity that delays payback periods for small-scale operators with fewer than fifty vehicles.
Strategic Opportunities
- Vehicle-to-grid integration:Electric fleet pilots in California and Quebec are creating demand for bi-directional charging coordination platforms that merge telematics with utility demand-response systems.
- Artificial intelligence convergence:Predictive failure detection algorithms trained on aggregated cross-fleet datasets represent unmonetized white space for platform vendors with sufficient data lake scale.
- Insurance channel partnerships:Usage-based coverage models from commercial auto underwriters are creating embedded distribution pathways that bypass traditional direct sales cycles.
Industry Challenges
- Interoperability certification backlog:State-level California Air Resources Board regulations extend federal EPA baselines, creating fragmented testing requirements that delay product launches by six to twelve months.
- Legacy system integration friction:ERP and dispatch software from incumbent providers in the trucking sector resists API standardization, forcing costly custom middleware development.
- Telematics engineering talent scarcity:Shortages in embedded systems firmware development and cloud architecture specialization constrain vendor scaling velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fleet Management Solutions Market |
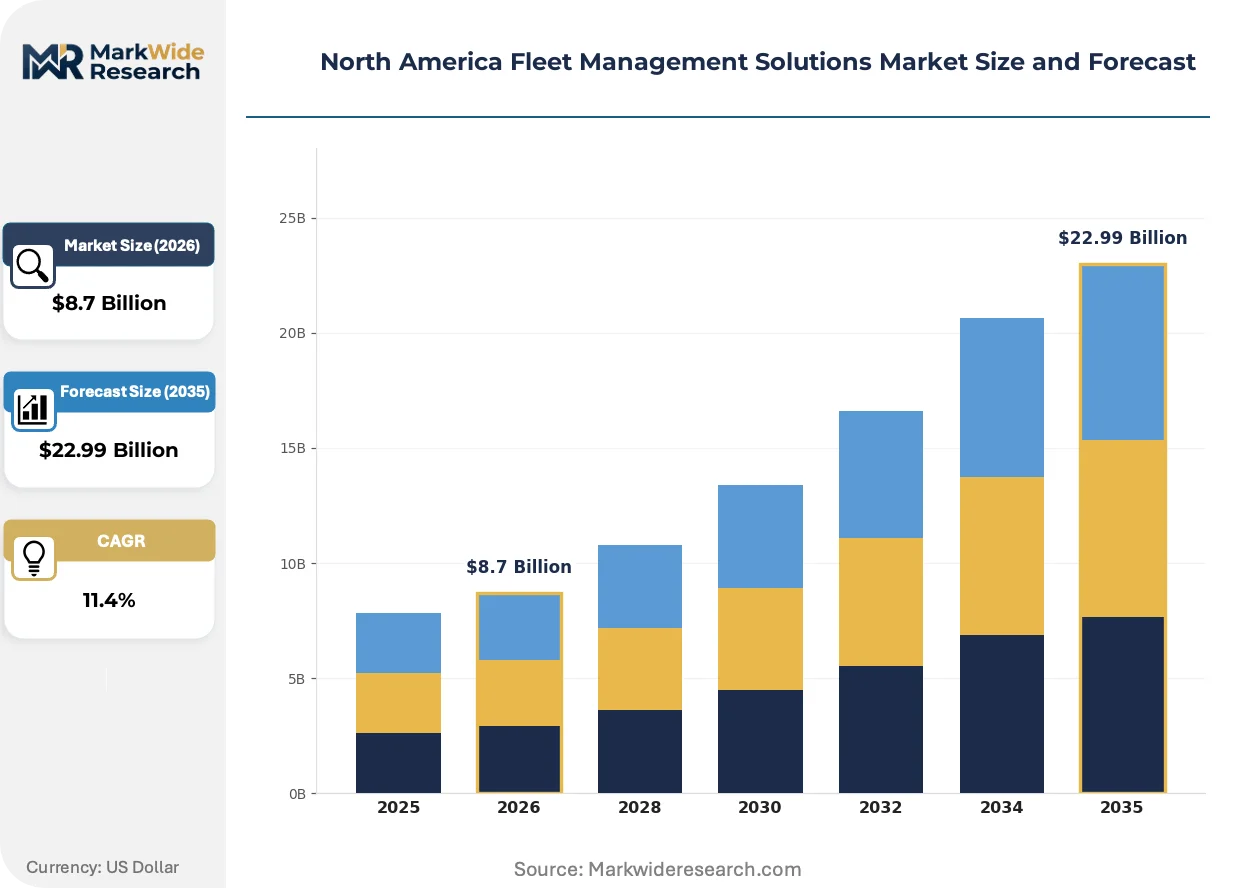
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics, Route Optimization, Fuel Management, Maintenance Management End User: Logistics Providers, Public Sector, Transportation Companies, Private Fleet Operators Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solutions Technology: GPS Tracking, IoT Integration, Big Data Analytics, Artificial Intelligence |
| Companies Covered | Geotab, Inc., Verizon Connect, Samsara Inc., Omnitracs, LLC, PowerFleet, Inc., Teletrac Navman, GPS Trackit, Inc., Trimble, Inc., Zonar Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fleet Management Solutions Market Evolving Landscape
Artificial intelligence capabilities are migrating from peripheral analytics features to core platform architecture, reshaping how fleet operators prioritize vendor selection criteria and compressing replacement cycles for first-generation telematics deployments.
Edge computing hardware is integrating directly into onboard diagnostic units, enabling localized inference for driver behavior scoring and collision avoidance alerts without cellular latency dependency. Heavy-duty carriers operating across the U.S. Interstate highway network are piloting these configurations to maintain functionality in dead zones. This architecture is integrating sensor fusion from video, radar, and CAN bus feeds into unified safety event detection workflows.
The U.S. EPA and Transport Canada have harmonized heavy-duty vehicle greenhouse gas verification protocols, creating cross-border certification reciprocity that reduces vendor compliance overhead. Manufacturers must now submit unified test data packages satisfying both jurisdictions. Private fleet operators with transnational routes are consolidating vendor relationships to exploit this regulatory convergence.
Subscription pricing models are displacing perpetual license structures across mid-market fleet segments, unbundling hardware procurement from software access and lowering initial capital barriers. Third-party logistics providers with variable contract durations prefer this flexibility. The U.S. Southeast and Texas logistics hubs exhibit the fastest migration velocity toward consumption-based fleet management contracts.
North America Fleet Management Solutions Market Segmentation
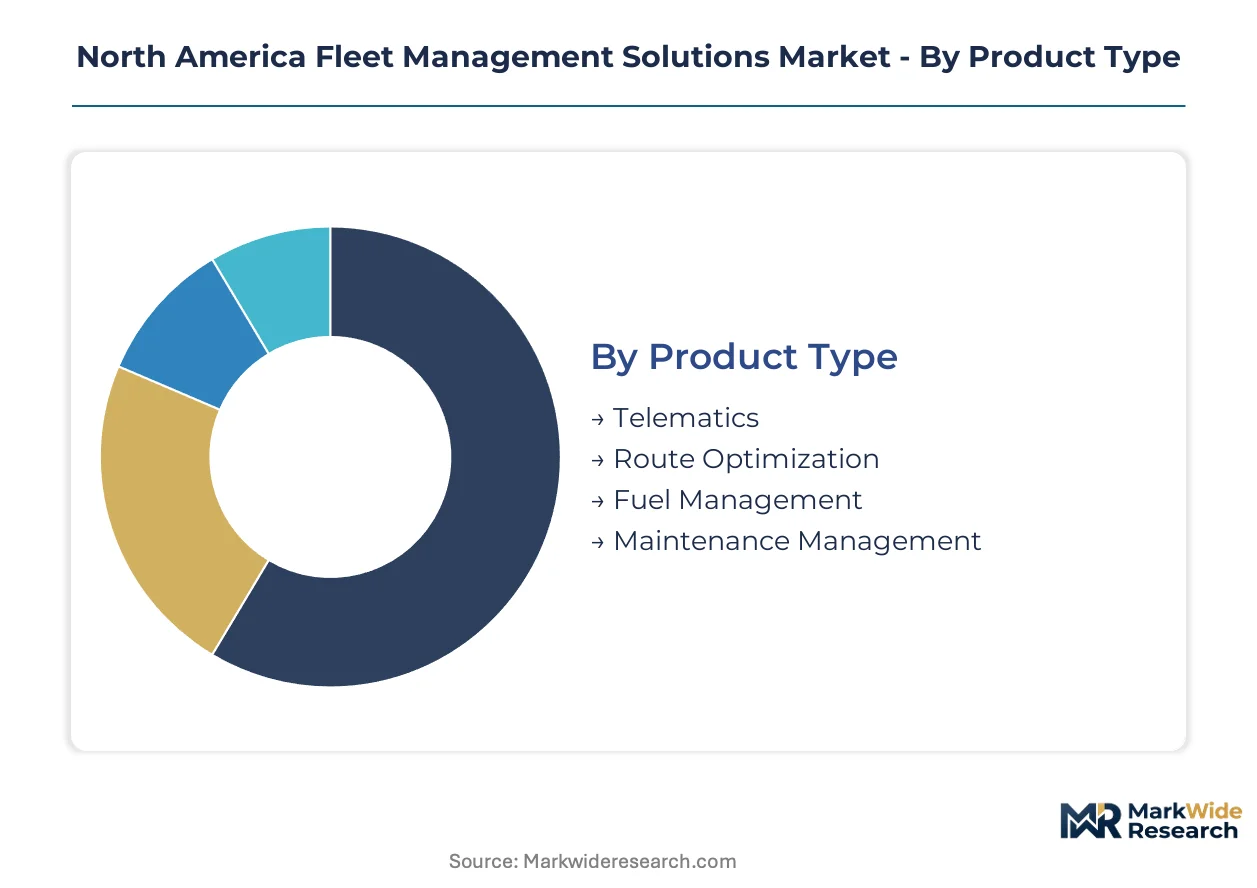
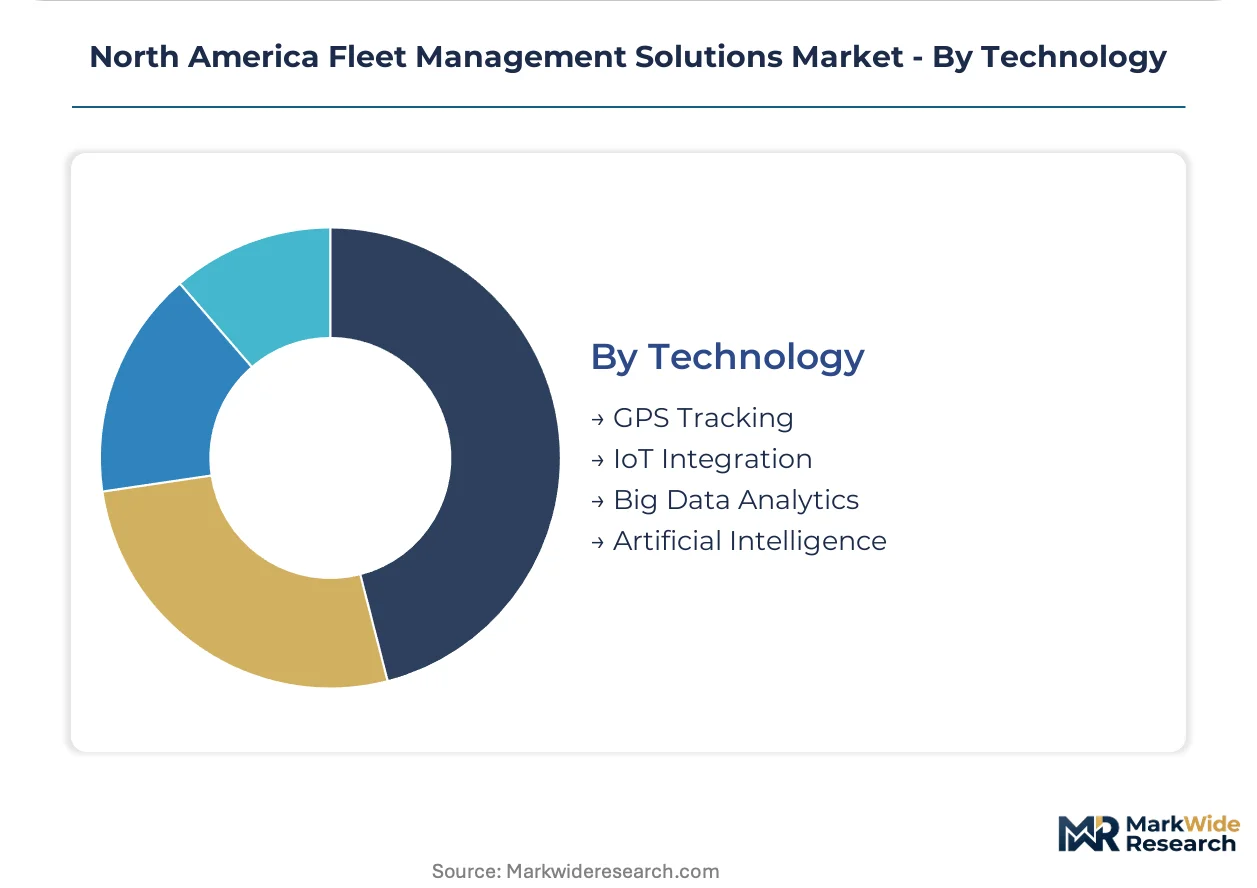
Fleet management solutions fragment across four critical dimensions that determine procurement priorities. Product type and deployment architecture dictate capital intensity, while end-user verticals and technology stacks shape feature requirements and integration complexity.
Product Type:
Supply concentration in telematics hardware manufacturing has compressed margins for standalone device vendors while elevating platform-integrated solution providers.
- Telematics:Integrated platforms combining GPS tracking, onboard diagnostics, and cellular connectivity form the foundational layer of fleet visibility. Demand concentrates among private fleet operators in the U.S. Midwest where EPA Phase 3 compliance mandates require continuous emissions verification. The Ontario manufacturing corridor generates parallel intensity for cross-border route synchronization.
- Route Optimization:Algorithmic engines processing real-time traffic, weather, and delivery window constraints to minimize fuel consumption and driver hours. Logistics providers across Texas and California logistics hubs are prioritizing these modules to offset driver shortage pressures and volatile diesel pricing.
- Fuel Management:Systems monitoring consumption patterns, idling behavior, and alternative fuel integration for cost allocation and sustainability reporting.
- Maintenance Management:Predictive modules scheduling service intervals based on actual vehicle condition rather than calendar thresholds.
Today's leader: Telematics. Tomorrow's challenger: Route Optimization.
End User:
Customer-type concentration tilts toward asset-heavy operators with compliance exposure and scale economies that justify platform investment.
- Logistics Providers:Third-party carriers managing heterogeneous vehicle fleets across multiple shipper contracts require unified visibility dashboards. The U.S. Southeast and Texas corridors exhibit fastest migration velocity toward consumption-based contracts that align platform costs with contract duration variability.
- Private Fleet Operators:Captive transportation departments of retailers, manufacturers, and distributors with dedicated routes and predictable demand patterns. These operators in the U.S. Midwest and Ontario's automotive parts distribution networks are accelerating procurement to satisfy synchronized U.S. FMCSA and Transport Canada electronic logging mandates.
- Public Sector:Municipal and provincial fleets with stringent data sovereignty requirements and multi-decade asset replacement cycles.
- Transportation Companies:Dedicated passenger and freight carriers with specialized vehicle configurations and unionized workforce considerations.
Private Fleet Operators command current procurement volume. Logistics Providers are climbing the fastest as outsourcing accelerates.
Deployment:
Architecture decisions increasingly hinge on data residency obligations and connectivity reliability across operating geographies.
- Cloud-Based:Subscription models unbundling hardware from software access now lead new implementations. The U.S. Southeast and Texas logistics hubs exhibit fastest migration velocity toward these consumption-based structures that lower initial capital barriers for mid-market operators.
- On-Premise:Deployments maintained within fleet operator data centers to satisfy provincial data residency laws. Canadian public sector fleets and U.S. defense contractors retain these configurations despite higher total cost of ownership.
- Hybrid:Architectures partitioning sensitive operational data locally while leveraging cloud analytics for aggregated benchmarking.
- Mobile Solutions:Driver-facing applications extending platform functionality through personal or company-issued devices.
Cloud-Based architectures dominate new adoption. Hybrid models are gaining share fastest among cross-border operators navigating fragmented compliance jurisdictions.
Technology:
Technology stack concentration is shifting from location-centric to inference-centric capabilities as artificial intelligence migrates from peripheral feature to core architecture.
- Artificial Intelligence:Predictive failure detection algorithms trained on aggregated cross-fleet datasets are compressing replacement cycles for first-generation telematics. Heavy-duty carriers across the U.S. Interstate network are piloting edge-integrated configurations that maintain functionality in cellular dead zones.
- GPS Tracking:Satellite and terrestrial positioning systems providing foundational location visibility with meter-level accuracy for route verification and geofencing applications.
- IoT Integration:Sensor fusion from video, radar, and CAN bus feeds into unified safety event detection workflows.
- Big Data Analytics:Aggregation platforms processing historical operational data for benchmarking and strategic network design.
Artificial Intelligence represents the steepest expansion trajectory. IoT Integration is emerging as the critical enabler for next-generation safety and emissions compliance workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telematics engineering talent clusters in the U.S. Interstate corridor and Ontario's technology hubs anchor regional platform development. Cross-border regulatory harmonization between U.S. and Canadian agencies accelerates vendor certification reciprocity. Mexican manufacturing logistics networks are emerging as a tertiary demand center for connected fleet infrastructure.
United States
Private fleet operators across the U.S. Midwest are retrofitting heavy-duty assets with emissions monitoring hardware to satisfy EPA Phase 3 compliance deadlines. The Federal Motor Carrier Safety Administration mandates synchronized electronic logging device certification with Transport Canada, reducing cross-border vendor fragmentation. Dallas-Fort Worth logistics hubs exhibit fastest migration velocity toward consumption-based fleet management contracts.
Canada
Provincial data residency laws compel public sector fleets in Ontario and Quebec to maintain on-premise deployment architectures despite higher total cost of ownership. Transport Canada's Motor Vehicle Safety Directorate harmonized greenhouse gas verification protocols with U.S. EPA standards, creating unified certification pathways. Toronto-Hamilton manufacturing corridors generate concentrated demand for predictive maintenance modules among automotive parts distributors.
Mexico
Maquiladora logistics networks in Nuevo León and Baja California are piloting connected fleet platforms to synchronize with U.S. cross-border supply chains. The country's federal telecommunications regulator shapes cellular connectivity standards that determine telematics coverage reliability in northern manufacturing zones. Mexico City Metro commercial fleets represent an emerging demand segment for route optimization engines addressing congestion-intensive urban delivery.
North America Fleet Management Solutions Market Competitive Landscape
Capital-heavy platform operators compete with asset-light software specialists across the North American fleet management ecosystem. Market structure tilts toward consolidated platform providers with integrated hardware-software stacks, though niche specialists retain footholds in vertical-specific applications. Three archetypes dominate: cellular-network-anchored telematics providers, open-architecture platform vendors, and vertically integrated safety-technology specialists. Competitive dynamics center on strategic partnerships with commercial auto underwriters and edge-computing hardware integration.
Among Canada-based platform vendors, Geotab, Inc. occupies a position exemplifying open-architecture deployment models across provincial fleet systems. Samsara Inc. and Verizon Connect represent contrasting archetypes within the integrated hardware-software tier, with the former anchoring real-time diagnostics specialization and the latter sitting within cellular-network-dominant logistics corridors. These three entities collectively illustrate the competitive tension between interoperability-focused and vertically integrated platform strategies.
| Leading Market Players |
|---|
| Geotab, Inc. |
| Verizon Connect |
| Samsara Inc. |
| Omnitracs, LLC |
| PowerFleet, Inc. |
| Teletrac Navman |
| GPS Trackit, Inc. |
| Trimble, Inc. |
| Zonar Systems |
| Others |
Value Network & Pricing Analysis
Platform-commodity divergence between integrated telematics stacks and standalone hardware vendors manifests in bifurcated margin structures across North American fleet management procurement. Subscription-based cloud deployments command pricing premiums through unbundled hardware-software contracts, while sensor manufacturers face cost compression from concentrated semiconductor sourcing.
Pricing Analysis
Bundled hardware-software contracts versus unbundled SaaS tiers define the pricing landscape for fleet management solutions. Three-tier pricing structure across enterprise, mid-market, and entry-level segments differentiates by API integration depth and edge-computing capability. Pricing pressure stems from cellular module commoditization and compressed sensor hardware margins. Mid-market logistics providers exhibit highest price sensitivity due to variable contract durations, while enterprise private fleets prioritize interoperability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries supplying GPS chipsets and cellular modems for onboard diagnostic units. Hardware assembly concentrates in Mexico, China, and Vietnam, drawing from rare earth magnet suppliers in China and memory component manufacturers in South Korea. Tariff exposure on Chinese-sourced IoT sensors threatens margin stability for device vendors. Distribution runs through cellular carrier partnerships and direct enterprise sales teams serving cross-border U.S.-Canada logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American fleet management solutions function as a stable compounder anchored by regulatory compliance mandates that perpetually refresh hardware replacement cycles. EPA Phase 3 standards and synchronized FMCSA-Transport Canada logging protocols create durable demand visibility.
For Market Incumbents: Acquire edge-computing firmware capabilities to defend against AI-native challengers entering predictive maintenance segments. Deepen API standardization investments to reduce middleware friction with legacy ERP systems in trucking dispatch software. Prioritize certification reciprocity across California Air Resources Board and EPA protocols to compress product launch timelines.
For New Entrants and Emerging Players: Commercial auto underwriters represent the most penetrable channel partner type for bypassing direct sales cycles in mid-market fleet segments. Target Ontario manufacturing corridor automotive parts distributors with route optimization modules purpose-built for cross-border synchronization. Pursue vehicle-to-grid integration pilots in California and Quebec as a differentiated entry wedge against established telematics platforms.
For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native vendors lack on-premise deployment capabilities to serve Canadian public sector data sovereignty requirements. Five-to-ten year viability favors platform operators with aggregated cross-fleet data lakes sufficient for training predictive failure algorithms. Monitor harmonization progress between EPA and Transport Canada certification protocols as an inflection signal for vendor margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telematics, route optimization, and predictive maintenance into single vendor relationships for cross-border operators. |
| Edge Computing Hardware Development | Enables localized inference in cellular dead zones across U.S. Interstate highway corridors and Canadian Prairie routes. |
| Insurance Channel Partnership | Embeds usage-based coverage models from commercial auto underwriters into fleet procurement workflows. |
| Regulatory Certification Investment | Secures unified EPA-Transport Canada test data packages that reduce compliance overhead for transnational fleet vendors. |
| AI Predictive Maintenance Acquisition | Captures failure detection algorithms trained on aggregated cross-fleet datasets as the fastest-expanding margin pool. |
Research Methodology
Multiple input streams — fleet operator procurement directors, telematics platform engineers, cellular carrier partnership managers, and commercial auto underwriters — were reconciled against secondary validation from FMCSA electronic logging device certification databases, EPA greenhouse gas compliance filings, Transport Canada Motor Vehicle Safety Directorate protocols, and cross-border trade flow records. Bottom-up vehicle-unit deployment estimates and top-down platform revenue aggregation were triangulated to anchor market sizing.
Data-stream reconciliation across product type, deployment architecture, end-user vertical, and technology stack dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curves weighted by regulatory mandate enforcement timelines and fleet replacement cycle patterns. Edge-computing integration velocity and AI module attach rates served as industry-specific forecast inputs.
Revisions become necessary when cellular coverage expansion in rural corridors accelerates, EPA Phase 4 standards materialize, or vehicle-to-grid infrastructure interoperability protocols shift. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Global Ridesharing Market