
 Automotive Park Brake Lever (Handbrake) Market | 2026-2036
Automotive Park Brake Lever (Handbrake) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Park Brake Lever (Handbrake) Market Outlook
Aftermarket distributors are collapsing as a buyer archetype while OEM direct procurement is gaining share in park brake lever sourcing. ZF Friedrichshafen AG leverages its integrated chassis systems portfolio to anchor long-term supply contracts with European and Asian automakers. Robert Bosch GmbH sustains technology leadership through electromechanical park brake actuation platforms. Continental AG competes on manufacturing scale across multiple vehicle segments simultaneously.
An automotive park brake lever is a mechanical or electromechanical control interface that transmits driver input to engage a vehicle's parking brake system, typically constructed from die-cast aluminum or reinforced polymer composites with steel cable attachments or electronic sensor interfaces. Its primary purpose is to secure stationary vehicles against unintended movement on inclines or during loading operations. Mechanical product type retains dominant volume share in emerging markets where cost sensitivity shapes procurement decisions, while electronic installations command premium positioning in luxury and electric vehicle platforms. Servo-assisted technology leads OEM fitment rates in passenger vehicles across North America and Western Europe, though smart adaptive configurations are expanding fastest in premium electric vehicle segments where integration with autonomous parking systems creates new functional requirements.
NHTSA Federal Motor Vehicle Safety Standard 135 governs parking brake performance criteria for vehicles sold in the United States, while ECE R13-H harmonizes brake system requirements across European type-approval frameworks. China's GB 21670 standard administered by MIIT imposes comparable deceleration and holding-force thresholds for domestic-market vehicles. Stakeholders must monitor divergence between mechanical legacy specifications and electronic system cybersecurity protocols as regulatory scopes expand beyond pure performance metrics into functional safety and data integrity domains.
Market Dynamics
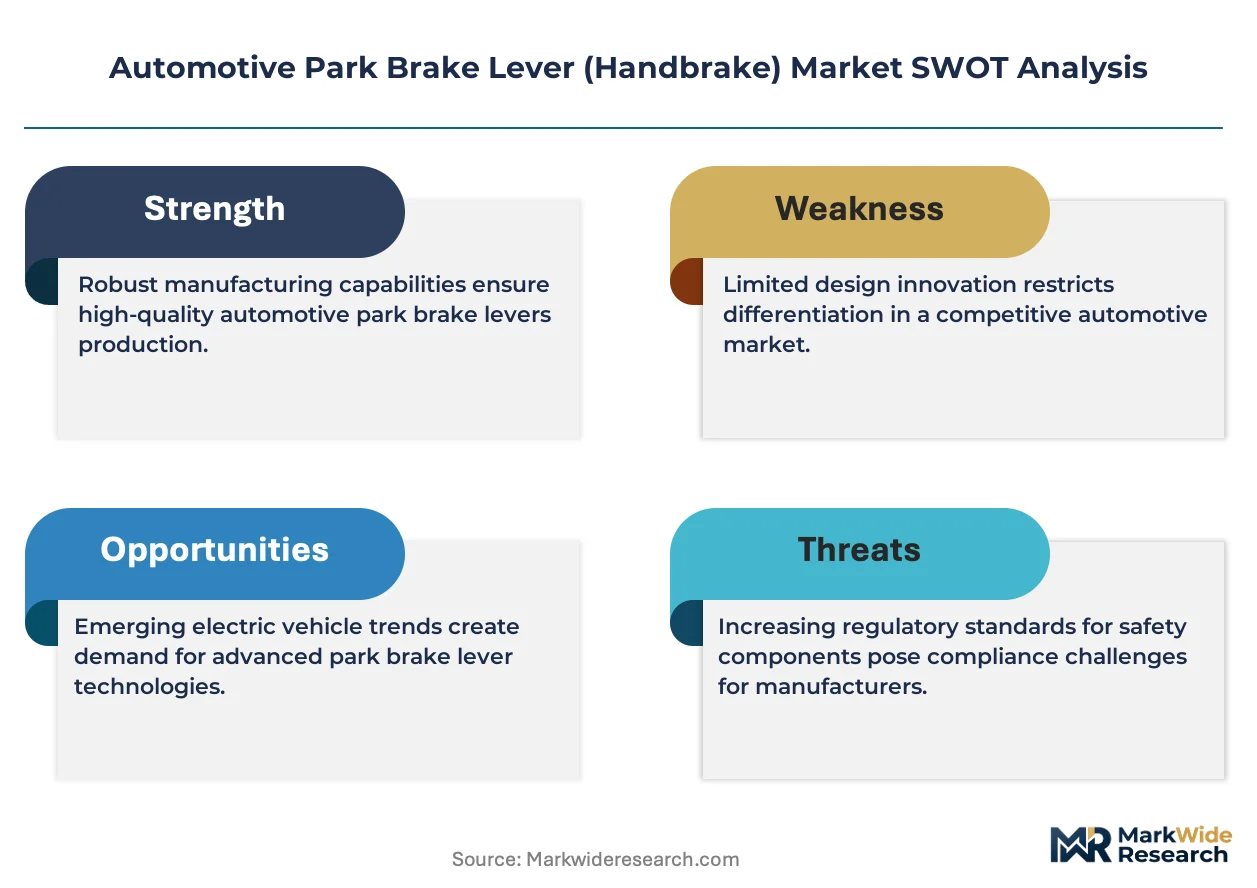
The automotive park brake lever market faces structural compression as electronic parking brake systems capture fitment share from mechanical architectures, forcing suppliers to reconfigure product portfolios toward electromechanical actuation platforms and integrated chassis electronics.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 135:US mandates for parking brake holding performance on inclines are accelerating OEM validation cycles for electromechanical alternatives with self-diagnostic capabilities.
- Electric vehicle platform proliferation:EV architectures favor brake-by-wire integration that eliminates mechanical cable routing, creating native demand for electronic park brake modules with autonomous parking compatibility.
- Die-cast aluminum supply localization:China's MIIT industrial policies are concentrating secondary aluminum smelting capacity in Jiangsu and Guangdong provinces, reducing input costs for lever housing production.
Market Restraints
- Steel cable commodity volatility:Galvanized steel wire rod prices fluctuate with scrap metal arbitrage between Turkish and Southeast Asian export markets, compressing margin stability for mechanical lever manufacturers.
- Electronic system validation costs:ISO 26262 functional safety certification for electromechanical park brakes requires ASIL-D compliance expenditure that excludes tier-two suppliers without chassis electronics heritage.
- Mechanical lever substitution ceiling:Emerging market commercial vehicle fleets in Brazil and India retain cable-actuated handbrakes due to aftermarket serviceability requirements and technician familiarity.
Strategic Opportunities
- India commercial vehicle electrification:The country's Bureau of Indian Standards is drafting performance benchmarks for electric bus parking brake systems, opening specification windows for integrated electromechanical suppliers.
- Autonomous parking convergence:Sensor fusion with ultrasonic and camera arrays enables self-engaging park brake protocols, creating software-defined functionality premiums beyond hardware commodity pricing.
- Direct OEM procurement channels:Tier-one chassis integrators are bypassing traditional brake component distributors to secure long-term lever supply agreements with volume commitment structures.
Industry Challenges
- Mechatronics talent scarcity:Electromechanical park brake development requires embedded software engineers with motor control algorithm expertise, a skill profile concentrated at automotive electronics specialists rather than legacy brake suppliers.
- Legacy system integration friction:Electronic park brake modules must maintain backward compatibility with mechanical emergency brake protocols during power failure scenarios, complicating fail-safe architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Park Brake Lever (Handbrake) Market |
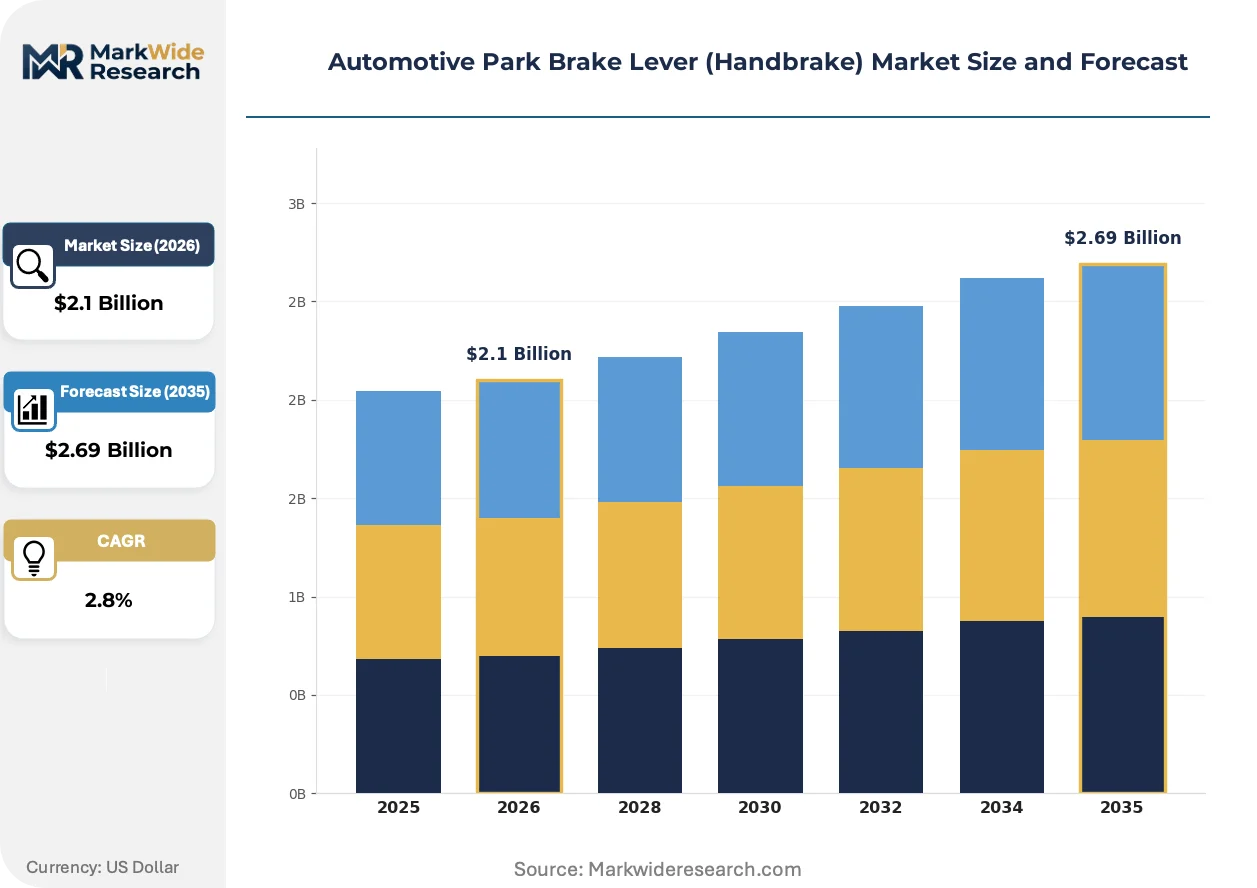
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.69 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Hybrid, Pneumatic Technology: Servo-Assisted, Manual, Adaptive, Smart Installation: OEM, Aftermarket, Retrofit, Custom End User: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Others |
| Companies Covered | ZF Friedrichshafen AG, Hitachi Astemo, Orscheln Products, Akebono, Brembo, JaiRaj Ancillaries Private Limited, Robert Bosch GmbH, Nissin, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Park Brake Lever (Handbrake) Market Strategic Shifts
Electromechanical actuation architectures are fundamentally restructuring competitive boundaries in brake lever supply, collapsing the distinction between mechanical component fabrication and electronic control system integration while redistributing value capture toward software-capable tier-one suppliers.
Reinforced polymer composite lever housings are displacing die-cast aluminum in mass-market passenger vehicles where weight reduction targets intersect with cost-neutral material substitution. European OEMs led by German premium manufacturers have validated glass-fiber reinforced polyamide formulations for pedal feel and thermal stability. This displacement is compressing traditional aluminum foundry capacity utilization while elevating injection molding tooling expertise as a core supplier competency.
ECE R13-H brake harmonization standards are mandating unified performance thresholds across European type-approval frameworks, eliminating national regulatory fragmentation that previously enabled regional product variants. The regulation's holding-force gradients and response-time specifications are accelerating convergence toward electronic actuation platforms with closed-loop motor control. Suppliers without ECE certification infrastructure are retreating to aftermarket mechanical replacement segments.
Fleet procurement centralization is consolidating brake lever sourcing decisions at commercial vehicle OEM headquarters rather than distributed regional manufacturing plants. This behavioral shift elevates total cost of ownership analytics over unit price negotiation, favoring suppliers with predictive maintenance data integration and warranty cost modeling capabilities. The pattern is most visible in North American heavy-duty truck manufacturing where fleet telematics penetration exceeds 70 percent.
Automotive Park Brake Lever (Handbrake) Market Segmentation
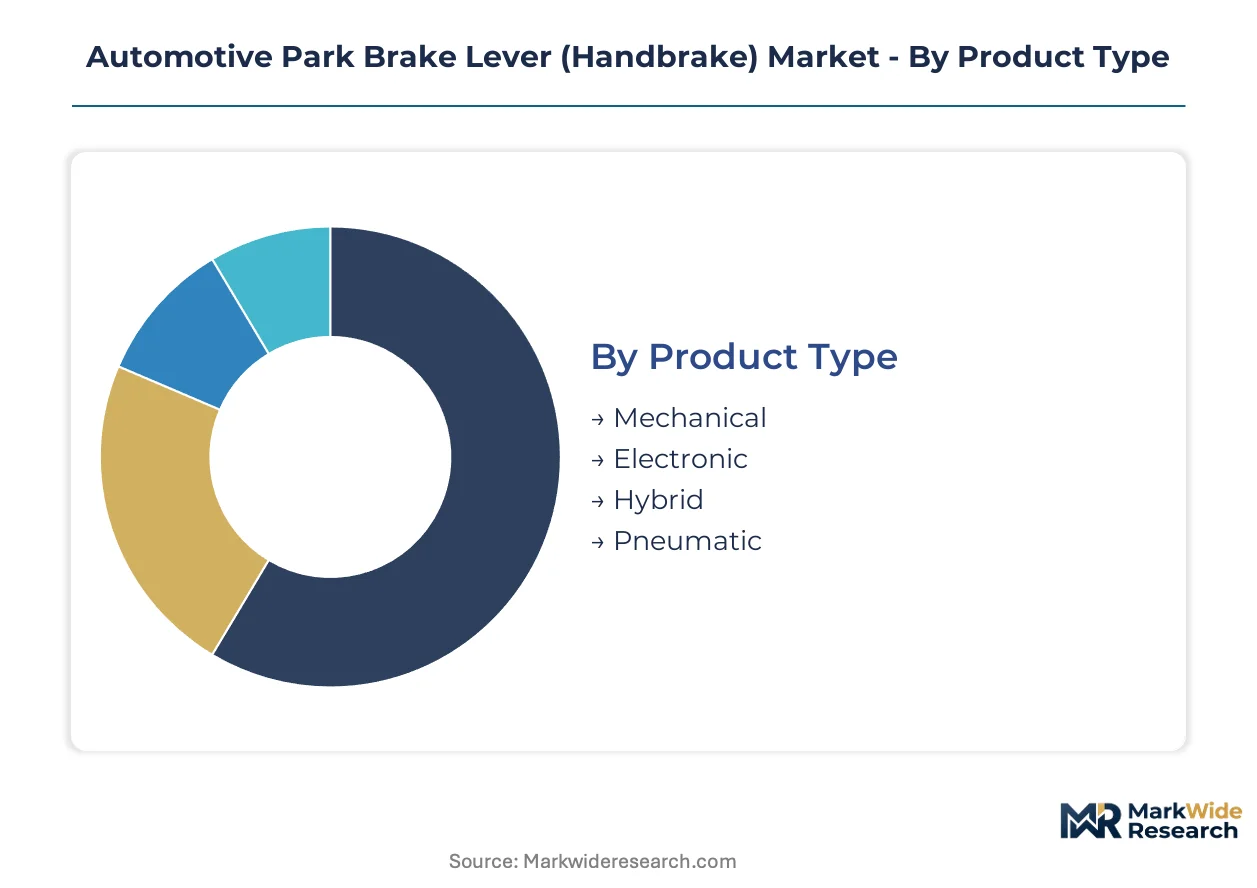
Segmentation in the automotive park brake lever market reveals divergent margin architectures across electromechanical and mechanical product architectures. Suppliers must align portfolio depth with the technology trajectory of target vehicle platforms rather than pursuing uniform coverage across all categories.
Product Type:
Premium margins concentrate in electronic and hybrid configurations where software integration and functional safety certification create supplier stickiness, while mechanical variants compete on scale economies in cost-sensitive emerging markets.
- Mechanical:Cable-actuated steel lever assemblies with die-cast aluminum housings dominate Brazil and India commercial vehicle production. Fleet operators in these markets prioritize field serviceability and technician familiarity over electromechanical sophistication.
- Electronic:Motor-driven actuation modules with integrated ECUs and CAN bus connectivity command OEM fitment in European and Chinese electric vehicle platforms. Brake-by-wire architectures eliminate mechanical routing entirely.
- Hybrid:Dual-mode systems retain mechanical backup for emergency scenarios while enabling electronic convenience features.
- Pneumatic:Compressed-air actuation serves heavy-duty truck and bus applications with existing air brake infrastructure.
The dominant share belongs to Mechanical, while Electronic is closing the gap fastest.
Technology:
Installation rates vary sharply by vehicle price tier, with servo-assisted systems achieving near-universal penetration in Western European passenger vehicles while manual configurations persist in entry-level emerging market offerings.
- Servo-Assisted:Vacuum-boosted or electric motor-assisted actuation reduces driver effort. German premium OEMs specify these for mid-range and above passenger vehicles.
- Manual:Direct mechanical linkage without power assistance. Indian and Brazilian commercial vehicle manufacturers specify these for cost containment.
- Adaptive:Load-sensing modulation adjusts holding force based on vehicle mass and incline angle.
- Smart:Sensor fusion with ultrasonic and camera arrays enables autonomous engagement protocols. Premium electric vehicle platforms in China integrate these with self-parking systems.
Servo-Assisted holds the volume lead, though Smart configurations are expanding most quickly in premium segments.
Installation:
Channel economics are restructuring as OEM direct procurement displaces traditional aftermarket distribution, compressing margin capture for distributors while elevating long-term contract value for tier-one chassis integrators.
- OEM:Direct supply agreements with volume commitments and joint development programs. ZF Friedrichshafen AG and Continental AG anchor this channel through integrated chassis system portfolios.
- Aftermarket:Replacement mechanical levers for aging vehicle fleets. Distributor consolidation is reducing buyer fragmentation in North America.
- Retrofit:Electronic system upgrades for commercial vehicle fleets seeking telematics integration.
- Custom:Specialized configurations for motorsport and modified vehicle applications.
OEM commands the revenue concentration, while Retrofit is gaining traction fastest among fleet operators.
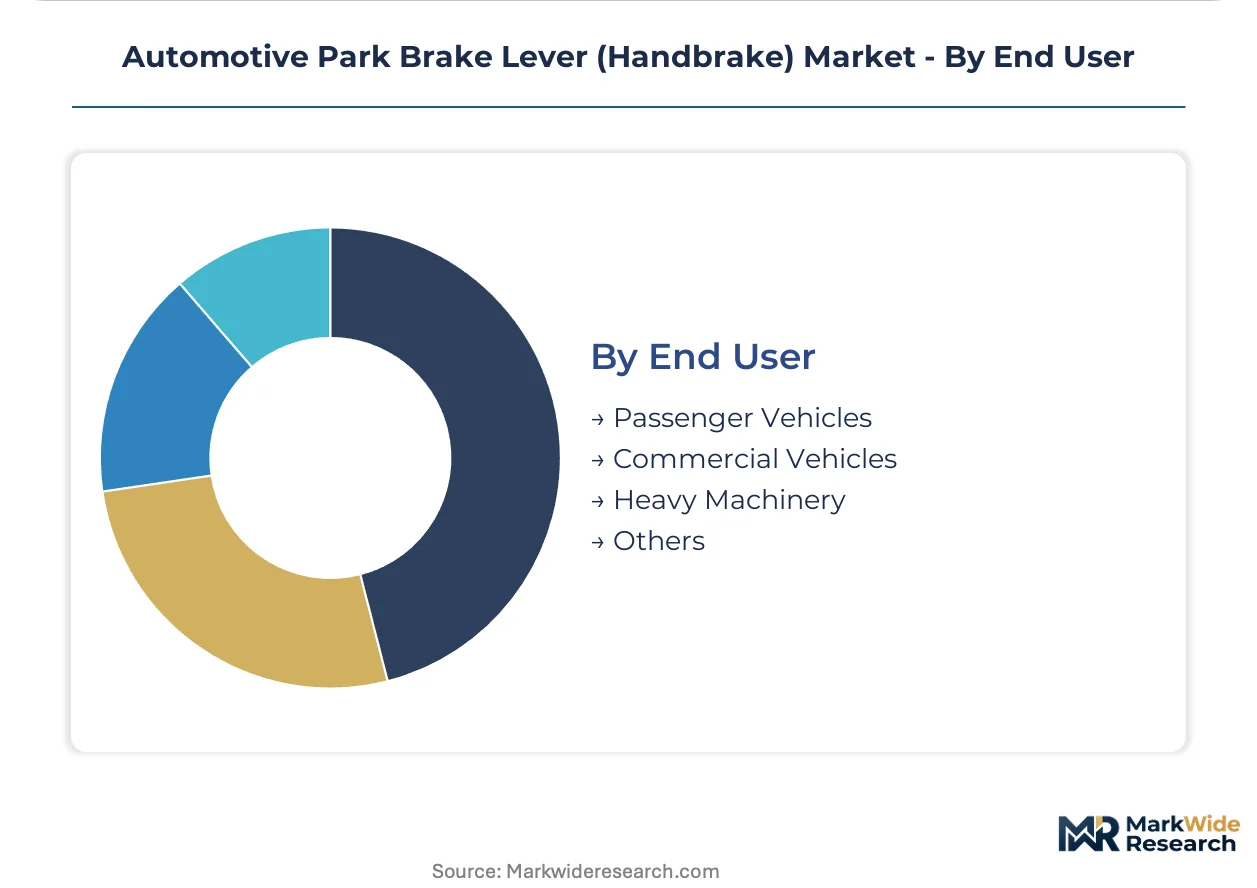
End User:
Application requirements diverge substantially between passenger vehicle emphasis on cabin ergonomics and commercial vehicle prioritization of regulatory compliance and fleet telematics integration.
- Passenger Vehicles:Center console or foot-pedal configurations with aesthetic integration requirements. European and Chinese electric vehicle platforms are accelerating electronic fitment rates.
- Commercial Vehicles:Heavy-duty mechanical or pneumatic levers with holding-force validation for loaded operation. NHTSA Standard 135 governs US market compliance.
- Heavy Machinery:Industrial-grade actuation with environmental sealing for construction and agricultural equipment.
- Others:Recreational vehicles, specialty transport, and off-highway applications with bespoke specifications.
Passenger Vehicles retains the dominant position, while Commercial Vehicles is advancing fastest through fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deepwater Port anchors China's dominance in automotive component trade, handling die-cast aluminum and polymer composite feedstock for brake lever manufacturing clusters across the Yangtze River Delta.
United States
Detroit Three OEMs are accelerating electronic park brake validation cycles to meet NHTSA Federal Motor Vehicle Safety Standard 135 holding-force requirements on steep grades. The Michigan-Ohio automotive corridor concentrates electromechanical system testing facilities. Tier-one suppliers in Detroit are securing long-term volume commitments with direct procurement structures that bypass traditional aftermarket distributors.
Germany
Premium manufacturers in Stuttgart and Munich specify servo-assisted configurations with glass-fiber reinforced polyamide housings for thermal stability. ECE R13-H harmonization standards eliminate national regulatory fragmentation across European type-approval frameworks. The Baden-Württemberg supplier ecosystem integrates brake-by-wire architectures with chassis electronics portfolios.
China
Domestic OEMs in Shanghai and Guangzhou are localizing die-cast aluminum supply chains under MIIT industrial policies concentrating secondary smelting capacity in Jiangsu and Guangdong provinces. GB 21670 standard administered by MIIT imposes deceleration thresholds comparable to NHTSA and ECE frameworks. BYD and NIO platforms are driving electronic fitment rates in premium electric vehicle segments.
India
Commercial vehicle manufacturers in Pune and Chennai retain cable-actuated mechanical handbrakes for field serviceability and technician familiarity in heavy-duty truck fleets. The Bureau of Indian Standards is drafting performance benchmarks for electric bus parking brake systems. JaiRaj Ancillaries and similar domestic suppliers anchor mechanical lever production for cost-sensitive procurement decisions.
Japan
Hitachi Astemo and Nissin supply electromechanical modules to Toyota and Honda platforms prioritizing brake-by-wire integration with autonomous parking compatibility. METI industrial standards guide functional safety certification alignment with ISO 26262 ASIL-D requirements. The Aichi Prefecture cluster concentrates motor control algorithm development for smart adaptive configurations.
Automotive Park Brake Lever (Handbrake) Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and technology integration dimensions, creating a tiered structure where scale-driven chassis integrators face agile component specialists. The market fragments across three strategic archetypes: integrated tier-one chassis suppliers with electromechanical portfolios, regional mechanical fabrication specialists serving cost-sensitive fleets, and electronics-focused entrants capturing brake-by-wire transitions. Dominant competitive moves include backward integration into aluminum foundry and polymer compounding capacity, plus strategic partnerships with electric vehicle platform developers seeking native electronic brake compatibility.
Among German-based integrated suppliers, ZF Friedrichshafen AG and Continental AG exemplify the tier-one chassis archetype with multi-vehicle segment coverage and long-term OEM contract structures. Robert Bosch GmbH represents the electronics-specialist vector, leveraging embedded software capabilities for electromechanical actuation platforms. Japanese fabricators Hitachi Astemo and Nissin occupy positions bridging precision mechanical heritage with motor control integration for hybrid architectures. Indian private specialist JaiRaj Ancillaries Private Limited anchors the cost-optimized mechanical tier serving commercial vehicle fleets in emerging markets.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Hitachi Astemo |
| Orscheln Products |
| Akebono |
| Brembo |
| JaiRaj Ancillaries Private Limited |
| Robert Bosch GmbH |
| Nissin |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Die-cast aluminum foundry utilization rates in Jiangsu and Guangdong provinces anchor cost floors for mechanical lever housings, concentrating margin pressure on suppliers without captive smelting capacity while elevating pricing power for integrated chassis manufacturers with backward aluminum supply control.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electromechanical modules with ASIL-D certification from servo-assisted mechanical assemblies and basic cable-actuated levers. Price differentiation rests on functional safety grade and volume commitment scale, with electronic configurations commanding premiums for brake-by-wire integration. Cost compression in mechanical tiers intensifies because of steel cable commodity volatility and distributor consolidation. Fleet operators in India and Brazil exhibit highest price sensitivity, while German premium OEMs prioritize performance validation over unit cost.
Supply Chain Analysis
China and Germany anchor brake lever component fabrication, with Jiangsu province concentrating die-cast aluminum housing production and Baden-Württemberg hosting precision electromechanical module assembly. Raw material dependencies include secondary aluminum ingot, glass-fiber reinforced polyamide resin, and galvanized steel wire rod. Single-source vulnerability around motor control chip supply creates exposure for electronic actuation platforms. Distribution runs through direct OEM procurement channels that bypass traditional aftermarket distributors, consolidating buyer power at chassis integrator headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as electronic-mechanical technology divergence creates distinct supplier archetypes, with brake-by-wire platform proliferation generating niche entry points for software-capable specialists outside legacy brake fabrication.
For Market Incumbents: Shield core OEM relationships by securing captive die-cast aluminum capacity in China's Yangtze River Delta and accelerating ISO 26262 ASIL-D certification for electromechanical portfolios. Electronic entrant pressure from Hitachi Astemo and Bosch demands defensive consolidation of long-term volume commitments with European and Asian automakers. Backward integration into polymer compounding capabilities reinforces margin position against composite housing displacement. For New Entrants and Emerging Players: Lead with brake-by-wire software integration for premium electric vehicle platforms in China, where autonomous parking convergence creates specification windows absent entrenched mechanical supplier relationships. India commercial vehicle electrification offers the most penetrable geography, with Bureau of Indian Standards drafting performance benchmarks that lack incumbent lock-in. Go-to-market positioning through fleet telematics partnerships bypasses traditional OEM qualification cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one chassis integrators with multi-year OEM service contracts and predictive maintenance data integration. Long-term viability over the analysis window favors electromechanical specialists with embedded software capabilities and functional safety certification infrastructure. Acquisition target archetype: mid-cap suppliers with motor control algorithm expertise and existing ECE R13-H validation. Watch electronic fitment rate inflection in Chinese electric vehicle production as demand signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces SKU complexity for tier-one suppliers serving multiple OEM brake-by-wire architectures simultaneously. |
| Battery Supply Agreement | Secures lithium-ion cell allocation for electric vehicle platforms requiring integrated electromechanical park brake modules. |
| Software-Defined Vehicle Investment | Enables autonomous parking protocol integration with sensor fusion arrays in premium Chinese electric vehicle segments. |
| Geographic Manufacturing Footprint | Localizes Jiangsu province aluminum foundry capacity to satisfy MIIT industrial policy requirements for domestic OEMs. |
| Charging Infrastructure Partnership | Creates fleet telematics integration pathways for commercial vehicle electrification mandates in India and North America. |
Study Parameters
Desk research of vehicle production databases, regulatory filing repositories, and customs trade data preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distribution heads, and fleet telematics specialists. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard 135 documentation, ECE R13-H type-approval frameworks, and MIIT GB 21670 administrative guidance. Bottom-up segment sizing triangulated against top-down OEM production forecasts across mechanical, electronic, and hybrid product architectures.
Variance-decomposition analysis isolated volume, mix, and pricing effects across the projection horizon. Segmentation dimensions modeled include product type, technology tier, installation channel, and end-user application, with additional granularity on vehicle propulsion architecture and regional production cluster. CAGRs derived from fitted trend extrapolation adjusted for technology substitution elasticities. Industry-specific inputs encompassed steel wire rod price indices, secondary aluminum smelting capacity utilization, and electronic system validation cost curves.
Forecasts assume regulatory continuity in NHTSA, ECE, and MIIT regimes; material policy shifts around functional safety scope expansion or cybersecurity protocol mandates would require re-modeling. Specific risks that could revise projections include accelerated mechanical-to-electronic substitution in emerging markets, trade restriction imposition on aluminum feedstock, and ASIL-D certification cost inflation excluding tier-two suppliers. Recalibration cycles align with material shifts in electric vehicle platform rollout schedules and fleet electrification mandate timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Camshaft Market
Powertrain
Engine Support Bar Market
Powertrain
Global Automotive Clutch Market
Powertrain
Europe Turbocharger Market
Powertrain
Automotive Camless Engine Market
Powertrain
Engines Market
Powertrain
Gear Reduction Starter Market
Powertrain
Transmission Control System Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Turbocharger Actuators Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Automotive Powertrain Components Market