
 Global Automotive Fuel Delivery and Injection Systems Market | 2026-2036
Global Automotive Fuel Delivery and Injection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Fuel Delivery and Injection Systems Market Intelligence
Steel is rebalancing component economics as manufacturers substitute aluminum in high-pressure common rail lines to cut weight without sacrificing burst pressure ratings. Robert Bosch GmbH leverages captive forging capacity in Germany to control cost curves on precision rail assemblies. DENSO Corporation anchors Asian supply networks through dedicated piezo crystal foundries in Aichi Prefecture. Continental AG competes via integrated ECU-injector pairing that tightens combustion control loops.
Automotive fuel delivery and injection systems encompass pressurized fuel circuits, metering valves, and electronic control modules engineered to atomize gasoline or diesel at pressures ranging from 3 bar in port injection to 2,500 bar in advanced common rail architectures, serving the essential function of optimizing air-fuel mixing for thermal efficiency and regulated emissions output. Direct injection systems command the largest installed base among product types, though piezo injector technology within the technology dimension captures expanding share as OEMs chase finer spray patterns and multiple injection events per cycle. Commercial trucks represent the most structurally demanding application segment, where duty cycles and load profiles sustain premium pricing for hardened components.
EPA tailpipe standards in the United States, EU Green Deal carbon benchmarks enforced by ECHA, and China's GB VI emission protocols administered by MEE collectively tighten permissible NOx and particulate thresholds, forcing hardware refreshes across every regulated jurisdiction. Tier-1 suppliers must certify injectors against divergent test cycles while maintaining single-platform economies of scale. Stakeholders should monitor how regulatory divergence between California's CARB pathway and Euro 7 implementation timelines fragments validation budgets and reshapes regional sourcing priorities.
Market Dynamics
Piezo injector architectures are compressing injection event windows from milliseconds to microseconds, forcing solenoid-dependent suppliers to retool or exit premium segments entirely.
Growth Catalysts
- PROCONVE P-8 mandates:Brazil's commercial truck fleets must upgrade injection hardware to meet tightened NOx thresholds, creating replacement demand for hardened common rail assemblies.
- Piezo crystal foundry capacity:Dedicated manufacturing clusters in Aichi Prefecture enable multi-event injection strategies that optimize diesel combustion phasing.
- Steel substitution in rail lines:High-pressure common rail manufacturers swap aluminum for advanced steel grades to cut weight while preserving 2,500 bar burst ratings.
Market Restraints
- Piezo crystal supply concentration:Sourcing of lead zirconate titanate crystals concentrates in Japanese and German specialty ceramics suppliers, exposing OEMs to single-source fragility.
- Divergent certification costs:EPA test cycles, ECHA enforcement protocols, and China's GB VI standards impose non-overlapping validation requirements on single-platform injector designs.
- Electrification substitution:Battery-electric powertrains in urban delivery segments eliminate fuel injection hardware entirely from certain duty cycles.
Strategic Opportunities
- Aftermarket service networks:Independent garages in India seek diagnostic-capable injector replacement programs as BIS emission norms tighten.
- Integrated ECU-injector pairing:Tighter combustion control loops enable software-defined injection mapping that commands premium positioning.
- Hydrogen dual-fuel retrofits:Port injection hardware adapted for hydrogen pilot ignition opens retrofit potential in existing diesel truck fleets.
Industry Challenges
- Piezo actuator calibration expertise:The shift from electromagnetic to electromechanical actuation demands physicists and materials scientists that traditional automotive engineering pipelines underproduce.
- Common rail forging capex:Precision rail assemblies require captive forging capacity that locks working capital into multi-year depreciation schedules.
- Legacy ECU integration:New injector architectures must communicate with decade-old engine control modules through protocol translation layers that introduce latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Fuel Delivery and Injection Systems Market |
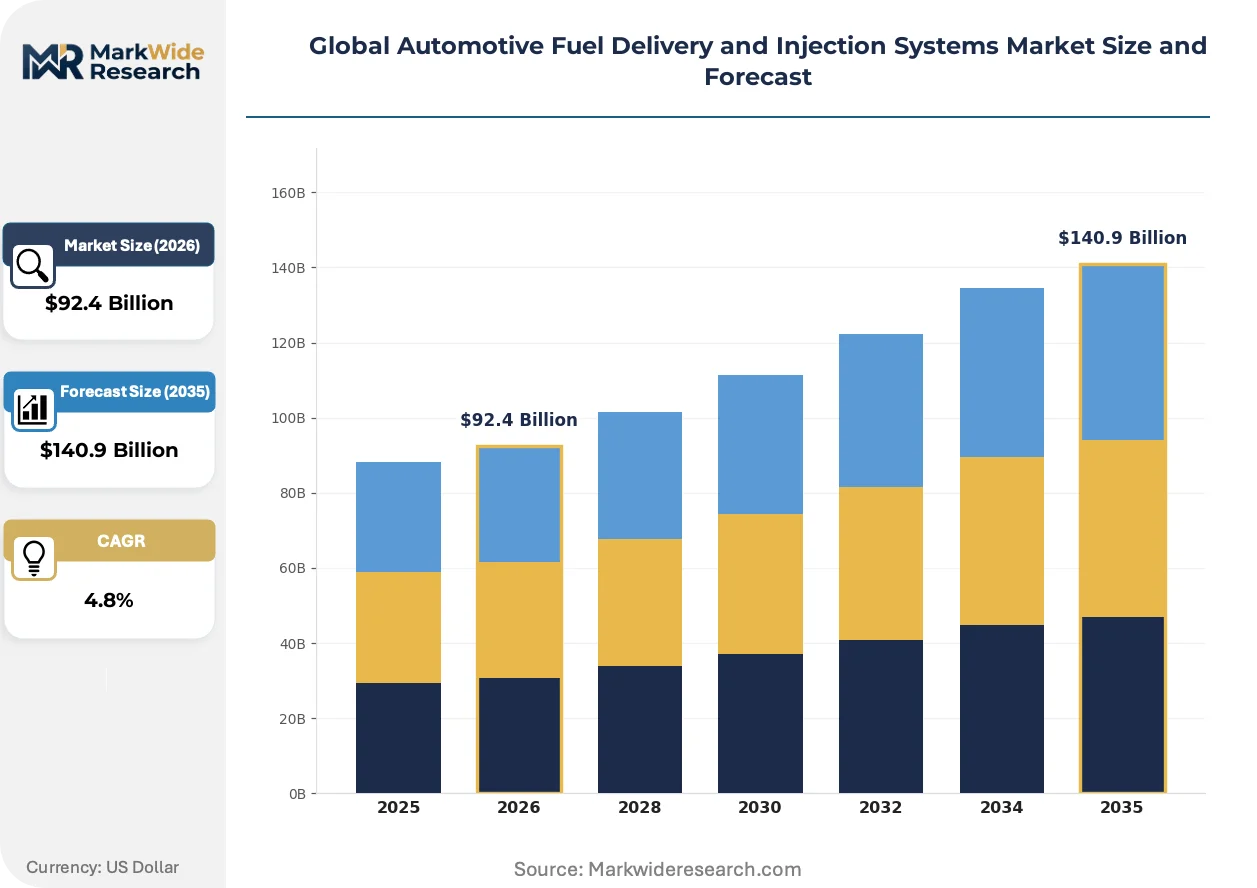
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $140.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Injection, Port Fuel Injection, Carbureted System, Common Rail System, Distributor Injection Technology: Electromechanical Injector, Piezo Injector, Solenoid Injector, Mechanical Pump, Electronic Control Unit Application: Passenger Vehicles, Commercial Trucks, Two Wheelers, Off-Highway Equipment, Specialty Vehicles End User: OEMs, Aftermarket Service Providers, Tier-1 Suppliers, Vehicle Assemblers, Maintenance Workshops |
| Companies Covered | Robert Bosch GmbH, DENSO Corporation, Continental AG, Marelli Holdings Co., Ltd., Keihin Corporation, TI Automotive, Delphi Technologies, Magna International Inc., Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Fuel Delivery and Injection Systems Market Strategic Shifts & Innovations
Hardware-software convergence in combustion control is redefining supplier value capture, with precision mechanical components now inseparable from embedded calibration algorithms.
Piezoelectric actuation enables injection events spaced within 0.1 millisecond intervals, permitting diesel engines to run partially premixed compression ignition strategies. European premium powertrain programs are overtaking solenoid architectures for their finer spray pattern control and reduced acoustic signature. This shift compresses margins for suppliers lacking captive piezo crystal supply or precision grinding capabilities.
EU Green Deal carbon benchmarks enforced by ECHA now extend to upstream manufacturing emissions, forcing Tier-1 suppliers to document foundry energy intensity and logistics carbon footprints. The industrial consequence is a bifurcation of supplier bases between those with renewable-powered forging operations and those facing carbon border adjustment exposure. German and Austrian machining clusters are responding fastest, relocating finishing operations to hydroelectric-powered facilities.
Fleet operators are unbundling injector replacement from scheduled maintenance, instead demanding condition-based swap intervals driven by real-time combustion feedback. This compresses aftermarket parts forecasting cycles and rewards suppliers with connected diagnostic platforms. The pattern is most visible in US long-haul trucking, where telematics-enabled injector health monitoring is displacing mileage-based replacement schedules.
Global Automotive Fuel Delivery and Injection Systems Market Segmentation
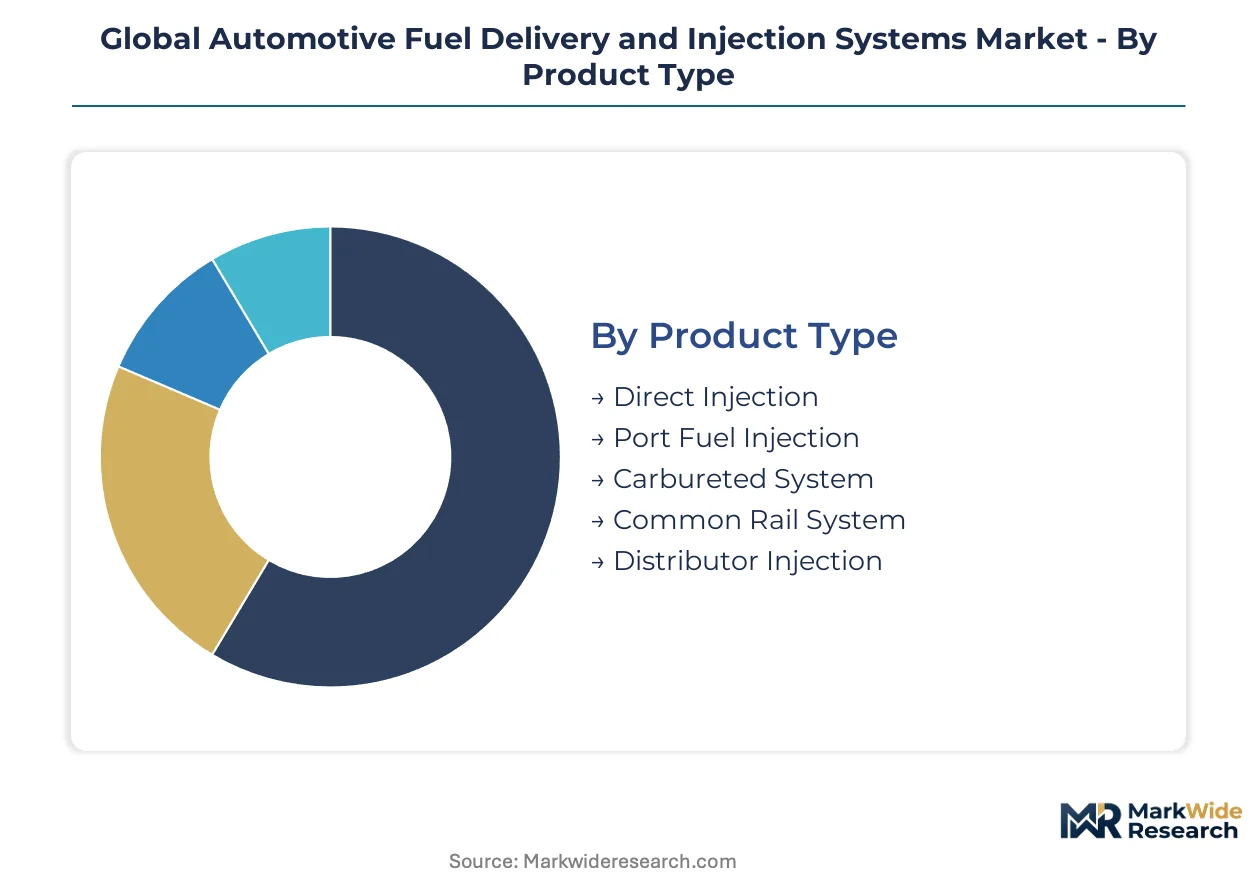
Injection system architectures vary dramatically in integration complexity, from standalone mechanical pumps to electronically embedded multi-event precision modules. Understanding where each segment sits on this integration spectrum reveals which suppliers control value capture and which face displacement risk from electrification.
Product Type:
Standalone fuel metering systems dominate legacy fleet maintenance, while embedded electronic architectures capture new vehicle production value.
- Direct Injection:High-pressure fuel circuits atomize gasoline or diesel directly into combustion chambers at pressures exceeding 200 bar. Passenger vehicle OEMs in Germany concentrate procurement here as EU Green Deal carbon benchmarks tighten thermal efficiency requirements.
- Common Rail System:Accumulator-type architectures maintain 2,000-2,500 bar pressure reservoirs enabling multiple injection events per cycle. Commercial truck fleets in Brazil upgrade to hardened rail assemblies as PROCONVE P-8 mandates enforce stricter NOx thresholds.
- Port Fuel Injection:Lower-pressure 3-5 bar systems premix fuel with intake air upstream of valves. Remains standard for cost-optimized two-wheeler powertrains across India.
- Carbureted System:Venturi-based mechanical mixing persists in aftermarket retrofits for vintage vehicle segments. Regulatory exemptions in select jurisdictions sustain residual demand.
- Distributor Injection:Rotary pump architectures meter fuel to individual cylinders via mechanical timing. Legacy commercial vehicle populations in Eastern Europe drive replacement part consumption.
Volume placements concentrate in Port Fuel Injection; the faster expansion belongs to Direct Injection.
Technology:
Actuation mechanisms separate commodity suppliers from precision component specialists, with crystal-dependent architectures commanding premium positioning.
- Piezo Injector:Lead zirconate titanate crystals expand microscopically under voltage, compressing injection windows to microseconds. Aichi Prefecture foundry clusters anchor supply for European premium powertrain programs chasing finer spray control.
- Solenoid Injector:Electromagnetic coil actuation remains cost-optimized for high-volume port injection applications. Suppliers lacking piezo calibration expertise defend position through integrated ECU pairing.
- Electromechanical Injector:Hybrid architectures blend electronic control with mechanical force multiplication. Emerging in hydrogen dual-fuel retrofit applications.
- Mechanical Pump:Cam-driven positive displacement systems persist in off-highway equipment where electronic vulnerability poses operational risk.
- Electronic Control Unit:Embedded combustion algorithms transform injector hardware into software-defined platforms. Stuttgart engineering clusters develop protocol stacks for real-time injection mapping.
Revenue concentrates in Solenoid Injector volumes; Piezo Injector applications are climbing the fastest.
Application:
Duty cycle severity determines component specification tiers, with continuous-load applications sustaining premium pricing for hardened materials.
- Commercial Trucks:Long-haul duty cycles demand forged steel common rail lines rated for 2,500 bar burst pressure. US fleet operators deploy telematics-enabled condition monitoring to unbundle injector replacement from scheduled maintenance.
- Passenger Vehicles:Stop-start transient operation favors rapid-response piezo actuation for multiple injection events. German OEM powertrain programs displace solenoid architectures fastest here.
- Two Wheelers:Cost-optimized port injection dominates emerging market two-wheeler production. BIS emission norms in India tighten hardware requirements for this volume segment.
- Off-Highway Equipment:Construction and agricultural machinery prioritize mechanical pump reliability over electronic precision. Mining applications in Australia sustain demand for distributor injection retrofits.
- Specialty Vehicles:Military and emergency vehicle segments require hardened fuel systems with electromagnetic pulse tolerance. Low volumes sustain specialty supplier margins.
Unit shipments concentrate in Passenger Vehicles; Commercial Trucks generate the steepest expansion trajectory for system value per vehicle.
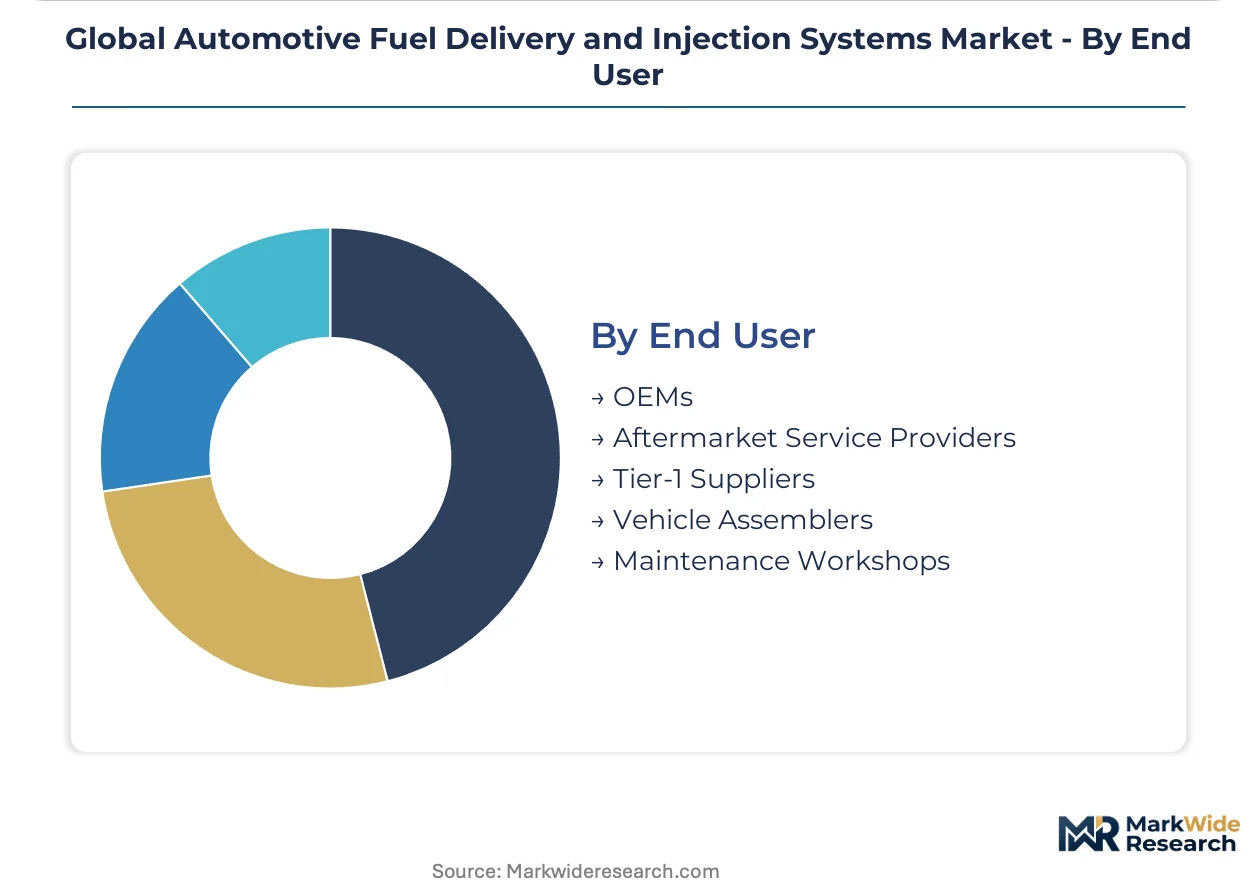
End User:
Purchasing sophistication varies from specification-driven OEM engineering teams to price-sensitive independent maintenance channels.
- OEMs:Original equipment manufacturers specify injector architectures during powertrain development cycles. Volkswagen Group and Stellantis anchor European demand for integrated ECU-injector platforms.
- Tier-1 Suppliers:Bosch and Continental purchase piezo crystals and precision-ground components for captive assembly operations. These intermediaries control forging capacity and calibration algorithm development.
- Aftermarket Service Providers:Independent garage networks in India seek diagnostic-capable injector replacement programs as emission norms tighten. Condition-based swap intervals compress forecasting cycles.
- Vehicle Assemblers:Contract manufacturers source complete fuel system modules rather than discrete components. Brazilian truck assembly plants import hardened common rail assemblies.
- Maintenance Workshops:Fleet-owned service facilities prioritize parts availability over technical specification. US long-haul operators centralize procurement through authorized dealer networks.
Procurement volume concentrates in OEMs; Aftermarket Service Providers are gaining share fastest as condition-based maintenance displaces scheduled replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial truck operators in Brazil and passenger vehicle manufacturers in Germany concentrate procurement activity, while forging clusters in Japan and engineering centers in the United States shape technology trajectories across distinct regulatory environments.
United States
Long-haul fleet operators deploy telematics-enabled condition monitoring to unbundle injector replacement from scheduled maintenance cycles. EPA tailpipe standards force hardware refreshes across heavy-duty diesel applications. Detroit and Columbus engineering clusters develop protocol stacks for real-time injection mapping software.
Germany
Volkswagen Group and Stellantis anchor European demand for integrated ECU-injector platforms in premium powertrain programs. EU Green Deal carbon benchmarks enforced by ECHA extend upstream to foundry energy intensity documentation. Stuttgart and Wolfsburg supplier ecosystems concentrate piezo calibration expertise and precision grinding capabilities.
Brazil
Commercial truck fleets upgrade injection hardware to comply with PROCONVE P-8 emission mandates enforcing tightened NOx thresholds. ANVISA coordinates with environmental regulators on industrial compliance frameworks. São Paulo and Curitiba assembly plants import hardened common rail assemblies for domestic truck production.
Japan
DENSO Corporation anchors Asian supply networks through dedicated piezo crystal foundries enabling multi-event injection strategies. METI oversees industrial standards alignment with export market requirements. Aichi Prefecture manufacturing clusters control lead zirconate titanate crystal supply for European premium powertrain programs.
India
Independent garage networks seek diagnostic-capable injector replacement programs as BIS emission norms tighten for two-wheeler and commercial vehicle segments. CDSCO maintains oversight of industrial component quality frameworks. Pune and Chennai aftermarket channels compress forecasting cycles through condition-based swap intervals.
Global Automotive Fuel Delivery and Injection Systems Market Key Industry Players
Capacity expansion dominates the current landscape as suppliers race to secure captive piezo crystal foundry output and precision forging capacity for high-pressure common rail assemblies. The vendor base stratifies between integrated system architects controlling calibration algorithms and component specialists supplying precision-ground subassemblies. Two strategic archetypes predominate: diversified industrial conglomerates with captive materials science capabilities, and focused injection system houses competing through ECU-injector integration depth. M&A activity and geographic expansion into emission-tightening emerging markets represent the dominant competitive vectors reshaping market share distribution.
Within the integrated system architect tier, Robert Bosch GmbH and Continental AG exemplify the German engineering cluster model, while DENSO Corporation represents the Asian supply network approach with dedicated manufacturing infrastructure. These three entities occupy positions spanning the full value chain from crystal sourcing through embedded software development, with each exemplifying distinct regional competitive strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| DENSO Corporation |
| Continental AG |
| Marelli Holdings Co., Ltd. |
| Keihin Corporation |
| TI Automotive |
| Delphi Technologies |
| Magna International Inc. |
| Aptiv |
| Others |
Cost & Logistics Intelligence
Captive forging capacity in Germany and dedicated piezo crystal foundries in Japan anchor supplier pricing power through backward integration into precision rail assemblies and lead zirconate titanate sourcing. This integration pattern insulates tier-1 suppliers from commodity volatility while compressing margins for component specialists lacking equivalent upstream control.
Pricing Analysis
Volume shipments concentrate in solenoid injectors for port fuel injection applications, while piezo architectures command premium positioning in direct injection programs. Three-tier pricing structure across premium, standard, and economy levels separates integrated ECU-injector platforms from standalone metering valves and aftermarket replacement units. Pricing pressure stems from electrification substitution in urban delivery segments, which eliminates hardware demand entirely from certain duty cycles. Fleet operators exhibit highest price sensitivity through telematics-enabled condition monitoring that unbundles replacement from scheduled maintenance, while OEM engineering teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Remanufacturing flows for common rail assemblies and injector cores create reverse-logistics revenue streams for authorized dealer networks in the United States and independent garage channels in India. Geographic supply concentration centers on Germany for precision forging, Japan for piezo crystal production, and China for electronic control module assembly. Raw material dependencies include advanced steel grades for high-pressure rail lines, lead zirconate titanate ceramics for actuators, and semiconductor substrates for embedded combustion algorithms. Single-source vulnerability in Japanese and German specialty ceramics suppliers exposes OEMs to lead zirconate titanate allocation constraints. Distribution runs through tier-1 supplier captive assembly operations feeding OEM platform engineering teams, with aftermarket channels compressing forecasting cycles through condition-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers controlling captive piezo crystal output and precision forging capacity, with electrification substitution and divergent regulatory certification costs forcing weaker players toward exit or niche specialization.
For Market Incumbents: To counter electrification-driven demand erosion in urban delivery segments, secure captive piezo crystal foundry capacity in Aichi Prefecture or equivalent specialty ceramics clusters, and deepen ECU-injector integration to tighten combustion control loops that software-defined platforms command. Add forging capacity in hydroelectric-powered German or Austrian machining clusters to satisfy EU Green Deal upstream carbon documentation requirements enforced by ECHA. For New Entrants and Emerging Players: Aftermarket service providers in India offer the most penetrable entry channel, where BIS emission norm tightening for two-wheeler and commercial vehicle segments creates diagnostic-capable injector replacement demand that incumbent tier-1 suppliers underserve. Target condition-based swap interval compression through connected diagnostic platforms that telematics-enabled fleet operators increasingly demand. Partner with independent garage networks seeking technical training and parts availability guarantees rather than competing for OEM platform engineering specifications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking captive materials science capabilities, with strategic buyers valuing piezo calibration expertise and precision grinding infrastructure that traditional automotive engineering pipelines underproduce. Long-term viability favors suppliers with renewable-powered forging operations and embedded algorithm development capacity, as carbon border adjustment exposure and hardware-software convergence reshape competitive positioning. Monitor PROCONVE P-8 implementation pace in Brazil and Euro 7 timeline divergence from California CARB pathways for early signals of regional sourcing priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Piezo Crystal Foundry Capacity Expansion | DENSO Corporation's Aichi Prefecture clusters anchor multi-event injection supply for European premium powertrain programs. |
| Integrated ECU-Injector Platform Development | Bosch and Continental tighten combustion control loops that software-defined injection mapping commands in Stuttgart engineering clusters. |
| Steel Substitution in Common Rail Lines | Advanced steel grades cut weight while preserving 2,500 bar burst ratings for commercial truck fleet upgrades in Brazil. |
| Condition-Based Aftermarket Service Networks | Telematics-enabled injector health monitoring displaces mileage-based replacement schedules for US long-haul fleet operators. |
| Hydrogen Dual-Fuel Retrofit Adaptation | Port injection hardware modified for hydrogen pilot ignition opens retrofit potential in existing diesel truck fleets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which analysts cross-referenced with primary interviews involving Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. EPA tailpipe standard documentation, EU ECHA enforcement protocols, China's GB VI submissions to MEE, and Brazil's PROCONVE P-8 compliance frameworks supplemented vehicle production databases and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market reconciliation.
Data-stream reconciliation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions generated volume and value outputs. CAGRs derived from segment-level growth trajectory analysis incorporating injection technology substitution rates, emission regulation implementation timelines, and electrification penetration assumptions across commercial truck, passenger vehicle, and two-wheeler duty cycles. Piezo injector displacement curves and common rail hardware refresh cycles informed projection horizon modeling.
Caveats apply where electrification substitution acceleration, piezo crystal supply disruption, or regulatory divergence between California CARB and Euro 7 implementation timelines could materially shift the outlook. Practitioners should monitor fleet telematics adoption rates and carbon border adjustment mechanism enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Camshaft Market
Powertrain
Transmission Sales Market
Powertrain
Global Automotive Tappet Market
Powertrain
Reciprocating Engine Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
Clutch Friction Plate Market
Powertrain
Timing Belt Kits Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
CNG Powertrain Market