
 Timing Belt Market | 2026-2036
Timing Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Timing Belt Market Intelligence
Aftermarket service revenue is rewriting margin capture across the timing belt value chain. Gates Corporation leverages its captive distribution network to sustain replacement-cycle visibility in North American fleets. Continental AG anchors its position through backward integration into rubber compounding and cord fabrication. Bando Chemical Industries dominates Asian OE supply relationships with dedicated manufacturing scale in Japan and Thailand.
A timing belt is a toothed, synchronous drive component fabricated from neoprene or hydrogenated nitrile rubber with fiberglass or aramid tensile cords, engineered to maintain precise crankshaft-to-camshaft phase alignment across temperature extremes from minus forty to one hundred twenty degrees Celsius. The automotive end-user segment leads absolute volume as internal combustion and hybrid powertrains require belt-driven valve train synchronization, while polyurethane material formulations represent the fastest-growing structural category due to extended service intervals and reduced stretch under load. Small and medium size classes concentrate OEM demand, though custom dimensions command premium positioning in racing and industrial retrofit applications.
EPA fuel economy mandates and Euro 7 emissions frameworks from the European Commission are forcing narrower tooth-profile tolerances and lower-friction surface treatments across supplier portfolios. Japan's Ministry of Economy, Trade and Industry (METI) promotes domestic advanced-material belt standards through JIS certification pathways that shape export competitiveness. Stakeholders must monitor regulatory divergence between combustion-centric and electrified powertrain test cycles, as belt-in-oil architectures and decoupled cam phasing systems redefine component specifications and qualification timelines.
Market Dynamics
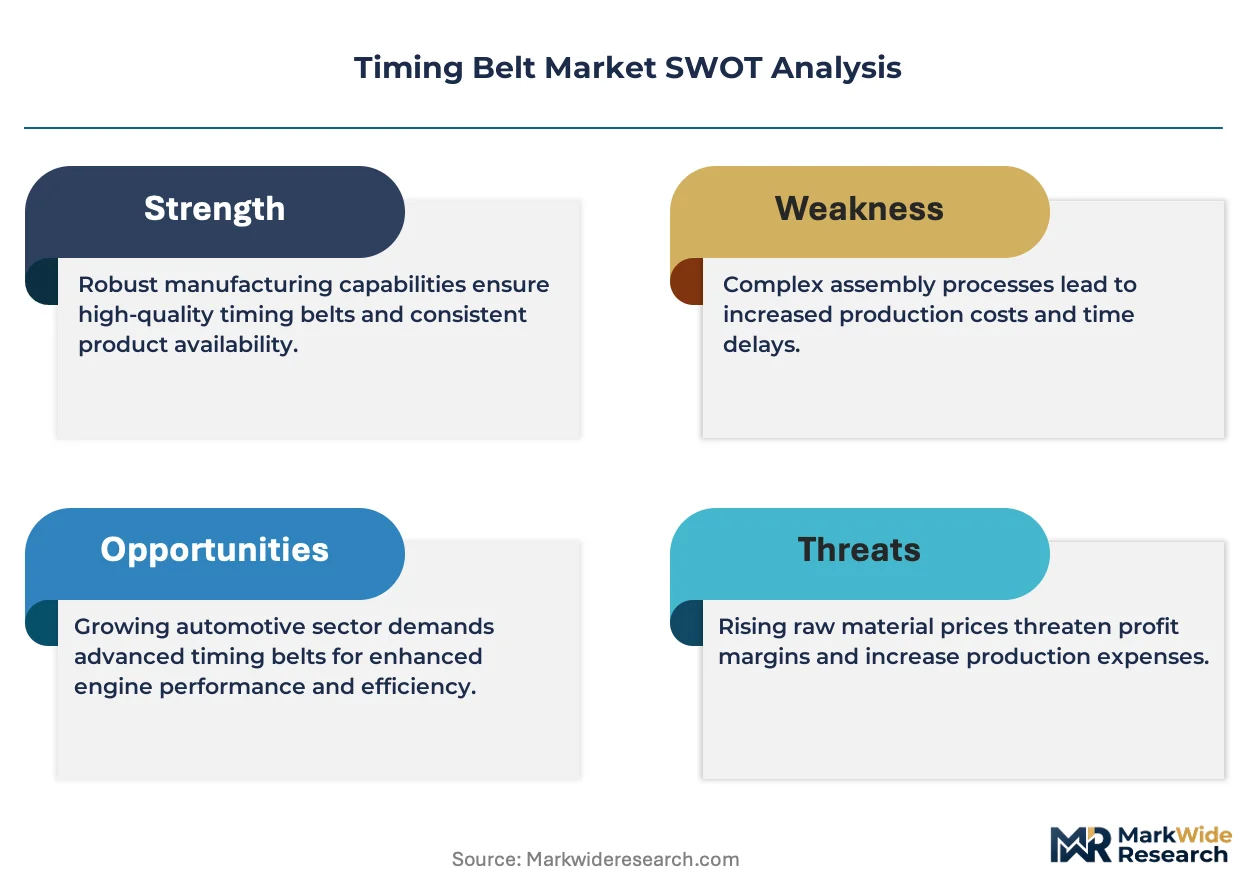
Powertrain electrification is fragmenting synchronous drive demand as hybrid architectures retain belt-driven valve trains while full-electric platforms eliminate them entirely, forcing suppliers to engineer dual-competency portfolios.
Growth Catalysts
- Euro 7 Emissions Framework:Tightened particulate and NOx limits mandate precision cam phasing that only advanced synchronous belts can deliver, expanding specification requirements across European OEM sourcing.
- Hybrid Powertrain Proliferation:Belt-in-oil architectures for Atkinson-cycle engines require specialized hydrogenated nitrile rubber formulations with enhanced thermal stability.
- Thailand Manufacturing Concentration:Dedicated molding capacity serving Japanese transplants anchors regional supply security for Southeast Asian vehicle assembly.
Market Restraints
- Aramid Cord Supply Concentration:DuPont and Teijin control over eighty percent of high-tenacity fiber output, creating input cost volatility when aerospace demand spikes.
- Full-Electric Powertrain Substitution:Battery-electric vehicles eliminate mechanical valve trains entirely, eroding addressable market in premium passenger segments.
- REACH Chemical Restrictions:ECHA scrutiny of short-chain chlorinated paraffins in rubber processing aids forces reformulation investments without performance guarantees.
Strategic Opportunities
- Indian Commercial Vehicle Fleet:BS-VI Phase II implementation and delayed replacement cycles create aftermarket volume expansion for synchronous belt retrofits in aging diesel powertrains.
- Industrial Robotics Integration:Servo-driven automation lines require precision timing belts for positioning accuracy, opening non-automotive demand verticals.
- Japan METI Advanced Material Standards:JIS-certified high-modulus belts command export premiums into ASEAN assembly plants seeking quality differentiation.
Industry Challenges
- Belt-in-Oil Certification Timelines:OEM validation protocols for submerged synchronous drives extend eighteen to thirty-six months, compressing product lifecycle returns.
- Compound Formulation Talent Scarcity:Hydrogenated nitrile rubber expertise concentrates among retiring Japanese compounders, constraining R&D velocity at newer entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timing Belt Market |
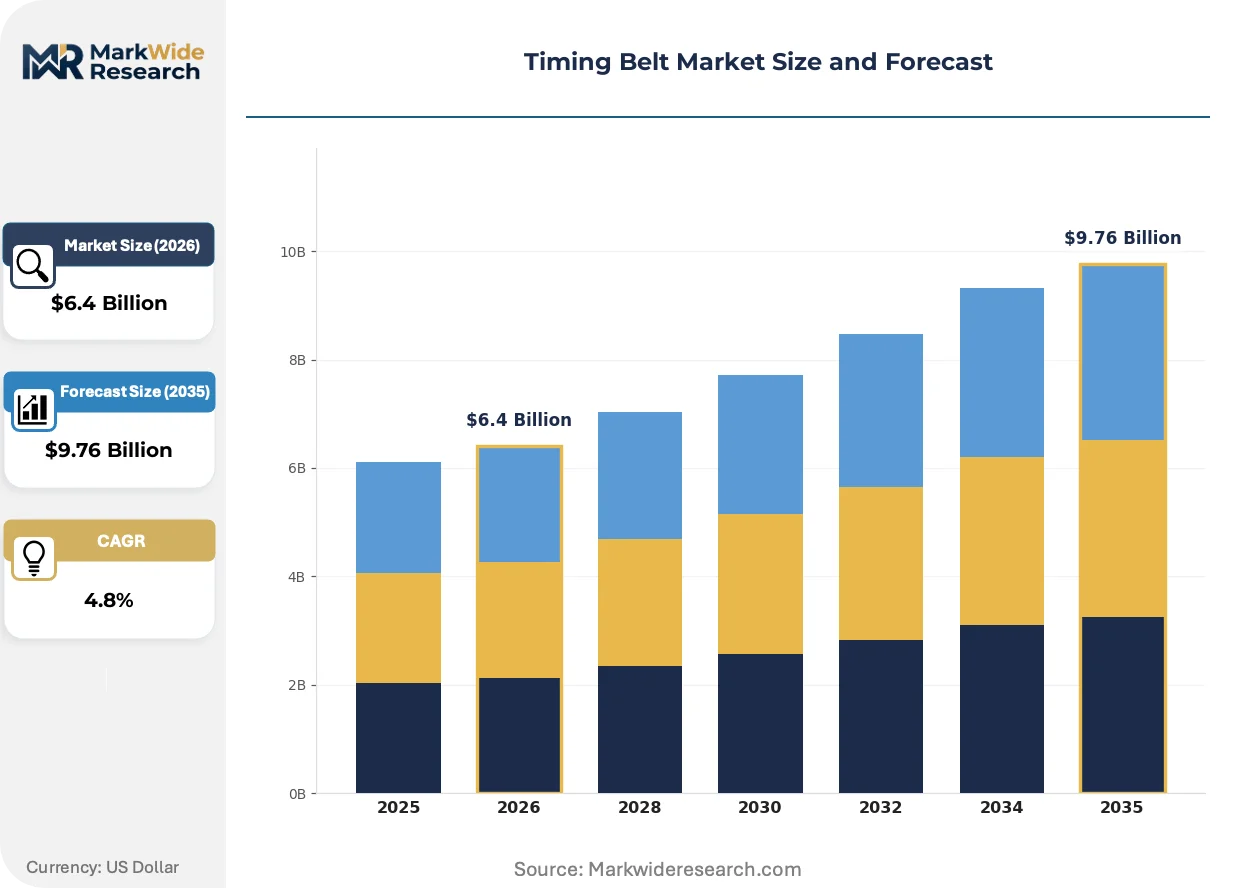
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Timing Belt, Timing Chain, Tensioner, Camshaft Material: Rubber, Polyurethane, Fiber Reinforced, Steel End User: Automotive, Industrial Machinery, Electrical Equipment, Marine Size: Small, Medium, Large, Custom |
| Companies Covered | Gates Corporation, Continental AG, Dayco LLC, Bando Chemical Industries, Mitsuboshi Belting Ltd., Tsubakimoto Chain Co., SKF Group, The Carlstar Group, ContiTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timing Belt Market Strategic Shifts & Innovations
Digital twin simulation is compressing development cycles while regulatory test protocols diverge between combustion-centric and electrified powertrain certification frameworks.
Polyurethane synchronous belt formulations with carbon fiber tensile members are virtualizing traditional neoprene-glass constructions in high-performance applications. Racing teams and premium German OEMs specify these compounds for extended service intervals exceeding two hundred thousand kilometers. This material shift is virtualizing supplier qualification hierarchies as compound expertise displaces legacy molding scale advantages.
EPA Corporate Average Fuel Economy test-cycle updates now incorporate cold-start phase optimization, mandating lower-friction tooth profiles that reduce parasitic losses during engine warm-up. Belt suppliers must validate surface treatments across expanded temperature envelopes. North American OEM procurement teams are accelerating qualification of plasma-etched tooth geometries to meet these tightened tolerances.
Fleet maintenance departments now unbundle timing belt replacement from bundled service packages, creating direct procurement relationships with Tier-1 distributors. Independent repair chains in Germany and California negotiate specification-grade contracts that bypass traditional dealer networks. This channel fragmentation concentrates volume with distributors offering real-time inventory visibility and VIN-matched kitting services.
Timing Belt Market Segmentation
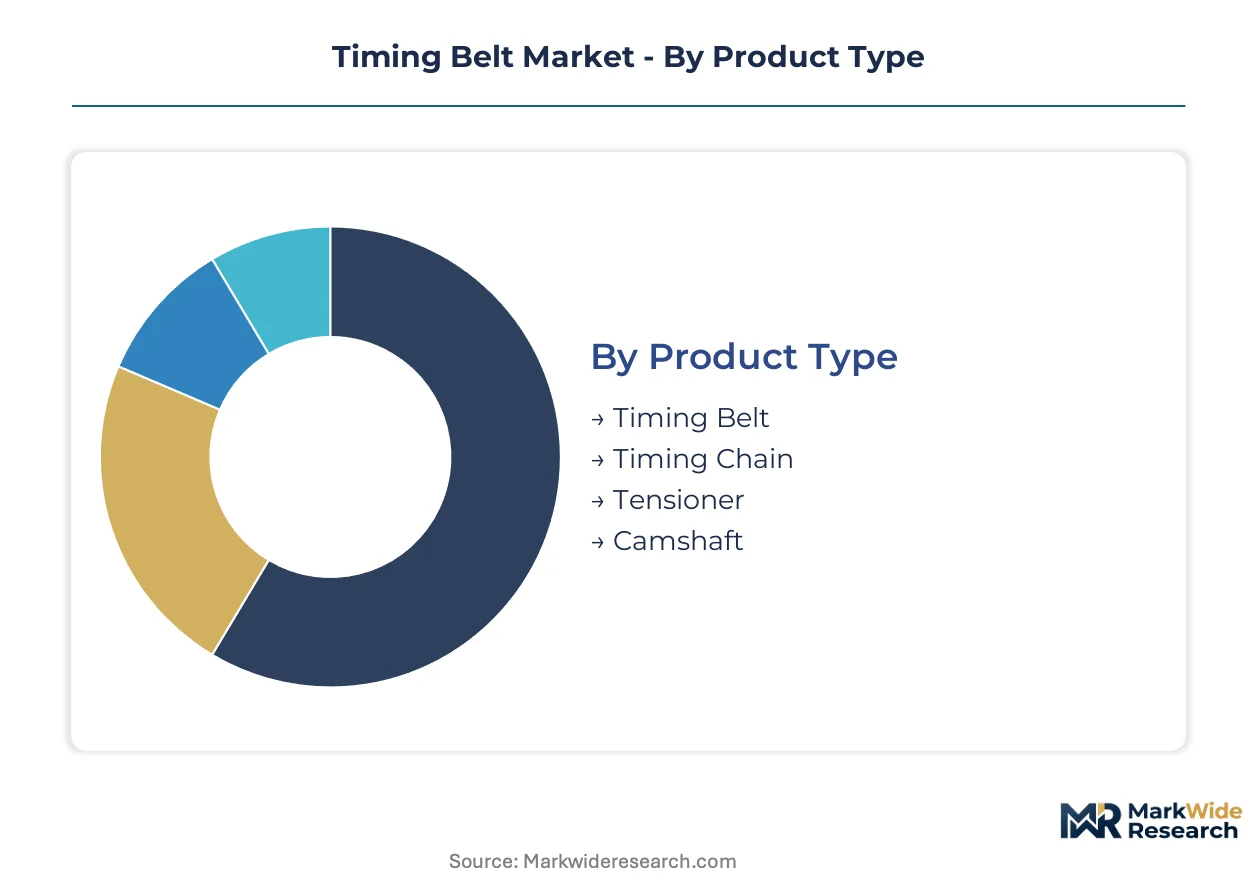
Segmentation in the timing belt market reveals how material science, powertrain architecture, and duty-cycle severity reshape supplier portfolios. Each dimension carries distinct margin profiles and qualification barriers that determine competitive positioning across OEM and aftermarket channels.
Product Type:
The use-case spectrum spans precision engine synchronization through ancillary drive management, with each component type serving distinct thermal and mechanical duty cycles.
- Timing Belt:Toothed synchronous drives fabricated from neoprene or hydrogenated nitrile rubber with fiberglass tensile cords maintain crankshaft-to-camshaft phase alignment. Automotive OEM demand concentrates in hybrid powertrains where belt-in-oil architectures tolerate extended immersion intervals.
- Timing Chain:Roller-link metal constructions deliver infinite service life in heavy-duty diesel and high-performance gasoline applications. German and Japanese OEMs specify these for premium passenger segments where maintenance-free operation justifies higher unit costs.
- Tensioner:Hydraulic or spring-loaded idler assemblies preserve optimal belt preload across thermal expansion cycles. Aftermarket replacement volume climbs as deferred maintenance in aging fleets accelerates pulley bearing fatigue.
- Camshaft:Precision-ground alloy shafts with integrated drive sprockets complete valve train synchronization systems. Racing and performance retrofit applications command premium positioning for custom grind profiles.
Established volume favors timing belts; emerging adoption favors tensioners as fleet maintenance intervals compress.
Material:
Cost tier differentiation separates commodity rubber formulations from advanced polymer compounds with certified thermal stability.
- Rubber:Neoprene and hydrogenated nitrile elastomers dominate OE supply through proven fatigue resistance across minus forty to one hundred twenty degrees Celsius operating envelopes. EPA cold-start friction mandates are forcing surface treatment investments that narrow margin capture at volume tiers.
- Polyurethane:Thermoplastic elastomers with carbon fiber tensile members extend service intervals beyond two hundred thousand kilometers. Premium German OEMs and racing teams specify these compounds for reduced stretch under load and extended replacement cycles.
- Fiber Reinforced:Aramid or glass cord constructions embedded in rubber matrices enhance tensile modulus for high-torque industrial drives. DuPont and Teijin fiber supply concentration creates input cost volatility when aerospace demand spikes.
- Steel:Link-plate and roller architectures eliminate elastomer aging in permanent lubrication environments. Heavy commercial vehicle powertrains in India and Southeast Asia specify these for million-kilometer durability targets.
Volume manufacturing centers on rubber; specification-grade procurement is climbing fastest for polyurethane.
End User:
Customer type segmentation isolates automotive qualification intensity from industrial lifecycle economics.
- Automotive:Internal combustion and hybrid powertrains require synchronous belt-driven valve train synchronization with validated eighteen-to-thirty-six-month OEM certification timelines. Euro 7 emissions frameworks mandate precision cam phasing that expands specification requirements across European sourcing.
- Industrial Machinery:Conveyor systems, packaging equipment, and machine tools demand standardized pitch profiles with rapid aftermarket availability. Servo-driven automation lines require positioning accuracy that opens precision timing belt demand outside automotive verticals.
- Electrical Equipment:Generator and motor drive applications specify synchronous belts for constant velocity transmission between rotating assemblies. NEMA and IEC frame standardization enables cross-manufacturer interchangeability that commoditizes margin capture.
- Marine:Salt-resistant neoprene formulations with stainless steel hardware tolerate corrosive environments in outboard and inboard propulsion systems. Coastal manufacturing clusters in Thailand and Japan anchor regional supply security for this corrosion-critical segment.
Automotive commands absolute revenue concentration; industrial machinery is expanding most quickly as automation adoption accelerates.
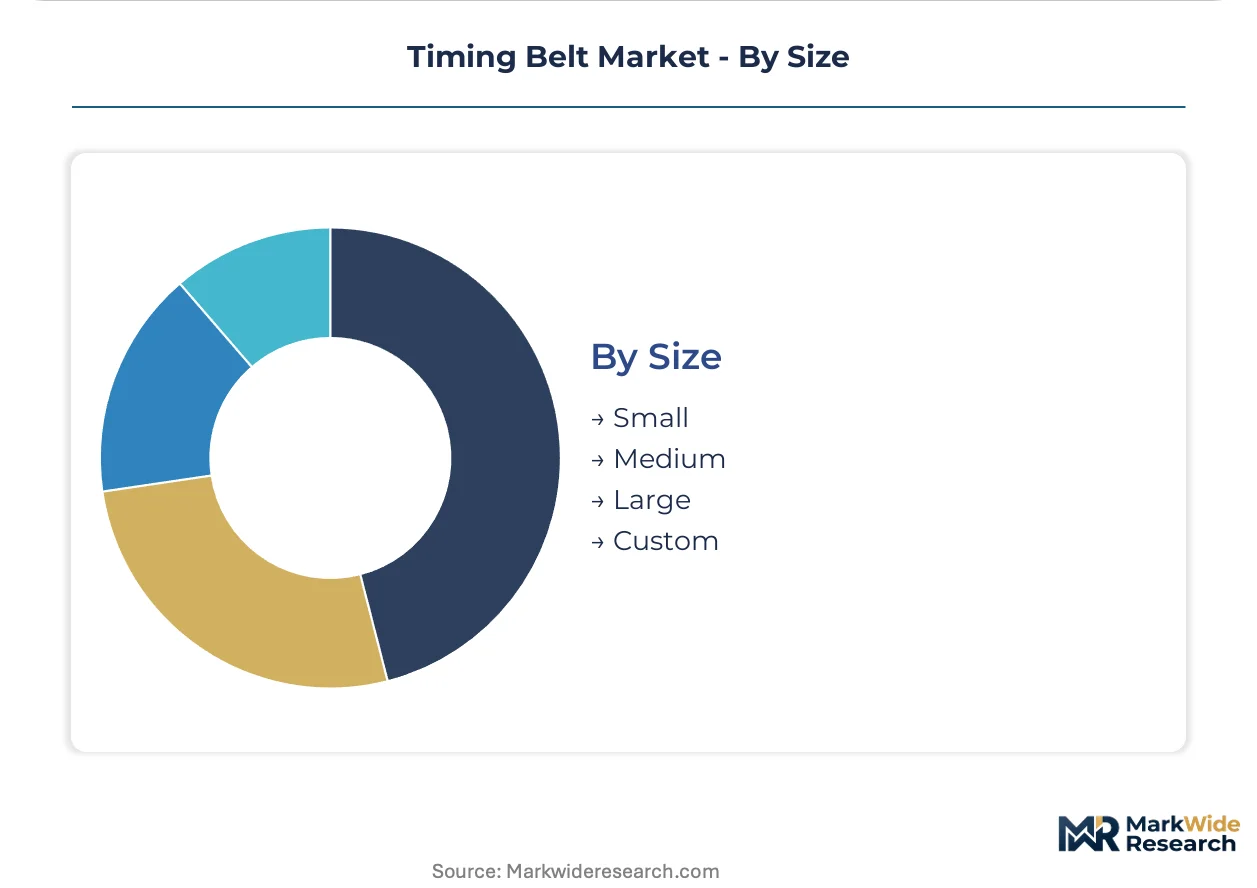
Size:
Supply concentration in precision molding capacity shapes availability across standardized and custom dimensional tiers.
- Small:Compact synchronous profiles serve motorcycle, small engine, and auxiliary automotive drives. Japanese and Thai manufacturing plants concentrate dedicated molding lines for high-volume OE supply to regional vehicle assembly.
- Medium:Passenger car and light commercial vehicle engine bays specify pitch lengths and widths that dominate absolute unit volume. China, Germany, and Japan concentrate the bulk of precision molding capacity for this core dimensional tier.
- Large:Heavy-duty diesel and industrial power transmission applications require reinforced constructions with expanded tooth engagement surfaces. Aramid cord supply constraints limit production scalability when aerospace fiber demand surges.
- Custom:Non-standard pitch, width, and tooth profile combinations serve racing, prototype, and specialized industrial retrofit applications. Extended lead times and engineering charges support premium margin positioning that offsets low volume throughput.
Medium dimensions capture established manufacturing scale; custom specifications yield the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes timing belts primarily for new vehicle assembly, while Germany and Japan concentrate on replacement-grade specification and belt-in-oil certification. The United States splits demand between OE supply to transplant assembly plants and aftermarket fleet maintenance.
China
Domestic automakers and joint ventures with German and Japanese partners drive OE volume for synchronous belt systems. MIIT fuel economy mandates under GB standards tighten tolerance requirements for cam phasing precision. Yangtze River Delta molding clusters in Shanghai and Jiangsu provinces supply precision tooth profiles to regional vehicle assembly hubs.
Germany
Premium OEM sourcing for belt-in-oil architectures and extended service interval specifications anchors demand. KBA type-approval protocols for Euro 7 emissions compliance extend validation timelines for new synchronous drive submissions. Stuttgart and Munich engineering centers coordinate Tier-1 supplier qualification for hybrid powertrain programs.
United States
Transplant assembly plants operated by Japanese and German OEMs sustain OE demand alongside independent aftermarket fleet channels. EPA Corporate Average Fuel Economy cold-start phase optimization mandates lower-friction tooth profile investments. Michigan and Ohio distribution hubs consolidate inventory for North American replacement cycle visibility.
Japan
METI promotes JIS-certified advanced-material belt standards that shape export competitiveness into ASEAN assembly plants. Domestic hybrid powertrain production retains belt-driven valve train architectures despite full-electric proliferation. Kanto region precision molding capacity serves both captive OE supply and regional aftermarket distribution.
Thailand
Japanese transplant assembly plants anchor regional demand for small and medium synchronous belt specifications serving Southeast Asian vehicle exports. Board of Investment incentives for automotive component manufacturing attract dedicated molding capacity investment. Eastern Seaboard industrial zones concentrate rubber compounding and cord fabrication for regional supply security.
Timing Belt Market Key Industry Players
Capability concentration sits with compound formulation specialists; scale advantage sits with integrated rubber processors. The market structures around three tiers: multinational integrated suppliers with captive distribution networks, regional molding specialists serving single OEM relationships, and aftermarket distributors unbundling service packages. Consolidation pressure runs through backward integration into aramid cord supply and forward integration into VIN-matched kitting services.
Among multinational integrated suppliers, Gates Corporation exemplifies the distribution-captive archetype, while Continental AG occupies a position emphasizing upstream material control. Bando Chemical Industries anchors the Asia-Pacific regional specialist tier. These three represent distinct competitive vectors: North American aftermarket channel dominance, European compound integration, and Japanese-Thai manufacturing scale.
| Leading Market Players |
|---|
| Gates Corporation |
| Continental AG |
| Dayco LLC |
| Bando Chemical Industries |
| Mitsuboshi Belting Ltd. |
| Tsubakimoto Chain Co. |
| SKF Group |
| The Carlstar Group |
| ContiTech |
| Others |
Cost & Logistics Intelligence
Aramid cord supply concentration between DuPont and Teijin anchors input cost volatility that propagates through rubber compounding tiers into OEM contract negotiations. This upstream duopoly forces timing belt manufacturers to absorb fiber price spikes or renegotiate long-term offtake terms with European and Japanese automakers.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement, with annual price reviews tied to rubber and cord commodity indices. Price differentiation rests on JIS certification grade and volume scale, with uncertified aftermarket tiers facing cost compression from unbundled fleet maintenance programs. Pricing pressure intensifies as battery-electric vehicle proliferation erodes addressable volume in premium passenger segments. Aftermarket distributors exhibit highest price sensitivity, while German OEMs prioritize qualification grade over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese OEMs strain working capital for Thailand-based molding specialists serving regional transplant assembly. Supply draws from China, Germany, and Japan for precision tooth profiles, with hydrogenated nitrile rubber and fiberglass cord as critical inputs. Single-source vulnerability concentrates in DuPont-Teijin aramid fiber supply when aerospace demand surges. Distribution runs through captive Tier-1 networks and independent aftermarket distributors offering VIN-matched kitting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Timing belt incumbents must defend against chain-to-belt substitution in heavy-duty commercial segments and full-electric powertrain elimination in passenger categories. The strategic imperative centers on preserving specification-grade positioning as powertrain architectures fragment.
For Market Incumbents: Build formulation expertise moats around hydrogenated nitrile rubber compounding as retiring Japanese compounders constrain R&D velocity at newer entrants. Deepen backward integration into cord fabrication to offset DuPont-Teijin supply concentration. Secure belt-in-oil certification pipelines with German OEMs before Euro 7 validation timelines compress product lifecycle returns.
For New Entrants and Emerging Players: Establish a beachhead in Indian commercial vehicle aftermarket retrofits where BS-VI Phase II implementation and delayed replacement cycles create synchronous belt demand in aging diesel powertrains. Target industrial robotics servo-drive applications outside automotive verticals. Lead with real-time inventory visibility and VIN-matched kitting services to bypass entrenched dealer networks.
For Investors and Strategic Acquirers: Capital is best deployed toward compound-specialist mid-caps with JIS-certified export pathways into ASEAN assembly plants. Long-term viability hinges on hybrid powertrain persistence through the next decade as full-electric adoption plateaus in commercial segments. Monitor battery-electric vehicle penetration rates in premium passenger categories as the critical demand erosion signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cord Fabrication | Reduces aramid fiber cost volatility exposure from DuPont-Teijin supply concentration. |
| Belt-in-Oil Certification Investment | Secures Euro 7-compliant positioning with German OEMs for hybrid Atkinson-cycle programs. |
| Industrial Robotics Vertical Expansion | Diversifies revenue beyond automotive as servo automation demand accelerates precision timing belt adoption. |
| JIS Certification Pathway Completion | Unlocks export premiums into ASEAN assembly plants seeking quality differentiation from Japanese standards. |
| Aftermarket Distribution Channel Control | Captures unbundled fleet maintenance procurement through VIN-matched kitting and real-time inventory systems. |
Research Approach
Operator-level perspectives from Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and rubber compounding specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, customs and trade flow records, SEC filings from listed suppliers, and JIS certification registries. Bottom-up volume builds across material-grade and end-use segments triangulated against top-down macroeconomic and regulatory scenario analysis.
Scenario-bracketing around powertrain electrification pace and emissions regulatory stringency shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material formulation, end-user vertical, and dimensional size class, with propulsion architecture as an automotive-specific overlay. CAGRs derived from elasticity-adjusted volume projections incorporating replacement cycle dynamics and content-per-vehicle shifts. Forecast inputs included hybrid powertrain production schedules, Euro 7 implementation timelines, and aramid fiber supply allocation patterns.
Sensitivities concentrate around battery-electric vehicle substitution rates and belt-in-oil certification timeline extensions. Forecasts reflect documented assumptions on regulatory implementation and technology adoption curves. Macroeconomic contraction, regulatory delay, or breakthrough chain durability technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
EV Powertrain Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Fuel Injection Systems Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Natural Gas Engines Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Small Gas Engine Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Global Automotive Engine and Engine Mounts Market
Powertrain
Fuel Pumps Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Global Automotive Torque Vectoring Market