
 Brazil Automotive Actuators Market | 2026-2036
Brazil Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Actuators Market Outlook
INMETRO certification under Ordinance 445/2021 is redrawing supplier eligibility for Brazil's automotive component sector. Robert Bosch GmbH leverages its Campinas engineering center to sustain local calibration capabilities for electronic actuators. Continental AG anchors its position through captive testing laboratories in Sorocaba that validate actuator response under tropical humidity cycles. BorgWarner Inc competes by specializing in turbocharger electronic actuators tuned for flex-fuel engine maps.
Automotive actuators are electromechanical or fluid-power devices that convert control signals into precise mechanical motion, typically operating at voltage ranges from 12V to 48V in passenger and commercial vehicle architectures. Their primary purpose is to execute real-time adjustments in powertrain, chassis, and body systems based on sensor feedback and ECU commands. Electronic actuators lead product type revenue due to their integration with engine management and brake-by-wire platforms, while hydraulic actuators retain structural importance in heavy-duty transmission and steering applications where force density requirements exceed electric motor limits. Smart actuation technology is expanding fastest among technology segments as OEMs demand self-diagnostic capability and predictive maintenance interfaces.
ANVISA governs material safety declarations for actuator polymers and lubricants in contact with cabin air systems, while INMETRO enforces energy efficiency labeling that affects auxiliary actuator selection in climate control modules. The Brazilian Institute of Metrology (INMETRO) also administers OCD certification requirements that foreign suppliers must satisfy before accessing the Mercosur automotive supply chain. Stakeholders must monitor how PROCONVE emission stage transitions will force recalibration of throttle and EGR actuator control algorithms.
Market Dynamics
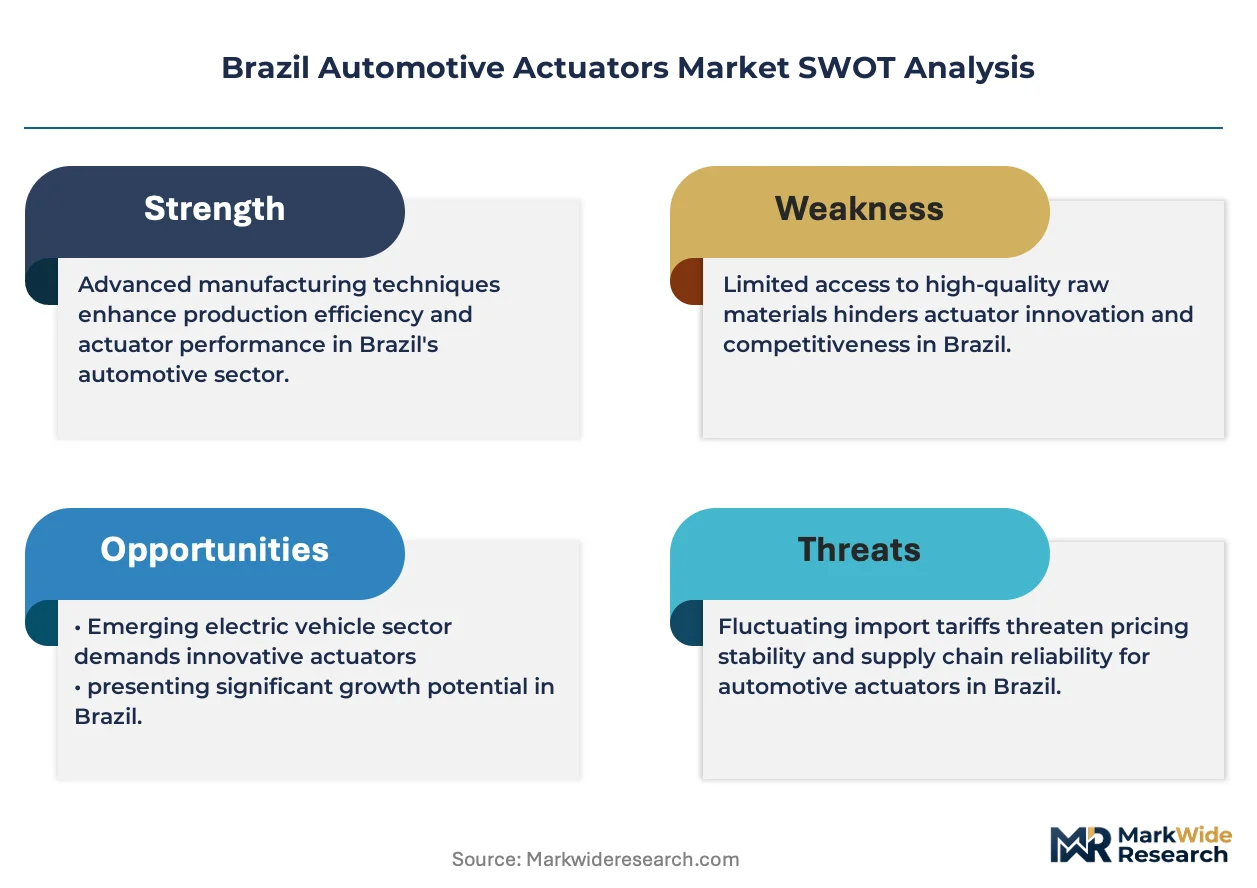
The Brazilian automotive actuators market is being fundamentally restructured by INMETRO's Ordinance 445/2021 certification regime, which is systematically disqualifying non-compliant suppliers from Mercosur supply chains while elevating local calibration capabilities as a competitive differentiator.
Growth Catalysts
- PROCONVE Emission Stages:Federal emission mandates are forcing recalibration of throttle and EGR actuator control algorithms, creating replacement demand across São Paulo's light commercial vehicle fleets.
- Flex-Fuel Engine Proliferation:Brazil's ethanol-gasoline flex technology requires specialized electronic actuators with real-time fuel map adaptation, differentiating local engineering requirements from global templates.
- ANVISA-Mercosur Alignment:Material safety declarations for cabin-contact polymers are tightening traceability standards, favoring suppliers with captive polymer validation capabilities.
Market Restraints
- Import Dependency for Semiconductors:Electronic actuator production relies on imported power management chips, exposing margins to dollar volatility and Asian foundry concentration.
- Oligopolistic Testing Infrastructure:INMETRO-certified tropical humidity validation is concentrated in Sorocaba and Campinas industrial clusters, creating bottleneck risk for new entrants.
- Hydraulic Actuator Substitution Ceiling:Heavy-duty transmission applications exceed 48V electric motor force density limits, locking hydraulic architectures into structural cost positions.
Strategic Opportunities
- Minas Gerais Industrial Corridor:Underpenetrated actuator assembly capacity in Betim and Contagem offers logistics proximity to southeastern OEM stamping plants.
- Smart Actuation Interfaces:Predictive maintenance protocols and self-diagnostic firmware represent white space for tier suppliers to differentiate beyond commodity motion control.
- Climate Control Module Integration:Energy efficiency labeling requirements are creating bundled specification opportunities for auxiliary actuator suppliers with HVAC system expertise.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time control algorithm development for flex-fuel engine maps requires specialized automotive software engineers concentrated in São Paulo state.
- OCD Certification Timelines:Foreign suppliers face 18-24 month INMETRO approval cycles that compress product launch windows relative to domestic competitors.
- Legacy Powertrain Integration:Brake-by-wire and steer-by-wire actuator retrofits must maintain backward compatibility with CAN bus architectures dating to PROCONVE L4 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Actuators Market |
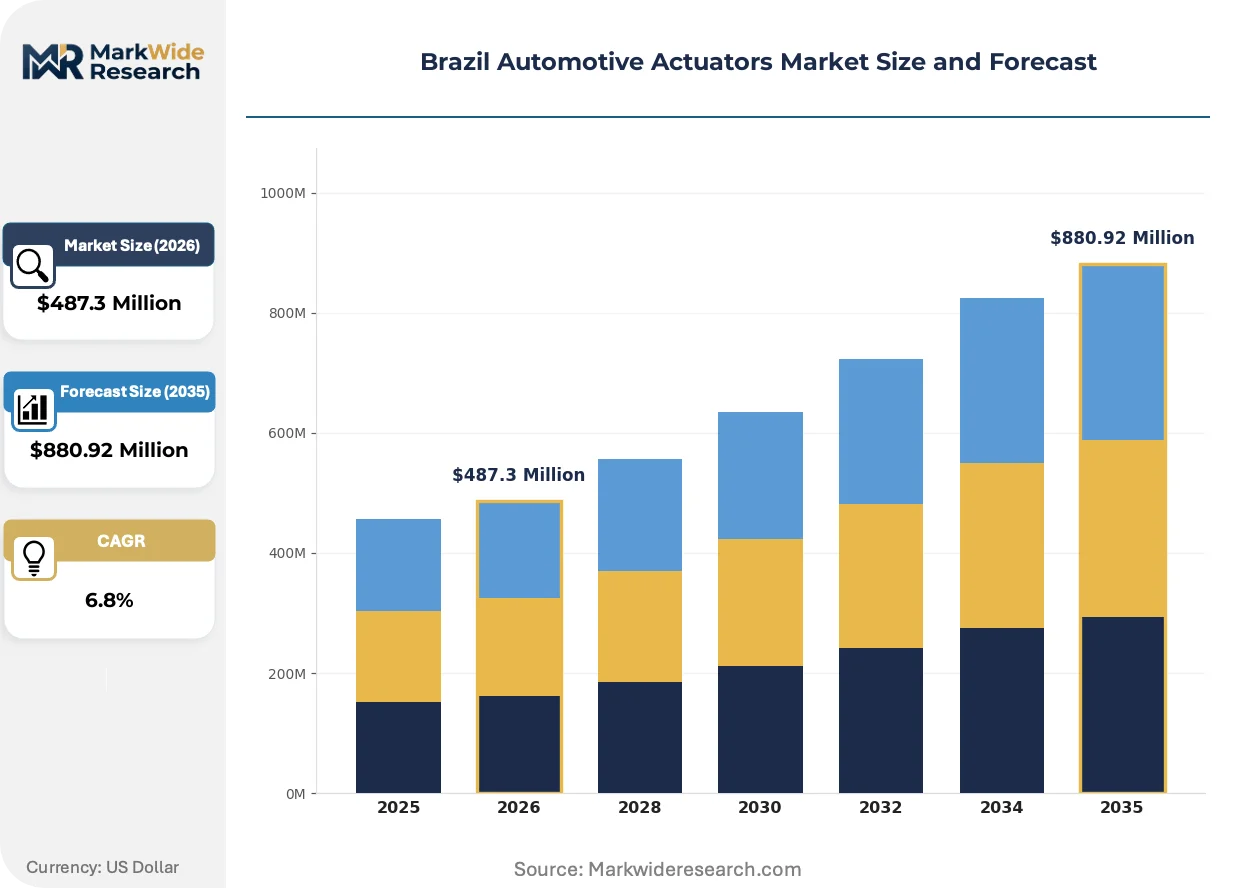
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators Application: Steering Control, Brake Systems, Engine Control, Transmission Systems End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Smart Actuation, Advanced Sensors, Wireless Control, Impact Sensors |
| Companies Covered | Wabco Holdings Inc, BorgWarner Inc, Continental AG, Johnson Electric, Denso Corporation, Robert Bosch GmbH, Sonceboz SA, CTS Corporation, Hella KGaA Hueck & Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Actuators Market Strategic Shifts
Electrification of vehicle architectures is compressing actuator voltage standards while expanding functional integration requirements, with Brazilian OEMs specifically demanding tropical-climate validation protocols that exceed baseline international specifications.
Brushless DC motor actuators with integrated position sensing are supplanting brushed motor designs in throttle body applications. São Paulo-based OEM powertrain divisions are adopting these architectures for flex-fuel engine programs. The shift is compressing supplier margins on legacy brushed motor inventories while rewarding firmware-capable tier ones.
INMETRO's OCD certification framework under Ordinance 445/2021 is mandating tropical humidity cycle validation for all electronic actuator imports. Foreign suppliers without captive Brazilian testing laboratories face extended approval timelines. Domestic engineering centers with Sorocaba-based validation capabilities are capturing specification influence earlier in OEM development cycles.
Fleet procurement departments are consolidating actuator sourcing decisions at the OEM group level rather than delegating to individual plant engineers. Tier-one suppliers with national account coverage and multi-site service contracts are displacing regional distributors. This concentration is most visible in São Paulo state's light commercial vehicle segment, where leasing companies demand standardized actuator part numbers across mixed-brand fleets.
Brazil Automotive Actuators Market Segmentation
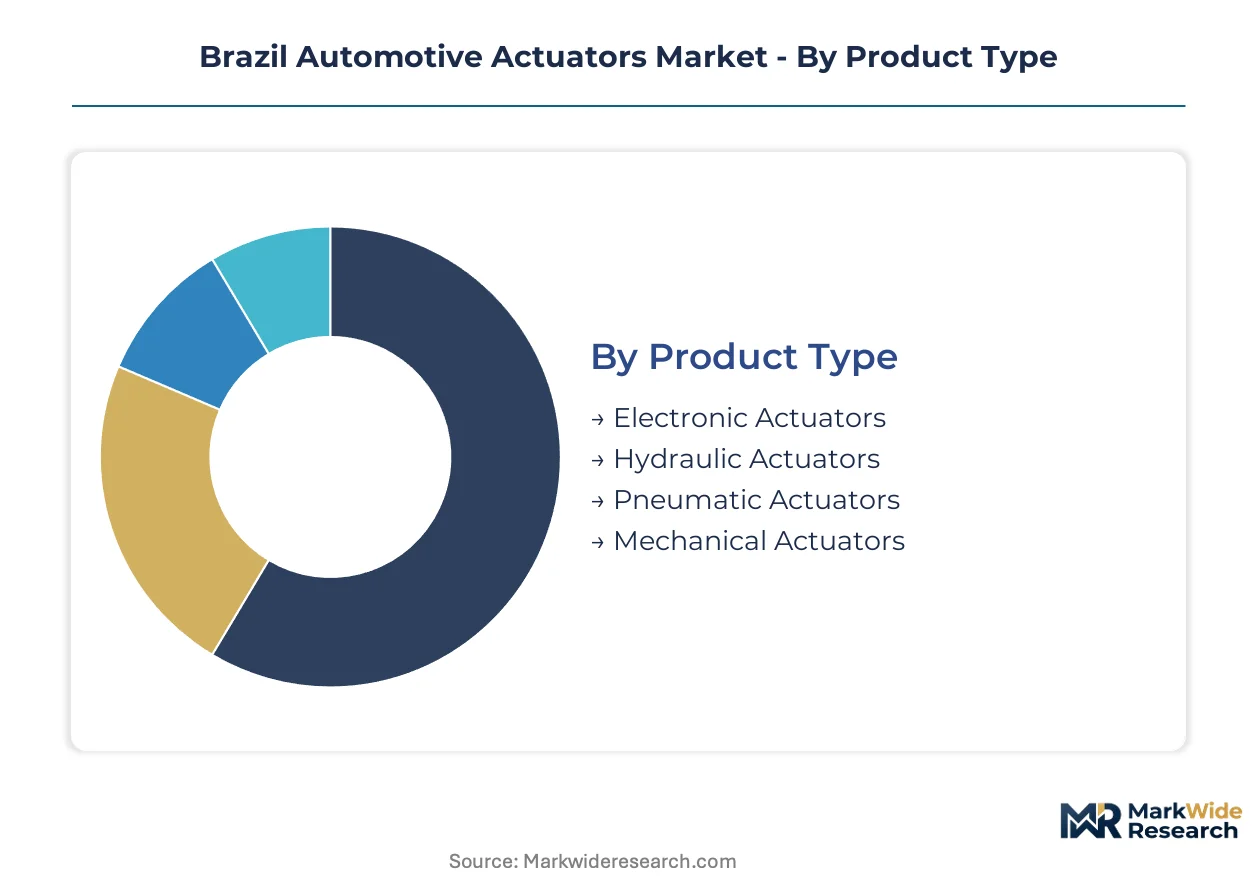
Segmentation in Brazil's automotive actuators market reveals how regulatory pressure and supply chain concentration reshape procurement patterns. Understanding channel flows and end-user specifications enables suppliers to align certification investments with actual demand concentration.
Product Type:
Electronic actuators flow predominantly through OEM direct channels and Tier-1 consolidated supply agreements, while hydraulic and pneumatic variants retain stronger aftermarket distribution due to heavy-duty fleet maintenance cycles.
- Electronic Actuators:These 12V to 48V electromechanical devices integrate position sensing and real-time ECU communication for throttle, EGR, and brake-by-wire systems. Demand concentrates among São Paulo-based OEM powertrain divisions calibrating flex-fuel engine maps, with INMETRO tropical humidity validation creating specification barriers for imports.
- Hydraulic Actuators:Fluid-power architectures deliver force density exceeding electric motor limits for heavy-duty transmission and steering applications. Fleet procurement in Minas Gerais industrial corridors drives volume, though 48V electrification ceilings lock these into structural cost positions with limited substitution upside.
- Pneumatic Actuators:Compressed-air systems serve commercial vehicle brake and suspension modules where rapid response cycles matter. Betim assembly plants source these through captive Tier-1 distributors with established Mercosur logistics.
- Mechanical Actuators:Legacy cable and linkage systems persist in entry-level vehicle segments and aftermarket replacement. Contagem-based distributors maintain inventory for older PROCONVE fleet standards.
By volume, hydraulic actuators lead in commercial vehicle penetration. By growth pace, electronic variants are expanding most quickly through flex-fuel powertrain integration.
Application:
Cost tier stratification separates premium electronic architectures in engine and brake systems from standard hydraulic configurations in transmission and steering modules.
- Engine Control:Throttle body, EGR valve, and variable geometry turbocharger actuators require real-time fuel map adaptation for Brazil's ethanol-gasoline flex technology. OEM engineering centers in Campinas specify firmware-capable suppliers with local calibration laboratories.
- Brake Systems:Brake-by-wire actuators demand self-diagnostic capability and predictive maintenance interfaces as fleet operators consolidate sourcing decisions at group level. ANVISA material safety declarations affect polymer selection for cabin-adjacent modules.
- Steering Control:Electric power steering actuators replace hydraulic racks in light commercial vehicles, though heavy-duty applications retain fluid-power architectures. Sorocaba testing clusters validate tropical humidity performance.
- Transmission Systems:Dual-clutch and automated manual transmission actuators face force density requirements that preserve hydraulic solutions in heavy segments. Minas Gerais stamping plant proximity influences supplier location decisions.
Engine control commands the highest specification intensity. Brake systems are gaining share fastest through electrification mandates and fleet consolidation.
End User:
Customer type determines contract structure, with OEMs demanding multi-year development partnerships and aftermarket providers seeking standardized part numbers across mixed-brand fleets.
- OEMs:Original equipment manufacturers in São Paulo state specify electronic actuators with integrated firmware for flex-fuel powertrains, requiring 18-24 month INMETRO OCD certification cycles that favor domestic engineering centers.
- Tier-1 Suppliers:Integrated system providers bundle actuator specification with HVAC, transmission, or braking modules, capturing climate control energy efficiency labeling opportunities through bundled procurement.
- Vehicle Assemblers:Final assembly plants in southeastern Brazil prioritize logistics proximity and multi-site service contracts over component-level technical differentiation.
- Aftermarket Providers:Regional distributors face displacement as leasing companies consolidate actuator sourcing at OEM group level, demanding standardized part numbers across fleet portfolios.
OEMs dominate value capture through specification influence. Aftermarket providers are restructuring fastest around fleet service contracts.
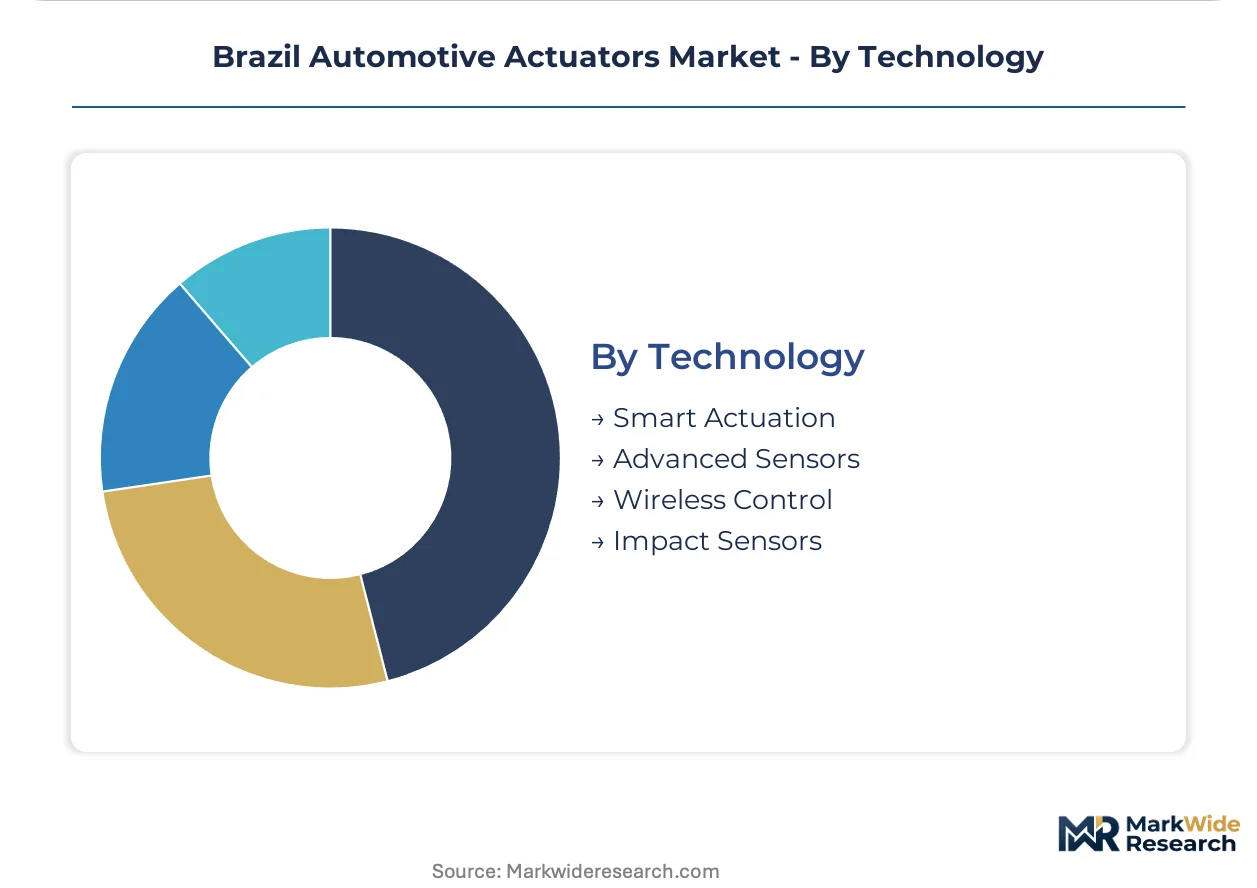
Technology:
Maturity gradients separate established sensor integration from emerging wireless and predictive maintenance protocols.
- Smart Actuation:Self-diagnostic firmware and predictive maintenance interfaces represent white space for tier suppliers to differentiate beyond commodity motion control. PROCONVE emission stage transitions force algorithm recalibration that rewards software-capable vendors.
- Advanced Sensors:Integrated position and force feedback enables closed-loop control in throttle and brake applications. Campinas engineering centers develop these capabilities for flex-fuel engine programs.
- Impact Sensors:Crash-detection actuation triggers safety system deployment, with ANVISA polymer traceability requirements affecting material selection.
- Wireless Control:Over-the-air update capability and remote diagnostics are emerging in premium fleet specifications, though cybersecurity validation extends INMETRO approval timelines.
Advanced sensors anchor current revenue. Smart actuation protocols are climbing the fastest as OEMs demand predictive maintenance interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PROCONVE emission mandates and INMETRO certification requirements are concentrating actuator demand in southeastern industrial corridors. State-level flex-fuel adoption rates and tropical humidity validation infrastructure determine supplier location decisions across Brazilian sub-regions.
São Paulo
Light commercial vehicle fleets dominate actuator procurement through consolidated OEM engineering centers. ANVISA alignment with Mercosur safety protocols tightens material traceability for cabin-contact polymers. Campinas anchors electronic actuator calibration capabilities for flex-fuel engine programs.
Minas Gerais
Betim and Contagem assembly plants source transmission and steering actuators through captive Tier-1 distributors with established Mercosur logistics. PROCONVE stage transitions force recalibration of control algorithms across heavy-duty fleet operators. Proximity to southeastern OEM stamping plants reduces inbound freight costs for hydraulic actuator suppliers.
Rio Grande do Sul
Automotive component manufacturing clusters in Porto Alegre metropolitan area support aftermarket actuator distribution networks. Legacy mechanical actuator inventory serves older PROCONVE fleet standards in southern Brazil. Regional distributors face displacement as leasing companies consolidate sourcing at OEM group level.
Paraná
Curitiba-based vehicle assemblers prioritize multi-site service contracts over component-level technical differentiation. Climate control module integration creates bundled specification opportunities for auxiliary actuator suppliers with HVAC system expertise. Energy efficiency labeling requirements under INMETRO Ordinance 445/2021 affect procurement decisions.
Bahia
Underpenetrated actuator assembly capacity offers expansion potential for suppliers seeking logistics diversification beyond southeastern concentration. Federal automotive sector incentives attract component manufacturers to northeastern industrial zones. Local engineering talent scarcity for embedded firmware development limits immediate electronic actuator adoption.
Brazil Automotive Actuators Market Competitive Environment
Listed leaders compete with private specialists across certification capability and tropical validation infrastructure. The supplier base concentrates around engineering centers with captive INMETRO-certified testing laboratories. Three archetypes dominate: integrated multinational systems suppliers, regional Tier-1 bundlers, and specialized motion control engineers. Competitive moves center on backward integration into polymer validation and geographic expansion into underpenetrated industrial corridors.
Within the integrated systems tier, Continental AG and Robert Bosch GmbH exemplify multinational suppliers with established Brazilian engineering presence. BorgWarner Inc occupies a position among powertrain specialists tuned for flex-fuel engine requirements. These three represent the certification-heavy segment where tropical humidity validation capabilities and ANVISA material traceability compliance determine specification access.
| Leading Market Players |
|---|
| Wabco Holdings Inc |
| BorgWarner Inc |
| Continental AG |
| Johnson Electric |
| Denso Corporation |
| Robert Bosch GmbH |
| Sonceboz SA |
| CTS Corporation |
| Hella KGaA Hueck & Co |
| Others |
Value Chain & Pricing Dynamics
INMETRO Ordinance 445/2021 certification gates both supplier qualification and price differentiation simultaneously, with tropical humidity validation capabilities creating tiered access that separates firmware-capable domestic engineering centers from import-dependent competitors facing extended approval timelines.
Pricing Analysis
Certification level under INMETRO OCD and ANVISA material traceability standards creates the primary spread between premium electronic actuators and commodity hydraulic alternatives. Three-tier pricing structure separates INMETRO-certified firmware-integrated units from standard sensor-equipped variants and economy mechanical linkages. Cost compression in electronic actuator tiers is intensifying because semiconductor import dependency exposes margins to dollar volatility. Fleet procurement departments exhibit lowest price sensitivity for brake-by-wire systems with predictive maintenance interfaces, while aftermarket distributors face maximum pressure on legacy mechanical replacement inventory.
Supply Chain Analysis
Semiconductor foundry concentration in Taiwan, South Korea, and China constitutes the critical chokepoint for electronic actuator production, with power management chip availability determining Tier-1 supplier output capacity. Brazilian actuator manufacturing draws from imported silicon wafers, specialty polymers for cabin-contact components, and rare earth magnets for brushless DC motors. Single-source vulnerability in tropical humidity testing infrastructure concentrated in Sorocaba and Campinas creates bottleneck risk for new market entrants. Distribution runs through OEM direct channels for electronic variants and captive Tier-1 distributors for hydraulic and pneumatic architectures serving heavy-duty fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's automotive actuators market sits at a platform-economics inflection where smart actuation firmware and predictive maintenance protocols are redefining supplier value capture beyond commodity motion control.
For Market Incumbents: Consolidate specification influence by deepening captive polymer validation capabilities under ANVISA traceability requirements and securing multi-site service contracts with São Paulo-based fleet operators facing PROCONVE emission recalibration deadlines. Backward integration into embedded firmware talent pools in Campinas engineering clusters defends against semiconductor supply disruption while elevating switching costs for OEM powertrain divisions. For New Entrants and Emerging Players: Lead with smart actuation interfaces targeting underpenetrated Minas Gerais industrial corridors where Betim and Contagem assembly plants prioritize logistics proximity over incumbent brand loyalty. White space exists in climate control module bundling for INMETRO energy efficiency labeling compliance, with auxiliary actuator specification offering a direct entry path through Tier-1 HVAC system partnerships. For Investors and Strategic Acquirers: PROCONVE stage transitions reshaping the acquisition landscape favor targets with validated flex-fuel engine map calibration capabilities and captive Sorocaba-based tropical humidity testing infrastructure. Long-term viability across the analysis window hinges on software-defined differentiation rather than hardware scale, with the signal to watch being OEM consolidation of actuator sourcing decisions at group level versus plant-level procurement autonomy.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Validation | ANVISA material traceability requirements favor suppliers with captive laboratory capabilities for cabin-contact components. |
| Smart Actuation Firmware Development | PROCONVE emission recalibration demands reward vendors with self-diagnostic and predictive maintenance protocol expertise. |
| Geographic Expansion to Minas Gerais Corridor | Betim and Contagem assembly plant proximity reduces inbound freight costs for hydraulic actuator suppliers serving heavy-duty fleets. |
| Multi-Site Fleet Service Contracting | São Paulo-based leasing companies consolidating sourcing at OEM group level displace regional distributors without national coverage. |
| Tropical Humidity Testing Infrastructure Investment | INMETRO OCD certification timelines compress to 18-24 months for foreign suppliers lacking captive Brazilian validation laboratories. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and INMETRO certification officers, then refined through secondary validation against vehicle production databases, IHS Markit registration data, ANVISA material safety filings, and PROCONVE emission standard documentation. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across the Brazilian automotive sector.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions structured the analytical framework. CAGRs were derived from installed base dynamics, replacement cycle analysis, and technology substitution curves specific to flex-fuel engine calibration requirements and brake-by-wire electrification mandates.
Underlying assumptions cover PROCONVE implementation timelines, semiconductor import availability, and INMETRO certification throughput capacity, with deviation risk concentrated in dollar volatility affecting electronic actuator margins and embedded firmware talent scarcity limiting smart actuation adoption velocity. Practitioners should keep alternative scenarios live as Mercosur automotive safety protocol harmonization and federal automotive sector incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Performance Tuning Market
Powertrain
Global Automotive Pumps Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Car Oil Filter Market
Powertrain
Crate Engines Market
Powertrain
Spark Plugs Market
Powertrain
Europe Turbocharger Market
Powertrain
Torque Limiter Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Engine Support Bar Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Drive Shaft Market
Powertrain
Transmission Fluids Market
Powertrain
Canada Automotive Engine Oils Market