
 Global Cylinder Deactivation System Market | 2026-2036
Global Cylinder Deactivation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cylinder Deactivation System Market Intelligence
Compliance with the ISO 26262 functional safety standard is reorganizing the competitive landscape for cylinder deactivation systems, raising the barrier for new entrants. BorgWarner Inc. leverages its expertise in powertrain components to offer integrated solutions for OEMs. Eaton Corporation specializes in advanced valvetrain technologies, including deactivating hydraulic lifters. Continental AG competes through its portfolio of engine management systems and electronic controls, which are essential for precise cylinder shutdown.
A cylinder deactivation system is a technology that temporarily shuts down a number of an engine's cylinders during low-load operation to improve fuel economy. This is achieved using components like electrohydraulic lifters to interrupt the valve train, effectively reducing the engine's displacement. The passenger vehicles application segment continues to dominate system installations, driven by consumer demand for fuel-efficient SUVs and trucks. Electrohydraulic systems represent the largest product segment, offering a balance of performance, cost, and reliability for mass-market vehicle platforms.
Regulatory mandates are a primary market catalyst, with the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) setting stringent fuel consumption limits. In Europe, the EU's CO2 emission performance standards for new cars directly incentivize the adoption of such efficiency technologies. The key decision for OEMs and Tier-1 suppliers now involves balancing investment in these internal combustion engine enhancements against the long-term transition to full electrification.
Market Dynamics
The primary structural force shaping the cylinder deactivation system market is the tension between automotive OEMs needing to meet immediate, stringent emissions regulations for internal combustion engines and allocating capital for the long-term transition to electrification.
Growth Catalysts
- Regulatory Mandates:China's Ministry of Ecology and Environment (MEE) enforces strict fuel consumption limits, compelling efficiency technology adoption in popular SUVs.
- Consumer Vehicle Preferences:Demand for large-engine trucks and SUVs in the United States requires fuel-saving systems for these vehicles to remain commercially viable.
- Technology Maturity:Electrohydraulic systems offer a mature, reliable method for cylinder deactivation, balancing cost and performance for mass-market platforms.
Market Restraints
- BEV Substitution:The shift to battery electric vehicles (BEVs) is a fundamental threat, making investments in internal combustion engine efficiency obsolete long-term.
- NVH Challenges:Deactivating cylinders can introduce noise, vibration, and harshness (NVH), requiring complex engineering and calibration to mitigate.
- Added System Cost:Integrating specialized components like deactivating lifters and controls increases an engine's per-unit cost and manufacturing complexity.
Strategic Opportunities
- Hybrid Powertrain Integration:Applying cylinder deactivation within hybrid electric vehicle (HEV) powertrains maximizes fuel efficiency when the combustion engine is active.
- Light Commercial Vehicles:Expanding systems into the light commercial vehicle segment, which faces its own emissions standards, represents a growth area.
- Dynamic Deactivation:Systems that deactivate a variable number of cylinders, not a fixed bank, can optimize engine performance across all driving conditions.
Industry Challenges
- Software Integration Complexity:Ensuring seamless communication between the cylinder deactivation controller and the main engine control unit (ECU) is a significant software engineering challenge, critical for system reliability.
- Functional Safety Compliance:Achieving certification for the ISO 26262 standard is a resource-intensive process that increases development time and costs, raising the barrier for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cylinder Deactivation System Market |
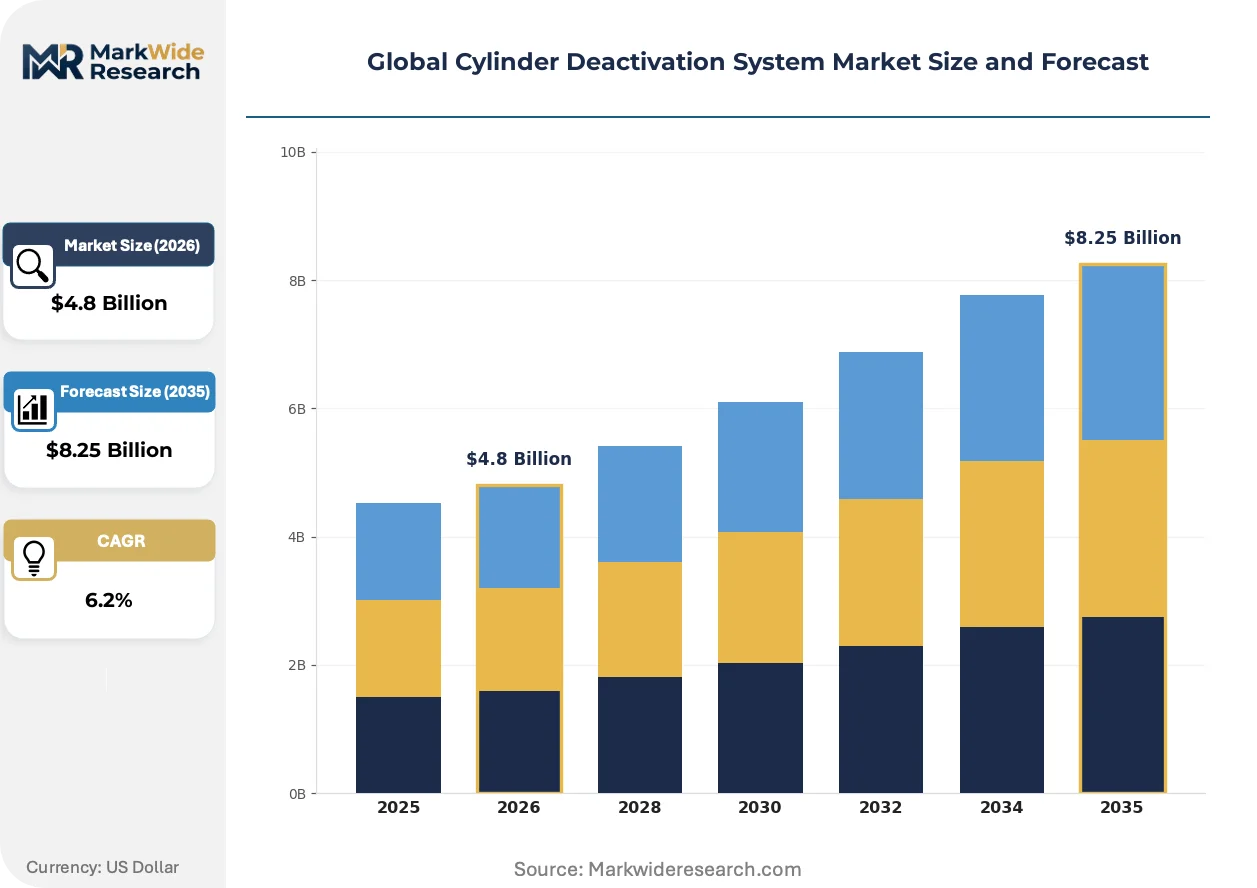
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Electrohydraulic, Electronic, Mechanical Technology: Solenoid Valve, Camshaft Phaser, Hydraulic Lifter, Variable Valve Timing Application: Passenger Vehicles, Light Commercial Vehicles, Heavy Duty Engines, Off-road Equipment End User: OEMs, Tier-1 Suppliers, Automotive Aftermarket, Vehicle Assemblers |
| Companies Covered | BorgWarner Inc, Delphi Technologies, Eaton Corporation, Magna International Inc, Denso Corporation, Robert Bosch GmbH, Schaeffler AG, General Motors, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cylinder Deactivation System Market Strategic Shifts & Innovations
The evolution of cylinder deactivation technology is increasingly defined by software and control strategy sophistication. Advanced electronics are enabling more granular management of engine displacement, improving both efficiency and driver experience.
Dynamic cylinder deactivation systems use predictive algorithms to choose which cylinders to shut down in real time. Premium and performance vehicle segments are the primary adopters of this advanced capability. This software-driven flexibility is supplanting older, fixed-pattern systems that only deactivate a predetermined set of cylinders.
Mandates from the US Environmental Protection Agency (EPA) regarding Corporate Average Fuel Economy (CAFE) directly incentivize efficiency gains in internal combustion engines. This regulatory pressure forces automakers to incorporate technologies that improve MPG figures. The large truck and SUV segments are most affected, leading to wider standardization on V6 and V8 engines.
A shift in OEM sourcing strategy involves procuring complete, pre-validated valvetrain modules rather than individual components. This approach favors Tier-1 suppliers capable of delivering an integrated system. This model is most prominent in North America and Europe, where automakers seek to de-risk and accelerate vehicle development.
Global Cylinder Deactivation System Market Segmentation
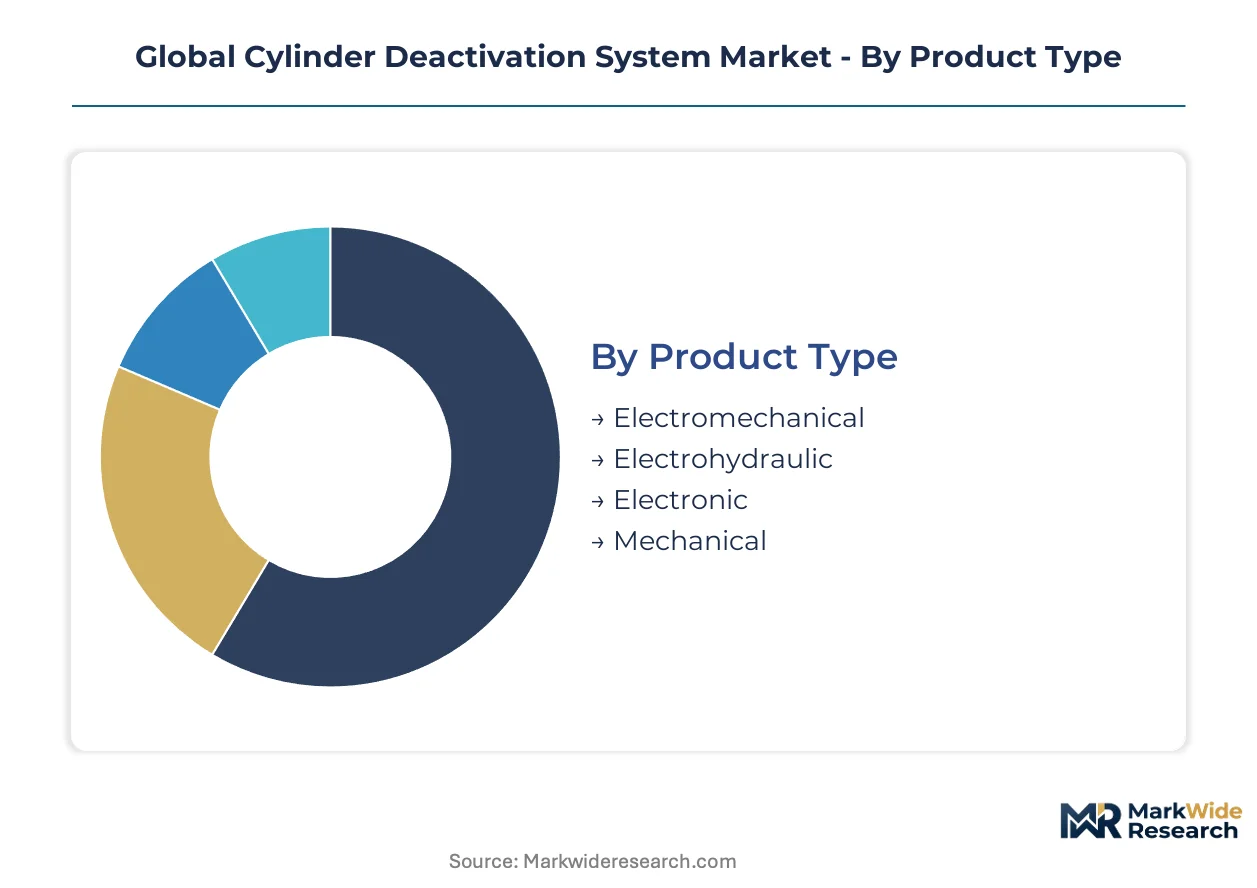
The cylinder deactivation system market is dissected across multiple dimensions, revealing distinct demand patterns and technological preferences. Understanding these segments helps automotive manufacturers and component suppliers align their product development and market strategies with evolving industry requirements.
Product Type:
The distribution of cylinder deactivation systems often follows established manufacturing and integration channels within the automotive supply chain.
- Electrohydraulic:These systems utilize hydraulic pressure controlled by electronic solenoids to disengage valve lifters, offering a precise and reliable method for cylinder shutdown. Demand for electrohydraulic systems is concentrating in the United States, driven by the need for fuel-efficient large-engine SUVs and pickup trucks to comply with EPA regulations.
- Electromechanical:Electromechanical systems employ electric actuators to modify valve lift or timing, providing flexibility in engine operation. This technology is gaining traction in Europe as OEMs seek adaptable solutions for diverse engine configurations to meet EU CO2 emission targets.
- Electronic:Electronic systems primarily rely on software and engine control unit (ECU) programming to manage cylinder deactivation, often working in conjunction with mechanical components. These systems are valued for their integration capabilities and fine-tuning potential.
- Mechanical:Mechanical systems use physical linkages or cam profiles to achieve cylinder deactivation, representing an older generation of the technology. They offer a simpler design but with less flexibility compared to electronic or hydraulic counterparts.
By volume, electrohydraulic systems lead the market. By growth pace, electromechanical systems are expanding most quickly.
Technology:
The choice of deactivation technology is largely dictated by engine architecture and the desired balance between performance, cost, and complexity for specific vehicle platforms.
- Hydraulic Lifter:Hydraulic lifters are critical components in many cylinder deactivation systems, enabling the temporary interruption of valve train operation. This technology is widely adopted in mass-market passenger vehicles, particularly in North America, due to its proven reliability and cost-effectiveness for fuel economy improvements.
- Solenoid Valve:Solenoid valves are electro-mechanical devices that precisely control the flow of hydraulic fluid, activating or deactivating the lifters. These valves are essential for the instantaneous response required for smooth cylinder deactivation transitions, especially in premium vehicle segments in Germany.
- Camshaft Phaser:Camshaft phasers adjust the timing of valve opening and closing, contributing to overall engine efficiency and can be integrated with deactivation strategies. They improve engine breathing across various RPMs.
- Variable Valve Timing:Variable valve timing (VVT) systems optimize engine performance by altering valve lift, duration, or timing, and can complement cylinder deactivation by further enhancing efficiency. VVT offers broader control over engine dynamics.
Hydraulic lifter technology sees the highest number of installations. Solenoid valve technology is being integrated into advanced systems at an accelerating rate.
Application:
Different vehicle applications present unique requirements and regulatory pressures that influence the adoption and design of cylinder deactivation systems.
- Passenger Vehicles:This segment encompasses sedans, hatchbacks, and SUVs, where fuel economy and emission reduction are paramount due to stringent regulations from the EPA and EU. Passenger vehicles represent the largest application segment, with a strong focus on consumer demand for fuel-efficient SUVs in China.
- Light Commercial Vehicles:Light commercial vehicles (LCVs) include vans and pickup trucks, which also face increasing pressure to meet fuel efficiency standards. Expanding cylinder deactivation into LCVs offers a significant opportunity for emissions compliance and operational cost reduction for fleets in the United Kingdom.
- Heavy Duty Engines:Heavy duty engines, found in large trucks and industrial equipment, are beginning to explore cylinder deactivation for efficiency gains. This application requires robust systems capable of handling high loads and extended operating hours.
- Off-road Equipment:Off-road equipment, such as construction and agricultural machinery, can benefit from cylinder deactivation to reduce fuel consumption during periods of low power demand. These systems need to withstand harsh operating environments.
The primary demand for efficiency solutions originates from passenger vehicles, with light commercial vehicles presenting significant expansion potential.
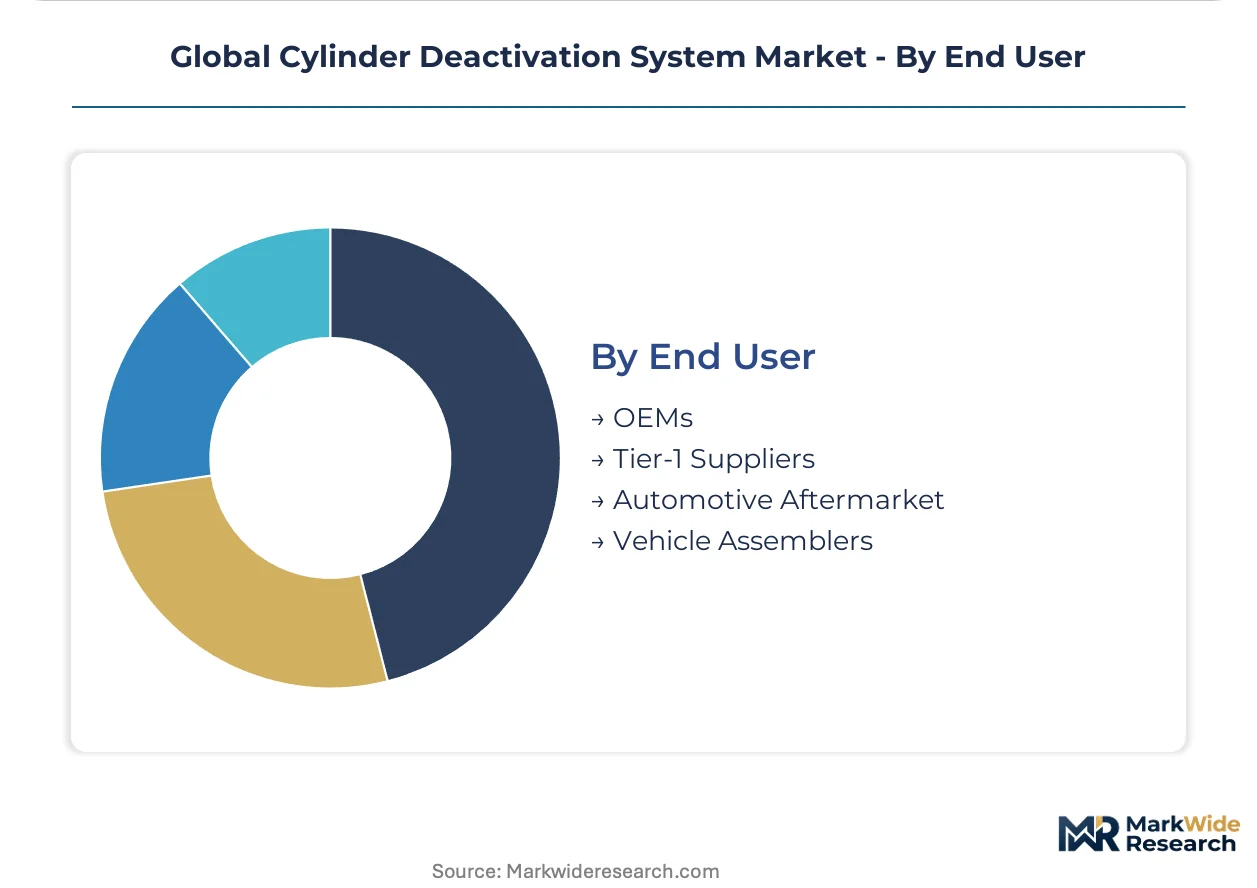
End User:
The end-user landscape defines the procurement channels and strategic partnerships within the cylinder deactivation system market.
- OEMs:Original Equipment Manufacturers (OEMs) are the primary integrators of cylinder deactivation systems into new vehicle designs. They drive specifications and demand for complete, validated modules from their suppliers.
- Tier-1 Suppliers:Tier-1 suppliers develop and manufacture complete cylinder deactivation systems or major sub-assemblies for OEMs. These companies often possess specialized expertise in engine components and electronic controls.
- Automotive Aftermarket:The automotive aftermarket includes replacement parts and performance upgrades, though cylinder deactivation systems are less common here due to their complexity. This segment primarily focuses on maintenance components.
- Vehicle Assemblers:Vehicle assemblers are involved in the final integration of components and systems into the finished vehicle. Their role is critical in ensuring proper installation and functionality.
Direct procurement is primarily driven by OEMs, while Tier-1 suppliers influence component specifications and system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent fuel economy regulations and CO2 emission targets from various national environmental agencies are driving the adoption of cylinder deactivation systems globally. These mandates compel automotive manufacturers to integrate efficiency technologies into their internal combustion engine vehicles. The market exhibits diverse regional responses to these regulatory pressures and consumer preferences.
United States
Consumer demand for large-engine SUVs and pickup trucks drives significant adoption of cylinder deactivation systems in the United States. The US Environmental Protection Agency (EPA) mandates Corporate Average Fuel Economy (CAFE) standards, pushing OEMs to enhance vehicle efficiency. Detroit's automotive manufacturing cluster actively integrates these systems into popular truck and SUV platforms to meet federal requirements.
China
Government policies favoring fuel-saving technologies are a primary catalyst for cylinder deactivation system demand in China. The Ministry of Ecology and Environment (MEE) enforces strict fuel consumption limits, particularly impacting the popular SUV segment. Shanghai and Guangzhou, major automotive hubs, see extensive investment in localizing and integrating these efficiency solutions into domestic vehicle production.
Germany
Premium and performance vehicle segments in Germany increasingly adopt advanced cylinder deactivation systems for efficiency and emissions compliance. European Union CO2 emission performance standards incentivize automakers to deploy sophisticated engine management technologies. Stuttgart and Munich's automotive engineering centers focus on developing precise electronic controls and electromechanical systems for high-end applications.
India
The rising demand for fuel-efficient passenger vehicles, especially compact SUVs, influences cylinder deactivation system integration in India. The country's national automotive emission standards, Bharat Stage (BS) norms, align with global benchmarks, prompting technology adoption. Chennai and Pune, significant automotive manufacturing clusters, are emerging as key locations for local production and integration of these systems.
Global Cylinder Deactivation System Market Key Industry Players
Player mix skews toward established Tier-1 automotive suppliers and powertrain component specialists. The market structure exhibits a tiered consolidation, with a few large entities dominating the core technology provision. Strategic archetypes include integrated solution providers and specialized valvetrain technology developers. Dominant competitive moves involve strategic partnerships with OEMs and continuous portfolio diversification into advanced electronic controls.
Within the integrated solution provider archetype, BorgWarner Inc. exemplifies comprehensive powertrain component expertise, offering complete systems to original equipment manufacturers. This company leverages its broad portfolio to deliver integrated solutions essential for modern engine efficiency. Eaton Corporation, a US-based company, occupies a position as a specialist in advanced valvetrain technologies, including deactivating hydraulic lifters, which are critical for precise and efficient cylinder management. Continental AG, a German multinational, sits within the electronic control systems segment, providing essential engine management solutions that enable precise and reliable cylinder shutdown applications across various vehicle platforms globally.
| Leading Market Players |
|---|
| BorgWarner Inc |
| Delphi Technologies |
| Eaton Corporation |
| Magna International Inc |
| Denso Corporation |
| Robert Bosch GmbH |
| Schaeffler AG |
| General Motors |
| Continental AG |
Cost & Logistics Intelligence
High-volume manufacturing efficiencies for electrohydraulic systems establish significant scale economies, driving supply concentration among specialized Tier-1 component providers. These scale advantages subsequently influence price floors for mass-market vehicle platforms.
Pricing Analysis
Functional safety compliance, particularly ISO 26262 certification, creates the primary spread in cylinder deactivation system pricing. The market largely operates on a contract-based long-term offtake model between Tier-1 suppliers and OEMs. Customization level for specific engine platforms and integrated software capabilities also drive price differentiation. Pricing softness stems from the long-term transition to electrification, impacting OEM investment priorities for ICE enhancements. Passenger vehicle OEMs, especially in emerging markets, exhibit the highest price sensitivity, while premium segment manufacturers prioritize performance and reliability.
Supply Chain Analysis
Rising inbound logistics costs, particularly for specialized electronic components from Southeast Asia, impact cylinder deactivation system manufacturing. Supply concentration for these systems centers in Germany, Japan, and the United States, reflecting specialized engineering expertise. The production relies on precision-machined metal parts and advanced semiconductors for electronic control units. Single-source vulnerability for certain electrohydraulic lifter components represents a structural risk. Downstream distribution typically runs through direct supply agreements from Tier-1 manufacturers to global automotive OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cylinder deactivation system market faces a critical shortage of integrated software-hardware engineering talent. This scarcity of expertise limits rapid innovation and raises the barrier for developing advanced control strategies.
For Market Incumbents: Shield existing market share by investing heavily in next-generation electrohydraulic and electromechanical system R&D, particularly for hybrid powertrains. Consolidate technical talent through targeted acquisitions of specialized software firms to counter the threat of new entrants focusing on electronic controls. Deepen vertical integration into critical component manufacturing to mitigate supply chain risks. Prioritize certification investments to maintain compliance with evolving functional safety standards like ISO 26262.
For New Entrants and Emerging Players: Anchor in niche segments that require highly customized software-driven dynamic deactivation solutions, particularly for premium performance vehicles. Target light commercial vehicles in Europe, which present significant expansion potential due to emissions standards. Develop modular electronic control units that can integrate seamlessly with diverse engine management systems, offering a flexible go-to-market angle. Focus on regions with less established Tier-1 dominance, such as India, to build early market presence.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Tier-1 suppliers offering complete, integrated valvetrain modules with embedded software. Long-term viability for this market hinges on the pace of full electrification versus continued investment in ICE efficiency, spanning a 5-10 year window. Identify acquisition targets specializing in advanced control software and electromechanical systems, which offer intellectual property defensibility. The signal to watch involves OEM announcements regarding accelerated BEV platform transitions for their core truck and SUV lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Electromechanical System R&D | Advances efficiency for diverse engine configurations to meet EU CO2 targets. |
| Acquire Software Control Specialists | Enhances dynamic deactivation capabilities and addresses software integration complexity. |
| Expand into Light Commercial Vehicle Segment | Captures new demand from fleet operators facing emissions standards in the United Kingdom. |
| Standardize Integrated Valvetrain Modules | Simplifies OEM procurement processes and accelerates vehicle development in North America. |
| Develop Hybrid Powertrain Integration Solutions | Maximizes fuel efficiency when the combustion engine is active in HEV applications. |
Research Approach
Desk research of regulatory filings, automotive industry reports, and technical journals preceded structured interviews with Tier-1 supplier R&D directors, OEM powertrain engineers, and automotive procurement managers. This approach combined primary insights with secondary validation to build a comprehensive market view. Bottom-up data aggregation from component sales and top-down analysis of vehicle production volumes informed market sizing. The triangulation process ensured robust data integrity.
Variance decomposition identified key drivers impacting cylinder deactivation system adoption across the analysis window, including regulatory mandates and consumer preferences. The analytical framework modeled market evolution by product type, technology, application, and regional vehicle production clusters. Compound Annual Growth Rates were derived from historical trends and projected technological shifts. Forecast inputs included projected fuel economy standards from the EPA and anticipated shifts in OEM electrification strategies.
Material uncertainties — such as a radical acceleration of electric vehicle adoption or unforeseen geopolitical events impacting automotive production — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and technological development trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Automotive Resonator Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
Global Automotive Radiator Market