
 South America Automotive Market | 2026-2036
South America Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
South America Automotive Market Outlook
PROCONVE Phase L8 emission standards is pivoting OEM investment toward cleaner combustion architectures and hybrid platforms. Toyota Motor Corporation leverages its regional hybrid manufacturing footprint to sustain cost-competitive electrified offerings. Stellantis anchors its Mercosur operations through integrated powertrain plants in Brazil. Volkswagen competes on modular platform flexibility across sedan and SUV lines.
The South America automotive sector encompasses passenger and commercial vehicles engineered to diverse road conditions, altitude tolerances up to 4,000 meters, and flex-fuel compatibility requirements, serving personal mobility, logistics, and agricultural transport needs. SUVs and pickup trucks dominate volume as rural infrastructure and terrain demands favor higher-clearance architectures; hybrid fuel types represent the fastest-expanding category as charging infrastructure lags full-electric deployment. Fleet operators constitute a concentrated margin pool where telematics integration and total-cost-of-ownership calculations drive procurement decisions.
ANVISA collaborates with INMETRO to enforce occupant safety and emissions compliance, while PROCONVE schedules tighten tailpipe limits through 2030. Brazil's Rota 2030 industrial policy ties tax incentives to local content thresholds and R&D expenditure, reshaping investment location decisions. Stakeholders must monitor Mercosur-EU trade agreement implementation timelines and their potential to alter tariff structures for imported components and finished vehicles.
Market Dynamics
PROCONVE Phase L8 emission standards are compressing combustion engine viability windows while accelerating hybrid powertrain adoption across Brazilian and Argentine manufacturing corridors.
Growth Catalysts
- ANVISA-INMETRO safety alignment:Fleet operators in São Paulo upgrade vehicle specifications to meet consolidated occupant protection mandates, expanding procurement volumes for crash-tested architectures.
- Congestion pricing corridors:Municipal low-emission zones in Brazilian state capitals create operational cost advantages for hybrid drivetrains among urban logistics providers.
- Rota 2030 tax incentives:Local content thresholds tied to R&D expenditure redirect OEM investment toward Brazilian powertrain engineering centers.
Market Restraints
- Lithium supply concentration:Battery cell manufacturing inputs depend on Chilean and Argentine brine extraction, exposing hybrid production schedules to Andean processing bottlenecks.
- Charging infrastructure lag:Grid interconnection delays in secondary Brazilian cities constrain full-electric deployment, trapping demand in transitional hybrid architectures.
- PROCONVE compliance costs:Tailpipe limit tightening forces small-scale assemblers toward capital-intensive catalytic after-treatment systems or exit.
Strategic Opportunities
- Colombian market underpenetration:Andean terrain and altitude tolerance requirements favor flex-fuel hybrid platforms where competitors maintain limited distribution.
- Telematics-integrated fleet services:Brazilian agribusiness operators seek real-time fuel monitoring and predictive maintenance bundling beyond standalone vehicle sales.
- Mercosur-EU tariff restructuring:Trade agreement implementation would reduce component import costs for European-origin transmission and electronics modules.
Industry Challenges
- Electrification skill scarcity:Brazilian technical institutes produce insufficient high-voltage systems technicians for hybrid assembly line expansion.
- Legacy flex-fuel integration:Engineering teams must reconcile ethanol-compatible fuel systems with hybrid battery thermal management in shared vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Automotive Market |
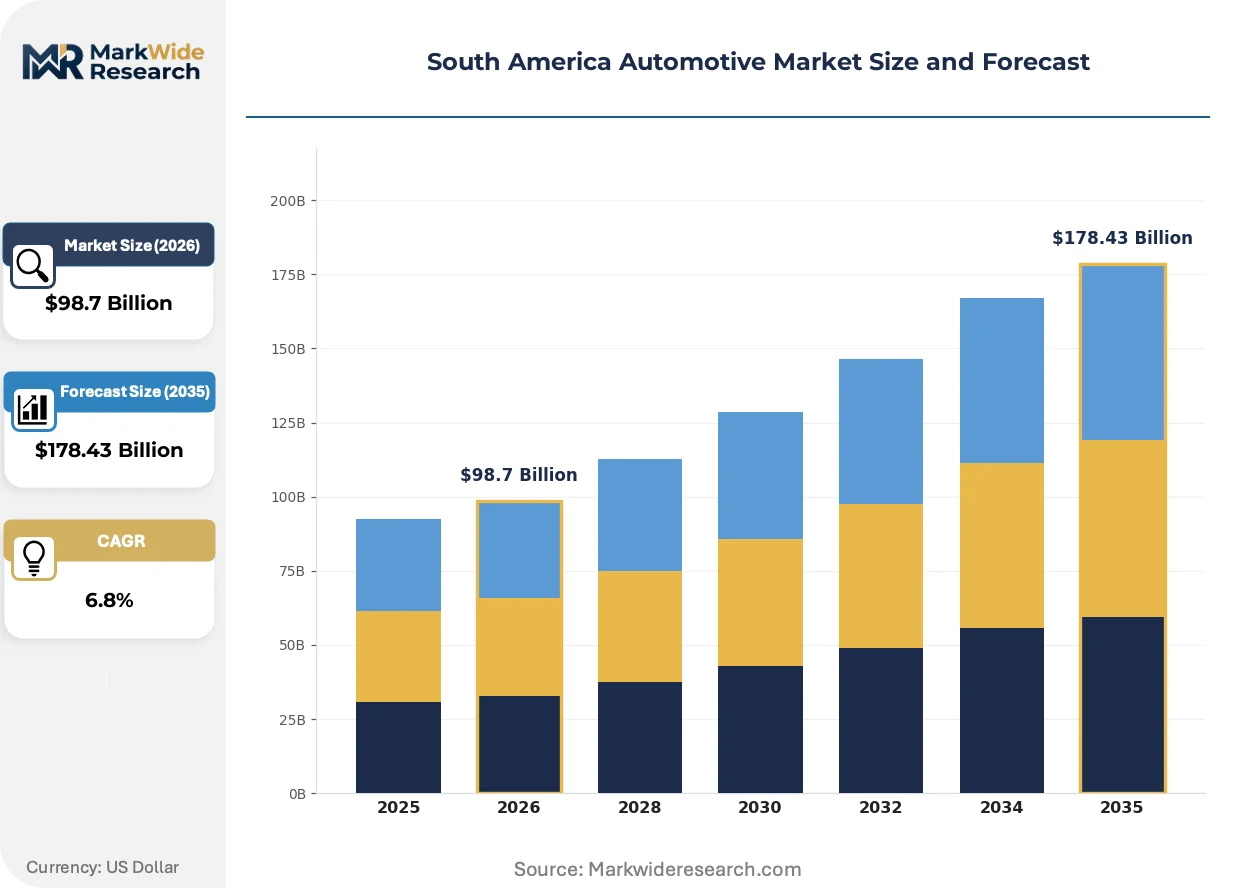
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Hatchbacks, Pickup Trucks End User: Private Users, Fleet Operators, Car Rentals, Dealerships Fuel Type: Petrol, Diesel, Electric, Hybrid Technology: Telematics, Infotainment, Autonomous, Safety Systems |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, Stellantis, Honda Motor Co. Ltd., Nissan Motor Co. Ltd., General Motors, Ford Motor Company, Renault, Volkswagen, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Automotive Market Strategic Shifts
Electrified drivetrains are penetrating South American vehicle portfolios through regulatory compression rather than consumer pull, reshaping engineering priorities and supply chain geography simultaneously.
Modular hybrid architectures are converging with flex-fuel combustion systems to preserve ethanol infrastructure compatibility while delivering emission reductions. São Paulo-based fleet managers pilot these dual-fuel hybrid configurations in urban delivery routes where stop-start optimization compounds fuel savings. The convergence is compressing pure-combustion development timelines as engineering resources migrate toward integrated powertrain platforms.
PROCONVE Phase L8 tailpipe limits are eliminating conventional diesel passenger vehicle economics in Brazilian metropolitan markets. OEM engineering centers redirect investment toward gasoline-hybrid and ethanol-hybrid architectures that satisfy nitrogen oxide thresholds without selective catalytic reduction complexity. Argentine border provinces with cross-border freight flows experience accelerated fleet turnover as older diesel architectures face registration restrictions.
Fleet procurement departments in Brazilian agribusiness and mining verticals unbundle vehicle acquisition from aftermarket service contracts, pressuring OEMs to compete on total-cost-of-ownership analytics rather than sticker price. Third-party telematics providers capture maintenance scheduling and fuel optimization relationships that manufacturers previously controlled. This pattern concentrates in Mato Grosso and Minas Gerais states where large-scale operators maintain centralized procurement functions.
South America Automotive Market Segmentation
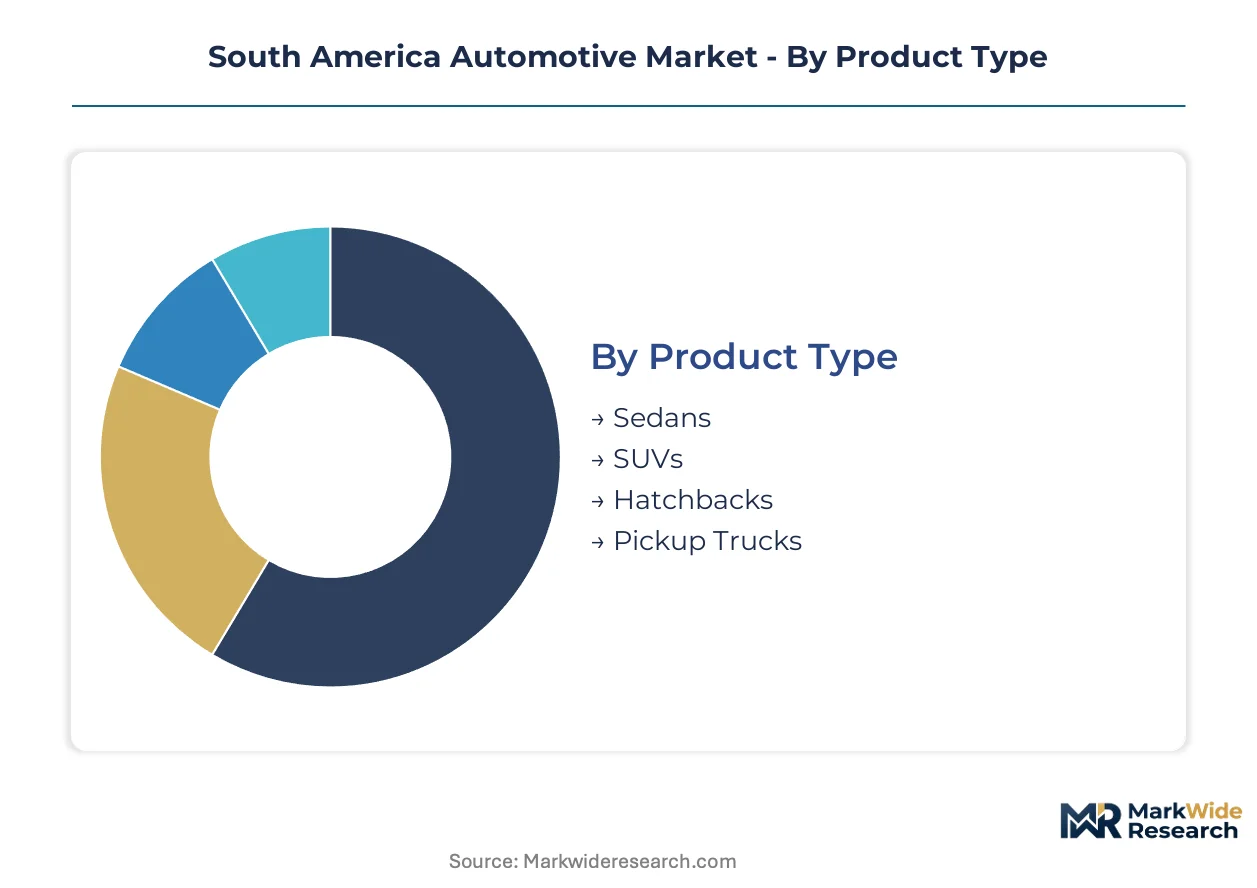
South American automotive procurement patterns diverge sharply between personal mobility and commercial logistics verticals, with fleet operators demanding integrated service architectures that reshape how OEMs configure product portfolios across vehicle classes and technology tiers.
Product Type:
Standalone vehicle architectures dominate Brazilian and Argentine assembly output, while embedded platform sharing accelerates cost amortization across regional manufacturing hubs.
- SUVs:Higher ground clearance and reinforced suspension systems accommodate unpaved rural corridors and Andean altitude gradients. Brazilian agribusiness fleets in Mato Grosso prioritize these architectures for year-round field access regardless of seasonal road degradation.
- Pickup Trucks:Dual-cab configurations with reinforced payload ratings serve cross-border freight flows between Brazil, Argentina, and Paraguay. Fleet operators in Argentine border provinces favor diesel-compatible variants for long-haul torque requirements, though PROCONVE Phase L8 is compressing their regulatory viability.
- Sedans:Urban taxi and ride-hail operators in São Paulo and Buenos Aires specify these for fuel efficiency and passenger capacity optimization.
- Hatchbacks:Compact dimensions suit congested Brazilian state capitals where parking scarcity and maneuverability constrain vehicle selection.
Volume placements concentrate in Pickup Trucks; the faster expansion belongs to SUVs.
End User:
Customer procurement sophistication varies dramatically across cost tiers, with enterprise buyers extracting service bundling concessions unavailable to individual purchasers.
- Fleet Operators:Centralized procurement functions in Brazilian mining and agribusiness verticals negotiate telematics integration and predictive maintenance contracts as standard inclusions. These operators unbundle vehicle acquisition from aftermarket service, pressuring OEMs to compete on total-cost-of-ownership analytics rather than sticker price alone.
- Private Users:Individual buyers in São Paulo's urban corridors respond to congestion pricing differentials, with hybrid drivetrain preference concentrated among this segment where operational cost sensitivity intersects with environmental positioning.
- Car Rentals:Fleet turnover velocity demands standardized maintenance protocols and residual value predictability, favoring established OEM brands with dense service networks.
- Dealerships:Inventory financing structures and manufacturer incentive programs determine stock composition, with regional distributors balancing PROCONVE-compliant new models against pre-owned vehicle margins.
Procurement volume clusters with Fleet Operators; Private Users are gaining share fastest as congestion pricing expands across Brazilian municipalities.
Fuel Type:
Application context dictates fuel architecture selection, with infrastructure availability and regulatory compression operating as primary constraints.
- Hybrid:Integrated powertrain platforms combining electric motor assist with flex-fuel combustion preserve Brazil's ethanol infrastructure while delivering emission reductions. São Paulo-based urban logistics providers pilot these configurations where stop-start optimization compounds fuel savings in congestion corridors.
- Petrol:Conventional spark-ignition architectures retain cost advantages in price-sensitive segments, though PROCONVE compliance is forcing catalytic after-treatment investments that erode margin structures.
- Diesel:Compression-ignition economics face elimination in Brazilian metropolitan markets as nitrogen oxide thresholds tighten without selective catalytic reduction complexity.
- Electric:Battery-electric deployment remains constrained by grid interconnection delays in secondary Brazilian cities, trapping demand in transitional hybrid architectures despite municipal low-emission zone incentives.
Current volume dominance sits with Petrol; Hybrid platforms are climbing the fastest as engineering resources migrate from pure-combustion development.
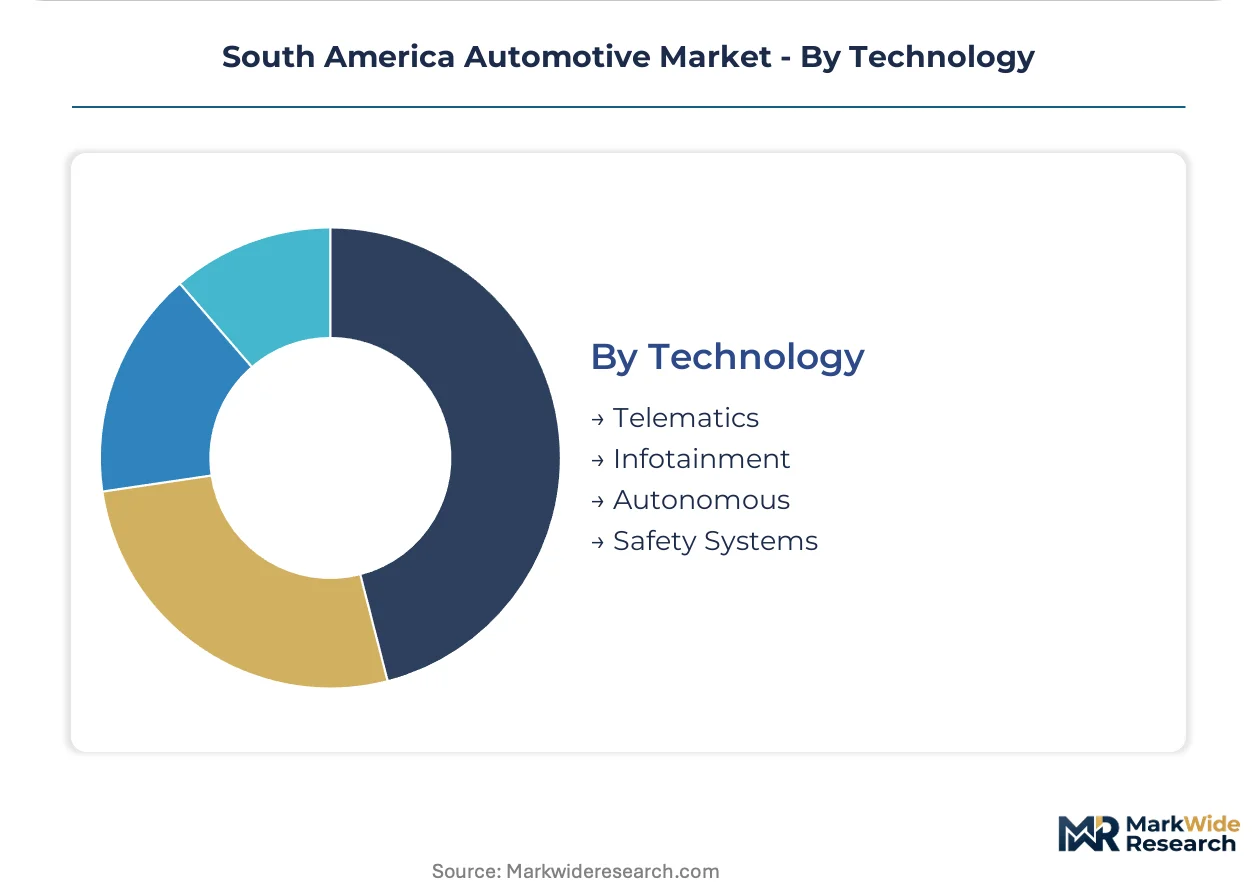
Technology:
Margin capture potential separates embedded safety mandates from optional infotainment upgrades, with regulatory enforcement determining baseline specification floors.
- Safety Systems:ANVISA-aligned occupant protection mandates mandate crash-tested architectures with reinforced passenger compartments and advanced restraint systems. Fleet operators upgrade vehicle specifications to meet these consolidated mandates, expanding procurement volumes for compliant platforms.
- Telematics:Real-time fuel monitoring and predictive maintenance bundling capture maintenance scheduling relationships that manufacturers previously controlled. Third-party providers are penetrating this space in Brazilian agribusiness verticals where large-scale operators maintain centralized procurement functions.
- Infotainment:Connectivity platforms and touchscreen interfaces differentiate consumer-facing models, though fleet buyers deprioritize these features in favor of durability and service cost predictability.
- Autonomous:Advanced driver-assistance systems remain limited to premium segments given sensor cost structures and liability framework uncertainties across Mercosur jurisdictions.
Specification mandates concentrate volume in Safety Systems; Telematics integration is gaining share fastest as fleet procurement unbundles vehicle acquisition from service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors South American automotive manufacturing through its ABC industrial corridor, where OEM assembly plants and tier-1 supplier networks concentrate production capacity for domestic consumption and Mercosur export.
Brazil
ABC Paulista manufacturing clusters sustain the region's largest vehicle output volumes as Rota 2030 tax incentives redirect powertrain engineering investment toward local content compliance. ANVISA collaborates with INMETRO to enforce consolidated occupant protection mandates, accelerating fleet procurement of crash-tested architectures. São Paulo-based urban logistics providers pilot flex-fuel hybrid configurations where municipal congestion pricing creates operational cost advantages for electrified drivetrains.
Argentina
Córdoba and Buenos Aires provinces concentrate vehicle assembly and stamping operations serving cross-border freight flows into Brazil and Chile. PROCONVE-aligned emission schedules compress diesel passenger vehicle economics, forcing fleet turnover toward gasoline-hybrid architectures. Argentine border provinces experience accelerated registration restrictions on older diesel architectures as nitrogen oxide thresholds tighten without selective catalytic reduction complexity.
Chile
Atacama Desert lithium extraction operations supply battery cell manufacturing inputs for regional hybrid production, though processing bottlenecks expose assembly schedules to Andean supply concentration. Santiago's urban corridors implement municipal low-emission zones that favor hybrid drivetrains among delivery fleet operators. Northern mining regions sustain demand for reinforced pickup architectures serving altitude-tolerant logistics requirements.
Colombia
Andean terrain and Bogotá's altitude tolerance requirements favor flex-fuel hybrid platforms where infrastructure constraints trap demand in transitional electrified architectures. The country's national automotive regulator enforces emission compliance schedules that accelerate fleet modernization among urban taxi operators. Medellín-based logistics providers seek telematics-integrated service bundling for real-time fuel monitoring across mountainous distribution routes.
Peru
Lima's coastal manufacturing corridors and Andean mining regions generate bifurcated demand for urban passenger vehicles and heavy-duty commercial architectures. Altitude gradients exceeding 4,000 meters in southern mining belts require reinforced powertrain cooling systems and flex-fuel compatibility. Fleet operators in Arequipa and Cusco procurement networks prioritize total-cost-of-ownership analytics over sticker price as service infrastructure scarcity elevates maintenance predictability requirements.
South America Automotive Market Competitive Environment
The competitive structure tilts toward integrated multinational OEMs with established Mercosur manufacturing footprints and localized powertrain engineering capabilities. Market concentration reflects high capital barriers to entry for assembly operations and Rota 2030 local content thresholds that favor incumbents with Brazilian supplier relationships. Two strategic archetypes dominate: diversified global manufacturers leveraging modular platform flexibility, and regional specialists optimizing for flex-fuel ethanol compatibility. Competitive moves center on hybrid powertrain portfolio expansion and telematics service bundling for fleet procurement verticals.
Among Japan-based manufacturers, Toyota Motor Corporation and Honda Motor Co. Ltd. occupy positions exemplifying hybrid technology leadership through regional manufacturing integration. Stellantis anchors the European-origin archetype with consolidated Mercosur operations spanning Brazilian and Argentine assembly corridors. These three entities represent distinct competitive vectors: Toyota leverages established hybrid production scale, Honda concentrates on motorcycle-to-automotive technology transfer, and Stellantis deploys multi-brand platform sharing across price tiers.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Stellantis |
| Honda Motor Co. Ltd. |
| Nissan Motor Co. Ltd. |
| General Motors |
| Ford Motor Company |
| Renault |
| Volkswagen |
| Others |
Value Chain & Pricing Dynamics
PROCONVE Phase L8 emission compliance gates qualified supply access and premium-tier pricing power, compressing margins for non-compliant assemblers while elevating certified hybrid architectures. Fleet procurement departments in São Paulo and Buenos Aires extract total-cost-of-ownership concessions that reshape how OEMs bundle telematics and service contracts into vehicle pricing.
Pricing Analysis
Total-cost-of-ownership anchoring dominates fleet procurement negotiations, with Brazilian agribusiness operators demanding predictive maintenance bundling and real-time fuel monitoring as standard inclusions. Price differentiation separates ANVISA-certified crash-tested architectures from pre-owned import alternatives, while congestion pricing corridors in Brazilian state capitals create operational cost premiums for hybrid drivetrains. Cost compression in entry-tier petrol architectures intensifies as catalytic after-treatment investments erode margin structures. Fleet operators exhibit lowest price sensitivity due to centralized procurement scale; individual private buyers in secondary cities remain most price-constrained.
Supply Chain Analysis
Remanufacturing flows for powertrain components and battery pack refurbishment are emerging as critical cost-offset mechanisms for Brazilian fleet operators managing extended vehicle lifecycles. Lithium extraction concentrates in Chilean Atacama brine operations and Argentine salares, while semiconductor and electronics module supply draws from China, South Korea, and Mexico. Single-source vulnerability in Andean lithium processing exposes hybrid production schedules to regional bottlenecks. Distribution runs through São Paulo-based OEM assembly clusters and tier-1 supplier networks serving Mercosur consumption corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America automotive market is becoming a vertical-integration race, with players pursuing captive lithium supply agreements to secure hybrid battery input availability against Andean processing constraints.
For Market Incumbents: Hedge against electrification skill scarcity by investing in Brazilian technical institute partnerships for high-voltage systems technician training. Consolidate telematics service relationships before third-party providers capture maintenance scheduling control in Mato Grosso and Minas Gerais agribusiness verticals. For New Entrants and Emerging Players: The price-point gap between premium Toyota hybrid offerings and economy-tier flex-fuel combustion models opens white-space for mid-market flex-fuel hybrid platforms in Colombian Andean corridors. Target Bogotá altitude-tolerant logistics providers with telematics-integrated service bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: PROCONVE L8 compliance deadline acceleration is the leading indicator that small-scale assemblers face forced exit or acquisition. Long-term viability centers on OEMs with integrated Mercosur manufacturing footprints and localized powertrain engineering capabilities. Monitor ANVISA-INMETRO safety mandate enforcement intensity for early signals of fleet procurement volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Stellantis deploys multi-brand architecture sharing across Brazilian and Argentine assembly corridors to amortize Rota 2030 compliance costs. |
| Battery Supply Agreement | Captive lithium offtake from Chilean and Argentine brine operations secures hybrid production schedules against Andean processing bottlenecks. |
| Software-Defined Vehicle Investment | Telematics integration captures maintenance scheduling relationships that third-party providers are penetrating in Brazilian agribusiness verticals. |
| Geographic Manufacturing Footprint | Rota 2030 local content thresholds redirect powertrain engineering investment toward Brazilian supplier relationship consolidation. |
| Charging Infrastructure Partnership | Grid interconnection delays in secondary Brazilian cities sustain demand for transitional hybrid architectures over full-electric deployment. |
Study Parameters
Vehicle production databases, IHS Markit registration data, and PROCONVE compliance filings formed the secondary backbone, cross-referenced with primary interviews involving OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers. Bottom-up triangulation across vehicle class, propulsion architecture, and regional production cluster dimensions validated top-down market sizing derived from customs and trade flow analysis.
Historical trendline analysis established baseline growth trajectories across the projection horizon, with segmentation modeling incorporating vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs were derived from regression analysis of production volume and value indicators, incorporating Rota 2030 incentive phase-in schedules and ANVISA safety mandate compliance timelines as structural forecast inputs.
Inputs from OEM production disclosures and fleet operator procurement records were available through the study window; gaps in small-scale assembler financial reporting introduce uncertainty bands around market concentration estimates. Practitioners should monitor PROCONVE L8 enforcement intensity and Mercosur-EU trade agreement implementation triggers for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Clutch Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Powertrain Testing Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Torque Limiter Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Automotive Brake Booster Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Colombia Automotive Engine Oils Market