
 Crankshaft Oil Market | 2026-2036
Crankshaft Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Crankshaft Oil Market Analysis
China is fragmenting as domestic blenders scale capacity for crankshaft lubricants serving high-performance engines. Freudenberg leverages its polymer science heritage to develop advanced seal-compatible formulations. SKF anchors European supply through integrated bearing-lubricant systems. Parker Hannifin competes via hydraulic-fluid cross-selling into marine crankshaft applications.
Crankshaft oil is a high-viscosity lubricant formulated with anti-wear additives, detergents, and dispersants to reduce friction between journal bearings and crankshaft surfaces under cyclic loading. Its primary purpose is to maintain hydrodynamic film strength, prevent metal-to-metal contact, and suspend combustion byproducts in internal combustion engines. Synthetic oil commands premium positioning as OEMs extend drain intervals and tighten volatility specifications. Mineral oil retains volume leadership in aftermarket repair shops where cost sensitivity dominates purchase decisions. Marine applications represent a concentrated margin pool due to IMO-mandated lubricant compatibility with low-sulfur fuel systems.
EPA regulates crankshaft oil volatility and toxicity through fuel and emissions standards that indirectly mandate lubricant reformulation. Japan's METI enforces JIS standards for industrial engine lubricants that constrain import eligibility. China's SAMR implements GB standards for domestic blending facilities that shape market access for foreign suppliers. Stakeholders must monitor regulatory divergence between sulfur-content rules and biodegradability mandates when allocating R&D budgets across regional formulation centers.
Market Dynamics
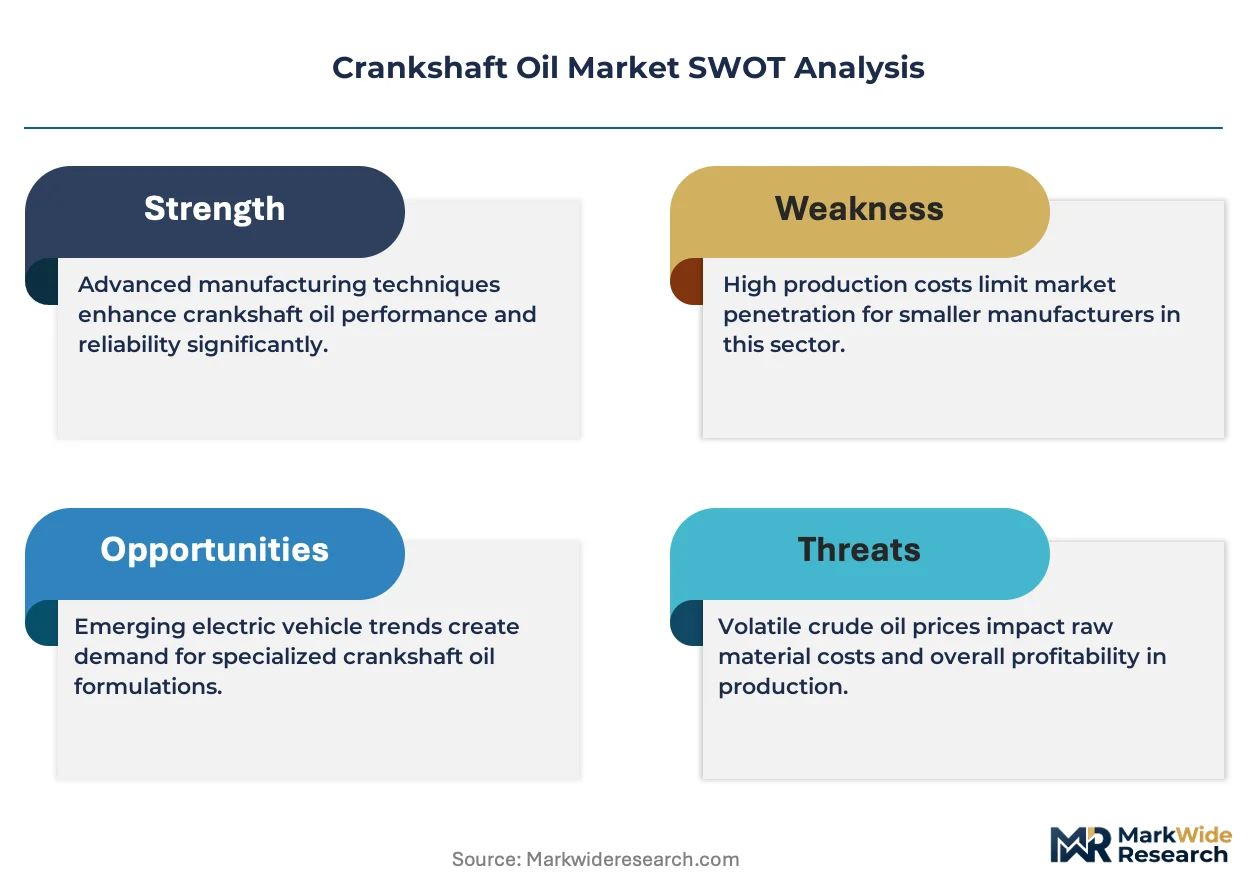
Synthetic formulation migration is compressing mineral oil margins while EPA volatility standards force reformulation cycles every 24-36 months across the United States, Germany, and Japan. This regulatory-technology squeeze is redistributing value toward polymer science capabilities and away from commodity blending capacity.
Growth Catalysts
- EPA Tier 3 Emissions Standards:Tightened volatility limits for crankcase lubricants in heavy-duty diesel applications are forcing fleet operators toward synthetic formulations with extended drain intervals.
- Marine Low-Sulfur Fuel Compatibility:IMO 2020 sulfur caps have created specialized demand for crankshaft oils formulated to handle corrosive combustion byproducts in two-stroke marine engines.
- Hydrodynamic Film Modeling:Computational fluid dynamics simulation tools now enable predictive lubricant design for high-RPM racing applications, opening premium segments in motorsport.
Market Restraints
- Group III Base Oil Concentration:Over 60% of synthetic feedstock supply originates from refineries clustered along the US Gulf Coast, exposing blenders to hurricane-related disruption.
- ZDDP Additive Substitution Limits:EPA toxicity restrictions on zinc dialkyldithiophosphate anti-wear chemistry have narrowed the performance gap between conventional and reformulated products.
- Electric Powertrain Displacement:Battery-electric commercial vehicle penetration in urban delivery fleets is eliminating crankshaft lubricant demand entirely in those duty cycles.
Strategic Opportunities
- India BIS Certification Gap:Domestic blenders in Mumbai and Chennai lack ISO 150 grade production lines, creating import windows for foreign suppliers meeting BIS IS 13656 standards.
- Wind Turbine Gearbox Convergence:Crankshaft oil formulators with EP additive expertise are pivoting into main bearing lubrication for offshore wind installations in the North Sea.
- Direct-to-Fleet Digital Channels:Telematics-integrated oil monitoring systems enable subscription-based lubricant replenishment, bypassing traditional distributor markups.
Industry Challenges
- Tribology Specialist Scarcity:Formulation chemists with expertise in elastohydrodynamic lubrication theory command compensation premiums that mid-size blenders cannot match.
- Multi-Regulatory Certification Overlap:Simultaneous compliance with EPA volatility rules, REACH substance restrictions, and JIS industrial standards extends product development timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crankshaft Oil Market |
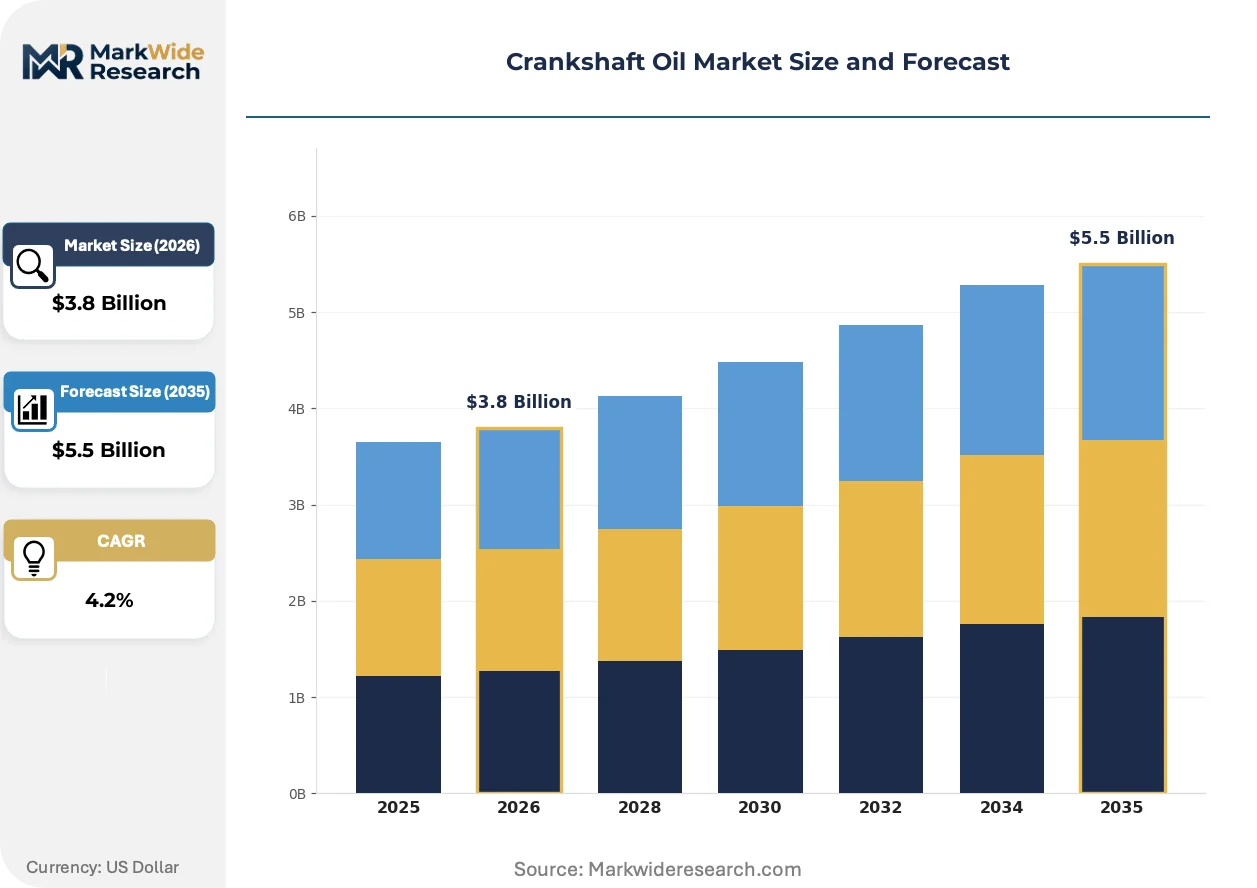
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oil, Mineral Oil, Semi-Synthetic Oil, Biodegradable Oil Application: Automobiles, Marine, Industrial Engines, Power Generation End User: OEMs, Repair Shops, Fleet Operators, End Consumers Distribution Channel: Online, Retail Stores, Wholesalers, Distributors |
| Companies Covered | NOK, Freudenberg, Parker Hannifin, Eaton, Trelleborg Sealing Solutions, SKF, Nippon Valqua Industries, Sakagami, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crankshaft Oil Market Emerging Trajectories
Digital twin technology is virtualizing lubricant performance validation before physical testing, compressing development cycles while regulatory divergence between sulfur-content and biodegradability mandates fragments formulation strategies.
Polyalkylene glycol synthetic base stocks are virtualizing traditional mineral oil applications in high-temperature crankshaft environments. European OEMs including BMW and Volkswagen have adopted PAG formulations for turbocharged gasoline direct injection engines operating above 150°C bulk oil temperatures. This chemistry shift is virtualizing the historical mineral-synthetic price hierarchy by enabling smaller sump volumes and reduced packaging material intensity.
REACH substance restriction proposals under Annex XIV evaluation are accelerating substitution of boron-containing EP additives in crankshaft oils sold across EU member states. The European Chemicals Agency's 2023-2025 roadmap targets sodium perborate and certain boron esters used in boundary lubrication regimes. German and Italian blenders are responding with sulfur-phosphorus additive packages originally developed for aerospace turbine applications.
Fleet maintenance departments are consolidating lubricant SKUs through performance-based specification rather than OEM brand loyalty. North American heavy-duty operators now issue technical tenders requiring 15,000-mile minimum drain intervals regardless of manufacturer approval. This procurement rationalization is displacing traditional jobber distribution networks with direct supplier relationships in the US Midwest and Ontario trucking corridors.
Crankshaft Oil Market Segmentation
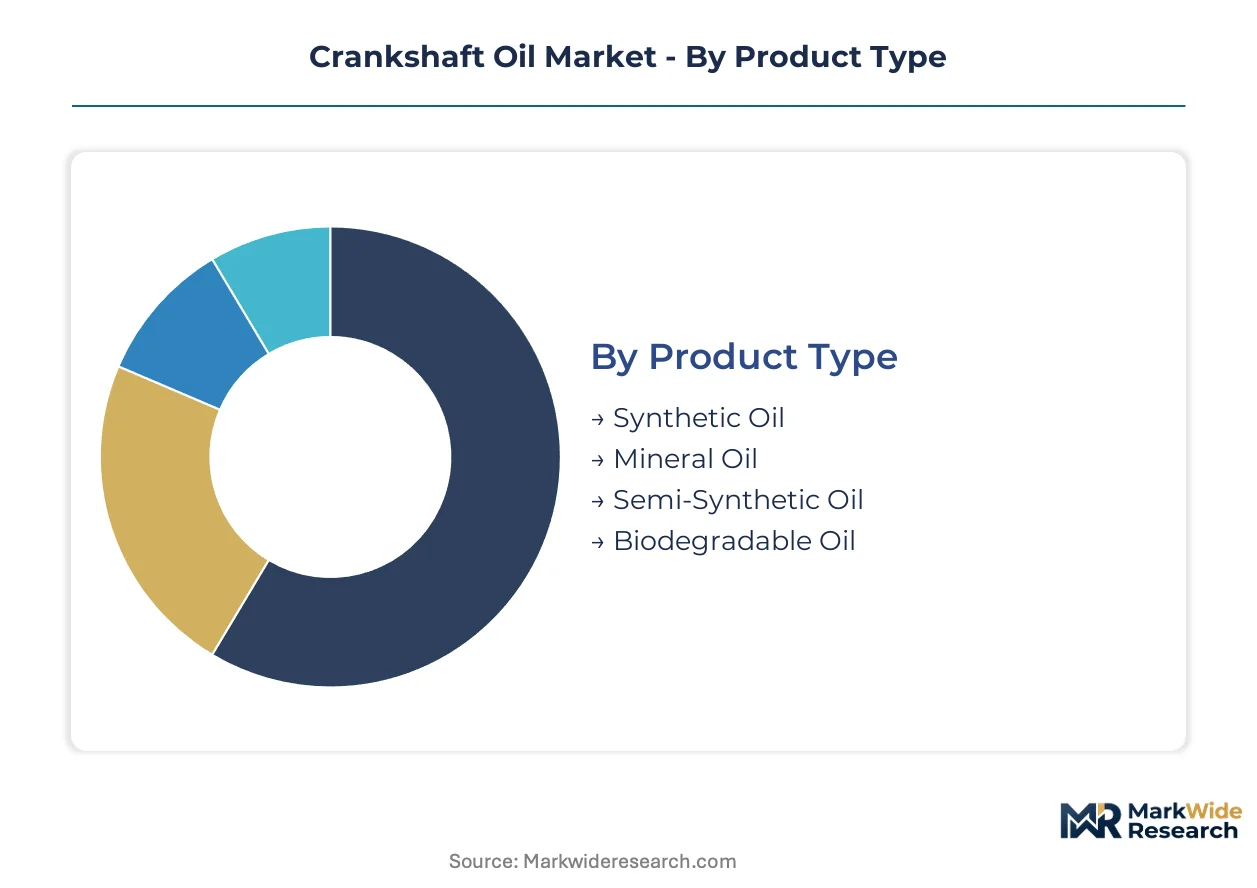
Crankshaft oil segmentation reveals divergent formulation strategies across duty cycles and procurement channels. Synthetic migration in heavy-duty fleets contrasts with mineral oil persistence in cost-driven aftermarket repair. Understanding these fault lines enables targeted positioning against regulatory and operational pressures.
Product Type:
Use-case spectrum spans extended-drain commercial fleets to biodegradable-sensitive marine environments, with base oil chemistry determining thermal stability and regulatory compliance pathways.
- Synthetic Oil:Formulated from Group III, IV, or V base stocks with precisely controlled molecular structures delivering oxidative stability above 150°C bulk temperatures. OEM specifications from BMW and Volkswagen now mandate PAG formulations for turbocharged gasoline direct injection engines, compressing development timelines through digital twin validation.
- Mineral Oil:Refined petroleum distillates with natural viscosity index improvers, dominant in aftermarket repair shops across Germany and Japan where cost sensitivity overrides drain interval optimization. EPA Tier 3 volatility limits are forcing gradual displacement in heavy-duty diesel applications despite price advantages.
- Semi-Synthetic Oil:Blended formulations combining mineral base stocks with synthetic additives, occupying mid-tier positioning in fleet procurement rationalization.
- Biodegradable Oil:Vegetable-derived or synthetic ester bases meeting EU biodegradability mandates for sensitive watershed operations, gaining traction in Nordic marine and forestry equipment.
Established volume favors mineral oil; emerging adoption favors synthetic formulations with PAG chemistry.
Application:
Operating environment severity dictates additive package selection, from high-RPM automotive to slow-speed two-stroke marine engines facing corrosive low-sulfur combustion byproducts.
- Automobiles:Passenger and commercial vehicle crankcase lubrication spanning internal combustion and hybrid powertrains. Japanese OEMs anchor specification development through JIS K 2215 standards, while EPA emissions rules indirectly mandate reformulation cycles every 24-36 months for US heavy-duty fleets.
- Marine:Two-stroke and four-stroke propulsion engines operating under IMO 2020 sulfur caps, requiring specialized detergency for acidic combustion residues. Concentrated margin pool in deep-sea shipping routes between Rotterdam and Singapore.
- Industrial Engines:Stationary power units in mining and construction, characterized by severe duty cycles and extended drain intervals.
- Power Generation:Emergency and continuous-duty gensets where lubricant reliability directly impacts grid stability obligations.
Automotive applications retain volume concentration; marine represents the steepest expansion trajectory for specialized formulation capabilities.
End User:
Procurement authority patterns separate specification-setters from price-takers, with fleet scale determining direct supplier relationship viability.
- OEMs:Original equipment manufacturers establishing factory-fill specifications and warranty requirements. German and Japanese automotive OEMs enforce stringent volatility and seal-compatibility standards that cascade through supply chains.
- Repair Shops:Independent service facilities prioritizing inventory turnover and cost minimization over performance differentiation.
- Fleet Operators:Heavy-duty trucking and marine operators consolidating lubricant SKUs through performance-based tenders requiring minimum drain intervals regardless of brand approval.
- End Consumers:Individual vehicle owners purchasing through retail channels with limited technical specification awareness.
Fleet operators are gaining procurement influence fastest; repair shops defend residual volume through convenience positioning.
Distribution Channel:
Channel economics reflect working capital intensity and technical service requirements, with digital disruption fragmenting traditional jobber networks.
- Online:Direct-to-fleet digital platforms integrating telematics-based oil monitoring with subscription replenishment, bypassing distributor markups in North American trucking corridors.
- Retail Stores:Automotive parts chains serving DIY consumers and small repair shops with immediate availability requirements.
- Wholesalers:Volume aggregators supplying jobber networks with inventory financing and logistics services.
- Distributors:Technical specialists providing formulation guidance and field service support for industrial and marine accounts.
Traditional distributor networks retain service-intensive segments; digital channels capture fleet volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery capacity for Group III base stocks clusters along the US Gulf Coast, exposing blenders to concentrated weather-related disruption. This supply-side concentration shapes regional competitive dynamics as formulators seek geographic diversification.
United States
Heavy-duty fleet operators in the Midwest and Ontario trucking corridors are consolidating lubricant procurement through performance-based tenders. EPA Tier 3 volatility standards force reformulation cycles every 24-36 months for diesel applications. Houston and Corpus Christi anchor domestic blending capacity serving both automotive OEM and aftermarket channels.
Germany
BMW and Volkswagen mandate PAG formulations for turbocharged gasoline direct injection engines operating above 150°C bulk oil temperatures. ECHA's REACH Annex XIV evaluation targets boron-containing EP additives, accelerating substitution with sulfur-phosphorus chemistry. The Stuttgart-Munich corridor concentrates R&D facilities developing seal-compatible advanced formulations.
Japan
METI enforces JIS K 2215 standards for industrial engine lubricants that constrain import eligibility and shape domestic specification development. Toyota and Honda anchor factory-fill demand through stringent volatility and seal-compatibility requirements. Nagoya and Tokyo-Yokohama clusters host tribology specialists commanding premium compensation.
China
Domestic blenders in Shanghai and Tianjin are scaling capacity for crankshaft lubricants serving high-performance engines as SAMR implements GB standards for domestic facilities. State-owned refiners are expanding Group III base oil production to reduce import dependence. The Yangtze River Delta fragmenting as foreign suppliers face market access constraints.
India
Domestic blenders in Mumbai and Chennai lack ISO 150 grade production lines, creating import windows for foreign suppliers meeting BIS IS 13656 standards. Commercial vehicle fleet growth in the Delhi-Mumbai industrial corridor is extending drain interval requirements. The PLI scheme for automotive components indirectly supports lubricant specification upgrading.
Crankshaft Oil Market Vendor Landscape
Integrated polymer science specialists and diversified industrial conglomerates split the market between formulation innovation and cross-selling scale. Freudenberg leverages polymer science heritage to develop advanced seal-compatible formulations. SKF anchors European supply through integrated bearing-lubricant systems. Parker Hannifin competes via hydraulic-fluid cross-selling into marine crankshaft applications. Consolidation pressures favor backward integration into additive manufacturing and captive base oil supply.
Within the integrated systems tier, SKF and Schaeffler AG occupy positions combining mechanical component expertise with lubricant formulation capabilities. Freudenberg exemplifies the polymer science archetype, translating seal and elastomer knowledge into compatibility-optimized crankshaft oils. Parker Hannifin sits within the diversified industrial conglomerate category, leveraging hydraulic fluid distribution networks to access marine applications. NOK and Nippon Valqua Industries represent Japanese specialists with regional specification influence through METI-aligned standards participation.
| Leading Market Players |
|---|
| NOK |
| Freudenberg |
| Parker Hannifin |
| Eaton |
| Trelleborg Sealing Solutions |
| SKF |
| Nippon Valqua Industries |
| Sakagami |
| Schaeffler AG |
| Others |
Supply Flow & Price Mechanics
Group III base oil concentration along the US Gulf Coast concentrates upstream supply power among coastal refiners, pushing margin capture downstream toward formulators with captive additive synthesis and direct fleet relationships. This geographic tethering of feedstock to hurricane-exposed infrastructure creates asymmetric pricing power where blenders with diversified sourcing command premium positioning.
Pricing Analysis
EPA Tier 3 volatility standards dictate the pricing tier structure across crankshaft oil categories, separating extended-drain synthetic formulations from mineral oil alternatives in heavy-duty procurement. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels reflects certification grade differentiation and volume scale discounts. Cost compression in mineral oil tiers is intensifying because fleet operators consolidate SKUs through performance-based tenders regardless of brand approval. Aftermarket repair shops exhibit highest price sensitivity, while OEM factory-fill specifications anchor least sensitive demand through warranty-linked requirements.
Supply Chain Analysis
Export-control restrictions on advanced polymer synthesis technology limit flow of seal-compatibility formulations from European specialists to certain Asian markets, fragmenting access to premium additive packages. Feedstock supply draws from United States, South Korea, and Middle Eastern refinery clusters, with Group III base oils, polyalkylene glycol synthetic stocks, and sulfur-phosphorus additive packages as critical inputs. Single-source vulnerability concentrates in US Gulf Coast hurricane corridors, threatening blender inventory positions. Distribution runs through technical specialist distributors for marine and industrial accounts, while digital platforms bypass traditional jobber networks in fleet segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation across North American heavy-duty corridors has shifted buyer power toward scale operators, compressing distributor margins and favoring direct supplier relationships with telematics-integrated service models.
For Market Incumbents: Harden formulation moats through backward integration into additive manufacturing, particularly sulfur-phosphorus chemistry substituting for REACH-restricted boron compounds. Captive production of PAG base stocks insulates margin pressure from Group III supply disruptions while extending digital twin validation capabilities compress competitor development cycles. For New Entrants and Emerging Players: Build out ISO 150 grade production capacity targeting India's BIS certification gap in Mumbai and Chennai corridors, where domestic blenders lack specification-compliant lines. Direct-to-fleet digital channels with telematics-integrated monitoring offer the most penetrable go-to-market angle, bypassing entrenched distributor relationships in Midwest trucking networks. For Investors and Strategic Acquirers: Capital is best deployed toward polymer science specialists with seal-compatibility expertise and REACH-compliant formulation pipelines, as regulatory divergence across EPA, ECHA, and METI standards extends product development timelines and concentrates value in technical capabilities. Watch for inflection in battery-electric commercial vehicle penetration rates, which eliminates crankshaft lubricant demand entirely in affected duty cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive sulfur-phosphorus production insulates REACH compliance costs from third-party supply volatility. |
| Digital Twin Validation Platform | BMW and Volkswagen specifications now require virtualized performance testing before physical approval. |
| Direct-to-Fleet Digital Channel | Telematics-integrated replenishment bypasses traditional jobber markups in Ontario and Midwest corridors. |
| PAG Base Stock Capacity Expansion | Turbocharged gasoline direct injection engines above 150°C bulk temperatures mandate synthetic chemistry migration. |
| Wind Turbine Gearbox Pivot | North Sea offshore installations leverage existing EP additive expertise for main bearing lubrication demand. |
Methodological Framework
A spread of perspectives from lubricant formulators, fleet maintenance directors, OEM procurement teams, and marine technical superintendents converged on the working assumptions driving segment growth trajectories. Primary field engagement with these stakeholders combined with secondary validation through EPA regulatory filings, ECHA substance restriction proposals, JIS K 2215 standard documentation, and customs trade flow data for base oil imports. Bottom-up volume modeling triangulated against top-down market sizing across synthetic, mineral, semi-synthetic, and biodegradable product categories.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling spanning base oil chemistry tier, application duty cycle severity, end-user procurement authority, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating fleet electrification displacement rates and marine low-sulfur fuel compatibility requirements. Forecast inputs included IMO 2020 sulfur cap compliance timelines and EPA Tier 3 reformulation cycle frequencies.
Practitioners should monitor battery-electric commercial vehicle penetration rates and REACH Annex XIV substance restriction finalizations for early signals of demand destruction or formulation cost step-ups. Forecasts reflect assumptions around synthetic migration pace and fleet SKU consolidation velocity. Material shifts in electrification adoption curves or multi-regulatory certification divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Power Modules Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Global Industrial Engine Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Global Driveline Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Dual Clutch Transmission (DCT) Market
Powertrain
Sway Bar Bushing Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
CNG Powertrain Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Global Automotive Clutch Pedals Market